
 Animal Health Software Market | 2026-2036
Animal Health Software Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Health Software Market Outlook
Veterinary informatics expertise is redrawing competitive boundaries across the animal health software landscape. IDEXX Laboratories leverages its diagnostic data ecosystem to anchor cloud-based workflows for mixed-animal practices. Covetrus sustains channel control through distribution-integrated software bundles that lock in pharmacy and inventory revenue. Cencora competes by extending pharmaceutical supply chain infrastructure into veterinary practice management, creating captive demand for its core distribution business.
Animal health software encompasses digital platforms that manage clinical records, diagnostic imaging, treatment protocols, and operational workflows for veterinary service providers, typically deployed through cloud architectures with HL7-FHIR or proprietary interoperability layers to ensure data exchange between laboratories, pharmacies, and regulatory databases. Practice Management systems dominate current revenue as veterinary clinics consolidate and require centralized scheduling, billing, and medical record coordination across multiple locations. Cloud-Based and SaaS delivery models represent the fastest-expanding technology dimension, displacing on-premises installations as smaller practices seek reduced IT overhead and automatic regulatory compliance updates.
FDA Center for Veterinary Medicine guidelines shape software validation requirements when platforms interface with diagnostic devices or prescribe treatment protocols, while the USDA National Animal Identification System mandates traceability data standards that livestock management software must embed. The EU Veterinary Medicines Regulation and GDPR impose parallel constraints on prescription recording and client data handling across European deployments. Stakeholders must monitor evolving software-as-medical-device classifications and interoperability mandates that will determine platform switching costs and vendor lock-in intensity.
Market Dynamics
Cloud migration is compressing IT infrastructure timelines for veterinary practices, forcing incumbents to re-architect legacy platforms around HL7-FHIR interoperability standards or lose integration access to diagnostic laboratories and pharmacy networks.
Growth Catalysts
- USDA National Animal Identification System:Livestock traceability mandates in the United States require electronic data capture for interstate cattle movement, expanding demand for herd management modules that embed RFID and EID compliance workflows.
- Companion animal spending concentration:Pet owners in Germany and Australia now expect digital appointment scheduling, telemedicine consultations, and automated prescription refills, pressuring independent clinics toward unified practice management platforms.
- Diagnostic device convergence:In-clinic analyzers and digital radiography systems increasingly ship with cloud-native software layers that auto-populate medical records, reducing manual data entry friction for mixed-animal practices.
Market Restraints
- GDPR prescription recording friction:The EU Veterinary Medicines Regulation imposes strict audit trails for antimicrobial dispensing, forcing software vendors to maintain EU-based data residency and granular consent management that inflates deployment costs.
- Veterinary informatics talent scarcity:The intersection of clinical veterinary knowledge and health informatics certification remains thinly populated, constraining implementation velocity for AI-assisted diagnostic tools.
- On-premises technical debt:Smaller practices running decade-old server installations face steep migration costs and workflow disruption, delaying SaaS conversion despite long-term total cost of ownership advantages.
Strategic Opportunities
- Brazilian livestock digitization:ANVISA harmonization with international traceability standards and expanding export certification requirements create whitespace for platforms integrating herd health, reproductive management, and slaughter-bound documentation.
- AI Act compliance tooling:The EU AI Act's risk classification for veterinary diagnostic algorithms creates demand for embedded explainability features and bias auditing modules that vendors can productize across jurisdictions.
- Pharmacy-inventory convergence:Distribution-integrated software bundles that lock in formulary compliance and automatic reordering represent an underexploited channel for capturing recurring revenue from mid-sized practice groups.
Industry Challenges
- HL7-FHIR implementation complexity:Mapping proprietary veterinary data structures to human-health interoperability standards requires sustained engineering investment, with laboratory interface maintenance consuming disproportionate support resources.
- Software-as-medical-device validation timelines:FDA Center for Veterinary Medicine scrutiny of diagnostic decision-support features extends release cycles and demands clinical evidence packages that smaller vendors struggle to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Health Software Market |
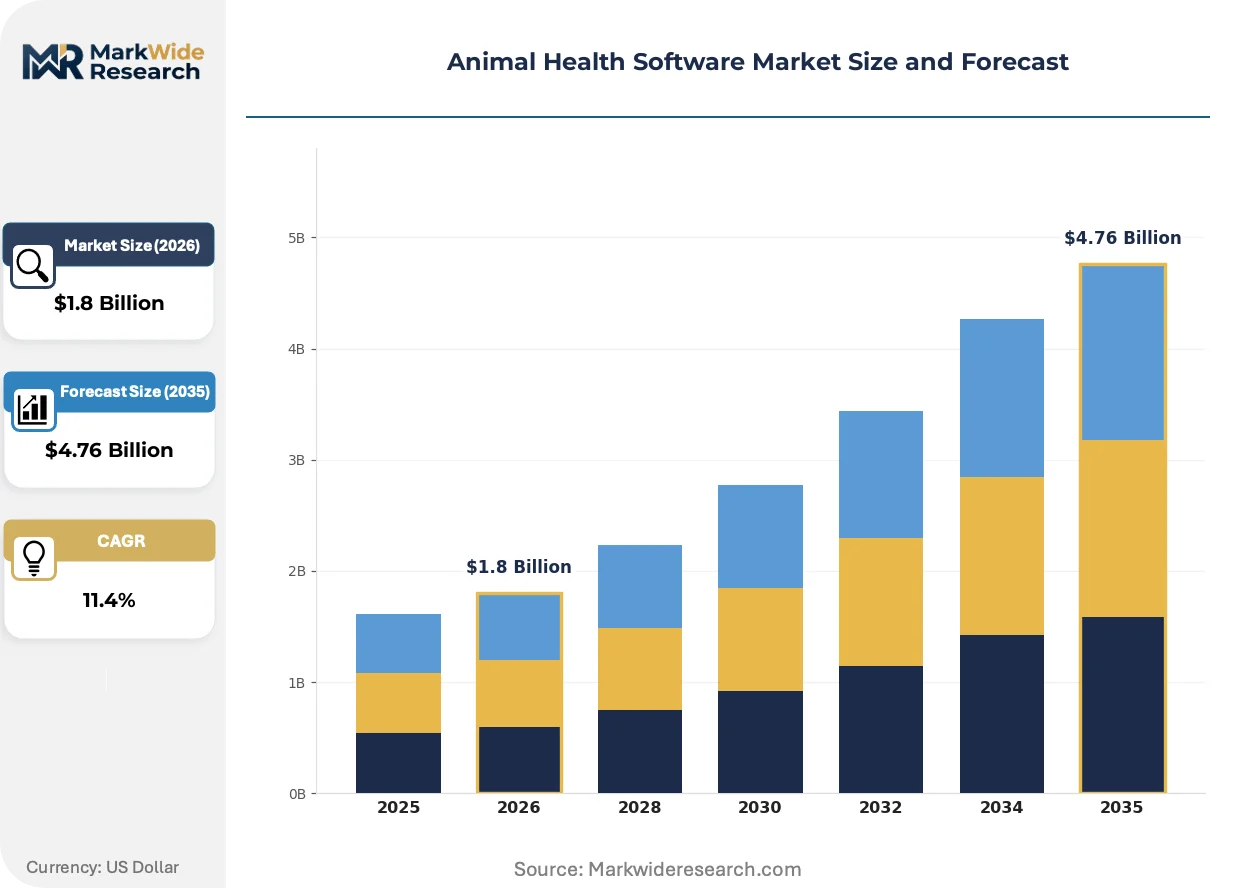
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Practice Management, Inventory Management, Telehealth Solutions, Diagnostic Software Technology: Cloud-Based, On-Premises, Mobile Applications, SaaS End User: Veterinary Clinics, Livestock Farms, Animal Shelters, Research Facilities Application: Patient Management, Billing Solutions, Health Tracking, Client Communication |
| Companies Covered | IDEXX Laboratories, Covetrus, Cencora, Nordhealth, Carestream Health, DaySmart Software, Animal Intelligence Software, Hippo Manager, Shepherd Veterinary Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Health Software Market Strategic Shifts
Veterinary software architecture is pivoting from record-keeping systems toward clinical decision engines, with data liquidity and predictive analytics becoming primary competitive differentiators rather than administrative convenience.
Cloud-native practice management platforms are displacing on-premises installations as the default infrastructure choice for North American veterinary groups. Multi-location consolidators demand centralized scheduling, billing, and inventory visibility across dozens of sites. This shift is compressing margins for legacy vendors unable to re-platform without disrupting existing customer bases.
The EU Veterinary Medicines Regulation tightens antimicrobial stewardship documentation, requiring software to capture prescriber justification, treatment duration, and outcome tracking at the individual animal level. European deployments now embed mandatory prescription review workflows before pharmacy fulfillment. Large livestock operations in Germany and France are prioritizing platforms with built-in regulatory reporting to avoid manual compliance overhead.
Subscription-based pricing models are replacing perpetual licenses across the buyer base, with veterinary groups preferring predictable operational expenditure over capital-intensive server purchases. This preference compresses upfront vendor revenue into amortized streams, forcing cash flow restructuring. The transition is most advanced in the United States, where private equity-backed practice consolidators negotiate enterprise SaaS contracts with embedded telemedicine and client communication modules.
Animal Health Software Market Segmentation
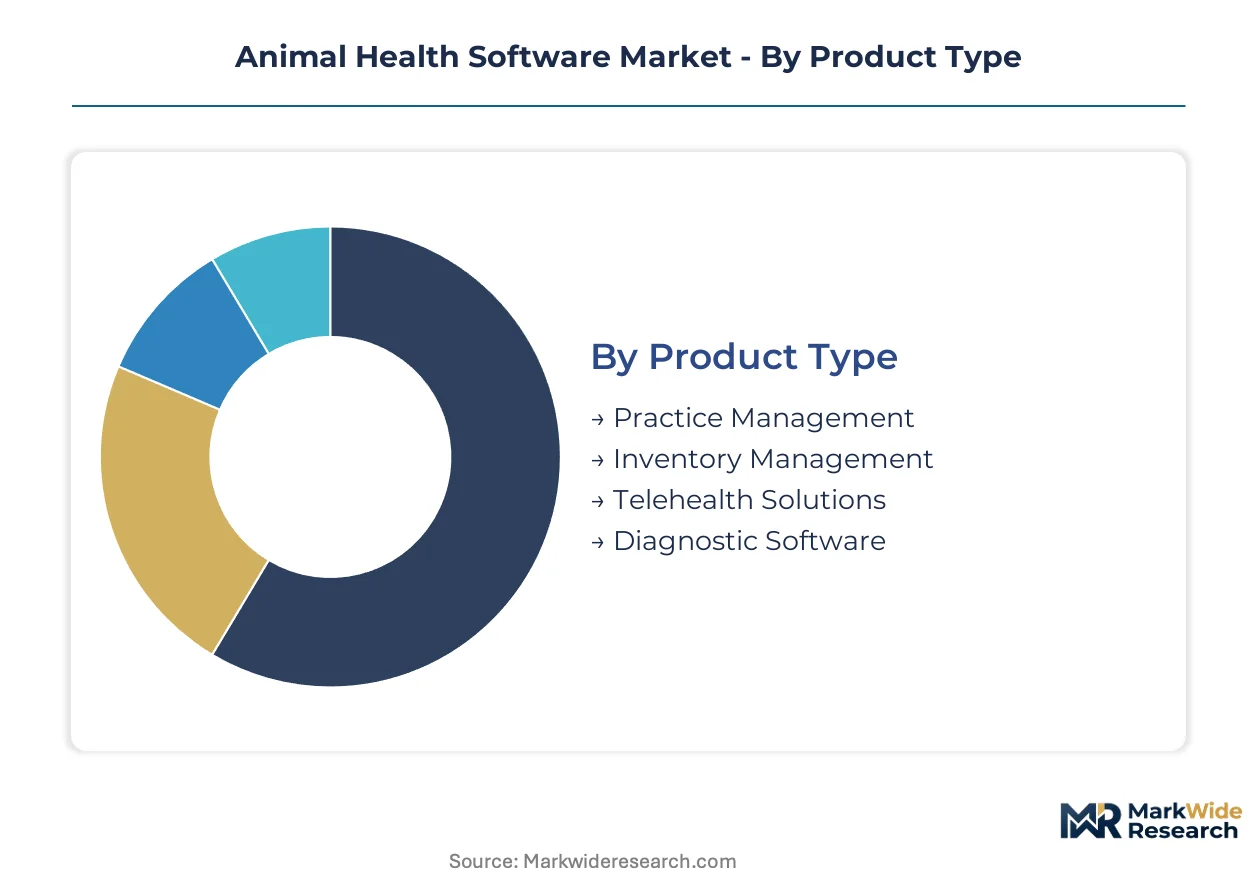
Veterinary practices and livestock operations exhibit sharply divergent software requirements, with companion animal clinics prioritizing client-facing convenience while production agriculture demands regulatory compliance architecture. Understanding these segment boundaries reveals where vendor specialization creates defensible positioning versus where platform consolidation captures cross-selling economies.
Product Type:
Practice Management systems anchor domestic revenue in the United States and Germany where clinic consolidation creates multi-location workflow demands. Inventory Management modules concentrate in export-dependent livestock regions requiring pharmaceutical traceability for international certification.
- Practice Management:Cloud-native platforms centralize scheduling, billing, and medical records across veterinary group networks. Demand clusters in US metropolitan markets and German urban corridors where private equity consolidation has created 50-plus location enterprises requiring unified data architecture.
- Inventory Management:Automated reordering and formulary compliance tools integrate with pharmaceutical distribution channels. Livestock operations in Australia and export-focused Brazilian farms drive adoption where antimicrobial stewardship documentation is mandatory for EU and Chinese market access.
- Telehealth Solutions:Remote consultation platforms with integrated payment processing.
- Diagnostic Software:In-clinic analyzer interfaces and imaging interpretation tools.
Practice Management commands the established base. The steepest expansion runs through Inventory Management as traceability mandates tighten across export supply chains.
Technology:
Deployment architecture selection tracks practice size and IT staffing constraints, with smaller clinics avoiding capital expenditure while enterprise livestock operations retain on-premises control for connectivity-limited rural environments.
- Cloud-Based:Browser-accessible platforms with automatic regulatory update deployment eliminate server maintenance burdens. US companion animal clinics and UK veterinary groups lead adoption where reliable broadband infrastructure supports real-time diagnostic laboratory integration.
- SaaS:Subscription pricing models bundle telemedicine, client communication, and analytics modules. German mid-market practices and Australian consolidators prefer operational expenditure structures that align costs with seasonal revenue fluctuations in mixed-animal settings.
- On-Premises:Local server installations for operations with limited internet connectivity.
- Mobile Applications:Smartphone-native tools for field-based livestock veterinarians.
Cloud-Based deployments hold the dominant installed base. SaaS offerings are climbing the fastest as subscription economics displace perpetual license renewal cycles.
End User:
Customer type determines feature prioritization, with clinical workflows diverging sharply from production agriculture's population-level health management and regulatory documentation requirements.
- Veterinary Clinics:Mixed-animal and companion-only practices requiring appointment optimization, client retention tools, and diagnostic device connectivity. Concentrated in US suburban corridors and Japanese metropolitan zones where pet humanization drives software investment.
- Livestock Farms:Dairy, beef, and swine operations managing herd health, reproductive programs, and slaughter-bound traceability. Canadian prairie provinces and Dutch intensive livestock regions anchor demand where USDA and EU export compliance creates non-negotiable data requirements.
- Animal Shelters:Non-profit intake, adoption, and population health management systems.
- Research Facilities:Protocol-driven data capture for pharmaceutical and academic studies.
Veterinary Clinics represent the mature revenue core. Livestock Farms are expanding most quickly as export certification digitization mandates proliferate.
Application:
Functional module adoption correlates with practice profitability pressures, with automation of administrative tasks preceding clinical decision-support investment.
- Patient Management:Electronic medical records with vaccination history, prescription tracking, and diagnostic result integration. US and Australian clinics prioritize these modules where malpractice exposure and client expectation elevate documentation standards.
- Billing Solutions:Insurance claim submission, payment plan management, and inventory cost allocation. German and Swiss practices emphasize this functionality where complex multi-payer reimbursement structures demand automated processing.
- Health Tracking:Individual and population-level monitoring with alert thresholds.
- Client Communication:Automated reminders, portals, and telemedicine scheduling.
Patient Management retains the deepest penetration. Billing Solutions are gaining share fastest as payment complexity and insurance participation deepen across veterinary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal clinics in the United States deploy software for client retention and telemedicine, while German livestock operations prioritize antimicrobial traceability modules for export compliance. This consumption-mix differential shapes vendor feature roadmaps and data architecture investments across major markets.
United States
Private equity-backed veterinary consolidators drive demand for multi-location practice management platforms with centralized billing and inventory visibility. FDA Center for Veterinary Medicine oversight of diagnostic decision-support features extends software validation timelines for vendors. Metropolitan clusters in Texas, California, and Florida anchor adoption where 50-plus location groups require unified cloud infrastructure.
Germany
Intensive livestock regions in Lower Saxony and Bavaria prioritize herd management software with embedded EU Veterinary Medicines Regulation compliance workflows. GDPR prescription recording requirements force EU-based data residency and granular consent management. Berlin and Munich veterinary groups lead SaaS conversion as subscription pricing aligns with seasonal revenue fluctuations in mixed-animal practices.
Australia
Export-dependent cattle operations in Queensland and New South Wales mandate electronic identification and movement documentation for Chinese and EU market access. The country's national agricultural regulator enforces traceability standards that livestock management platforms must embed. Sydney and Melbourne companion animal clinics accelerate telehealth adoption as pet humanization drives digital service expectations.
Brazil
Beef and dairy operations in São Paulo and Minas Gerais states require slaughter-bound documentation for international certification as ANVISA harmonizes with global traceability standards. Expanding export volumes to China and the Middle East create demand for integrated herd health and reproductive management modules. Southern Brazilian farm cooperatives pilot cloud-based platforms to replace paper-based compliance workflows.
United Kingdom
Companion animal practices in London and Southeast England prioritize client communication portals and automated appointment scheduling. The UK veterinary regulator maintains parallel antimicrobial stewardship requirements to EU standards post-Brexit. Scottish livestock operations in the Highlands adopt mobile-native tools for field-based veterinary interventions where broadband connectivity remains limited.
Animal Health Software Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with diagnostic data ecosystems and pharmaceutical distribution channels determining competitive boundaries. Diagnostic-anchored platforms leverage laboratory connectivity to lock in practice workflows, while distribution-integrated bundles capture pharmacy and inventory revenue through formulary compliance tools. Incumbents re-architect legacy systems around HL7-FHIR interoperability standards or risk losing integration access to laboratory networks. Consolidation pressure intensifies as private equity-backed veterinary groups negotiate enterprise contracts spanning dozens of locations.
Within the diagnostic-anchored tier, IDEXX Laboratories exemplifies the data ecosystem model, leveraging in-clinic analyzer connectivity to embed cloud-based workflows. Covetrus and Cencora represent distribution-integrated strategies, extending pharmaceutical supply chain infrastructure into practice management to create captive demand for core distribution services. Specialist vendors including Nordhealth, DaySmart Software, and Hippo Manager occupy positions targeting independent clinics with simplified deployment and lower total cost of ownership.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Covetrus |
| Cencora |
| Nordhealth |
| Carestream Health |
| DaySmart Software |
| Animal Intelligence Software |
| Hippo Manager |
| Shepherd Veterinary Software |
| Others |
Value Chain & Pricing Dynamics
Ninety-day implementation cycles for cloud-based practice management platforms compress vendor cash conversion timelines while amplifying pricing power for distribution-integrated incumbents with captive pharmacy revenue streams. This lead-time compression concentrates procurement leverage among private equity-backed veterinary consolidators negotiating enterprise SaaS contracts spanning fifty-plus locations.
Pricing Analysis
Long-term enterprise offtake agreements dominate pricing structures as US veterinary consolidators negotiate multi-year SaaS bundles embedding telemedicine and inventory modules. Price differentiation rests on HL7-FHIR interoperability certification and automatic regulatory update deployment, with premium tiers commanding spreads for FDA-validated diagnostic decision-support features. Cost compression in the mid-market tier intensifies as independent clinics migrate from perpetual licenses to subscription models, eroding upfront vendor revenue. Small mixed-animal practices in rural Australia exhibit highest price sensitivity, while German livestock operations show lowest sensitivity due to EU Veterinary Medicines Regulation compliance mandates that embed software costs into export certification requirements.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure provisioning for North American and European veterinary software deployments, while India supplies engineering talent for platform development and technical support operations. Software architecture draws from proprietary diagnostic device protocols, HL7-FHIR interoperability frameworks, and pharmaceutical distribution APIs as critical input dependencies. Single-source vulnerability concentrates in laboratory interface maintenance, where IDEXX Laboratories' analyzer connectivity creates captive workflow lock-in for mixed-animal practices. Distribution runs through pharmaceutical wholesalers and veterinary buying groups, with Covetrus and Cencora leveraging formulary compliance tools to capture recurring inventory revenue from mid-sized practice networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary practice consolidation concentrates buyer power among private equity-backed groups, fragmenting negotiating leverage for independent clinics and forcing vendors toward enterprise SaaS pricing architectures.
For Market Incumbents: Consolidate diagnostic data ecosystem advantages by deepening laboratory interface exclusivity and embedding AI-assisted imaging interpretation before emerging cloud-native entrants achieve FHIR interoperability parity. Prioritize backward integration into pharmaceutical distribution channels to capture inventory reordering automation revenue that locks in formulary compliance workflows. Defensive positioning requires re-architecting legacy on-premises installations around subscription pricing before technical debt forces customer attrition to SaaS-native competitors. For New Entrants and Emerging Players: FDA Center for Veterinary Medicine 510(k) fast-track pathways for software-as-medical-device diagnostic tools open whitespace for specialized entrants targeting AI-assisted radiography interpretation. Brazilian livestock digitization presents the most penetrable geography, with ANVISA harmonization creating demand for integrated herd health and slaughter-bound documentation platforms. Cloud-native deployment with embedded EU GDPR consent management enables rapid European market entry without legacy technical debt burdens. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical distributors seeking to monetize veterinary software assets non-core to human health supply chain operations. Long-term viability centers on platforms achieving diagnostic-laboratory integration density that creates switching costs exceeding five-year amortization horizons. Watch private equity consolidation velocity in US metropolitan markets as the inflection signal determining enterprise contract pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7-FHIR interoperability embeds diagnostic laboratory workflows into practice management systems, locking in IDEXX revenue streams. |
| Acquisition of Specialist Firm | AI-assisted imaging interpretation targets narrow capability gaps in radiography decision-support for mixed-animal practices. |
| Strategic Partnership | Pharmaceutical distribution alliances capture formulary compliance automation and recurring inventory reordering revenue. |
| Geographic Expansion | Brazilian livestock digitization leverages ANVISA harmonization to replace paper-based export certification workflows. |
| Regulatory Certification Pathway | FDA Center for Veterinary Medicine validation for diagnostic algorithms extends release cycles but creates defensible moats against unvalidated competitors. |
Study Parameters
Desk research of FDA Center for Veterinary Medicine guidance documents, EU Veterinary Medicines Regulation compliance frameworks, and USDA National Animal Identification System technical standards preceded structured interviews with veterinary practice owners, pharmaceutical distribution procurement directors, and health informatics implementation specialists. Primary fieldwork captured cloud migration timelines and SaaS conversion friction points across US metropolitan consolidators and German mixed-animal practices. Secondary validation drew from SEC filings of publicly traded diagnostic and distribution companies, veterinary industry association technology adoption surveys, and regulatory docket analysis. Bottom-up triangulation of practice-level software expenditure patterns with top-down market sizing from vendor revenue disclosures anchored value estimates.
Variance decomposition across deployment model, practice size tier, and regional regulatory cluster shaped analytical framework construction throughout the projection horizon. Segmentation modeling captured technology dimension splits between cloud-native and on-premises architectures, end-user divergence between companion animal clinics and livestock operations, and application module prioritization from patient management through billing automation. CAGRs derived from logistic adoption curves fitted to historical SaaS conversion rates in adjacent healthcare verticals, with veterinary-specific adjustments for regulatory validation timelines and diagnostic device convergence patterns.
Decision-makers should treat outputs as directional under assumptions of continued private equity consolidation velocity and stable FDA software-as-medical-device classification frameworks; material deviation in either driver would warrant model refresh. Forecasts embed assumptions regarding broadband infrastructure expansion in rural veterinary markets and ANVISA traceability harmonization progress in Brazil. Specific risks that could revise projections include EU AI Act risk reclassification of veterinary diagnostic algorithms and abrupt shifts in antimicrobial stewardship documentation requirements. Recalibration cycles align with material shifts in regulatory validation timelines or consolidation-driven buyer power concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Canada Animal Health Care Market
Animal Health
Animal Health Market
Animal Health
Canine Influenza Treatment Market
Animal Health
US Military Animals Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Rat Model Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
US Companion Animal Health Market
Animal Health
Companion Animal Medicine Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Animal Healthcare Market
Animal Health
Cattle Healthcare Market
Animal Health
China Companion Animal Health Market