
 Canine Influenza Treatment Market | 2026-2036
Canine Influenza Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Canine Influenza Treatment Market Analytics
USDA-CVB strain-matching requirements for canine influenza vaccines is rebalancing the cost-of-entry calculus for new market participants. Zoetis leverages its vertically integrated biologics infrastructure to sustain rapid antigen adaptation cycles. Merck Animal Health anchors its position through deep veterinary channel relationships and field technical service density. Boehringer Ingelheim differentiates via dual-strain H3N2/H3N8 vaccine formulations that address evolving pathogen circulation patterns.
Canine influenza treatment encompasses prophylactic and therapeutic interventions targeting H3N2 and H3N8 viral strains in domestic dogs, with vaccines typically containing inactivated whole-virus antigens adjuvanted for enhanced immunogenicity and administered in two-dose priming series followed by annual revaccination. These products serve to reduce clinical severity, viral shedding duration, and outbreak propagation in high-density canine populations including shelters, boarding facilities, and breeding operations. Vaccines command the dominant value share given recurring revaccination schedules and regulatory mandates for strain updates, while antivirals represent a faster-growing segment as off-label human neuraminidase inhibitor use expands under veterinary supervision. Injectable delivery modes lead in clinical settings due to precise dosing and immune response reliability, though oral formulations gain traction in home-administered supportive care protocols.
FDA-CVM oversight of extralabel drug use, USDA-CVB vaccine licensing protocols, and state veterinary practice acts collectively shape product development timelines, distribution channel access, and prescriptive authority across the United States. Compliance with batch-release potency testing and adverse event reporting obligations extends development cycles but reinforces quality barriers that protect established manufacturers. Stakeholders must monitor emerging H3N2 antigenic drift patterns and corresponding USDA strain update triggers to align R&D pipelines with regulatory revision timelines.
Market Dynamics
USDA-CVB strain-matching mandates are compressing product development cycles while elevating compliance costs, forcing manufacturers to choose between rapid antigen adaptation and regulatory capital reserves. This structural pressure favors biologics specialists with captive manufacturing infrastructure over contract-dependent entrants.
Growth Catalysts
- Pet Insurance Penetration:Expanding coverage for preventive veterinary care reduces out-of-pocket vaccination costs for owners, driving clinic visit frequency and multi-dose protocol completion rates in the United States.
- Shelter Density Regulations:Municipal mandates for H3N2/H3N8 vaccination in high-intake facilities create institutional procurement streams independent of discretionary consumer spending patterns.
- Adjuvant Platform Advances:Novel immunostimulant formulations reduce the antigen mass required per dose, lowering per-unit production costs while maintaining seroconversion thresholds.
Market Restraints
- Egg-Based Production Dependency:Viral cultivation in embryonated chicken eggs creates supply vulnerability to avian disease outbreaks and input cost volatility from feed grain markets.
- USDA Batch-Release Bottlenecks:Potency testing queues at the Center for Veterinary Biologics extend inventory holding periods and compress effective shelf life for distributed product.
- Antigenic Drift Uncertainty:H3N2 mutation rates in circulating field strains create mismatch risk between licensed vaccines and outbreak pathogens, undermining confidence in preventive protocols.
Strategic Opportunities
- Cell Culture Manufacturing:Transition from egg-based to mammalian cell substrate production reduces lead times for strain updates and eliminates supply chain exposure to poultry health cycles.
- Home Administration Formats:Oral and intranasal delivery platforms bypass clinic dependency, capturing revenue from rural and convenience-seeking owner segments underserved by injectable protocols.
- Multivalent Combination Vaccines:Integration of H3N2/H3N8 antigens with core canine pathogens reduces injection burden and positions products for preferential formulary placement in corporate veterinary chains.
Industry Challenges
- Field Surveillance Integration:Manufacturers must maintain real-time antigenic monitoring networks to trigger strain update submissions, requiring sustained investment in veterinary diagnostic partnerships.
- Cold Chain Integrity:Temperature excursion tolerance for inactivated viral vaccines remains narrow, complicating distribution to secondary markets with inconsistent logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canine Influenza Treatment Market |
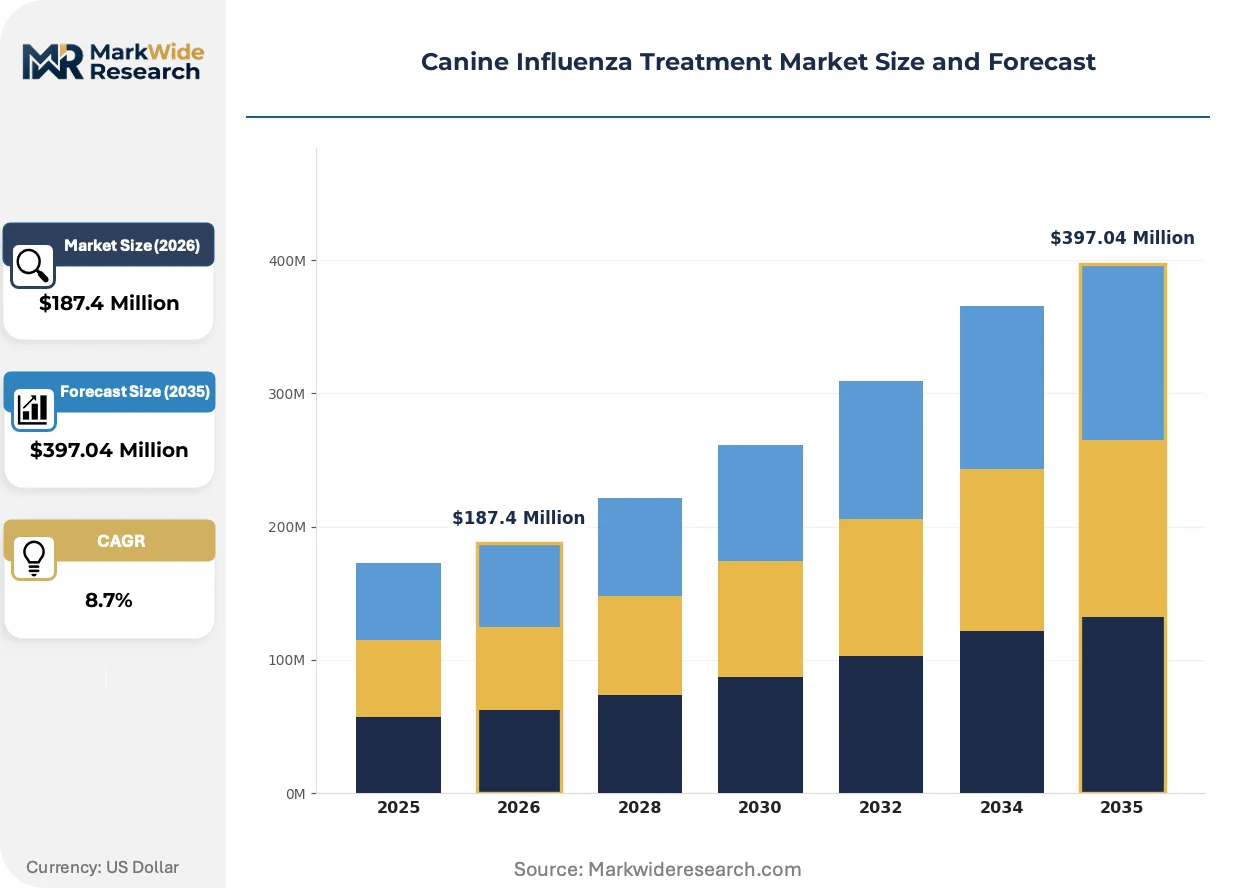
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antivirals, Supportive Care, Diagnostics Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Veterinary Clinics, Animal Hospitals, Research Labs, Pet Owners Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Zoetis, Merck Animal Health, Elanco Animal Health, Boehringer Ingelheim, Pfizer, Sanofi, Virbac, Novartis, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canine Influenza Treatment Market Evolving Landscape
Antigen delivery platforms and regulatory data requirements are undergoing parallel transformation, compressing the gap between pathogen emergence and commercial response capability. These shifts reward integrated biologics operations over modular outsourcing models.
mRNA vaccine technology is converging with veterinary applications after human platform validation, offering rapid sequence-to-dose timelines for emerging H3N2 variants. Large companion animal hospital networks are piloting mRNA protocols in outbreak response scenarios, attracted by the elimination of egg supply dependencies. This convergence is compressing the traditional multi-year strain update cycle toward seasonal adaptation rhythms.
The USDA-CVB has signaled expanded post-licensing potency surveillance requirements, mandating real-world efficacy data collection beyond initial field trial submissions. Manufacturers must now maintain active pharmacovigilance infrastructure spanning thousands of vaccinated animals. High-volume distributors with embedded practice management software access capture preferential compliance support relationships.
Corporate veterinary consolidators are unbundling vaccine procurement from equipment and pharmaceutical supply agreements, enabling direct manufacturer negotiations previously intermediated by group purchasing organizations. Independent clinics respond by forming regional buying cooperatives to restore volume leverage. This behavior shift concentrates procurement influence in the southeastern United States, where shelter dog intake density sustains outbreak-driven demand spikes.
Canine Influenza Treatment Market Segmentation
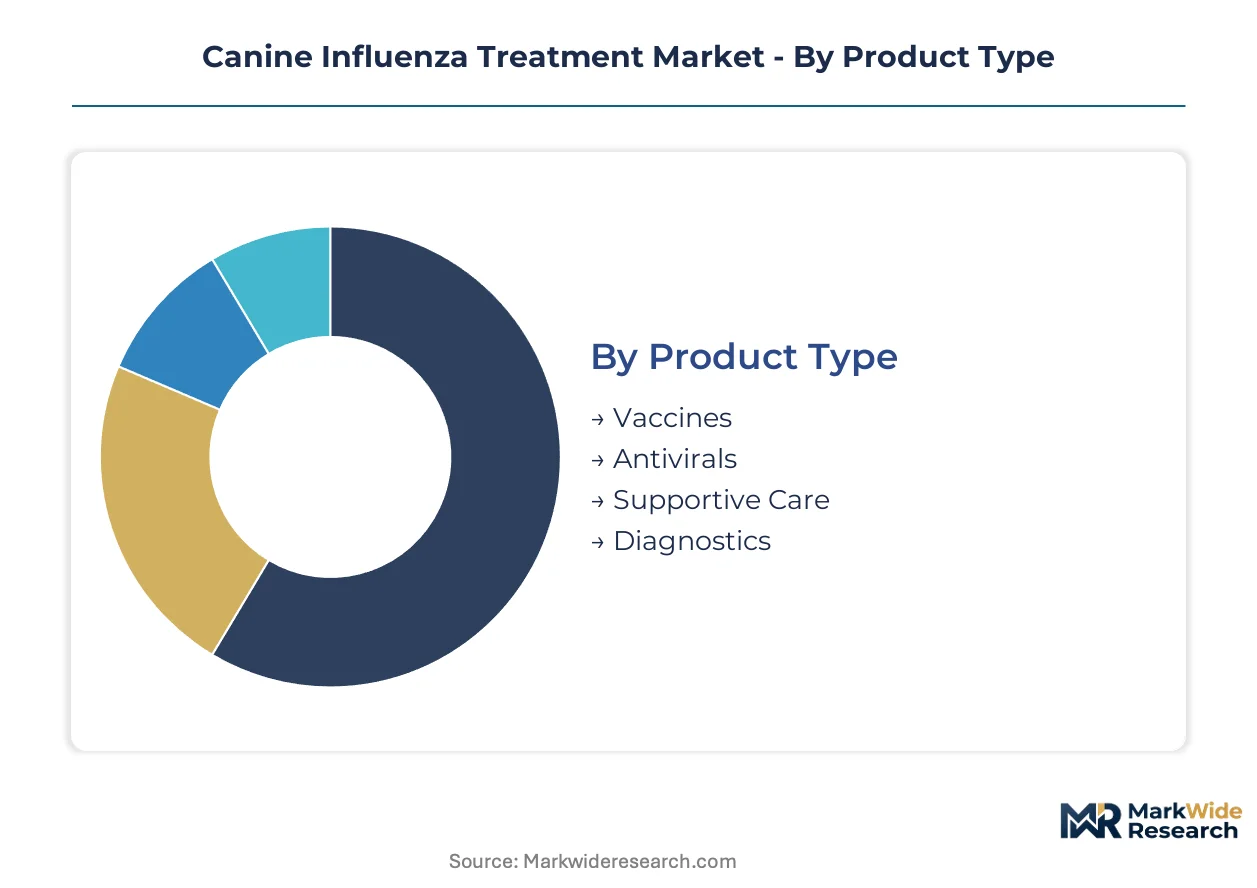
Segmentation in canine influenza treatment reveals distinct procurement patterns across institutional and retail channels. Vaccine delivery protocols, diagnostic workflows, and prescriptive authority boundaries reshape how manufacturers align product formats with customer capabilities.
Product Type:
Standalone biologics dominate procurement budgets, while embedded diagnostic-supportive care bundles gain traction in corporate veterinary chains seeking protocol standardization.
- Vaccines:Inactivated whole-virus formulations with oil-in-water adjuvants generate recurring revenue through annual revaccination schedules. Demand concentrates in high-intake municipal shelters across Texas, Florida, and California, where H3N2 outbreak density sustains bulk procurement contracts tied to USDA strain-matching compliance.
- Antivirals:Off-label neuraminidase inhibitors administered under veterinary supervision reduce viral shedding duration in confirmed cases. Faster expansion belongs to this segment as pet insurance reimbursement for therapeutic interventions broadens beyond preventive coverage alone.
- Supportive Care:Intravenous fluid therapy and nutritional supplementation manage dehydration in severe H3N2 presentations.
- Diagnostics:PCR and rapid antigen detection kits enable point-of-care outbreak confirmation.
Volume placements concentrate in Vaccines; the faster expansion belongs to Antivirals.
Delivery Mode:
Cost tier alignment separates precision-dose clinical formats from convenience-oriented home administration alternatives.
- Injectable:Subcutaneous and intramuscular routes ensure reliable immune response kinetics for inactivated viral antigens. Premium pricing sustains in corporate hospital networks where liability concerns prioritize administration documentation.
- Oral:Palatable liquid and tablet formulations enable owner-administered supportive care protocols. Budget tier capture accelerates in rural markets with limited clinic access, where telemedicine prescriptions bypass geographic barriers.
- Topical:Transdermal absorption platforms remain experimental for antiviral delivery.
- Inhalation:Nebulized therapies address respiratory symptom management in hospital settings.
Injectable formats command institutional volume; oral alternatives are gaining share fastest in retail channels.
End User:
Customer type fragmentation creates divergent purchasing authority structures, from centralized formulary committees to individual owner discretion.
- Veterinary Clinics:Independent and franchise practices administer the majority of prophylactic doses through appointment-based protocols. Mid-range pricing acceptance prevails where pet insurance eligibility verification occurs at point of sale.
- Animal Hospitals:Emergency and specialty referral centers manage severe H3N2 cases requiring isolation protocols and intensive supportive care. Premium tier procurement concentrates here, driven by critical care reimbursement rates and outcome-based fee structures.
- Research Labs:Academic and contract research organizations source vaccines for challenge studies.
- Pet Owners:Direct-to-consumer channels expand through online pharmacies with veterinary prescription verification.
Veterinary Clinics anchor volume placements; Animal Hospitals show the steepest expansion trajectory in revenue per transaction.
Price Tier:
Margin stratification reflects certification grade differentiation and volume scale economies across manufacturer portfolios.
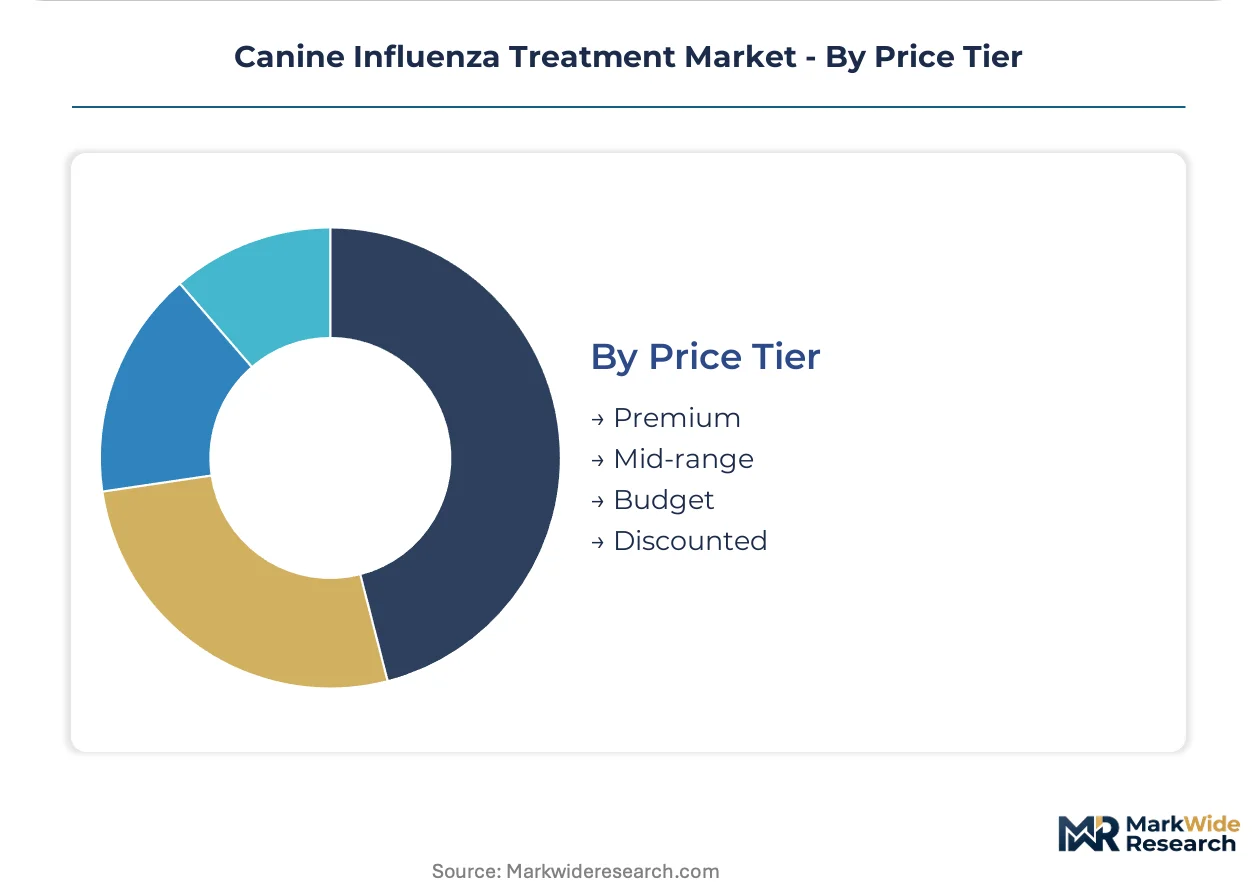
- Premium:USDA-licensed vaccines with demonstrated field efficacy data and dedicated technical service support. Demand clusters in metropolitan markets with high pet insurance penetration and corporate hospital formulary requirements.
- Mid-range:Standard adjuvanted formulations without differentiated service packages. Budget-conscious independent clinics in the southeastern United States favor this tier for shelter contract fulfillment.
- Budget:Generic supportive care products with minimal brand recognition.
- Discounted:Near-expiry inventory and volume contract surplus redistribution.
Mid-range tier captures shelter procurement volume; Premium tier is climbing the fastest as insurance coverage reduces owner price sensitivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones across Guangdong and Jiangsu provinces concentrate veterinary biologics manufacturing capacity. These designated zones offer 15% corporate tax rates and expedited customs clearance for imported viral substrates. Concentrated demand for canine influenza treatment clusters in five national markets.
United States
Municipal shelter mandates in Texas, Florida, and California drive institutional procurement of H3N2/H3N8 vaccines. USDA-CVB strain-matching protocols require manufacturers to submit updated antigen formulations within 90 days of drift detection. The Dallas-Fort Worth metroplex anchors distribution logistics for southeastern boarding facility networks.
China
Pet ownership registration in tier-one cities exceeds 20 million households, expanding clinic visit frequency for preventive care. NMPA veterinary biologics licensing aligns with national agricultural biosecurity frameworks. Shanghai's Zhangjiang Hi-Tech Park hosts mammalian cell culture R&D facilities serving domestic vaccine producers.
Germany
Mandatory pet health insurance in Baden-Württemberg and Bavaria reduces owner cost sensitivity for revaccination schedules. EMA veterinary product guidelines influence national implementation of H3N2 surveillance protocols. The Munich-Stuttgart corridor concentrates specialty animal hospital networks purchasing premium-tier therapeutics.
Brazil
ANVISA regulatory harmonization with USDA standards accelerates import approval timelines for strain-updated vaccines. São Paulo state shelters process 150,000 canine intakes annually, sustaining outbreak-response procurement. Campinas anchors regional distribution for southeastern veterinary clinic chains.
Japan
PMDA post-market surveillance requirements mandate adverse event reporting across all administered doses. METI biotechnology subsidies support domestic cell-culture manufacturing transitions away from egg-based production. The Osaka-Kobe manufacturing belt concentrates adjuvant formulation capacity for export markets.
Canine Influenza Treatment Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions through regulatory alignment. The vendor base concentrates around three strategic archetypes: vertically integrated biologics majors, regional vaccine specialists, and diversified human-pharma divisions. Market consolidation proceeds through captive manufacturing infrastructure acquisition and veterinary channel partnership density. Competitive positioning hardens around strain-update response velocity and USDA-CVB compliance track records.
Within the integrated biologics tier, Zoetis and Merck Animal Health exemplify archetype leaders with captive antigen adaptation infrastructure. Boehringer Ingelheim occupies a differentiated position through dual-strain formulation expertise. Elanco Animal Health and Virbac represent mid-scale specialists competing on regional veterinary relationship depth rather than manufacturing scale.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Elanco Animal Health |
| Boehringer Ingelheim |
| Pfizer |
| Sanofi |
| Virbac |
| Novartis |
| Bristol-Myers Squibb |
| Others |
Value Network & Pricing Analysis
Embryonated chicken egg price volatility cascades through canine influenza vaccine manufacturing into three-tier pricing structure across premium, standard, and economy levels, with strain-update frequency and USDA-CVB compliance status determining tier placement for institutional buyers.
Pricing Analysis
Short lead-time premiums of 15-30% apply to strain-matched vaccines ordered within 90-day USDA-CVB drift detection windows, while spot inventory of prior-strain lots trades at steep discounts to municipal shelters. Certification grade and captive manufacturing infrastructure serve as the primary price differentiation drivers. Pricing pressure stems from corporate veterinary chain formulary unbundling, which compresses distributor markups. Independent clinics in the southeastern United States exhibit highest price sensitivity; corporate hospital networks show least sensitivity due to insurance reimbursement pass-through.
Supply Chain Analysis
Domestic-content mandates in China's NMPA veterinary biologics framework and India's PLI scheme for animal health products are reshaping sourcing patterns for multinational manufacturers. Supply concentrates in the United States, China, and Germany, with viral substrate cultivation and adjuvant formulation as critical input dependencies. Single-source vulnerability characterizes egg-based production networks exposed to avian influenza outbreaks. Distribution runs through temperature-controlled third-party logistics networks serving veterinary clinic chains and municipal shelter systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where USDA-CVB strain-matching protocols erect a barrier-to-entry moat protecting manufacturers with captive antigen adaptation infrastructure and established pharmacovigilance networks.
For Market Incumbents: Lock in strain-update velocity advantages by deepening captive cell-culture manufacturing transitions that bypass egg supply dependencies. Consolidate field technical service density in Texas, Florida, and California shelter corridors to preempt regional buying cooperative formation. Threat exposure centers on mRNA platform entrants compressing traditional multi-year adaptation cycles; priority lever rests with real-world efficacy data infrastructure exceeding post-licensing surveillance mandates. For New Entrants and Emerging Players: Telemedicine-integrated oral formulation channels offer the most penetrable route for bypassing clinic-dependent injectable protocols in rural markets with limited veterinary access. White-space targets include home-administered supportive care bundles and intranasal delivery platforms for convenience-seeking owner segments. Go-to-market execution should anchor in direct-to-consumer online pharmacy partnerships with prescription verification infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mammalian cell culture specialists in the United States and mammalian substrate R&D facilities in China's Zhangjiang Hi-Tech Park as egg-based production assets face obsolescence risk. Long-term viability over a multi-year horizon hinges on regulatory compliance track records rather than manufacturing scale alone. The signal to watch is USDA-CVB signaling on mRNA platform licensure pathways, which would trigger incumbent capability acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Culture Manufacturing Transition | Eliminates egg supply vulnerability and accelerates strain-update response velocity for USDA-CVB compliance. |
| Real-World Efficacy Data Infrastructure | Captures post-licensing surveillance relationships with corporate veterinary chains and shelter networks. |
| Multivalent Combination Vaccine Development | Reduces injection burden and secures preferential formulary placement in consolidated hospital networks. |
| Telemedicine-Integrated Home Administration | Expands addressable market into rural segments underserved by traditional clinic-based protocols. |
| Regional Buying Cooperative Partnership | Restores volume leverage for independent clinics responding to corporate chain procurement unbundling. |
Research Methodology
Independent corroboration across veterinary biologics manufacturing executives, regulatory affairs specialists at USDA-CVB, shelter operations directors, corporate veterinary chain procurement managers, and pet insurance reimbursement policy leads underwrites the qualitative findings. Secondary validation draws from FDA-CVM extralabel drug use databases, USDA-CVB adverse event reporting systems, state veterinary practice act compilations, and municipal shelter intake statistics. Bottom-up demand modeling triangulates against top-down market sizing across product type, delivery mode, end user, and price tier segmentation dimensions.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled encompass product type, delivery mode, end user archetype, price tier, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and adjusted for strain-matching protocol compliance thresholds. Forecast inputs include pet insurance penetration trajectories, shelter density regulation adoption rates, and antigenic drift surveillance frequency.
The model holds under stable USDA-CVB licensure timelines and consistent pet insurance reimbursement expansion; deviation in mRNA platform regulatory acceptance or avian influenza outbreak severity would shift manufacturer capability valuations and procurement channel structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Animal Health Market
Animal Health
Cattle Health Market
Animal Health
Animal Healthcare Market
Animal Health
Animal Health Software Market
Animal Health
Equine Healthcare Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
US Military Animals Market
Animal Health
Swine Healthcare Market
Animal Health
Global Companion Animal Health Market
Animal Health
Cattle Healthcare Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Zoonotic Disease Treatment Market