
 Herbal Nutraceuticals Market | 2026-2036
Herbal Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Nutraceuticals Market Outlook
Clean-label extraction technology is tilting formulation standards toward solvent-free and supercritical CO2 processes that preserve bioactive marker compounds. The Himalaya Drug Company leverages its vertically integrated Himalayan herb cultivation to sustain supply security for high-volume botanicals. Amway Corporation anchors its competitive position through direct-to-consumer channel control across Asian markets. Sabinsa Corporation differentiates via patent-protected standardized extracts backed by clinical validation infrastructure.
Herbal nutraceuticals comprise plant-derived bioactive compounds formulated for physiological benefits beyond basic nutrition, typically standardized to marker compounds such as withanolides, curcuminoids, or ginsenosides at specified concentrations. These products serve preventive health applications where synthetic alternatives face consumer skepticism. Herbal extracts command premium positioning due to raw material variability and extraction complexity, while probiotics represent the fastest-expanding category as gut-brain axis research validates strain-specific claims. Dietary supplements absorb the dominant volume share, though functional foods are gaining shelf space as beverage and snack formats integrate adaptogenic botanicals.
The US FDA oversees dietary supplement Good Manufacturing Practices under 21 CFR Part 111, while the European Food Safety Authority evaluates health claims under the Nutrition and Health Claims Regulation, creating divergent compliance burdens for cross-border portfolios. India's Food Safety and Standards Authority mandates Ayurveda-specific licensing pathways that advantage domestic heritage brands with established pharmacopeia documentation. Stakeholders must monitor evolving Novel Food catalog expansions and adaptogen-specific regulatory classifications that will determine which botanicals achieve mainstream pharmacy distribution versus restricted specialty positioning.
Market Dynamics
Clean-label extraction technology is compressing formulation timelines while EFSA's Novel Food Regulation tightens safety documentation requirements for standardized herbal extracts entering European commerce.
Growth Catalysts
- Ayurveda-aligned domestic demand:India's FSSAI licensing pathways advantage heritage brands with established pharmacopeia documentation, accelerating consumer preference for traditional medicine credibility.
- Supercritical CO2 adoption:Functional food manufacturers in Germany are expanding procurement of solvent-free extracts as bioactive marker preservation becomes a procurement priority.
- Gut-brain axis validation:Strain-specific probiotic research is expanding preventive health applications where synthetic alternatives face consumer skepticism.
Market Restraints
- Raw material variability:Himalayan herb cultivation faces climate-induced harvest fluctuations that compress margin predictability for high-volume botanicals.
- Divergent compliance burdens:The US FDA's 21 CFR Part 111 GMP requirements and EFSA's Nutrition and Health Claims Regulation create fragmented documentation costs for cross-border portfolios.
- Extraction complexity premiums:Standardization to withanolides, curcuminoids, or ginsenosides requires capital-intensive chromatographic infrastructure that limits supplier entry.
Strategic Opportunities
- Adaptogen pharmacy distribution:Evolving regulatory classifications for botanicals will determine which compounds achieve mainstream pharmacy positioning versus restricted specialty channels.
- Direct-to-consumer channel control:Asian markets present white space for vertically integrated brands capturing margin through owned distribution networks.
- Beverage format integration:Functional foods and adaptogenic beverages represent shelf space expansion opportunities as snack formats integrate standardized extracts.
Industry Challenges
- Clinical validation infrastructure:Patent-protected standardized extracts require sustained trial investment that strains mid-cap R&D budgets.
- Pharmacopeia documentation gaps:Heritage brands face digitization pressure to convert traditional knowledge into regulator-acceptable safety dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Nutraceuticals Market |
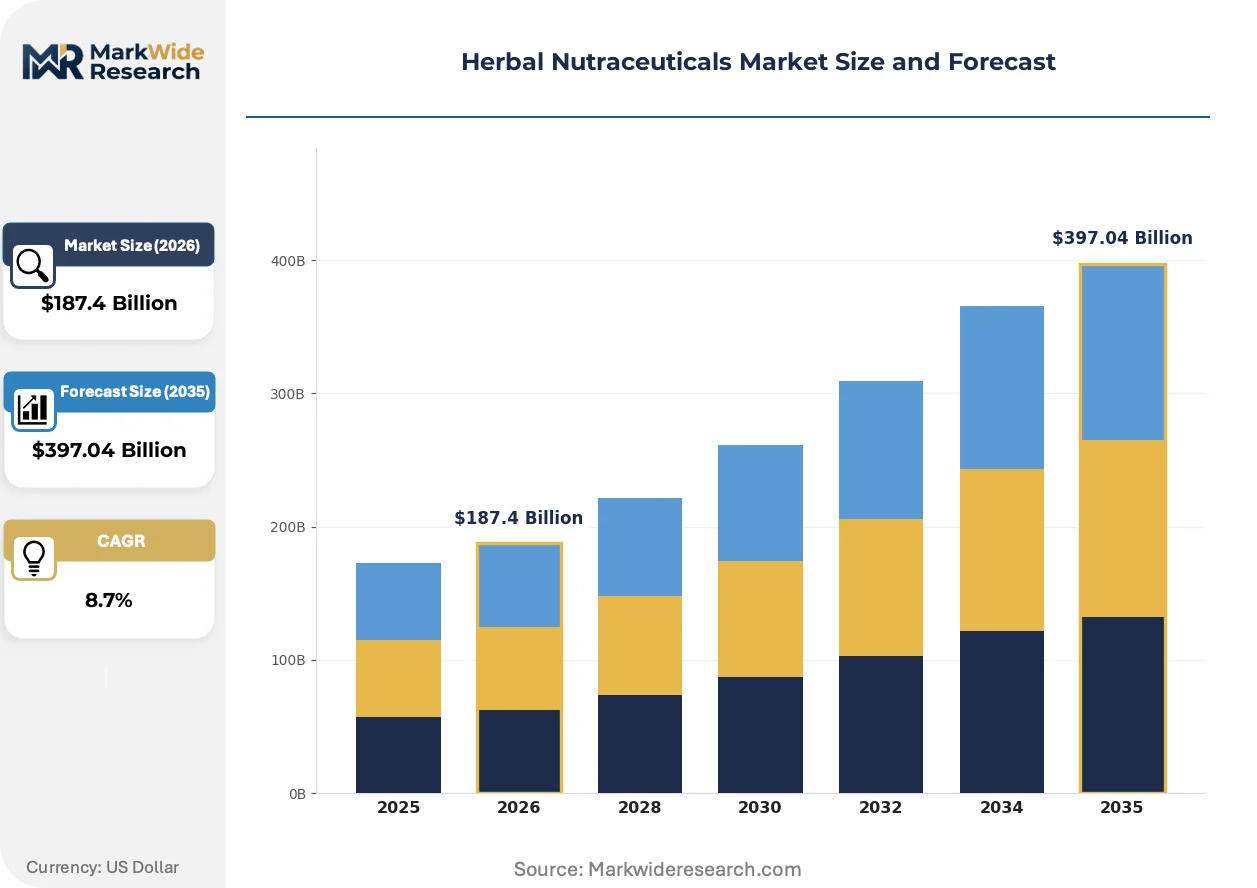
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Probiotics Application: Functional Foods, Dietary Supplements, Personal Care, Pharmaceuticals Form: Pills, Capsules, Powders, Liquid Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | The Himalaya Drug Company, Amway Corporation, Nutraceutical International Corporation, Nature's Bounty, Herbalife Nutrition Ltd., NOW Foods, Gaia Herbs, Sabinsa Corporation, Bio Botanica, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Nutraceuticals Market Strategic Shifts
Bioprocessing automation and regulatory data science are compressing the gap between traditional herbal knowledge and pharmaceutical-grade compliance requirements.
Supercritical fluid extraction systems are digitizing quality assurance workflows through inline spectroscopic monitoring of bioactive marker concentrations. Contract manufacturers serving German functional food producers are adopting these platforms to reduce batch-to-batch variability. The technology is digitizing documentation trails that EFSA Novel Food submissions require.
REACH-compliant solvent traceability mandates are forcing extraction facilities to retrofit volatile organic compound recovery systems. Industrial consequence includes capital reallocation toward closed-loop processing infrastructure. European botanical suppliers are responding by consolidating toll manufacturing relationships to share compliance costs.
Pharmacy buyers are unbundling after-sales technical support from ingredient supply contracts, demanding standalone stability data packages. This behavior disrupts traditional distributor-led technical service models. The shift is most visible in India's Ayurveda-aligned retail chains where pharmacists now specify certificate-of-analysis requirements directly.
Herbal Nutraceuticals Market Segmentation
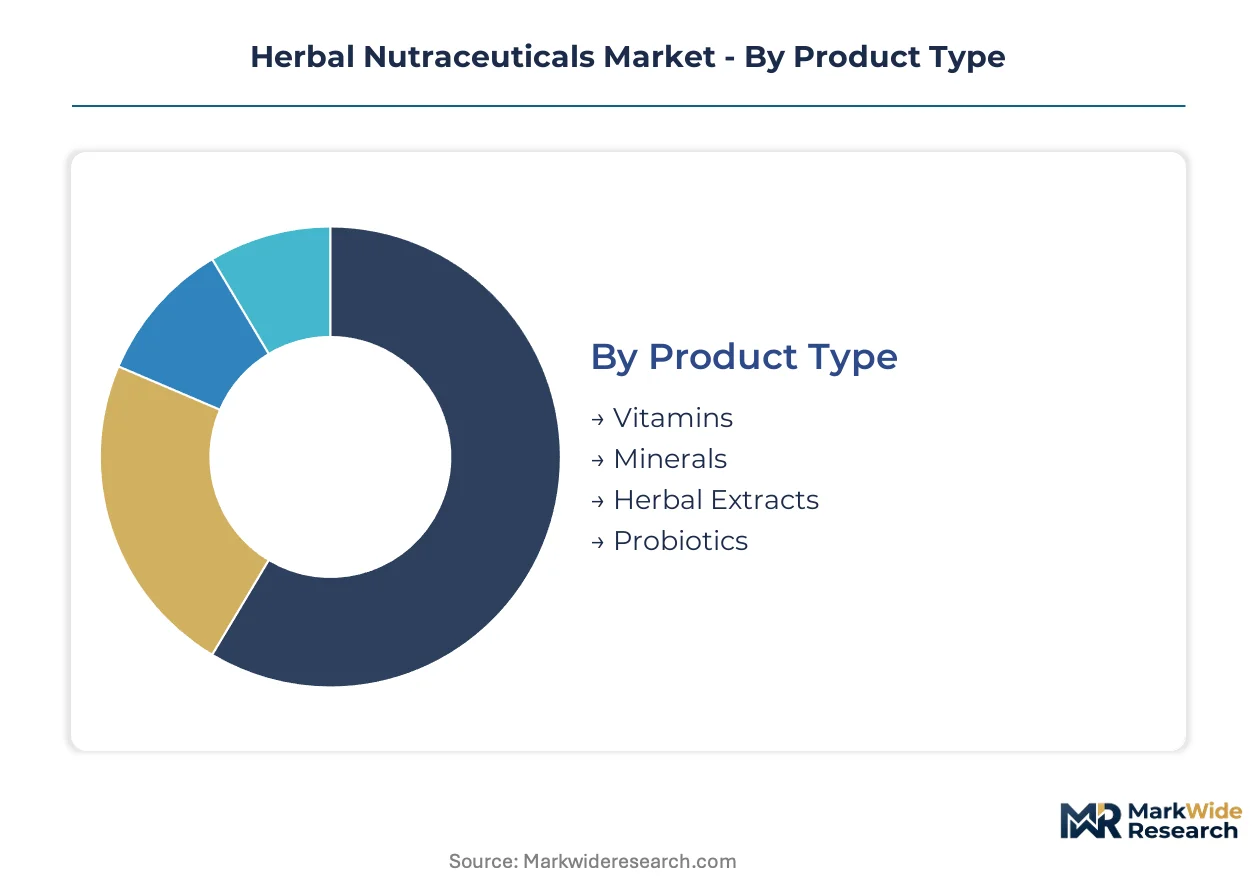
Segmentation in herbal nutraceuticals reveals divergent margin structures and regulatory exposure across product formats. Manufacturers configure supply chains differently for pharmacy-grade extracts versus mass-market functional foods, while distribution channel selection determines compliance documentation intensity.
Product Type:
Cost tier stratification separates commodity vitamins from premium-positioned herbal extracts with marker compound standardization.
- Herbal Extracts:Standardized to specified concentrations of withanolides, curcuminoids, or ginsenosides through chromatographic purification. Demand concentrates in Germany's functional food sector where EFSA Novel Food documentation requirements favor suppliers with validated extraction protocols.
- Probiotics:Strain-specific formulations targeting gut-brain axis applications with live culture stability requirements. India's FSSAI licensing pathways advantage domestic heritage brands with established pharmacopeia documentation for Ayurveda-aligned strains.
- Vitamins:Synthetic and nature-identical compounds serving cost-sensitive preventive health segments.
- Minerals:Chelated and inorganic forms for bioavailability-optimized formulations.
Herbal extracts hold installed capacity. Probiotics are rotating up the share rankings.
Application:
Application scope determines whether products face pharmaceutical-grade GMP requirements or food-grade safety standards.
- Dietary Supplements:Capsule, tablet, and softgel formats regulated under US FDA 21 CFR Part 111 with stringent batch record requirements. Pharmacy buyers in India's Ayurveda-aligned retail chains now specify standalone certificate-of-analysis requirements that disrupt traditional distributor technical service models.
- Functional Foods:Beverage and snack formats integrating adaptogenic botanicals for shelf space expansion. German manufacturers prioritize solvent-free supercritical CO2 extracts as bioactive marker preservation becomes a procurement priority.
- Personal Care:Topical delivery systems with dermal absorption safety testing protocols.
- Pharmaceuticals:Prescription and over-the-counter botanical drugs requiring clinical validation infrastructure.
Dietary supplements anchor volume throughput. Functional foods are climbing the fastest as format innovation accelerates.
Form:
Form factor selection shapes stability testing protocols and consumer compliance rates across demographic segments.
- Capsules:Gelatin and vegetarian shells with enteric coating options for acid-sensitive compounds.
- Pills:Compressed tablets with disintegration time specifications for bioavailability optimization.
- Powders:Bulk and single-serve sachets for flexible dosing and beverage integration.
- Liquid:Tinctures, syrups, and shots with preservative system validation for shelf life extension.
Capsules dominate pharmacy distribution. Powders are gaining share fastest through direct-to-consumer subscription channels.
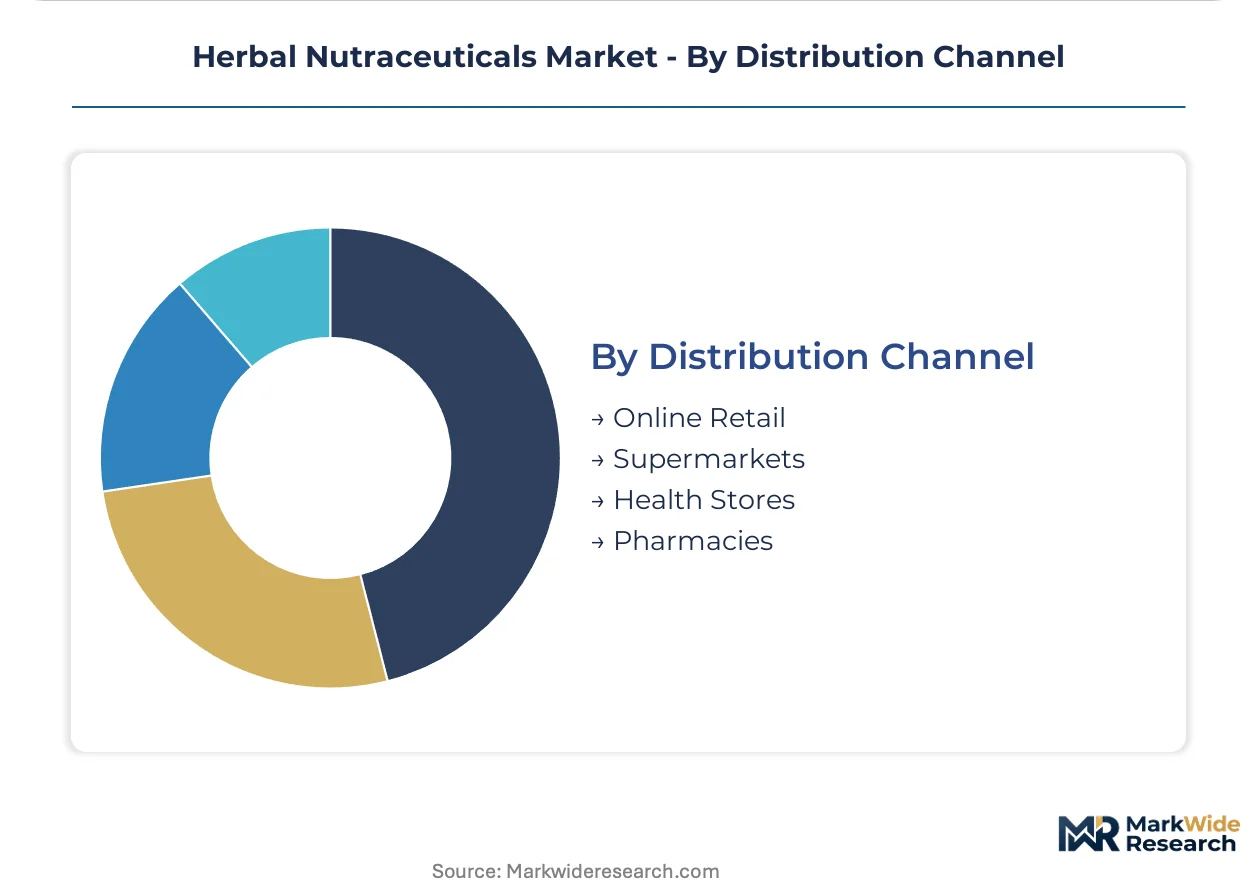
Distribution Channel:
Channel structure dictates margin capture and regulatory documentation intensity for cross-border portfolios.
- Pharmacies:Professional recommendation-driven sales with pharmacopeia-grade documentation requirements. India's Ayurveda-aligned retail chains unbundle after-sales technical support from ingredient contracts, demanding standalone stability data packages.
- Online Retail:Direct-to-consumer platforms enabling vertically integrated brands to capture margin through owned distribution networks across Asian markets.
- Supermarkets:Mass-market placement with price-competitive positioning and shelf space negotiation.
- Health Stores:Specialty retail with educated consumer base and premium product tolerance.
Pharmacies maintain institutional credibility. Online retail is expanding most quickly as logistics infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports standardized herbal extracts to Germany's functional food manufacturers, creating a trade-flow corridor shaped by divergent regulatory documentation requirements between EFSA Novel Food submissions and domestic Ayurveda licensing pathways.
United States
Direct-to-consumer channel expansion drives demand for adaptogenic beverages and subscription-formatted supplements. The FDA's 21 CFR Part 111 GMP requirements enforce stringent batch record protocols that favor established manufacturers with validated quality systems. California's Bay Area hosts formulation startups integrating bioactive marker testing into product development workflows.
Germany
Functional food manufacturers prioritize solvent-free supercritical CO2 extracts as bioactive preservation becomes a procurement criterion. EFSA's Novel Food Regulation mandates extensive safety documentation that compresses supplier qualification timelines. Bavaria's ingredient processing clusters concentrate toll manufacturing relationships for shared compliance cost structures.
India
Ayurveda-aligned consumer preference accelerates domestic brand loyalty for heritage formulations with pharmacopeia documentation. FSSAI licensing pathways create regulatory advantages for established players with traditional medicine credibility. Maharashtra's Mumbai-Pune corridor anchors vertically integrated cultivation-to-retail operations for high-volume botanicals.
China
Traditional Chinese Medicine modernization programs expand standardized extract capacity for export markets. NMPA oversight of health food registration creates dual-track compliance for domestic versus international product lines. Zhejiang and Jiangsu provinces concentrate extraction facilities serving European and North American contract manufacturing demand.
Japan
Aging demographics drive preventive health applications for gut-brain axis validated probiotics and botanical compounds. PMDA's Foods with Function Claims system requires clinical evidence packages that advantage research-capable suppliers. Tokyo-Osaka metropolitan corridors concentrate pharmacy distribution networks for premium-positioned herbal formulations.
Herbal Nutraceuticals Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin capture models. The vendor base organizes into three tiers: vertically integrated heritage brands with captive cultivation, direct-to-consumer platform operators with owned distribution networks, and research-driven extract specialists with patent-protected standardization. Consolidation pressure concentrates among mid-cap manufacturers lacking clinical validation infrastructure. Dominant competitive moves include backward integration into Himalayan herb cultivation and strategic partnerships for shared EFSA Novel Food documentation costs.
Within the heritage brand tier, The Himalaya Drug Company and Amway Corporation occupy positions defined by channel control and geographic footprint respectively. Sabinsa Corporation anchors the specialist extract segment through patent-protected standardization infrastructure. These three entities exemplify the competitive archetypes reshaping procurement relationships with German functional food manufacturers and India's Ayurveda-aligned retail chains.
| Leading Market Players |
|---|
| The Himalaya Drug Company |
| Amway Corporation |
| Nutraceutical International Corporation |
| Nature's Bounty |
| Herbalife Nutrition Ltd. |
| NOW Foods |
| Gaia Herbs |
| Sabinsa Corporation |
| Bio Botanica, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Mumbai-Rotterdam maritime corridor carries standardized herbal extracts from India's Ayurveda processing clusters to Germany's functional food manufacturers, with freight cost volatility compressing margin buffers for mid-tier suppliers while amplifying price premiums for EFSA Novel Food-compliant documentation packages. This logistics artery concentrates pricing power among vertically integrated heritage brands with captive Himalayan cultivation, forcing contract manufacturers to absorb documentation cost inflation or cede shelf space to solvent-free supercritical CO2 extract specialists.
Pricing Analysis
Prior-generation solvent-based extraction commands economy-tier positioning at commodity vitamin price points, while current-generation supercritical CO2 processing sustains mid-tier premiums through bioactive marker preservation guarantees, and next-generation inline spectroscopic monitoring systems are compressing batch-to-batch variability premiums toward standard-tier pricing. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-grade pharmacopeia documentation from functional food-grade stability data from commodity bulk extracts. Pricing pressure stems from REACH-compliant solvent traceability mandates forcing European toll manufacturers to retrofit volatile organic compound recovery systems. Contract manufacturers exhibit highest price sensitivity due to shared compliance cost structures, while direct-to-consumer heritage brands with owned cultivation show lowest sensitivity.
Supply Chain Analysis
Upstream Himalayan herb cultivation draws from climate-vulnerable high-altitude zones in India, Nepal, and Bhutan, with harvest fluctuations feeding raw material variability into margin predictability for high-volume botanicals. Chromatographic purification infrastructure, supercritical fluid extraction systems, and closed-loop solvent recovery equipment constitute capital-intensive component dependencies. Single-source vulnerability concentrates around Maharashtra's Mumbai-Pune corridor for vertically integrated cultivation-to-retail operations. Distribution runs through pharmacy networks for premium-positioned extracts, direct-to-consumer platforms for subscription-formatted powders, and supermarket mass-market placement for functional food-integrated adaptogens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where FSSAI licensing pathways and EFSA Novel Food documentation requirements create switching costs that cement heritage brand positions against agile contract manufacturers lacking pharmacopeia digitization infrastructure.
For Market Incumbents: Build pharmacopeia documentation moats by converting traditional Ayurveda knowledge into regulator-acceptable safety dossiers that satisfy India's FSSAI digitization pressure. Add supercritical CO2 capacity in Bavaria's ingredient processing clusters to share EFSA compliance costs through toll manufacturing consolidation. Patent-protected standardized extract competitors threaten margin capture unless clinical validation infrastructure is sustained through trial investment.
For New Entrants and Emerging Players: Pursue white-space in direct-to-consumer adaptogenic beverage formats across Asian markets where logistics infrastructure maturation enables owned distribution network margin capture. India's Ayurveda-aligned retail chains present the most penetrable geography given unbundled after-sales technical support demands disrupting traditional distributor models. Launch through standalone stability data package offerings that pharmacy buyers now specify directly, bypassing legacy technical service intermediaries.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap manufacturers lacking clinical validation infrastructure and facing consolidation pressure from research-driven extract specialists. Long-term viability over the projection horizon favors patent-protected standardization capabilities and captive Himalayan herb cultivation security. Watch for evolving adaptogen-specific regulatory classifications as the inflection signal determining which botanicals achieve mainstream pharmacy distribution versus restricted specialty positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Himalayan Cultivation | Captive supply of high-volume botanicals insulates margin predictability from climate-induced harvest fluctuations. |
| Supercritical CO2 Capacity Expansion | Solvent-free extraction protocols satisfy German functional food procurement priorities for bioactive marker preservation. |
| Pharmacopeia Digitization Investment | FSSAI-compliant safety dossiers convert traditional Ayurveda knowledge into defensible regulatory entrenchment. |
| Direct-to-Consumer Platform Launch | Owned distribution networks across Asian markets capture margin otherwise lost to pharmacy and supermarket intermediaries. |
| Clinical Validation Infrastructure Buildout | Patent-protected standardized extracts require sustained trial investment to defend against mid-cap R&D budget constraints. |
Study Parameters
Cross-validation between primary interviews with herbal extract procurement managers, regulatory affairs leads at functional food manufacturers, pharmacy category buyers, and Ayurveda heritage brand supply chain directors anchors the qualitative findings against secondary validation from FSSAI licensing databases, EFSA Novel Food submission registers, customs trade flow records, and SEC filings of publicly listed nutraceutical companies. Bottom-up segment sizing triangulates against top-down market envelope checks.
Calibration against historical CAGRs from analogous botanical extract markets and cross-reference with capacity expansion announcements shapes the analytical framework across product type, application, form factor, and distribution channel segmentation dimensions. Growth trajectory modeling incorporates bioactive marker standardization adoption curves, gut-brain axis research publication velocity, and regulatory classification evolution timelines as industry-specific forecast inputs without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by contract manufacturers or rapid pharmacopeia digitization by emerging heritage brands would shift outcomes beyond modeled ranges. Cross-checking against EFSA Novel Food approval velocity and FSSAI licensing backlog data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
LAMEA Digestive Enzymes Market
Nutraceuticals
Fish-Oil Based Drugs Market
Nutraceuticals
Pygeum Bark Extract Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Asia-Pacific Effervescent Tablet Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
Chondroitin Market
Nutraceuticals
Cordyceps Militaris Extract Market
Nutraceuticals
Coenzyme Q10 Market
Nutraceuticals
Healthy Care Coenzyme Q10 Market
Nutraceuticals
Micro-Ecological Regulators Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Ayurvedic Products Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market