
 Laboratory Animal Models Market | 2026-2036
Laboratory Animal Models Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Animal Models Market Outlook
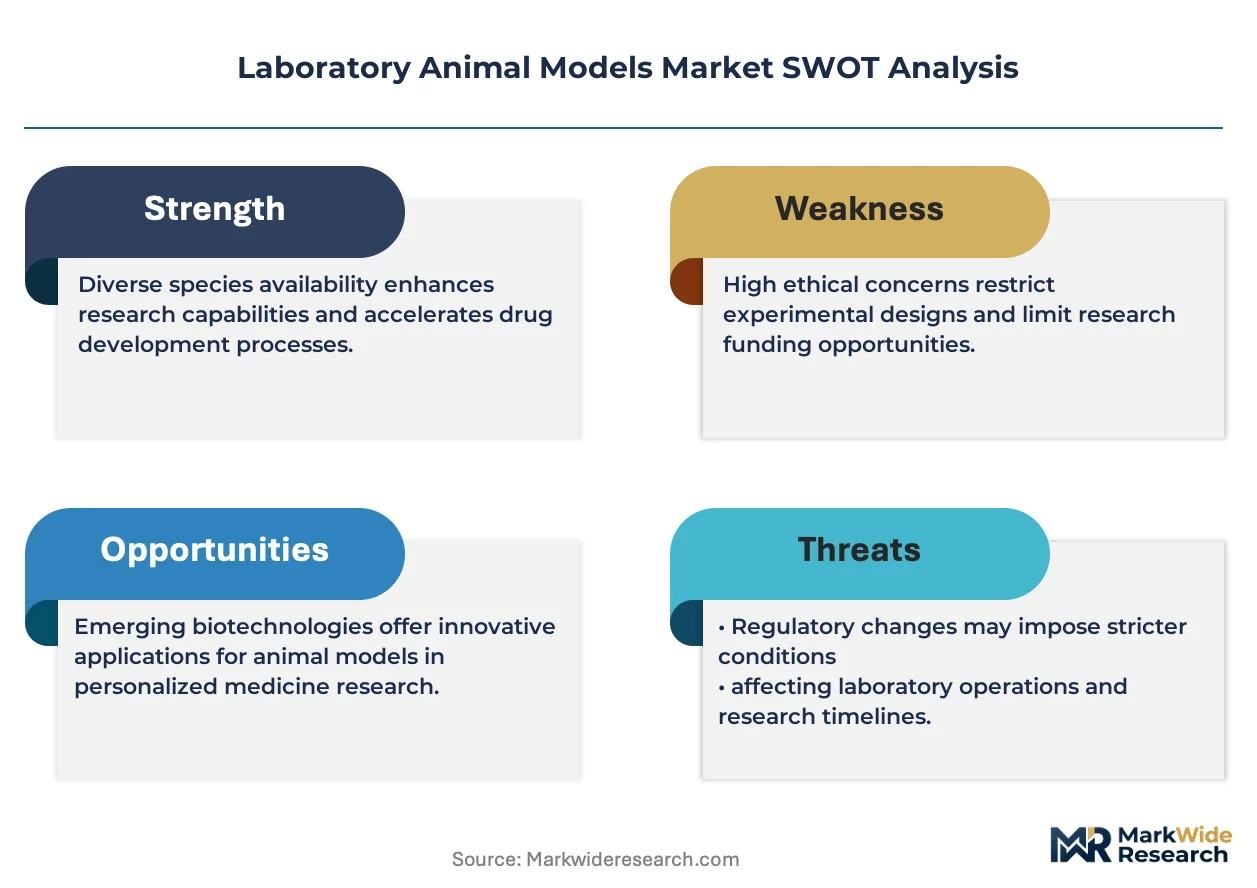
Asset-light leasing of genetically engineered rodent colonies is reconfiguring competitive dynamics in laboratory animal supply. Charles River Laboratories leverages captive breeding networks across North America to sustain its position in high-complexity immunodeficient models. The Jackson Laboratory anchors academic and government demand through its repository of standardized inbred strains. Taconic Biosciences specializes in rapid-turnaround contract breeding, competing on delivery speed for CRISPR-edited lines.
Laboratory animal models are living organisms bred or modified to exhibit specific genetic, physiological, or pathological traits for controlled scientific study, with mice and rats constituting over eighty percent of specimens due to short gestation cycles and sequenced genomes. These models serve as predictive systems for human disease progression, therapeutic efficacy, and toxicological safety prior to clinical translation. The Application dimension shows Drug Discovery commanding the largest revenue share, while Genetic Research represents the fastest-expanding segment as CRISPR precision editing reduces model development timelines. Within End User categories, Contract Research Organizations are capturing disproportionate growth as pharmaceutical firms outsource preclinical validation to reduce fixed infrastructure costs.
The FDA's Animal Rule pathway and EMA's Directive 2010/63/EU on animal welfare standards shape model validation requirements and facility accreditation protocols across supplier networks. ISO 10993 biocompatibility testing standards and AAALAC International accreditation further constrain market entry by mandating documented husbandry and veterinary oversight. Stakeholders must monitor evolving regulatory acceptance of alternative methods and gene-editing governance to anticipate shifts in model demand specifications and compliance investment thresholds.
Market Dynamics
CRISPR precision editing is compressing model development timelines from years to months, while harmonized FDA and EMA welfare standards are raising facility compliance thresholds and reshaping supplier economics across the preclinical services ecosystem.
Growth Catalysts
- Preclinical Pipeline Expansion:Pharmaceutical firms are escalating outsourced validation studies to reduce fixed infrastructure costs, driving demand for contract-bred immunodeficient rodent colonies.
- EMA Directive 2010/63/EU:Stricter European welfare accreditation protocols are forcing facility upgrades that favor large-scale breeders with documented veterinary oversight and AAALAC International certification.
- Gene Editing Maturation:CRISPR-Cas9 workflows are enabling rapid generation of patient-derived xenograft models, accelerating oncology and immuno-oncology study initiation timelines.
Market Restraints
- Input Cost Volatility:Specialized pathogen-free feed and barrier facility energy consumption expose suppliers to agricultural commodity and utility price swings.
- Supply Concentration Risk:North American captive breeding networks dominate high-complexity immunodeficient model production, creating geographic vulnerability to regional disease outbreaks or logistics disruptions.
- Regulatory Friction:The FDA's Animal Rule pathway imposes stringent validation documentation that extends model qualification periods and elevates compliance overhead for novel genetically engineered lines.
Strategic Opportunities
- Biotech Cluster Proximity:San Diego and Boston corridor expansion offers localized breeding capacity to serve just-in-time model customization orders from emerging cell therapy developers.
- Alternative Method Convergence:Organoid and organ-on-chip technology maturation is creating hybrid validation workflows where animal models serve as confirmatory rather than primary screens.
- Academic Repository Access:Standardized inbred strain archives present licensing revenue streams for institutions with deep cryopreservation capabilities and documented pedigree databases.
Industry Challenges
- Veterinary Pathology Talent Scarcity:Board-certified laboratory animal veterinarians with transgenic model expertise remain concentrated at established suppliers, constraining facility expansion.
- CRISPR IP Licensing Complexity:Broad Institute and University of California patent disputes create uncertainty around royalty stacking for commercial model developers.
- Facility Reconfiguration Costs:ISO 10993 biocompatibility testing compliance and barrier maintenance capex requirements delay ROI for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Animal Models Market |
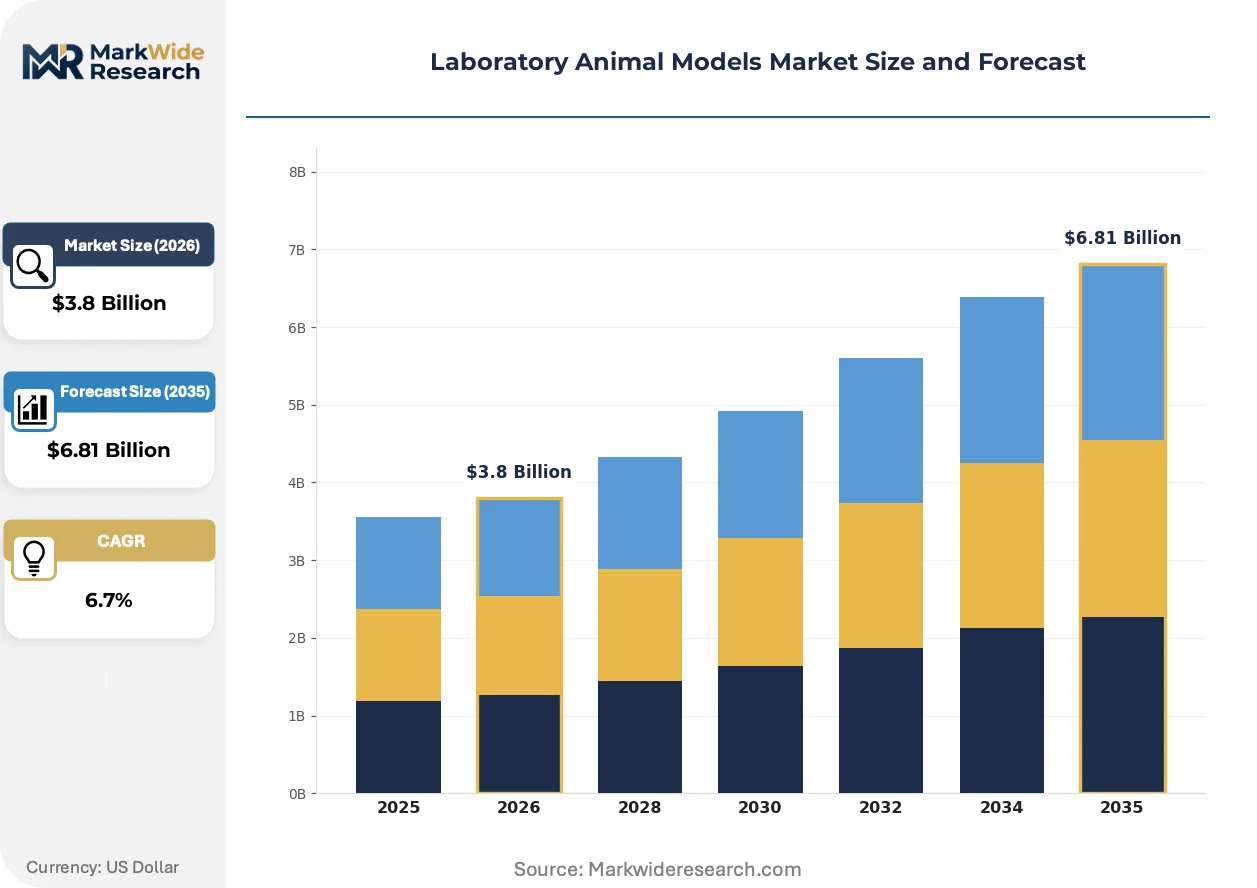
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Model Type: Mice, Rats, Guinea Pigs, Rabbits Application: Drug Discovery, Toxicology Testing, Genetic Research, Behavioral Studies End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Biotechnology Firms Service Type: Breeding Services, Health Monitoring, Research Services, Laboratory Management |
| Companies Covered | Charles River Laboratories, The Jackson Laboratory, Taconic Biosciences, genOway, Janvier Labs, Inotiv, Crown Bioscience, Envigo, Biocytogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Animal Models Market Strategic Shifts
Gene editing automation and welfare monitoring telemetry are converging to transform how laboratory animal models are produced, validated, and deployed across pharmaceutical and academic research networks.
CRISPR-Cas9 multiplexing platforms are rendering obsolete traditional embryonic stem cell targeting methods for complex immunodeficient humanization. Contract research organizations in oncology and immuno-oncology verticals are adopting these workflows at accelerating velocity. The structural compression of model generation timelines is enabling iterative study designs previously infeasible under conventional breeding schedules.
EMA's evolving interpretation of Directive 2010/63/EU on severity classification and retrospective assessment is mandating real-time welfare telemetry integration in accredited facilities. Industrial consequence includes mandatory capital deployment into automated behavior monitoring and environmental control systems. European contract research organizations are responding by consolidating supplier relationships toward breeders with pre-installed digital compliance infrastructure.
Academic and government laboratories are consolidating procurement through centralized repository agreements rather than maintaining in-house breeding colonies. This channel shift is displacing direct-to-laboratory sales for standardized inbred strains. The transition is most visible in United States National Institutes of Health-funded institutions, where per-animal cost accounting now favors external sourcing for all but highly specialized genetically engineered lines.
Laboratory Animal Models Market Segmentation
Segmentation in laboratory animal models reveals how supplier capabilities align with distinct research workflows. Pharmaceutical pipelines, academic funding cycles, and regulatory validation requirements each demand specialized model specifications and service configurations.
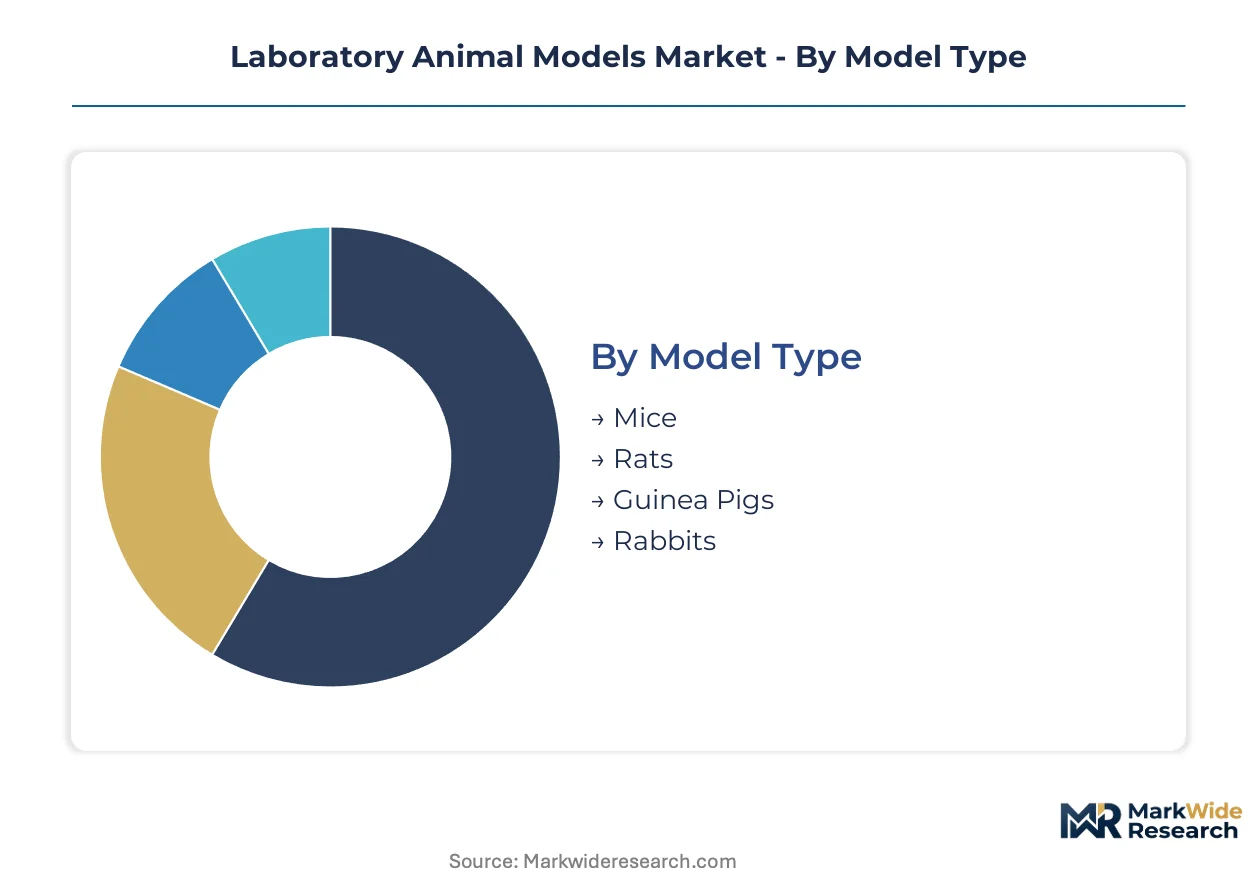
Model Type:
Cost tier stratification across model categories reflects breeding complexity, genetic engineering investment, and pathogen-free maintenance overhead.
- Mice:Short gestation cycles and fully sequenced genomes enable rapid CRISPR editing for oncology and immuno-oncology studies. Pharmaceutical companies in the United States concentrate orders for immunodeficient humanized lines as cell therapy pipelines expand.
- Rats:Larger physiological scale suits toxicology and pharmacokinetic studies where blood volume requirements exceed murine capacity. Toxicology testing demand from contract research organizations drives specialized outbred colony maintenance.
- Guinea Pigs:Historical use in auditory and respiratory research sustains niche demand from academic institutions with established protocol libraries.
- Rabbits:Large vessel access and human-scale ocular anatomy support cardiovascular and ophthalmology device testing for FDA biocompatibility submissions.
Mice hold installed capacity. Rats is rotating up the share rankings.
Application:
Application dimension tracks where research investment concentrates across the preclinical development cycle and basic science funding priorities.
- Drug Discovery:Target validation and lead optimization consume the largest model volumes, with oncology and rare disease programs driving genetically engineered line customization. United States biotechnology clusters in Boston and San Diego generate concentrated demand for patient-derived xenograft models.
- Toxicology Testing:Regulatory safety assessment mandates repeat-dose and carcinogenicity studies using standardized outbred stocks. FDA GLP compliance requirements constrain supplier qualification to facilities with documented veterinary pathology capabilities.
- Genetic Research:CRISPR precision editing is compressing model development timelines, expanding academic and government laboratory access to complex disease models. This segment is climbing the fastest as funding agencies prioritize mechanistic biology.
- Behavioral Studies:Neuroscience and psychiatric drug development relies on specialized apparatus and trained technical staff, limiting supplier participation to dedicated behavioral cores.
Drug Discovery holds installed capacity. Genetic Research is rotating up the share rankings.
End User:
Customer type segmentation captures divergent procurement patterns between centralized pharmaceutical outsourcing and distributed academic purchasing.
- Pharmaceutical Companies:Vertical integration pressures and pipeline volatility drive asset-light strategies, concentrating demand on contract breeding and research services rather than captive colonies.
- Academic Institutions:NIH-funded researchers are consolidating procurement through centralized repository agreements, displacing in-house breeding for standardized inbred strains.
- Contract Research Organizations:Preclinical outsourcing acceleration positions CROs as the fastest-expanding demand channel, capturing disproportionate growth in immunodeficient model volumes.
- Biotechnology Firms:Emerging cell therapy developers in United States coastal clusters require rapid-turnaround customization, favoring regional breeding partnerships over distant suppliers.
Pharmaceutical Companies hold installed capacity. Contract Research Organizations is rotating up the share rankings.
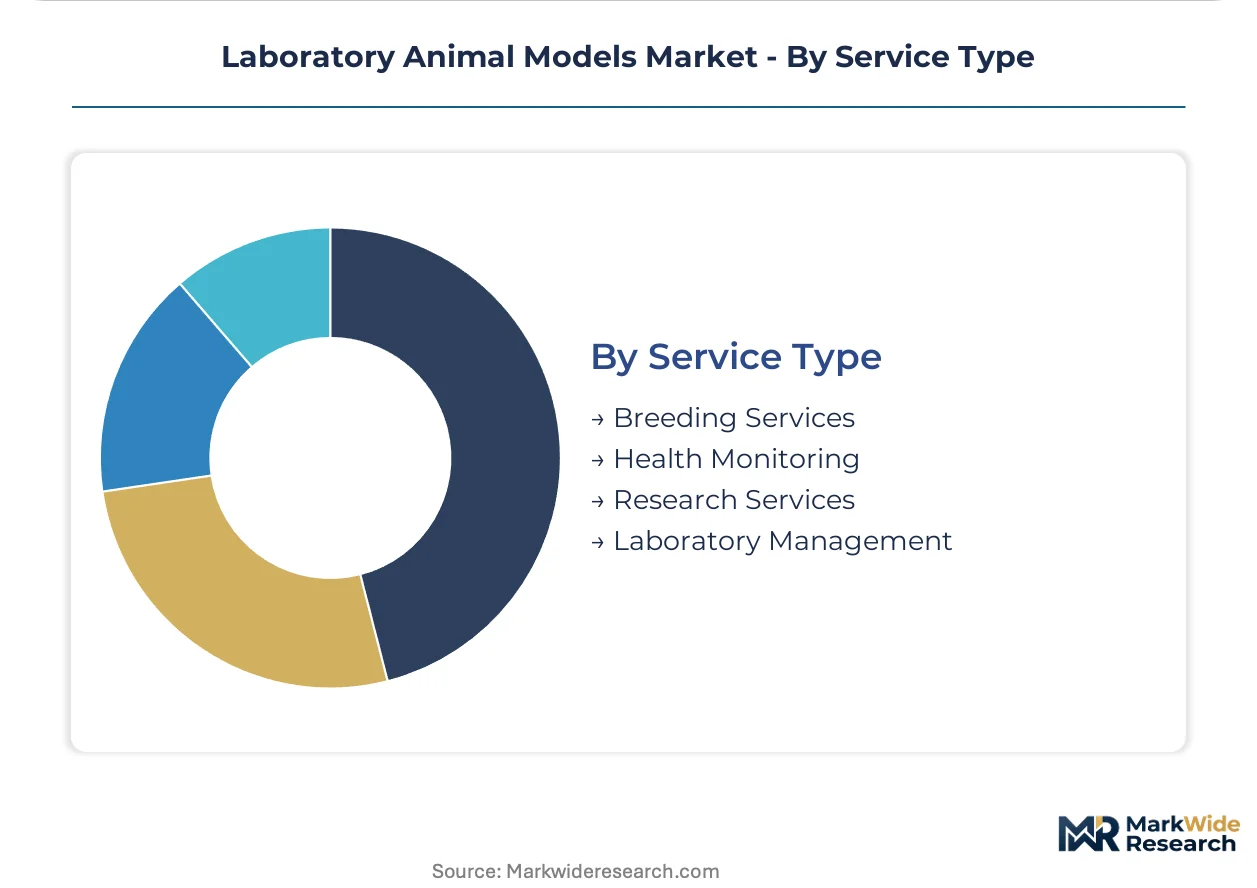
Service Type:
Service configuration determines supplier margin structure and capital intensity, from high-volume breeding to specialized pathology diagnostics.
- Breeding Services:Pathogen-free colony expansion and genetic quality control constitute the volume base, with CRISPR-edited line production commanding premium pricing due to technical complexity and IP licensing overhead.
- Health Monitoring:Microbiome surveillance and sentinel screening programs are becoming mandatory under EMA Directive 2010/63/EU severity classification protocols, forcing facility telemetry upgrades.
- Research Services:In vivo pharmacology and efficacy study execution captures higher margins than commodity breeding, requiring GLP certification and board-certified veterinary pathology staff.
- Laboratory Management:Facility design, compliance documentation, and training services address accreditation requirements for new market entrants facing ISO 10993 and AAALAC International standards.
Breeding Services holds installed capacity. Research Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in laboratory animal models tilt heavily toward surplus economies with captive breeding infrastructure and AAALAC-accredited facilities. Import demand concentrates in research-intensive jurisdictions lacking domestic high-complexity immunodeficient production.
United States
Pharmaceutical outsourcing and NIH-funded academic consolidation drive model volumes. FDA Animal Rule pathway requirements shape validation documentation standards for genetically engineered lines. Boston and San Diego biotech clusters generate concentrated demand for patient-derived xenograft customization.
Germany
EMA Directive 2010/63/EU enforcement elevates facility compliance thresholds across preclinical service providers. The country's national pharmaceutical regulator mandates severity classification protocols with retrospective assessment requirements. Heidelberg and Munich research corridors favor regional breeding partnerships over distant suppliers.
United Kingdom
Post-Brexit divergence from EU animal welfare frameworks creates parallel accreditation complexity for cross-border suppliers. Home Office licensing requirements maintain stringent project authorization procedures. Cambridge and Oxford academic concentrations consolidate procurement through centralized repository agreements.
China
Domestic cell therapy pipeline expansion accelerates demand for CRISPR-edited immunodeficient lines. NMPA preclinical guidance convergence with ICH standards elevates documentation expectations for novel models. Shanghai and Suzhou biotech parks attract regional breeding capacity investments from established suppliers.
Japan
PMDA harmonization with FDA toxicology study designs sustains standardized outbred rat demand for regulatory submissions. METI funding priorities favor mechanistic biology programs requiring complex genetically engineered mice. Osaka and Tokyo pharmaceutical R&D centers maintain just-in-time ordering relationships with accredited breeders.
Laboratory Animal Models Market Competitive Environment
On the supply side, the industry is consolidating around large-scale captive breeding networks with documented veterinary oversight and barrier facility infrastructure. Tiered competitive positioning separates full-service preclinical providers from specialized genetic engineering boutiques. Three archetypes dominate: integrated research service organizations, repository-centric academic suppliers, and rapid-turnaround contract breeders. Capacity expansion and strategic technology licensing constitute the primary competitive vectors as CRISPR workflows commoditize.
Within the integrated service tier, Charles River Laboratories exemplifies scale-driven preclinical infrastructure with North American breeding network dominance. The Jackson Laboratory anchors academic and government demand through repository specialization. Taconic Biosciences occupies a position emphasizing rapid-turnaround contract breeding for customized genetically engineered lines.
| Leading Market Players |
|---|
| Charles River Laboratories |
| The Jackson Laboratory |
| Taconic Biosciences |
| genOway |
| Janvier Labs |
| Inotiv |
| Crown Bioscience |
| Envigo |
| Biocytogen |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on North American pathogen-free breeding networks determines both pricing tier spreads and supply chain shape. Pharmaceutical outsourcing patterns concentrate purchasing power among contract research organizations, compressing margins for standardized inbred strains while preserving premiums for CRISPR-edited customization.
Pricing Analysis
Pharmaceutical companies anchor pricing stratification across premium, standard, and economy tiers. CRISPR-edited immunodeficient lines command substantial premiums over conventional outbred stocks due to genetic complexity and IP licensing overhead. Cost compression in commodity breeding intensifies because academic procurement consolidation favors volume discounts. Contract research organizations exhibit highest price sensitivity for standardized strains, while biotechnology developers show lowest sensitivity for rapid-turnaround customization.
Supply Chain Analysis
Specialized pathogen-free feed formulations draw from agricultural commodity markets in the United States, Canada, and Argentina. Barrier facility construction materials and veterinary equipment hinge on precision manufacturing from Germany, Japan, and the United States. Single-source vulnerability concentrates in high-complexity immunodeficient model production, where regional disease outbreaks would disrupt global availability. Distribution runs through AAALAC-accredited captive breeding networks serving biotech cluster corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory animal models market tracks pharmaceutical R&D cycle recovery. Preclinical pipeline expansion following cell therapy investment waves sustains demand visibility across the projection horizon.
For Market Incumbents: Insulate breeding network economics by deepening captive supply of CRISPR-edited founder lines, reducing royalty exposure to Broad Institute patent disputes. Accelerate facility telemetry upgrades ahead of EMA severity classification enforcement to capture European contract research organization consolidation. Prioritize veterinary pathology talent retention through specialized compensation structures. For New Entrants and Emerging Players: China's domestic cell therapy pipeline expansion offers the most penetrable geography, where NMPA guidance convergence with ICH standards elevates documentation expectations without entrenched supplier relationships. Target rapid-turnaround contract breeding for patient-derived xenograft models serving Shanghai and Suzhou biotech parks. Pursue regional breeding partnerships rather than national distribution. For Investors and Strategic Acquirers: FDA Animal Rule pathway maturation reshapes the acquisition landscape by elevating compliance documentation capabilities to strategic premium status. Long-term viability centers on facilities with pre-installed digital welfare telemetry and documented GLP pharmacology execution. Monitor EMA retrospective assessment implementation velocity as the inflection indicator for European facility upgrade capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Platform Licensing | Broad Institute patent clarity reduces royalty stacking uncertainty for commercial model developers. |
| Barrier Facility Telemetry Deployment | EMA Directive 2010/63/EU severity classification mandates real-time welfare monitoring infrastructure. |
| Veterinary Pathology Talent Acquisition | Board-certified laboratory animal veterinarians remain concentrated at established suppliers, constraining expansion. |
| Regional Breeding Partnership Formation | San Diego and Boston corridor proximity enables just-in-time model customization for cell therapy developers. |
| Academic Repository Consolidation | NIH-funded institutions favor centralized procurement agreements, displacing direct-to-laboratory sales. |
Study Parameters
Desk research of regulatory filing databases, scientific publication repositories, and institutional procurement records preceded structured interviews with drug development executives, preclinical services procurement leads, laboratory animal veterinarians, and facility accreditation specialists. Primary fieldwork captured operational metrics from breeding network operators and contract research organization model sourcing practices. Secondary validation drew from FDA Animal Rule guidance documents, EMA Directive 2010/63/EU implementation reports, and AAALAC International accreditation databases. Bottom-up model generation across supplier capacity and top-down demand validation from pharmaceutical pipeline tracking were triangulated.
Assumptions held fixed include regulatory acceptance timelines for novel genetically engineered lines and AAALAC accreditation maintenance rates. Variables tested across sensitivity scenarios encompassed CRISPR editing cost reduction velocity and academic outsourcing penetration. Segmentation dimensions modeled spanned model type complexity tiers, application workflow stages, end-user procurement centralization patterns, and service configuration margin structures. CAGRs were derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated pharmaceutical preclinical pipeline expansion rates and NIH funding allocation shifts.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices or utility energy costs would shift the trajectory. Forecasts reflect assumptions around regulatory harmonization pace and gene editing IP resolution. Cross-checking against pharmaceutical R&D expenditure surveys and academic laboratory animal usage statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Cattle Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
US Companion Animal Health Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
China Companion Animal Health Market
Animal Health
Animal Health Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Canada Animal Health Care Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Global Companion Animal Health Market
Animal Health
Canine Arthritis Treatment Market