
 Companion Animal Medicine Market | 2026-2036
Companion Animal Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Companion Animal Medicine Market Intelligence
Multi-source API procurement is pivoting toward captive manufacturing as sponsors seek supply security for biologic parasiticides. Zoetis Services LLC anchors its dermatology franchise through in-house monoclonal antibody production. Dechra Pharmaceuticals specializes in narrow-aqueous formulations for transdermal delivery. Boehringer Ingelheim International GmbH dominates the oral vaccine segment with its thermostable platform technology.
Companion animal medicine comprises pharmaceutical and biological agents formulated for therapeutic or prophylactic use in dogs, cats, and other household pets, with active ingredients typically dosed by body weight and species-specific metabolism. These products prevent infectious disease, manage chronic conditions, and control ectoparasite burdens in clinical and home settings. Parasiticides command the largest revenue pool among product types due to year-round compliance programs and OTC channel expansion. Oncology represents the fastest-expanding treatment area as veterinary reference laboratories scale companion diagnostic testing. Injectable administration routes retain premium pricing power in hospital settings despite oral convenience formats gaining traction in retail pharmacy channels.
The FDA Center for Veterinary Medicine mandates New Animal Drug Application pathways for novel small-molecule therapeutics, while EMA veterinary marketing authorizations enforce batch consistency standards for vaccines distributed across EU member states. USDA APHIS regulates veterinary biologics manufacturing through facility licensing and potency testing protocols, shaping where companies locate bulk antigen production. Stakeholders must monitor how FDA draft guidance on platform technologies will compress development timelines for monoclonal antibody products.
Market Dynamics
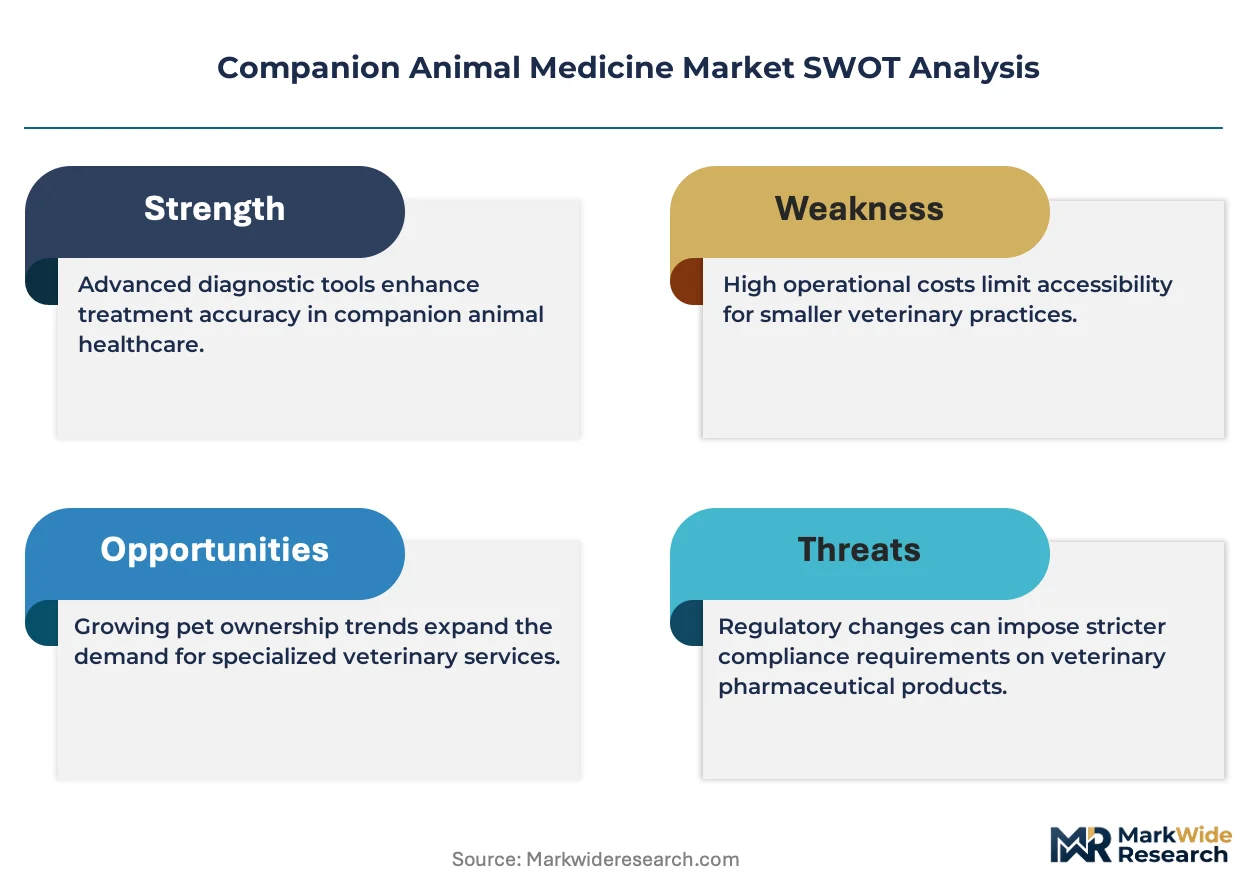
Captive biologics manufacturing is reshaping competitive positioning as sponsors internalize monoclonal antibody production to secure supply continuity against tightening FDA Center for Veterinary Medicine pharmacovigilance requirements.
Growth Catalysts
- EMA Veterinary Marketing Authorization batch consistency standards:These protocols elevate manufacturing quality across EU member states, accelerating professional channel preference for certified biologicals over unregulated alternatives.
- Pet insurance penetration in the United States:Specialty veterinary referral networks deepen treatment access as reimbursement frameworks expand coverage for chronic disease management and oncology protocols.
- Monoclonal antibody platform technologies:FDA draft guidance on streamlined approval pathways compresses development timelines for novel therapeutics targeting atopic dermatitis and osteoarthritis in companion species.
Market Restraints
- API supply concentration in Asian contract manufacturers:Bulk chemical sourcing for small-molecule parasiticides remains dependent on limited qualified suppliers, exposing formulators to input volatility and qualification delays.
- USDA APHIS facility licensing timelines:Veterinary biologics manufacturing site approvals extend 18-24 months, constraining rapid capacity expansion for thermostable oral vaccine production.
- Species-specific metabolism complexity:Feline cytochrome P450 enzyme deficiencies limit therapeutic options and require costly reformulation for drugs initially developed for canine indications.
Strategic Opportunities
- Underpenetrated Japanese companion animal channel:METI regulatory harmonization initiatives and aging pet demographics create whitespace for imported specialty therapeutics and reference laboratory services.
- Transdermal narrow-aqueous formulation convergence:Lipid nanoparticle delivery systems combined with microneedle patches enable home administration of previously injectable biologics, expanding retail pharmacy participation.
- India PLI scheme for pharmaceutical manufacturing:Domestic production incentives attract contract development organizations seeking cost-competitive bulk antigen production for export markets.
Industry Challenges
- Veterinary pharmacology specialist scarcity:Companion animal clinical pharmacologists command premium compensation as academic programs fail to match industry demand for dose-optimization expertise.
- Cold chain infrastructure capex for biologics:Thermolabile monoclonal antibodies require validated storage and distribution networks that strain regional veterinary clinic capital budgets.
- Cross-species immunogenicity assessment complexity:Anti-drug antibody testing protocols lack standardization, complicating multi-species label expansion and post-market surveillance obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Companion Animal Medicine Market |
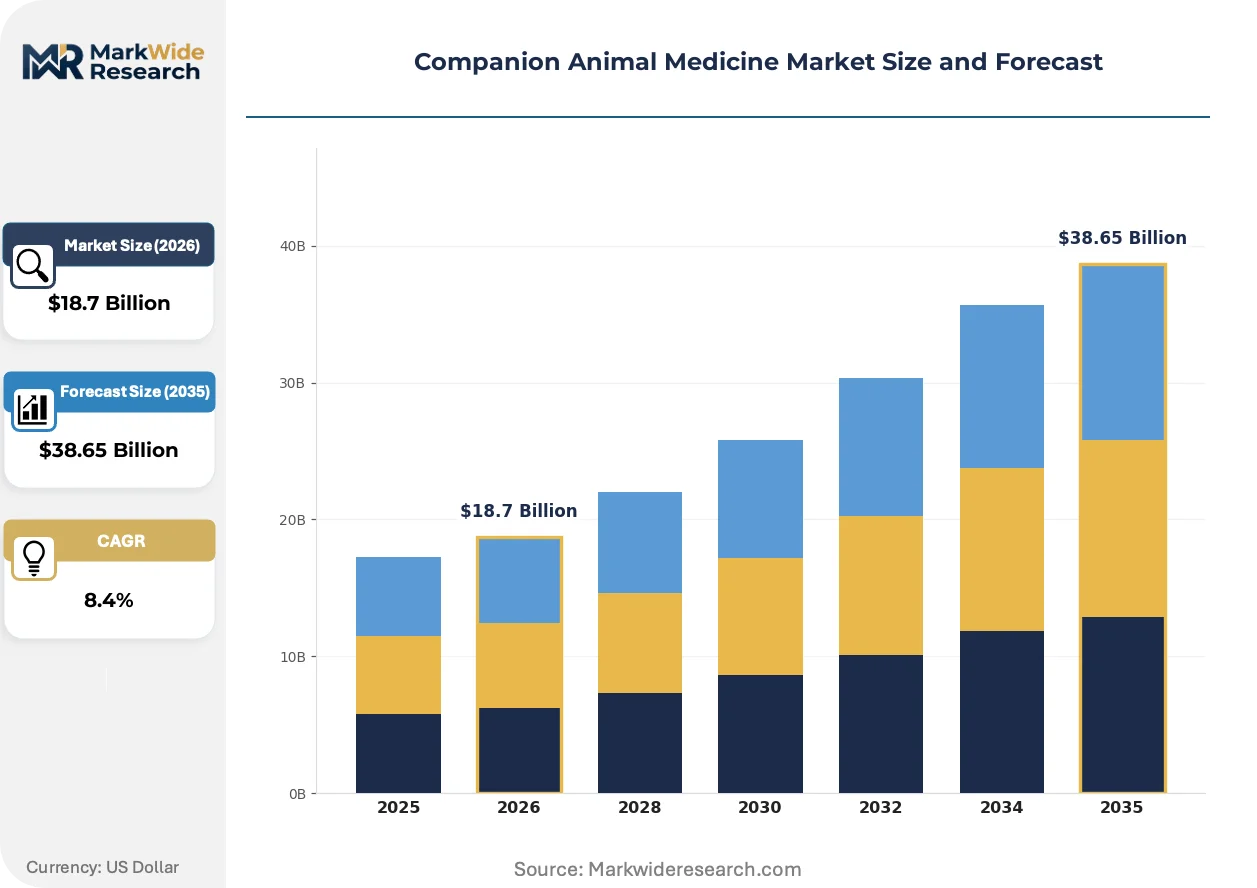
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Parasiticides, Antifungals Treatment Area: Dermatology, Oncology, Dentistry, Cardiology Administration Route: Oral, Injectable, Topical, Transdermal End User: Veterinary Clinics, Animal Hospitals, Pet Pharmacies, Research Laboratories |
| Companies Covered | Elanco Animal Health, Dechra Pharmaceuticals, Zoetis Services LLC, Virbac, IDEXX Laboratories, Inc., Merck Animal Health, Ceva Sante Animale, Vetoquinol, Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Companion Animal Medicine Market Strategic Shifts & Innovations
Platform manufacturing technologies and diagnostic-enabled prescribing are compressing product lifecycles while elevating evidence requirements for market access across major veterinary jurisdictions.
Monoclonal antibody therapeutics targeting IL-31 and NGF pathways deliver targeted cytokine neutralization for canine atopic dermatitis and osteoarthritis pain. Specialty veterinary hospitals in the United States and Western Europe are adopting these agents as first-line alternatives to corticosteroids and NSAIDs. Injectable biologics is overtaking traditional small-molecule maintenance therapy in premium service segments, forcing incumbents to accelerate biosimilar development or cede chronic disease management revenue pools.
REACH chemical registration requirements are extending data obligations to veterinary pharmaceutical metabolites and environmental fate assessments. Formulators must now submit extended ecotoxicology dossiers for parasiticide active ingredients used in household settings. The ectoparasiticide segment faces the steepest compliance burden, with sponsors reformulating topical products to reduce aquatic toxicity profiles and satisfy EU Green Deal contamination reduction targets.
Direct-to-clinic distribution models are displacing traditional wholesale veterinary channels as manufacturers invest in proprietary e-commerce platforms and telemedicine integration. Independent veterinary practices in Germany and France are consolidating purchasing through buying groups that negotiate formulary placement fees and volume rebates. United States corporate veterinary groups leverage centralized procurement to extract price concessions on chronic disease biologics, compressing margins for specialty therapeutics previously protected by fragmented demand.
Companion Animal Medicine Market Segmentation
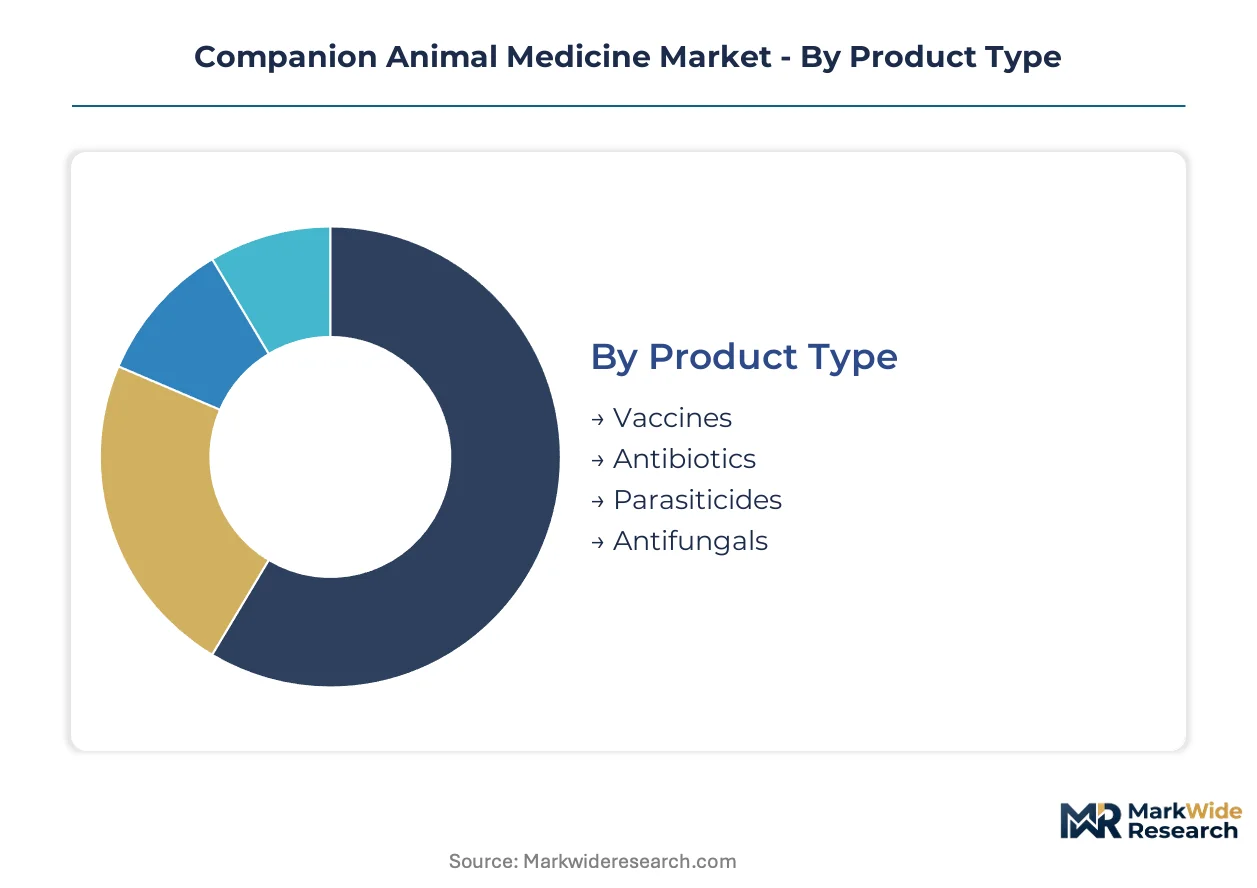
Segmentation in companion animal medicine reveals distinct technology-performance trade-offs across product formats and clinical settings. Each dimension carries unique regulatory pathways, margin structures, and channel access requirements that shape competitive strategy.
Product Type:
Formulation chemistry and biological complexity define manufacturing investment intensity and approval timelines.
- Parasiticides:Small-molecule actives targeting fleas, ticks, and heartworm dominate volume through year-round compliance programs. United States retail pharmacy expansion and OTC channel growth drive demand concentration, though REACH ecotoxicology dossiers for metabolites are extending EU registration costs.
- Vaccines:USDA APHIS-licensed biologics deliver durable immunity against viral pathogens. Thermostable oral platforms are gaining share fastest in corporate veterinary group formulary negotiations, displacing traditional injectable formats in wellness protocols.
- Antibiotics:Narrow-spectrum formulations address bacterial infections with species-specific pharmacokinetic profiling. FDA Center for Veterinary Medicine antimicrobial stewardship guidance is tightening prescription requirements.
- Antifungals:Azole and allylamine classes target dermatophyte infections in immunocompromised patients. Compounding pharmacies supply customized dosing for feline cytochrome P450 deficiencies.
Mature deployment sits with parasiticides. Newer deployment is concentrated in thermostable vaccine platforms.
Treatment Area:
Clinical specialization depth determines reimbursement capture and reference laboratory integration intensity.
- Oncology:Chemotherapy protocols, monoclonal antibodies, and companion diagnostic-enabled therapeutics address lymphoma, mast cell tumors, and osteosarcoma. United States specialty referral networks and pet insurance reimbursement expansion are accelerating treatment access.
- Dermatology:IL-31 and NGF pathway biologics for canine atopic dermatitis displace corticosteroid maintenance. Injectable monoclonal antibodies command premium pricing in hospital settings despite oral convenience competition.
- Cardiology:ACE inhibitors, diuretics, and pimobendan manage degenerative valve disease and dilated cardiomyopathy. Board-certified veterinary cardiologists concentrate prescribing in metropolitan specialty hospitals.
- Dentistry:Antimicrobial rinses, NSAIDs, and local anesthetics support periodontal procedures. General practice clinics drive volume through wellness plan bundling.
Established therapeutic protocols anchor cardiology. Steepest expansion trajectory belongs to oncology with diagnostic-enabled prescribing.
Administration Route:
Delivery mechanism selection shapes patient compliance, cold chain requirements, and channel economics.
- Injectable:Parenteral biologics and depot formulations ensure bioavailability and extended duration. Hospital capture of chronic disease management revenue depends on staff-trained administration protocols.
- Oral:Chewable tablets and flavored suspensions maximize home compliance for maintenance therapy. Retail pharmacy and direct-to-clinic e-commerce platforms are displacing wholesale distribution.
- Topical:Spot-on and pour-on parasiticides require minimal handler training. EU Green Deal aquatic toxicity targets are forcing reformulation of legacy actives.
- Transdermal:Lipid nanoparticle and microneedle patch technologies enable biologic delivery without injection. Narrow-aqueous formulation specialists are targeting home administration expansion.
Injectable formats retain hospital premium pricing. Transdermal innovation is climbing fastest in home care segments.
End User:
Procurement scale and clinical capability differentiation determine formulary access and price realization.
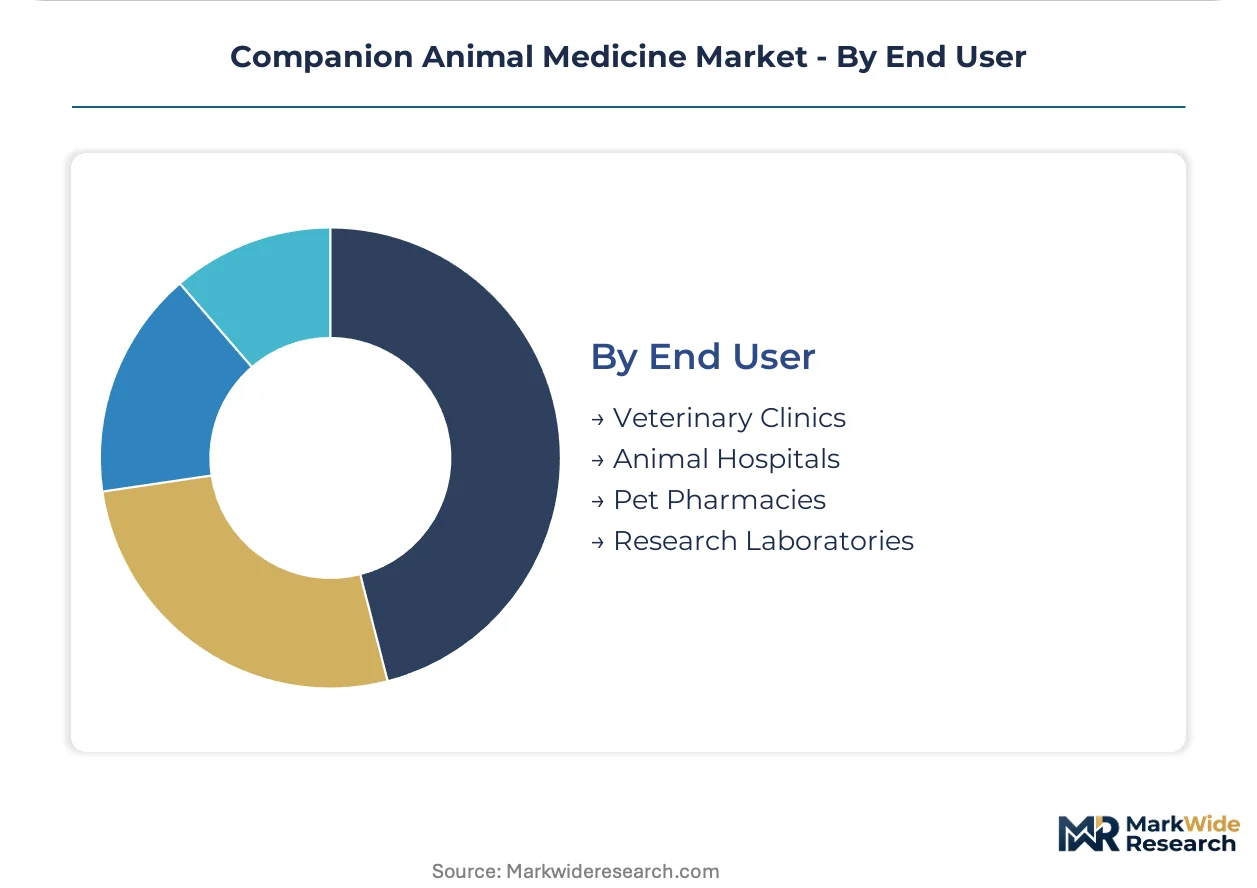
- Veterinary Clinics:Independent and corporate general practice settings manage wellness, parasiticide dispensing, and chronic disease monitoring. German and French buying groups consolidate purchasing power for volume rebates.
- Animal Hospitals:24-hour emergency and specialty referral centers deliver oncology, cardiology, and advanced surgery. Corporate group centralized procurement compresses biologic margins through formulary placement fees.
- Pet Pharmacies:Retail and online dispensaries extend OTC parasiticide access and prescription fulfillment. Telemedicine integration is deepening channel participation.
- Research Laboratories:Contract research organizations and academic institutions supply pharmacokinetic and safety studies for regulatory submissions. USDA APHIS and FDA Center for Veterinary Medicine facility requirements shape site selection.
Volume concentration rests with veterinary clinics. Margin expansion concentrates in animal hospitals with specialty service tiering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for veterinary parasiticides concentrates in Chinese and Indian chemical manufacturing clusters, with formulation and biologics production gravitating toward United States and European Union regulatory jurisdictions.
United States
Pet insurance penetration exceeds 25% in metropolitan markets, expanding specialty oncology and dermatology treatment access. FDA Center for Veterinary Medicine pharmacovigilance requirements for novel biologics are tightening post-market surveillance obligations. Greater Boston and Research Triangle Park anchor monoclonal antibody development pipelines for canine atopic dermatitis therapeutics.
Germany
Veterinary clinic consolidation through buying groups concentrates procurement power in North Rhine-Westphalia and Bavaria. EMA veterinary marketing authorization batch consistency standards elevate manufacturing quality thresholds for imported biologicals. Munich and Stuttgart host specialty referral hospitals scaling companion diagnostic-enabled oncology protocols.
Japan
Aging pet demographics and rising veterinary expenditure per household deepen demand for chronic disease management. METI regulatory harmonization initiatives streamline import pathways for specialty therapeutics previously excluded from domestic formularies. Tokyo and Osaka metropolitan areas concentrate corporate veterinary group expansion and reference laboratory networks.
India
Domestic companion animal ownership growth in Tier-1 cities drives demand for imported vaccines and parasiticides. PLI scheme incentives attract contract development organizations seeking cost-competitive bulk antigen production for export markets. Hyderabad and Bengaluru clusters specialize in veterinary biologics manufacturing under USDA APHIS-equivalent facility standards.
United Kingdom
Corporate veterinary group acquisition activity consolidates independent practices into centralized procurement networks. VMD enforcement of EU-legacy pharmacovigilance requirements maintains stringent post-authorization monitoring for novel therapeutics. London and Southeast England concentrate specialty referral capacity and pet insurance policy distribution.
Companion Animal Medicine Market Key Industry Players
Captive biologics manufacturing dominates the current landscape as sponsors internalize monoclonal antibody production to secure supply continuity. The market structures around three tiers: integrated pharmaceutical conglomerates with human-animal health synergies, pure-play veterinary specialists with narrow therapeutic focus, and emerging biotech platforms leveraging human drug repurposing. Consolidation through corporate veterinary group formulary placement agreements and strategic technology licensing for thermostable vaccine platforms represent the dominant competitive moves.
Among integrated health science conglomerates, Zoetis Services LLC and Boehringer Ingelheim International GmbH exemplify archetypes combining human pharmaceutical capabilities with veterinary-specific development. Dechra Pharmaceuticals occupies a specialist position within the pure-play tier, representing narrow-aqueous formulation expertise. These three entities anchor competitive dynamics through differentiated manufacturing strategies and regulatory navigation capabilities across FDA, EMA, and USDA APHIS jurisdictions.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Dechra Pharmaceuticals |
| Zoetis Services LLC |
| Virbac |
| IDEXX Laboratories, Inc. |
| Merck Animal Health |
| Ceva Sante Animale |
| Vetoquinol |
| Boehringer Ingelheim International GmbH |
| Others |
Cost & Logistics Intelligence
Corporate veterinary group procurement concentration in the United States and Western Europe anchors contract-based formulary placement agreements as the dominant pricing model, with centralized purchasing extracting volume rebates that compress margins for specialty biologics manufacturers.
Pricing Analysis
Warranty and cold-chain integrity guarantees remain unbundled from base product pricing, creating service-tier differentiation between hospital-direct and retail pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by administration complexity and diagnostic bundling, with injectable monoclonal antibodies commanding the highest tier. Pricing pressure stems from corporate group formulary negotiations consolidating demand across multi-site networks. Independent veterinary clinics exhibit the greatest price sensitivity due to capital budget constraints, while specialty animal hospitals absorb premium pricing for diagnostic-enabled protocols.
Supply Chain Analysis
Temperature-controlled freight costs for thermolabile biologics constitute a disproportionate share of landed product expense, particularly for monoclonal antibodies requiring validated cold chain infrastructure. Active pharmaceutical ingredient synthesis concentrates in China and India, while formulation and biologics production centers on United States and EU regulatory jurisdictions. Bulk chemical sourcing for parasiticides draws from Chinese contract manufacturers, with formulation inputs resting on Indian excipient suppliers. Single-source vulnerability in monoclonal antibody captive manufacturing exposes sponsors to facility licensing delays. Distribution runs through direct-to-clinic e-commerce platforms displacing traditional wholesale veterinary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA Center for Veterinary Medicine pharmacovigilance requirements for novel biologics erect substantial barrier-to-entry moats favoring sponsors with established regulatory affairs infrastructure and post-market surveillance capabilities.
For Market Incumbents: Anticipate biosimilar erosion in the monoclonal antibody dermatology segment by accelerating patent estate defense and expanding indication labels through companion diagnostic integration. Captive biologics manufacturing capacity additions in United States and EU jurisdictions will secure supply continuity against tightening USDA APHIS facility licensing timelines. Prioritize formulary placement fee structures that lock in corporate veterinary group purchasing commitments before channel consolidation accelerates. For New Entrants and Emerging Players: Transdermal narrow-aqueous formulation platforms offer a technology-first wedge into home administration segments underserved by injectable incumbents. The Japanese companion animal channel presents the most penetrable geography given METI regulatory harmonization streamlining import pathways. Pursue reference laboratory partnership models that bundle diagnostic testing with therapeutic prescribing to bypass established hospital channel gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play veterinary specialists with narrow therapeutic focus in North American and Western European markets where pet insurance reimbursement expansion sustains chronic disease management revenue pools. Long-term viability hinges on platform technology licensing positions enabling rapid label expansion across species. Monitor FDA draft guidance finalization on monoclonal antibody streamlined approval pathways as the critical inflection signal for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Biologics Manufacturing Scale-Up | Zoetis Services LLC and Boehringer Ingelheim International GmbH internalize monoclonal antibody production to secure supply continuity against FDA pharmacovigilance tightening. |
| Companion Diagnostic Integration | IDEXX Laboratories, Inc. and reference laboratory networks enable diagnostic-enabled prescribing that locks in oncology and dermatology therapeutic selection. |
| Transdermal Formulation Development | Dechra Pharmaceuticals leverages narrow-aqueous expertise to expand home administration of previously injectable biologics through lipid nanoparticle delivery systems. |
| Direct-to-Clinic Distribution Platform | Proprietary e-commerce and telemedicine integration displaces wholesale veterinary channels, deepening manufacturer control over formulary placement negotiations. |
| Regulatory Harmonization Lobbying | METI initiatives in Japan and EMA batch consistency standards create preferential market access for sponsors with established multi-jurisdiction compliance infrastructure. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with veterinary formulary directors, specialty hospital procurement managers, regulatory affairs leads at animal health sponsors, and reference laboratory commercial officers. FDA Center for Veterinary Medicine submission databases, EMA veterinary marketing authorization registers, USDA APHIS facility licensing records, and companion animal insurance reimbursement datasets provided validation benchmarks. Bottom-up product-level modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation granularity extended to product type, treatment area, administration route, and end-user channel, with regional regulatory clusters modeled as distinct adoption environments. CAGRs derived from logistic growth curve fitting applied to historical prescription volumes and reimbursement expansion trajectories. Species-specific metabolism constraints, cold chain infrastructure capex requirements, and corporate veterinary group consolidation patterns informed forecast sensitivity ranges throughout the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement shifts, abrupt pet insurance reimbursement contraction, and novel zoonotic disease emergence disrupting veterinary service delivery. Forecasts reflect assumptions about continued specialty referral network expansion and biologic platform technology maturation. Stakeholders should weight assumptions against their own operating context and monitor FDA pharmacovigilance guidance evolution as a material revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Animal Healthcare Market
Animal Health
Animal Health Market
Animal Health
Swine Health Market
Animal Health
Equine Healthcare Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Laboratory Animal Models Market
Animal Health
Global Poultry Healthcare Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Canada Animal Health Care Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
US Companion Animal Health Market
Animal Health
Cattle Healthcare Market
Animal Health
US Military Animals Market
Animal Health
Companion Animal Healthcare Market