
 Global Facility Management Software Market | 2026-2036
Global Facility Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Facility Management Software Market Intelligence
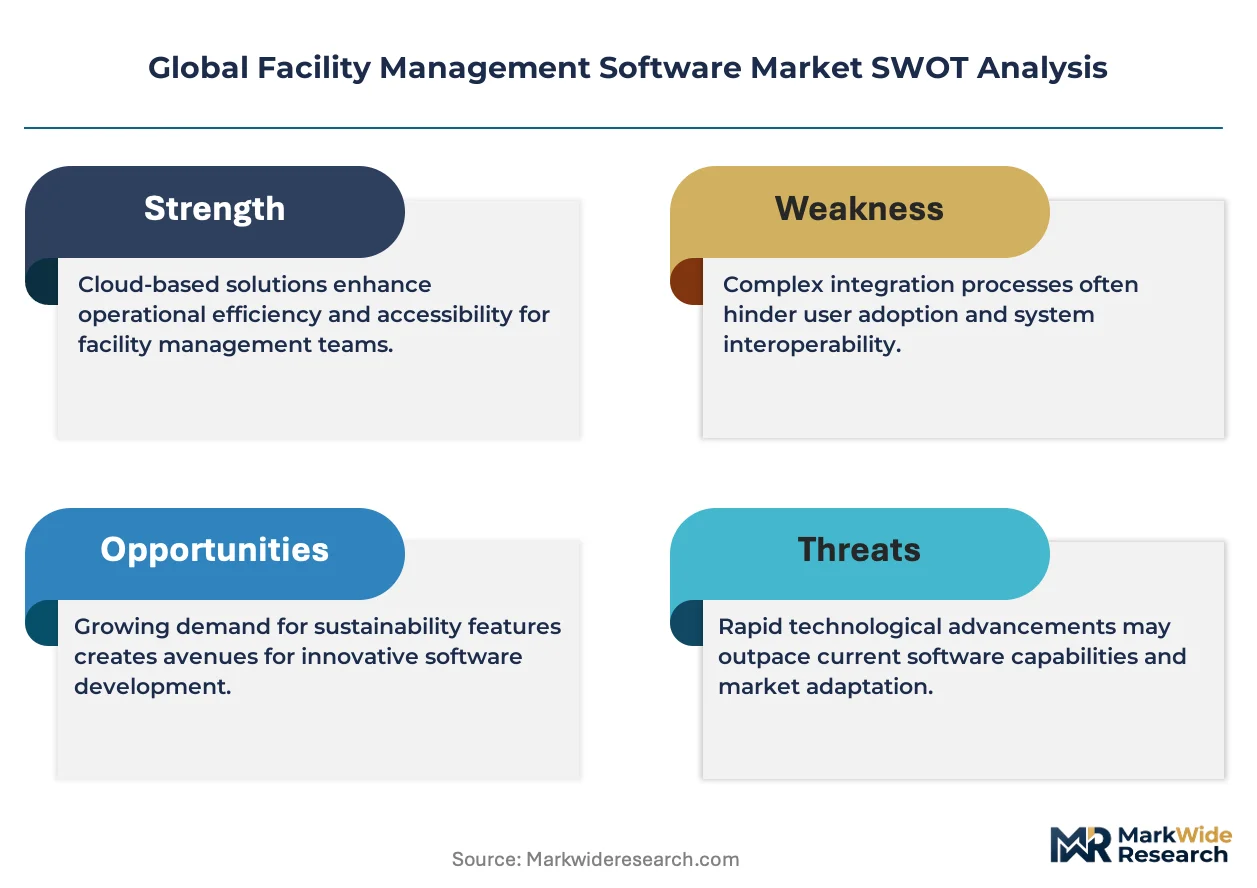
The European Union's Corporate Sustainability Reporting Directive (CSRD) is realigning procurement priorities for facility management software toward platforms with robust energy and sustainability tracking capabilities. ServiceNow leverages its workflow automation expertise to integrate sustainability metrics into broader enterprise service management. Meanwhile, Johnson Controls International anchors its software offerings with its deep building systems and hardware integration knowledge. SAP SE competes by embedding facility management functions within its extensive ERP ecosystem for large enterprises.
Facility management software is a suite of digital tools for overseeing physical assets, spaces, and infrastructure within a built environment. These platforms integrate CAFM and IWMS functionalities to optimize maintenance scheduling, space utilization, and operational costs. Cloud-based deployment models dominate the market over on-premises solutions, offering greater scalability and accessibility for property managers. While maintenance management remains a core solution type, energy management modules represent the fastest-growing segment to meet sustainability goals.
In the United States, compliance with standards from the Occupational Safety and Health Administration (OSHA) drives demand for safety and maintenance modules. Concurrently, adherence to the EU's General Data Protection Regulation (GDPR) and China's GB standards for building efficiency shapes data handling and system design requirements. Vendor selection increasingly hinges on a platform's ability to provide auditable data trails for both regulatory compliance and corporate sustainability reporting.
Market Dynamics
The convergence of enterprise-level sustainability mandates with granular operational efficiency requirements is the central force shaping the facility management software market. This dynamic compels vendors to integrate energy and compliance reporting directly into core maintenance and space management workflows, moving beyond siloed functionalities.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) is forcing companies to procure software with auditable energy and emissions tracking, making sustainability modules a non-negotiable procurement criterion.
- Healthcare Sector Complexity:Healthcare facilities are accelerating adoption to manage intricate compliance demands for life safety and environmental controls, alongside optimizing the maintenance of specialized medical equipment and infrastructure.
- National Decarbonization Goals:China's dual carbon goals, combined with a surge in new commercial building projects, create significant demand for integrated platforms that can manage energy consumption and report on efficiency metrics at a portfolio scale.
Market Restraints
- High Implementation Costs:The significant upfront investment and total cost of ownership for comprehensive Integrated Workplace Management Systems (IWMS) create a substantial barrier for small and medium-sized enterprises (SMEs).
- Legacy System Integration:Difficulty in integrating modern cloud-based software with older, proprietary on-premises building automation systems (BAS) can lead to data silos, implementation delays, and diminished ROI.
- Perceived Complexity:Many smaller organizations opt for disparate, simpler point solutions for tasks like work orders or space booking, viewing them as sufficient and avoiding the perceived complexity and training overhead of a unified platform.
Strategic Opportunities
- Predictive Maintenance with AI:Integrating artificial intelligence and machine learning algorithms to analyze sensor data from IoT devices offers a significant opportunity to move from scheduled to predictive, condition-based maintenance, reducing downtime and costs.
- Specialized Vertical Modules:Developing pre-configured software modules for high-compliance industries like life sciences R&D labs or multi-tenant data centers presents a path for differentiation and higher-margin sales.
- Emerging Market Penetration:Rapid urbanization and commercial construction in regions like Southeast Asia and Latin America create new, underpenetrated markets for facility management software, especially for scalable cloud-based solutions.
Industry Challenges
- Data Security and Privacy:Ensuring that the vast amounts of operational, spatial, and occupant data collected by software platforms comply with evolving regulations like GDPR and various national data sovereignty laws is a constant challenge.
- Skilled Personnel Shortage:A persistent talent gap exists for facility managers who possess the dual expertise in traditional building engineering and modern data analytics required to maximize the value of these software platforms.
- Interoperability Standards:The lack of universal data standards across different building equipment manufacturers (HVAC, lighting, security) complicates the process of creating a single, unified data layer for analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Facility Management Software Market |
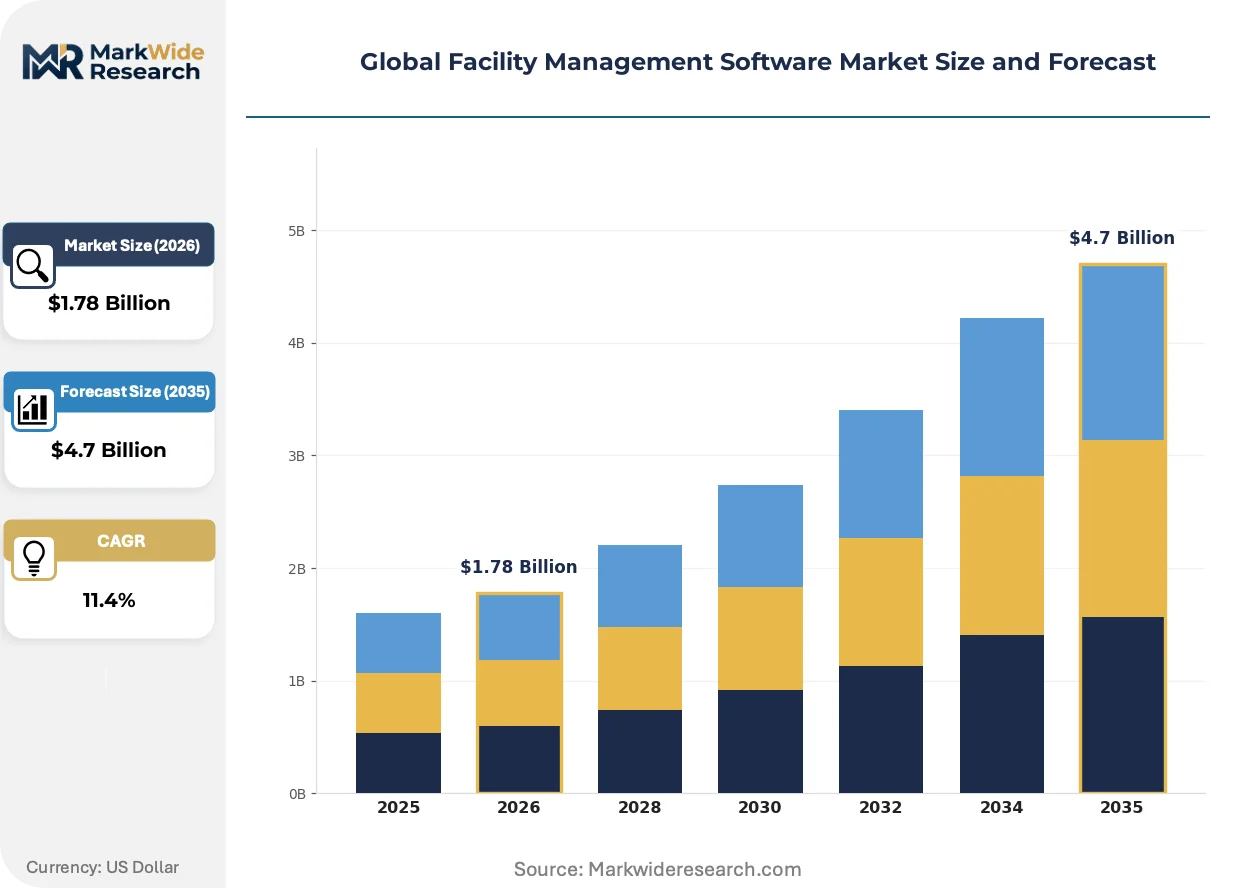
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-Premises, Hybrid, SaaS, Web-Based Solution Type: Asset Management, Space Management, Maintenance Management, Energy Management, Security Management Application: Commercial Buildings, Educational Institutions, Healthcare Facilities, Industrial Complexes, Government Offices End User: Property Managers, Facility Operators, Corporate Offices, Real Estate Developers, Public Sector Entities |
| Companies Covered | ServiceNow, Johnson Controls International, IBM Corporation, MRI Software, Nemetschek Group, Oracle Corporation, Planon Group, Trimble Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Facility Management Software Market Strategic Shifts & Innovations
The evolution of facility management software reflects a pivot from being a system of record for physical assets to becoming a strategic engine for sustainability performance and enhanced occupant experience. This shift is driven by technological convergence, stringent new regulations, and changing expectations for the workplace.
Digital Twin technology creates dynamic, virtual replicas of physical assets, spaces, and entire buildings, which allows for real-time monitoring and advanced simulation. Owners of large, complex portfolios like airports and industrial manufacturing sites are pioneering its adoption for operational scenario planning and risk assessment. This technology is converging with AI-powered analytics to enable predictive, rather than merely reactive, facility management strategies and long-term capital planning.
China's strict enforcement of its national GB standards for building energy efficiency is compelling property owners to implement more sophisticated energy monitoring and reporting tools. The policy directly impacts both new construction and major retrofits, requiring verifiable data on energy performance and carbon emissions. Consequently, energy management modules represent the fastest-growing software segment specified by developers and building operators within the Chinese market.
Buyers are increasingly prioritizing the overall occupant experience, moving evaluation criteria beyond pure operational cost savings. This behavioral shift favors platforms that offer intuitive, mobile-first interfaces for common tasks like booking a desk, reporting a maintenance issue, or accessing building services. This trend is most visible within the competitive corporate real estate sectors of North America and Western Europe, where workplace quality is used as a tool for talent attraction and retention.
Global Facility Management Software Market Segmentation
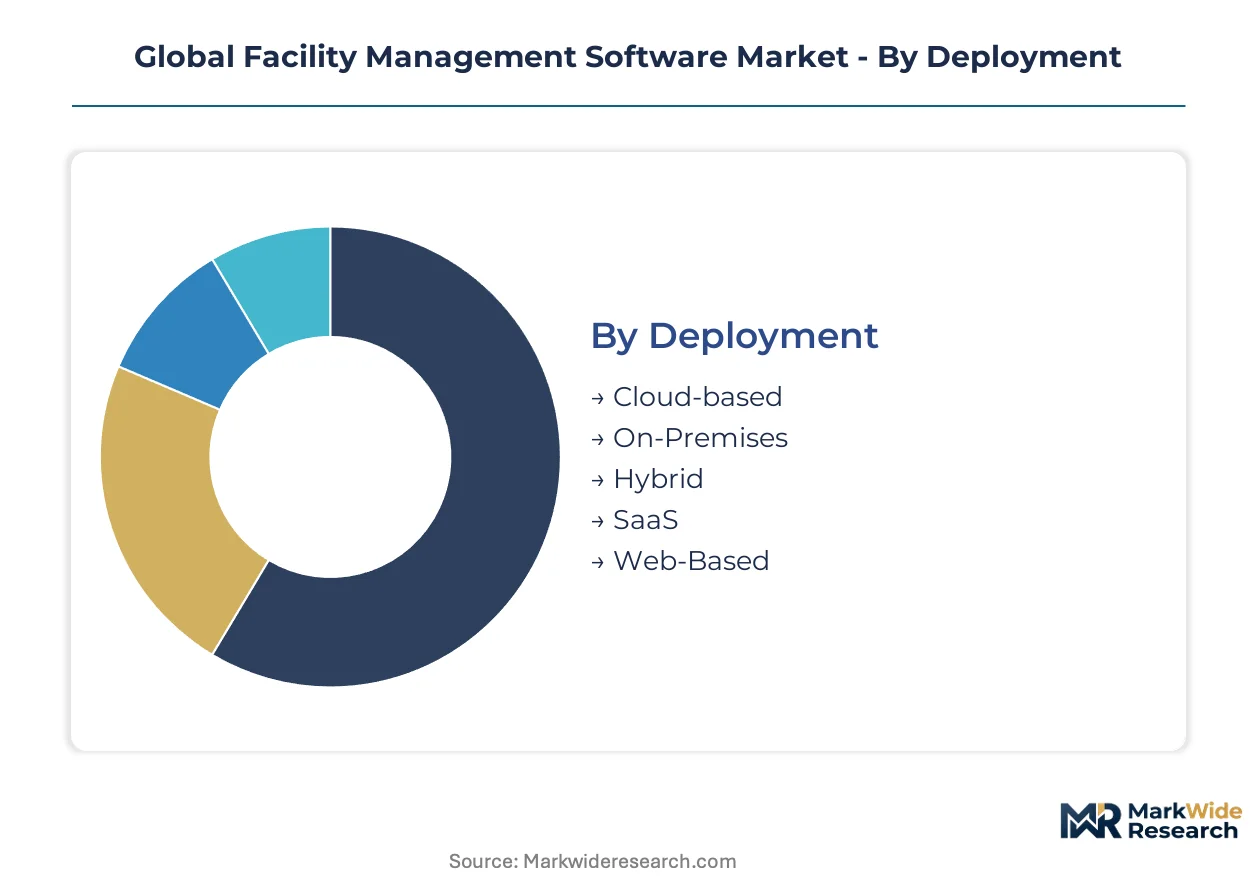
The facility management software market segments reflect the diverse operational needs and technological preferences of organizations overseeing built environments. Understanding these distinct categories provides clarity on procurement patterns and vendor specialization across different industries and deployment models.
Deployment:
The technological underpinnings of facility management software deployments dictate accessibility and scalability for end-users.
- Cloud-based:This model hosts software on vendor-managed servers, providing internet-based access without local infrastructure requirements. Demand is high among property managers seeking scalability and accessibility for geographically dispersed portfolios.
- SaaS:Software as a Service operates on a subscription model where the vendor manages all infrastructure, updates, and maintenance. This deployment option attracts small and medium-sized enterprises and corporate offices due to lower upfront costs and automatic feature enhancements.
- On-Premises:Organizations install and manage this software directly on their own servers and infrastructure. This model suits entities with stringent data security policies or limited internet connectivity.
- Hybrid:A combination of on-premises and cloud components, offering a balance between data control and flexible remote access. This approach allows for selective data storage locally while leveraging cloud benefits.
- Web-Based:These solutions are accessed through a web browser, typically offering a streamlined set of functionalities compared to full cloud or SaaS platforms. They provide basic operational capabilities without extensive setup.
Cloud-based solutions lead on scale; SaaS models gain share with their subscription flexibility.
Solution Type:
Specific operational requirements within facilities drive the development and adoption of distinct software solution types.
- Maintenance Management:This module streamlines work order generation, preventive maintenance scheduling, and asset repair tracking. Compliance with Occupational Safety and Health Administration (OSHA) standards in the United States drives its adoption, alongside operational efficiency needs for industrial complexes.
- Energy Management:These tools monitor, analyze, and optimize energy consumption across buildings and portfolios, facilitating carbon reporting. The EU's Corporate Sustainability Reporting Directive (CSRD) and China's GB standards for building efficiency compel organizations to implement these modules.
- Asset Management:This solution tracks the lifecycle, performance, and depreciation of physical assets within a facility. It supports strategic planning for equipment replacement and capital expenditures.
- Space Management:This module optimizes the utilization of floor plans, meeting rooms, and workstations, often incorporating desk booking and occupancy sensors. Corporate offices in North America leverage these tools to enhance employee experience.
- Security Management:This software integrates access control systems, video surveillance, and incident reporting functionalities. It provides a centralized platform for managing physical security protocols.
The market's trajectory increasingly favors integrated platforms that combine multiple functionalities.
Application:
Diverse facility types present unique challenges, necessitating specialized software applications tailored to their operational contexts.
- Healthcare Facilities:This application manages complex environments, including specialized medical equipment, life safety systems, and environmental controls. Intricate compliance demands for patient care and infrastructure optimization drive adoption in the United States and Europe.
- Commercial Buildings:This segment encompasses office spaces, retail centers, and mixed-use developments, focusing on space utilization, energy efficiency, and tenant services. New commercial building construction in China and talent attraction initiatives in North America contribute to its demand.
- Educational Institutions:These applications manage campus infrastructure, classrooms, student housing, and administrative buildings. They support operational efficiency across large and varied property portfolios.
- Industrial Complexes:This segment includes manufacturing plants, warehouses, and logistics centers, where software optimizes machinery maintenance and safety protocols. It ensures continuous operation and regulatory adherence.
- Government Offices:Public sector entities utilize these solutions for managing municipal buildings, public infrastructure, and administrative facilities. Transparency and compliance with national regulations are paramount.
Healthcare facilities and commercial buildings represent the fastest-growing segments, driven by regulatory and efficiency pressures.
End User:
The primary beneficiaries of facility management software span a range of organizational roles, each with distinct operational imperatives.
- Property Managers:These users oversee multiple properties, handling tenant relations, lease management, and overall building operations. They require scalable solutions for portfolio-wide visibility and efficiency.
- Facility Operators:These professionals manage the day-to-day maintenance, repairs, and operational tasks within a single facility or a small cluster. They benefit from mobile-first interfaces and real-time data for immediate action.
- Corporate Offices:Large corporations use facility management software to optimize their workplace environments, focusing on employee experience, space utilization, and sustainability reporting. This supports talent retention strategies.
- Real Estate Developers:These entities integrate facility management software during the design and construction phases of new buildings. The aim is to optimize long-term operational costs and building performance.
- Public Sector Entities:Government bodies and agencies use these platforms for managing public assets, infrastructure, and administrative buildings. Emphasis is placed on accountability and regulatory compliance.
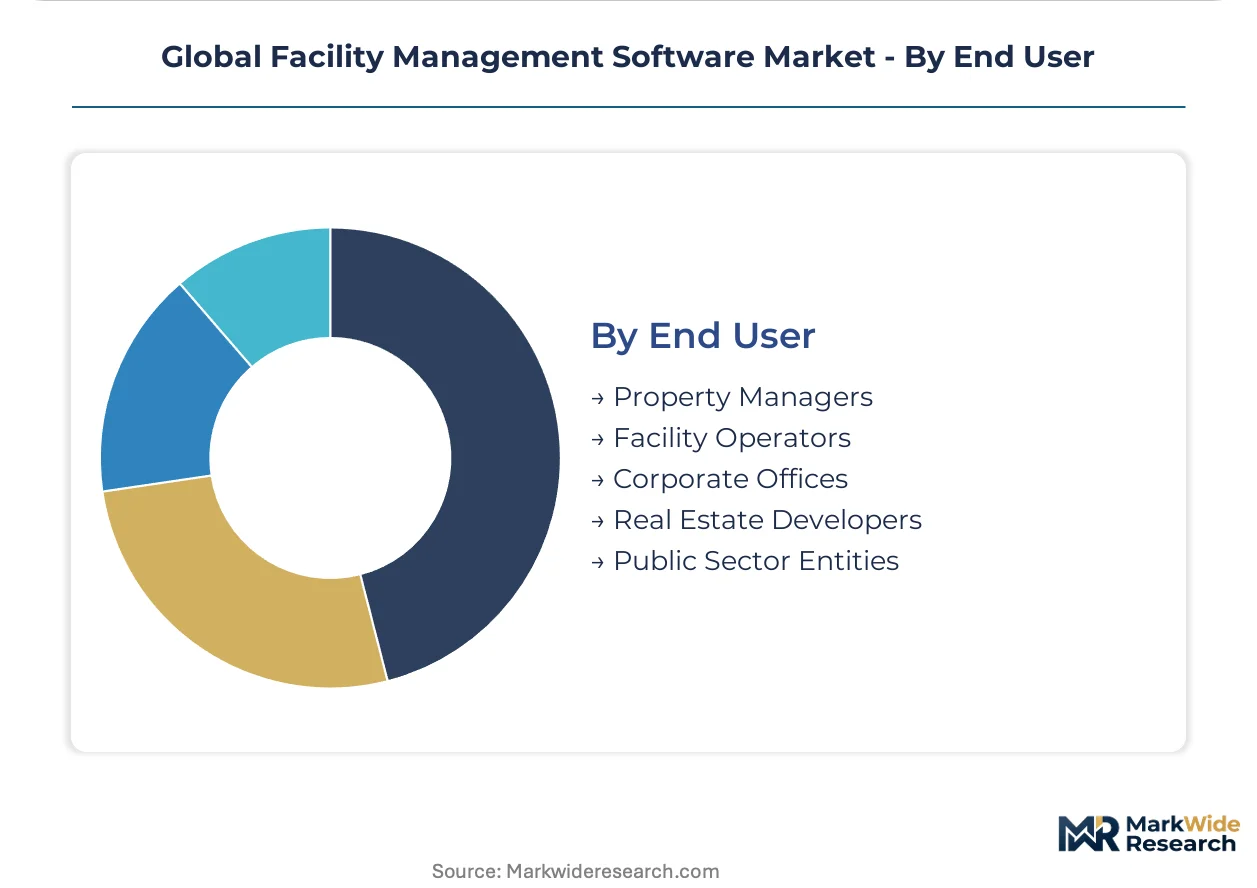
Property managers and facility operators form the core user base, with corporate offices expanding their influence on software design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The facility management software industry initially scaled in developed economies, particularly across North America and Western Europe, driven by complex commercial real estate portfolios. This foundational adoption established early market leaders and shaped initial software functionalities. Today, diverse regulatory and economic factors continue to influence regional market dynamics and procurement patterns.
United States
Demand for facility management software in the United States stems from the intricate operational needs of healthcare facilities and large corporate offices. Compliance with Occupational Safety and Health Administration (OSHA) standards drives the adoption of safety and maintenance modules. Major commercial centers like New York City leverage these platforms to optimize space utilization and enhance occupant experience.
Germany
German organizations are increasingly adopting facility management software to meet stringent sustainability mandates and manage advanced industrial complexes. The EU's Corporate Sustainability Reporting Directive (CSRD) compels companies to procure solutions with robust energy and emissions tracking capabilities. Cities such as Frankfurt, with its prominent financial district, prioritize integrated platforms for efficient building operations.
China
China's rapid urbanization and ambitious national dual carbon goals fuel significant demand for facility management software, especially in new commercial building construction. Adherence to China's GB standards for building energy efficiency requires sophisticated energy monitoring and reporting tools. The Yangtze River Delta region, a hub for manufacturing and commerce, showcases strong adoption for portfolio-wide management.
United Kingdom
Corporate real estate firms and public sector entities in the United Kingdom seek facility management software to improve operational efficiency and ensure data privacy. Compliance with the General Data Protection Regulation (GDPR) shapes data handling requirements for software platforms. London's financial and technology hubs integrate these solutions to manage complex office environments and support talent retention strategies.
India
India's burgeoning commercial property development and rapid urbanization are generating substantial demand for scalable facility management software. National building codes and a focus on operational efficiency drive the adoption of maintenance and asset management modules. Major metropolitan areas like Bengaluru, with its expanding IT and commercial sectors, increasingly utilize these platforms for large-scale facility oversight.
Global Facility Management Software Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the facility management software market, creating a tiered competitive environment. The market structure features established enterprise software giants alongside specialized cloud-native providers. Strategic archetypes include integrated solution providers, niche vertical specialists, and hardware-agnostic platform developers. Companies pursue strategic partnerships and technology licensing agreements to expand their offerings and market reach.
Specialists in integrated solutions include ServiceNow, which leverages its workflow automation expertise across enterprise service management. Johnson Controls International anchors its software offerings with deep building systems and hardware integration knowledge for comprehensive facility control. SAP SE represents the enterprise resource planning (ERP) ecosystem, embedding facility management functions within its broader suite for large corporate clients.
| Leading Market Players |
|---|
| ServiceNow |
| Johnson Controls International |
| IBM Corporation |
| MRI Software |
| Nemetschek Group |
| Oracle Corporation |
| Planon Group |
| Trimble Inc. |
| SAP SE |
| Others |
Cost & Logistics Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) gates qualified software supply and premium-tier pricing access for facility management solutions. This mandate compels vendors to invest in sophisticated energy and emissions tracking capabilities, impacting overall solution costs.
Pricing Analysis
Subscription-based SaaS models dominate facility management software pricing, offering tiered access based on features and user count. Price differentiation stems from customization levels, integration complexity with existing systems, and the depth of bundled modules like energy management or predictive maintenance. Pricing pressure stems from small and medium-sized enterprises (SMEs) seeking cost-effective, simpler solutions. Large enterprises, however, exhibit lower price sensitivity for comprehensive, integrated platforms that ensure regulatory compliance and operational efficiency.
Supply Chain Analysis
Software development talent and cloud infrastructure services form the core input dependencies for facility management software. Geographic supply concentration for these critical inputs centers on established tech hubs in the United States, India, and parts of the European Union. A significant supply chain risk involves the global shortage of skilled software developers, impacting innovation cycles and development costs. Distribution runs through a combination of direct sales channels, strategic channel partners, and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with mandates like the EU's Corporate Sustainability Reporting Directive (CSRD) consistently driving demand for advanced software capabilities.
For Market Incumbents: Acquire niche vertical specialists to expand domain expertise in high-compliance industries such as life sciences or data centers. This move counters the threat from specialized point solutions offering deep functionality within specific operational contexts. Incumbents should also invest in R&D for advanced AI-driven predictive analytics to maintain a technology lead against emerging competitors. Deeper hardware integration with building automation systems represents another key lever.
For New Entrants and Emerging Players: Enter via specialized modules addressing acute pain points for specific industry verticals. Target underpenetrated emerging markets in Southeast Asia with scalable, cloud-native SaaS offerings. A go-to-market angle focusing on rapid deployment and demonstrable ROI for energy efficiency or space optimization can attract initial customers. Focus on solutions with low upfront costs for small and medium-sized enterprises.
For Investors and Strategic Acquirers: Roll-up economics work for technology-focused private equity firms because the market exhibits fragmentation among specialized point solution providers. Long-term viability is strong due to persistent demand for operational efficiency and sustainability reporting across built environments. Acquisition targets should include AI/IoT platform specialists or regional SaaS providers with strong customer bases. A signal to watch is the increasing consolidation of disparate functionalities into unified platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI/ML for Predictive Maintenance | Enhances operational efficiency and reduces downtime for facility operators. |
| Develop Specialized Vertical Modules | Captures higher-margin sales in high-compliance sectors like healthcare facilities. |
| Expand Cloud-Native SaaS Offerings | Increases accessibility and scalability for property managers in diverse markets. |
| Form Strategic Partnerships with Hardware Providers | Strengthens comprehensive building system integration for large enterprises. |
| Target Emerging Markets with Scalable Solutions | Unlocks new revenue streams from rapid commercial construction in regions like India. |
Research Approach
Bottom-up application and end-user modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with facility managers, property developers, IT directors, and sustainability officers provided qualitative insights and validated market dynamics. Secondary data sources included company financial reports, regulatory body publications from OSHA and CSRD, and industry association reports.
An input-output matrix framework guided the forecasting process over the projection horizon, segmenting the market by deployment model, solution type, application, end-user, and regional regulatory compliance. Compound annual growth rates (CAGRs) were derived from historical trend analysis and future growth drivers such as new commercial building construction. Key forecast inputs included global commercial construction starts and upcoming regulatory compliance deadlines.
Inputs from public financial statements and regulatory filings were available through the study window; gaps in comprehensive global private company data introduce uncertainty bands. Forecasts reflect assumptions on technology adoption rates and the enforcement of environmental regulations. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Slovenia Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
India Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Soft Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Moldova Facility Management Market