
 Germany Facility Management Market | 2026-2036
Germany Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Facility Management Market Analysis
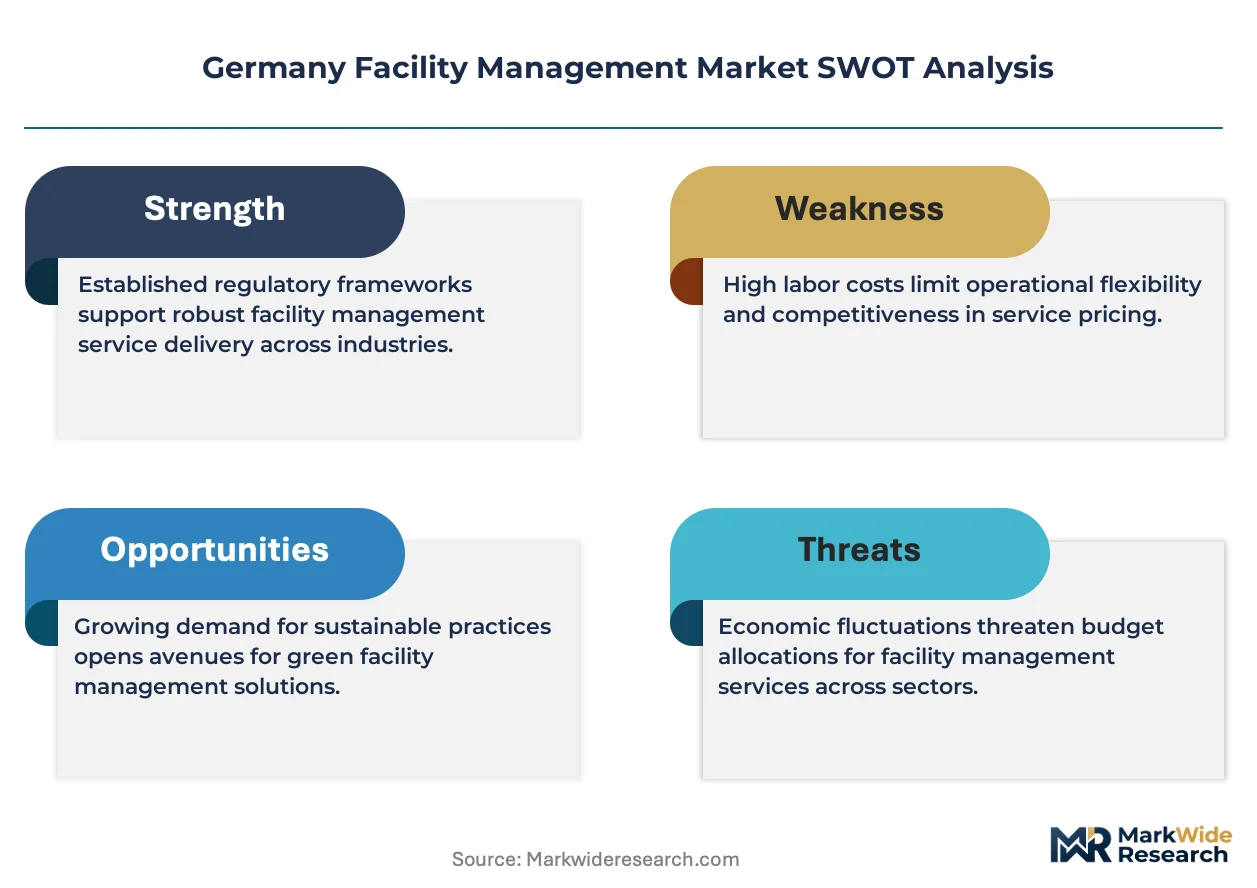
Skilled FM technician availability is rotating toward deficit in eastern Bundesländer, tightening service delivery timelines across industrial contracts. ISS Facility Services GmbH leverages its nationwide technician network to sustain coverage in thin labor markets. Sodexo Deutschland GmbH anchors healthcare facility portfolios through specialized clinical support services. Apleona GmbH differentiates via integrated technical and commercial property management under single accountability structures.
Germany Facility Management encompasses the coordinated delivery of hard services (mechanical, electrical, HVAC maintenance) and soft services (cleaning, security, catering) to maintain built environment operability, governed by VDI 2067 lifecycle cost standards and DIN EN 15221 facility management frameworks. The primary purpose is optimizing total cost of ownership while ensuring regulatory compliance and user productivity across commercial, industrial, and public estates. Hard maintenance and energy management segments command the deepest margin pools due to technical certification barriers and long-term contract tenors. Soft services including cleaning and security operate at higher competitive intensity with price pressure from fragmented regional competitors. Building Management Systems integration represents the fastest structural expansion as clients mandate real-time energy telemetry and predictive maintenance protocols.
KBA emission thresholds for commercial vehicle fleets and federal Energieeinsparverordnung standards are reshaping FM procurement specifications toward carbon-accountable service contracts. DIN standards for facility management processes and regional Bauordnung requirements create compliance layers that favor certified multi-service providers over single-trade vendors. Stakeholders must monitor how upcoming EU CSRD disclosure obligations will cascade into mandatory sustainability reporting clauses within FM tender documents.
Market Dynamics
German healthcare estates are expanding outsourced facility operations under tighter energy performance mandates, compressing procurement cycles toward integrated multi-service contracts. KBA emission thresholds and federal Energieeinsparverordnung standards are accelerating digital building management adoption across automotive manufacturing clusters.
Growth Catalysts
- Energieeinsparverordnung mandates:Federal energy conservation ordinances force commercial estates to retrofit HVAC and lighting systems, creating sustained demand for certified technical FM services.
- Automotive corridor concentration:Baden-Württemberg's manufacturing density generates concentrated demand for precision environmental controls and predictive maintenance protocols.
- VDI 2067 lifecycle frameworks:Standardized total cost of ownership methodologies enable long-term contracting structures that favor integrated service providers over fragmented vendors.
Market Restraints
- Skilled technician deficit:Eastern Bundesländer face rotating labor shortages for certified electrical and mechanical technicians, tightening service delivery timelines across industrial contracts.
- Certification cost barriers:DIN EN 15221 compliance and specialized technical credentials impose capital requirements that exclude smaller regional competitors from premium contract tiers.
- Energy price volatility:Natural gas and electricity input cost fluctuations compress margins on fixed-price energy management contracts.
Strategic Opportunities
- CSRD disclosure cascade:Upcoming EU Corporate Sustainability Reporting Directive obligations will embed mandatory carbon-accountable clauses into FM tender documents, favoring providers with verified telemetry infrastructure.
- Building Management System convergence:Integration of IoT sensors with AI-driven predictive analytics creates white space for real-time energy optimization services in healthcare estates.
- Thuringia-Saxony expansion:Underpenetrated eastern industrial zones present acquisition opportunities for technicians with dual electrical-HVAC certifications.
Industry Challenges
- Legacy system integration friction:Brownfield manufacturing facilities operate heterogeneous equipment generations that resist standardized Building Management System overlays.
- Multi-trade coordination complexity:Single-accountability contracts require seamless orchestration of hard and soft services, straining workforce management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Facility Management Market |
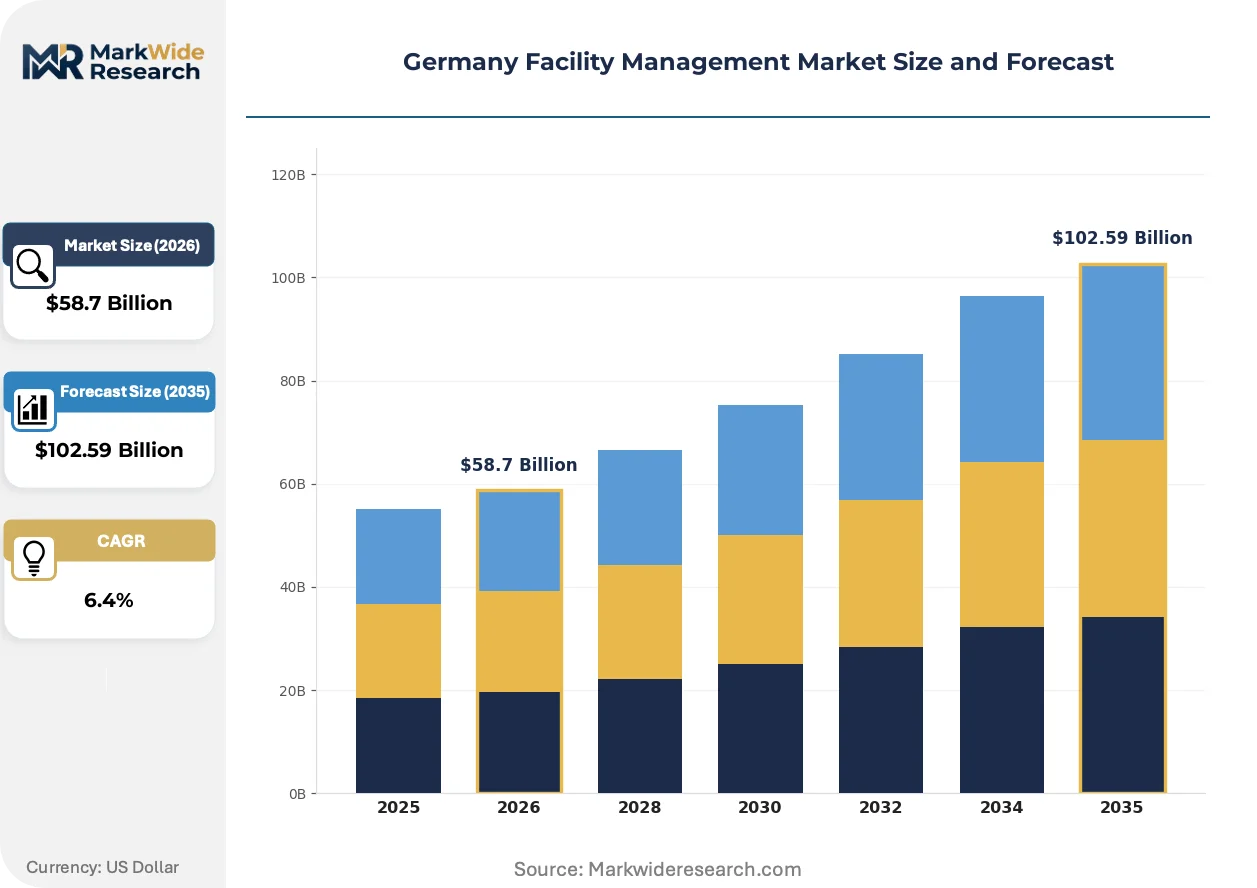
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
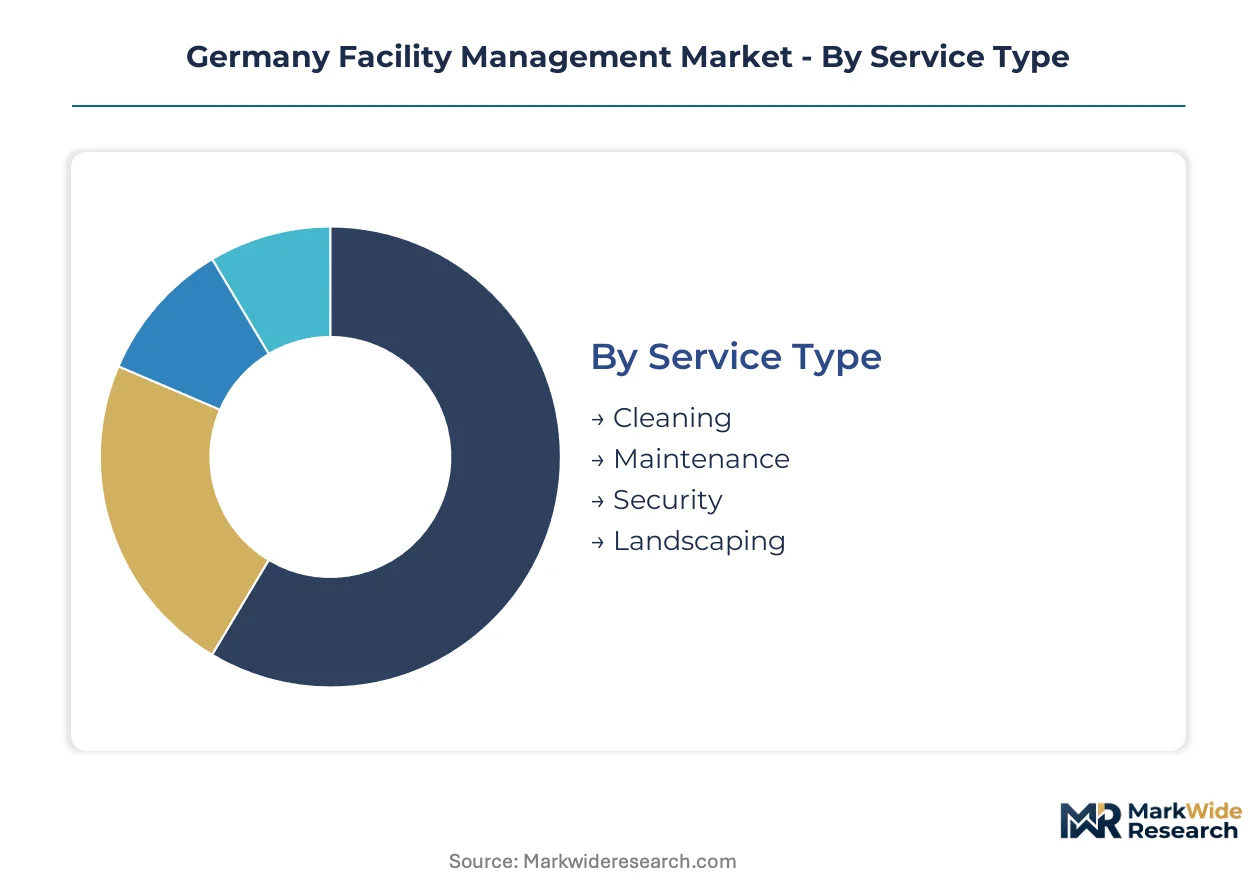
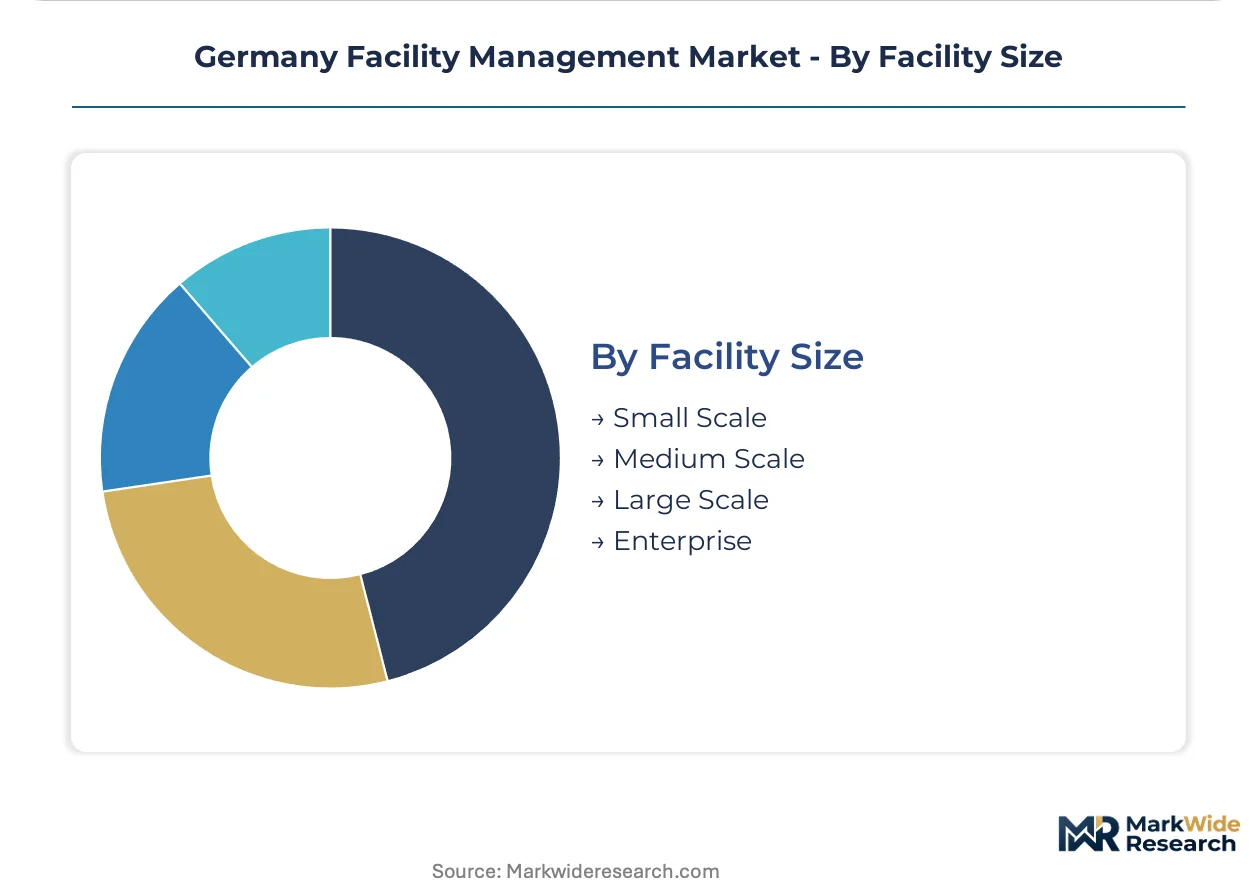
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping Client Type: Residential, Commercial, Industrial, Government Technology: IoT Solutions, Automation Tools, Building Management Systems, Energy Management Facility Size: Small Scale, Medium Scale, Large Scale, Enterprise |
| Companies Covered | ISS Facility Services GmbH, Sodexo Deutschland GmbH, Strabag SE, Compass Group PLC, Apleona GmbH, Bilfinger SE, WISAG Facility Service Holding GmbH, ENGIE Deutschland GmbH, Dussmann Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Facility Management Market Emerging Trajectories
Digital telemetry and predictive protocols are actively restructuring how German estates procure and measure facility services. Three convergent developments are compressing traditional maintenance cycles and redefining provider accountability structures.
Digital twin technology is decomposing reactive maintenance schedules into continuous simulation-driven asset management. Automotive manufacturers in Stuttgart and Wolfsburg deploy virtual building replicas to forecast HVAC degradation and optimize energy loads. This capability is decomposing the traditional periodic inspection model into subscription-based predictive service contracts.
KBA commercial fleet emission thresholds cascade into facility energy budgets through corporate carbon accounting linkages. Federal transport ministry mandates force logistics operators to attribute warehouse energy consumption to fleet carbon footprints. Industrial estates in Bavaria and North Rhine-Westphalia respond by procuring FM contracts with guaranteed kWh reduction clauses.
Healthcare operators now unbundle clinical support from infrastructure maintenance, creating distinct procurement streams for patient-facing versus building-facing services. University hospitals in Berlin and Munich separate catering and cleaning contracts from technical maintenance, enabling specialized vendor selection. This bifurcation is most visible in academic medical centers with research laboratory portfolios.
Germany Facility Management Market Segmentation
German FM procurement increasingly segments around accountability structures and telemetry capabilities rather than traditional trade boundaries. Service bundling patterns and facility scale thresholds now determine contract tenors and margin structures more decisively than legacy vendor relationships.
Service Type:
Cleaning services face the most acute substitution pressure from in-house staffing models during labor cost spikes, while technical maintenance commands durable outsourcing loyalty due to certification barriers.
- Cleaning:Labor-intensive surface sanitation and waste removal operations. Demand concentrates in Berlin and Munich healthcare estates where DIN hygiene standards and patient throughput requirements prevent internal staffing economies. Substitution risk peaks when federal minimum wage adjustments compress contract margins.
- Maintenance:Hard technical services spanning mechanical, electrical, and HVAC systems. Baden-Württemberg automotive manufacturing clusters drive precision environmental control requirements under VDI 2067 lifecycle frameworks, locking in long-tenor outsourced contracts.
- Security:Access control and surveillance operations with regulatory compliance overlays.
- Landscaping:Exterior grounds maintenance with seasonal demand fluctuation patterns.
Maintenance retains volume leadership; cleaning holds the steepest expansion curve as healthcare estates unbundle clinical from infrastructure services.
Client Type:
Cost tier stratification separates price-sensitive residential contracts from premium industrial engagements where technical certification justifies margin premiums.
- Commercial:Office and retail estates requiring integrated multi-service accountability. Frankfurt and Hamburg financial districts concentrate demand for CSRD-aligned carbon reporting capabilities within FM contracts.
- Industrial:Manufacturing and logistics facilities with specialized environmental controls. Bavarian and North Rhine-Westphalian industrial zones procure energy management services with guaranteed kWh reduction clauses tied to KBA fleet emission accounting.
- Residential:Multi-unit housing and property management portfolios.
- Government:Federal and municipal estates with public procurement transparency requirements.
Industrial commands margin leadership; commercial posts the steepest expansion trajectory as Energieeinsparverordnung mandates accelerate outsourced technical retrofits.
Technology:
Application maturity separates legacy building systems from predictive analytics platforms where capability scarcity creates vendor concentration.
- Building Management Systems:Centralized control platforms for HVAC, lighting, and security integration. Stuttgart and Wolfsburg automotive manufacturers deploy digital twin overlays for continuous simulation-driven asset management, displacing periodic inspection models.
- IoT Solutions:Sensor networks enabling real-time telemetry and predictive maintenance protocols. Healthcare estates in Berlin and Munich mandate verified telemetry infrastructure to satisfy upcoming EU CSRD disclosure obligations.
- Automation Tools:Robotic and AI-driven process optimization systems.
- Energy Management:Carbon-accountable service contracts with guaranteed consumption reductions.
Building Management Systems retain deployment volume leadership; IoT Solutions climb the fastest as CSRD disclosure cascades into mandatory tender clauses.
Facility Size:
Customer procurement sophistication stratifies sharply between enterprise accounts with integrated service demands and small-scale estates managing fragmented vendor relationships.
- Enterprise:Multi-site portfolios requiring standardized service delivery across federal states. Large healthcare systems and automotive manufacturing groups leverage scale to mandate single-accountability structures and real-time performance dashboards.
- Large Scale:Single-site industrial and commercial estates with complex technical requirements.
- Medium Scale:Regional commercial and light industrial properties.
- Small Scale:Localized service requirements with price-sensitive procurement patterns.
Enterprise retains contract value leadership; large scale gains share fastest as mid-market manufacturing facilities adopt digital building management to satisfy federal energy ordinances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management procurement intensity varies sharply across German states, with industrial density and regulatory stringency driving divergent service mix patterns. Western manufacturing corridors concentrate multi-service integrated contracts, while eastern regions exhibit higher fragmentation and technician scarcity.
Baden-Württemberg
Automotive manufacturing clusters in Stuttgart and Wolfsburg generate concentrated demand for precision environmental controls and predictive maintenance protocols. KBA emission thresholds force logistics operators to attribute warehouse energy consumption to fleet carbon footprints, accelerating digital building management adoption. Precision HVAC and energy telemetry services command premium contract tenors across the Stuttgart manufacturing belt.
North Rhine-Westphalia
Chemical and logistics estates in the Ruhr and Lower Rhine regions procure energy management services with guaranteed kWh reduction clauses tied to corporate carbon accounting. Federal Energieeinsparverordnung mandates compress procurement cycles toward integrated technical retrofits. Industrial facilities in Düsseldorf and Cologne corridors unbundle clinical from infrastructure services, enabling specialized vendor selection.
Bavaria
Munich and Nuremberg healthcare estates expand outsourced facility operations under tighter energy performance mandates, separating patient-facing from building-facing procurement streams. University hospitals mandate verified telemetry infrastructure to satisfy upcoming EU CSRD disclosure obligations. Academic medical centers with research laboratory portfolios drive bifurcated contracting structures.
Berlin-Brandenburg
Capital region healthcare and government estates concentrate demand for CSRD-aligned carbon reporting capabilities within FM contracts. Public procurement transparency requirements favor certified multi-service providers over single-trade vendors. Berlin university hospitals unbundle catering and cleaning contracts from technical maintenance, enabling specialized selection.
Thuringia-Saxony
Underpenetrated eastern industrial zones present acquisition opportunities for technicians with dual electrical-HVAC certifications. Rotating labor shortages for certified technicians tighten service delivery timelines across industrial contracts. Leipzig and Dresden manufacturing facilities adopt digital building management to satisfy federal energy ordinances despite legacy system integration friction.
Germany Facility Management Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multi-service accountability structures commanding premium positioning. Consolidation pressure favors providers with verified telemetry infrastructure and nationwide technician networks. Three archetypes dominate: integrated technical-commercial operators, healthcare-focused clinical support specialists, and energy-centric technical service providers. Competitive dynamics center on M&A to secure technician capacity in thin labor markets and strategic partnerships to embed IoT-enabled predictive capabilities.
Among Germany-based integrated operators, ISS Facility Services GmbH, Apleona GmbH, and Bilfinger SE exemplify the multi-service accountability tier. ISS Facility Services GmbH leverages nationwide technician network scale to sustain coverage in eastern Bundesländer labor markets. Apleona GmbH occupies a position representing integrated technical and commercial property management under single accountability structures. Bilfinger SE anchors the energy-centric technical archetype with industrial maintenance specialization. These entities sit within a competitive set where DIN EN 15221 compliance and specialized credentials exclude smaller regional competitors from premium contract tiers.
| Leading Market Players |
|---|
| ISS Facility Services GmbH |
| Sodexo Deutschland GmbH |
| Strabag SE |
| Compass Group PLC |
| Apleona GmbH |
| Bilfinger SE |
| WISAG Facility Service Holding GmbH |
| ENGIE Deutschland GmbH |
| Dussmann Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day technician lead times in eastern Bundesländer compress margin structures for industrial FM contracts while amplifying pricing power for providers with verified dual-certification workforces. This supply-side scarcity interacts with Energieeinsparverordnung-driven demand to stratify contract tenors around technical capability access rather than pure price competition.
Pricing Analysis
Long-term integrated service contracts dominate German FM procurement, displacing fragmented spot arrangements as healthcare and automotive estates mandate single-accountability structures. Price differentiation rests on DIN EN 15221 certification tiers and VDI 2067 lifecycle compliance depth, with premium technical providers commanding margin multiples over cleaning-only vendors. Cost compression in soft services intensifies as federal minimum wage adjustments squeeze labor-intensive contracts, while industrial clients show lowest price sensitivity for predictive maintenance bundled with guaranteed energy reduction clauses.
Supply Chain Analysis
Just-in-time technician deployment prevails across western manufacturing corridors, whereas eastern regions require strategic workforce stockpiling to cover rotating certification gaps. Germany, Austria, and Switzerland anchor technician training pipelines, drawing specialized HVAC and electrical credentials from dual-education apprenticeship systems. Supply chain risk centers on single-source vulnerability for Building Management System software modules embedded in predictive analytics platforms. Distribution runs through regional FM service hubs co-located with automotive and healthcare clusters in Stuttgart, Munich, and Berlin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German FM procurement is reconfiguring around service-attach revenue streams, with predictive maintenance subscriptions and CSRD-aligned carbon reporting expanding faster than baseline technical labor contracts. This recurring-revenue layer justifies capability investments that hardware-centric providers cannot replicate.
For Market Incumbents: Consolidate technician capacity in Thuringia-Saxony through targeted apprenticeship partnerships before labor deficits harden into structural constraints. Deepen Building Management System integration capabilities to defend against specialized IoT analytics entrants capturing healthcare telemetry mandates. DIN EN 15221 certification depth remains the critical lever for premium contract tier access. For New Entrants and Emerging Players: Anchor in underpenetrated eastern industrial zones where dual electrical-HVAC certification scarcity creates immediate coverage gaps. Target mid-scale manufacturing facilities adopting digital building management to satisfy federal energy ordinances but lacking enterprise-scale procurement sophistication. Lead with IoT-enabled predictive maintenance pilots that demonstrate measurable kWh reduction against Energieeinsparverordnung baselines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because technician network density and verified telemetry infrastructure compound defensively against fragmented regional competitors. Acquisition targets should display dual-certification workforce depth and existing healthcare or automotive contract anchors. The signal to watch is CSRD disclosure clause penetration in public FM tenders crossing threshold density in Berlin and Munich healthcare systems.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Apprenticeship Expansion | Secures dual electrical-HVAC certification pipelines in eastern Bundesländer labor markets. |
| Building Management System Integration | Positions providers for digital twin and predictive analytics mandates from Stuttgart automotive clusters. |
| CSRD-Aligned Carbon Reporting Capability | Enables premium contract access as EU disclosure obligations cascade into tender clauses. |
| Healthcare Estate Unbundling Specialization | Captures bifurcated procurement streams separating clinical support from infrastructure maintenance. |
| Energy Management Guarantee Structures | Differentiates industrial offerings through kWh reduction commitments tied to KBA emission accounting. |
Methodological Framework
The analysis maps hard services, soft services, and integrated multi-service contracts, each validated through facility directors, procurement officers at healthcare systems, automotive plant engineers, and FM vendor account executives. Primary interview insights combined with secondary validation from KBA regulatory filings, federal Energieeinsparverordnung documentation, DIN standards repositories, and regional Bauordnung databases. Bottom-up contract value aggregation and top-down market sizing triangulate volume estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions include service type bundling patterns, client industry verticals, technology deployment maturity, and facility scale thresholds. CAGRs derived from historical contract tenor analysis and forward procurement intention surveys. Forecast inputs incorporate KBA emission threshold implementation timelines and CSRD disclosure obligation phase-in patterns.
Material uncertainties — energy price volatility, technician migration patterns, and regulatory enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding federal ordinance compliance rates and digital adoption curves in brownfield manufacturing estates. Revision becomes warranted when CSRD clause penetration in public tenders or eastern technician deficit severity crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Spain Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Iceland Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
China Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
GCC Facility Management Market