
 Middle East and Africa Hard Facility Management Market | 2026-2036
Middle East and Africa Hard Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hard Facility Management Market Foresight
Saudi Arabia's contractor base is shifting toward integrated hard service delivery as giga-project construction peaks and transitions into operational phases. Emdad Facility Management leverages its government-linked heritage to anchor long-term maintenance contracts across Riyadh's developing economic zones. Farnek Services LLC differentiates through technology-led energy auditing and building automation specialization in the UAE. CBRE Group Inc extends its platform across multiple African hubs, competing on cross-border standardization for multinational clients.
Hard facility management encompasses the physical maintenance of building infrastructure including HVAC systems, electrical distribution, plumbing networks, fire safety equipment, and structural elements, typically governed by service level agreements specifying response times, uptime thresholds, and preventive maintenance schedules. Its primary purpose is to preserve asset value, ensure regulatory compliance, and sustain occupant safety across commercial and institutional properties. Maintenance services within the Service Type category dominate contract value due to recurring revenue streams and mandatory compliance cycles, while IoT Solutions under Technology is expanding fastest as predictive diagnostics reduce unplanned downtime. Outsourced contracts lead the Contract Type dimension, though hybrid models are gaining share as owners retain strategic oversight while delegating technical execution.
SFDA in Saudi Arabia and the UAE's civil defense authorities enforce fire safety and building system standards that hard service providers must certify against, creating compliance-driven demand for specialized technical labor. South Africa's National Building Regulations and Kenya's Energy Management Regulations add further standardization layers that shape procurement criteria and vendor qualification. Stakeholders must monitor how smart building mandates and carbon disclosure requirements redefine the technical skill mix and capital intensity of service delivery models.
Market Dynamics
Giga-project construction peaks across Saudi Arabia and the UAE are transitioning into operational phases, forcing hard facility management providers to pivot from installation support toward long-term maintenance contracts governed by stricter SFDA and civil defense compliance mandates.
Growth Catalysts
- Saudi Arabia's SFDA building safety mandates:Certification requirements for mechanical and electrical systems create recurring compliance-driven demand for specialized technical labor across healthcare and commercial assets.
- IoT-enabled predictive diagnostics:Smart building automation is expanding fastest under the Technology segment as sensor networks reduce unplanned downtime in Dubai's mega-project portfolios.
- Healthcare Facilities adoption:Gulf Cooperation Council states are accelerating hospital infrastructure investment, concentrating contract volumes for integrated hard services in Riyadh and Abu Dhabi economic zones.
Market Restraints
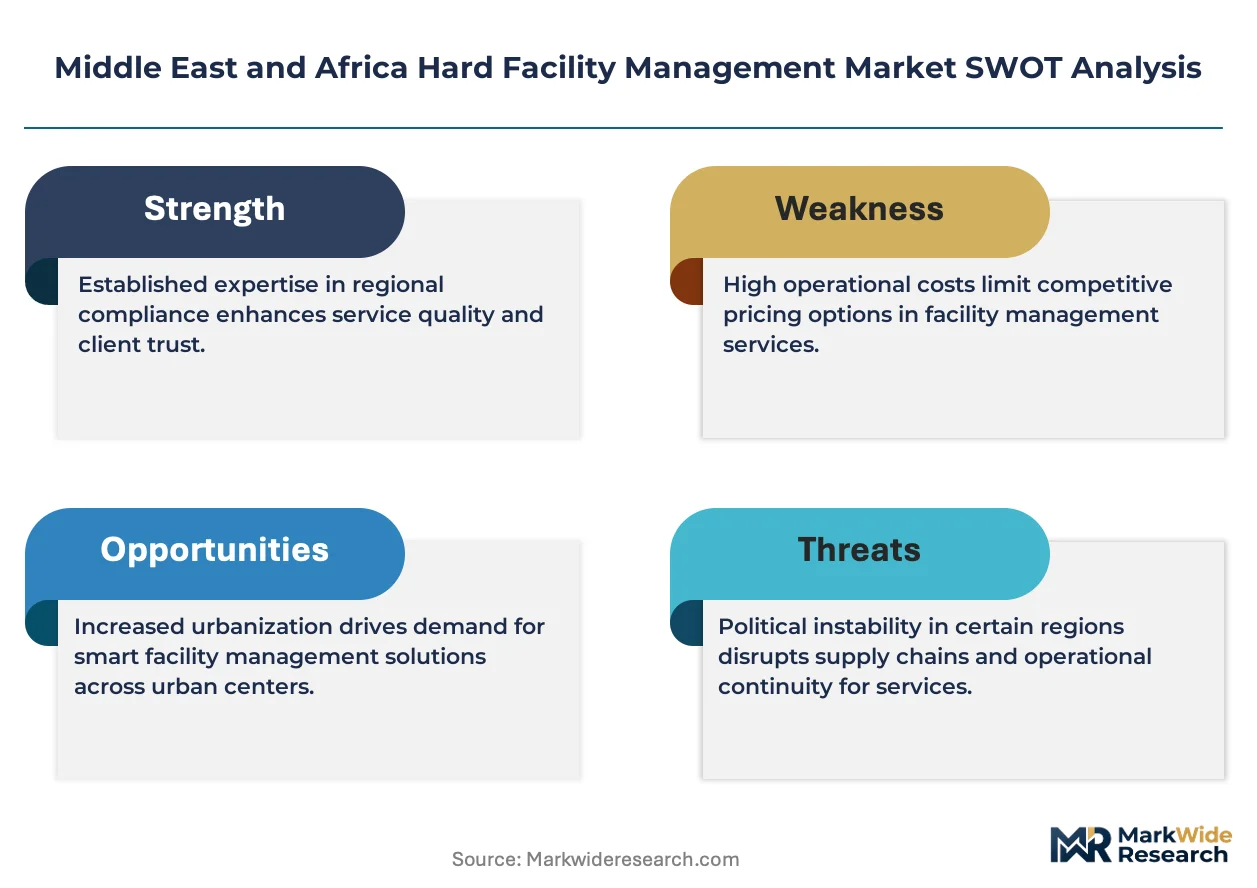
- Technical labor scarcity:Specialized certification requirements for fire safety and HVAC systems outpace vocational training pipeline output across the UAE and Saudi Arabia.
- Input cost volatility:Copper and semiconductor price fluctuations destabilize maintenance budgeting for electrical distribution and building automation component replacement cycles.
- Regulatory fragmentation:Divergent enforcement timelines between South Africa's National Building Regulations and Kenya's Energy Management Regulations complicate cross-border standardization for multinational facility operators.
Strategic Opportunities
- Kenya's underpenetrated commercial stock:Nairobi's emerging Grade-A office supply lacks mature hard service provider networks, opening first-mover positioning for integrated maintenance platforms.
- Carbon disclosure convergence:Dubai's smart building codes and Saudi Vision 2030 sustainability targets are mandating energy auditing capabilities that reward technology-led differentiation.
- Hybrid contract models:Owners retaining strategic oversight while delegating technical execution creates white space for vendors offering transparent SLA dashboards and predictive analytics layers.
Industry Challenges
- Certification timeline compression:SFDA and UAE civil defense authority approval cycles for fire safety equipment maintenance credentials strain workforce onboarding velocity.
- Legacy system integration friction:Building automation retrofits in aging Dubai and Riyadh commercial stock face protocol incompatibility with IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hard Facility Management Market |
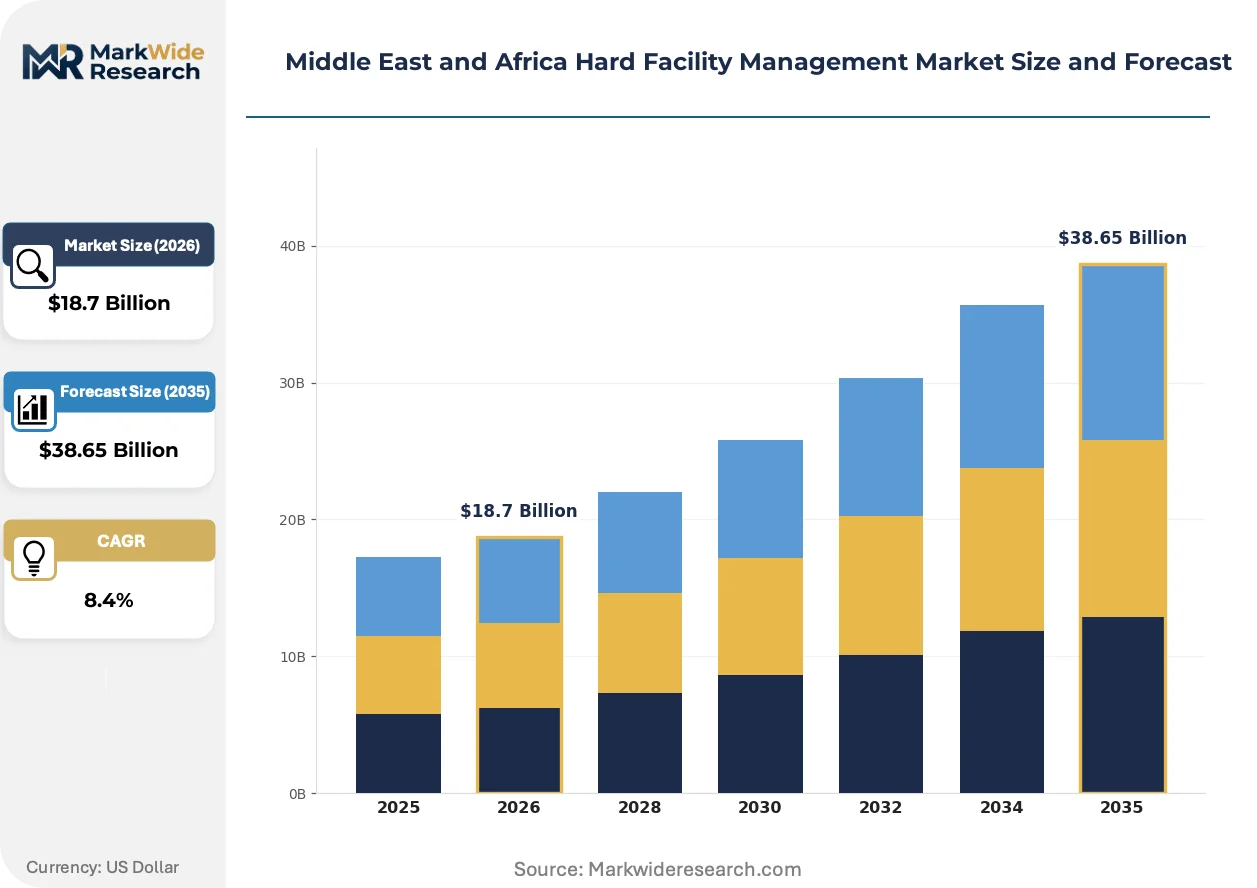
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Landscaping End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Government Offices Technology: IoT Solutions, Building Automation, Energy Management, Data Analytics Contract Type: Outsourced, In-house, Hybrid, Others |
| Companies Covered | CBRE Group Inc, Emdad Facility Management, EFS Facilities Services Group, Musanadah Facilities Management, Farnek Services LLC, Emrill Services LLC, Broll Nigeria, AG Facilities Solutions, Sodexo Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hard Facility Management Market Shifts & Advancements
Digital infrastructure is penetrating building operations at unprecedented depth across the Middle East and Africa, compressing response timelines and redefining competitive differentiation around data transparency rather than labor scale alone.
Building automation systems integrating HVAC, electrical distribution, and fire safety monitoring through centralized control platforms are expanding into premium commercial and healthcare assets. UAE-based property developers are specifying these systems in new construction at accelerating rates. The technology is expanding into mid-market office stock as cloud-based subscription models reduce upfront capital barriers.
Saudi Arabia's SFDA has tightened building safety certification requirements for mechanical and electrical maintenance providers, mandating documented preventive maintenance schedules and uptime thresholds. Industrial consequence includes disqualification of uncertified contractors from government-linked healthcare and education facility contracts. Healthcare Facilities and institutional commercial assets in Riyadh's economic zones are responding by consolidating vendor relationships toward integrated hard service specialists with established regulatory track records.
Buyers are unbundling after-sales service from initial equipment procurement, selecting hard facility management providers through competitive tender rather than manufacturer-captive maintenance agreements. This pattern is displacing single-brand service monopolies in Dubai's mega-project portfolios. The shift is most visible in Abu Dhabi's sovereign wealth-backed commercial developments, where procurement teams now mandate multi-vendor interoperability clauses in building automation specifications.
Middle East and Africa Hard Facility Management Market Segmentation
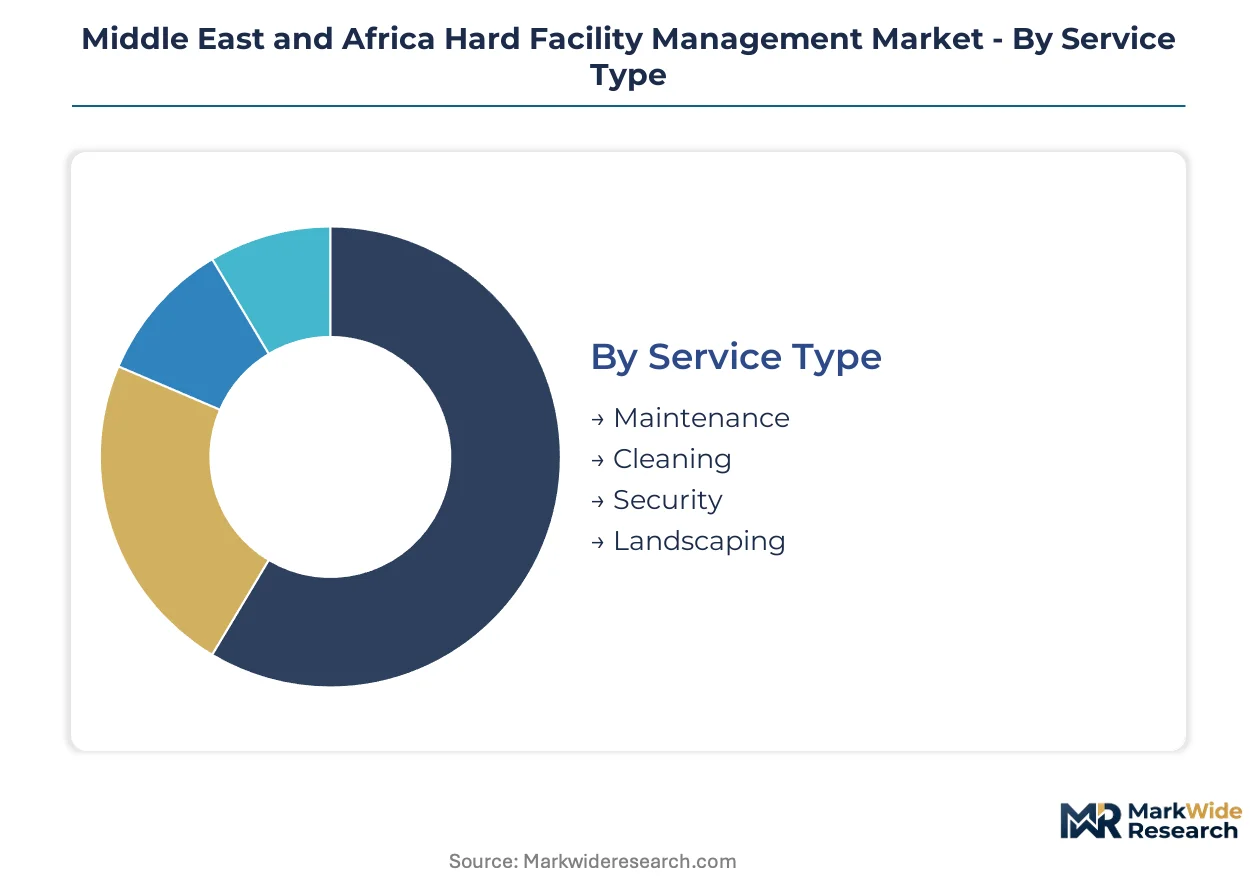
Hard facility management providers across the Middle East and Africa must align service architectures with divergent asset maturity, regulatory intensity, and technology readiness. Segmentation reveals where contract value concentrates versus where capability investments unlock premium positioning.
Service Type:
Maintenance commands the largest share of recurring revenue, while specialized services extract premium pricing from compliance-sensitive verticals.
- Maintenance:Encompasses preventive and corrective upkeep of HVAC, electrical, plumbing, and structural systems governed by SLA response thresholds. Demand concentrates in Saudi Arabia's healthcare and education assets where SFDA mandates documented uptime schedules and certified technician deployment.
- Cleaning:Specialized decontamination protocols for healthcare facilities and food-grade commercial spaces require HACCP-aligned staffing and equipment. Dubai's mega-project hospitality portfolios are tightening specifications around sustainability-certified chemical usage and water reclamation systems.
- Security:Physical access control and surveillance integration with building automation platforms.
- Landscaping:Irrigation and grounds maintenance, increasingly specified in Abu Dhabi's sovereign wealth-backed commercial developments with sustainability scoring requirements.
Today's leader: Maintenance. Tomorrow's challenger: Cleaning.
End User:
Healthcare and commercial assets drive contract sophistication, while government and education segments reward scale and regulatory track record.
- Commercial Buildings:Grade-A office towers and mixed-use developments in Dubai and Riyadh specify integrated hard services bundling HVAC, electrical, and fire safety under unified SLAs. Procurement teams now mandate multi-vendor interoperability clauses that disqualify single-brand captive maintenance agreements.
- Healthcare Facilities:Hospitals and clinics across Gulf Cooperation Council states require SFDA-certified mechanical and electrical maintenance with documented preventive schedules. Riyadh's developing economic zones are consolidating vendor relationships toward specialists with established regulatory credentials.
- Educational Institutions:Universities and K-12 facilities with seasonal occupancy patterns and deferred maintenance backlogs.
- Government Offices:Public sector assets where procurement favors government-linked heritage and long-term framework agreements.
Healthcare Facilities are climbing the fastest as giga-project construction peaks transition into operational compliance phases.
Technology:
Building automation anchors current investment, while predictive layers redefine competitive differentiation around data transparency.
- IoT Solutions:Sensor networks enabling predictive diagnostics for HVAC and electrical distribution systems. Dubai's smart building codes are accelerating deployment across mega-project portfolios where unplanned downtime carries penalty clauses.
- Building Automation:Centralized control platforms integrating HVAC, electrical, and fire safety monitoring. UAE developers specify these systems in new construction at accelerating rates, with cloud-based subscriptions reducing upfront capital barriers for mid-market office stock.
- Energy Management:Auditing and optimization platforms responding to Saudi Vision 2030 sustainability targets and Dubai's carbon disclosure mandates.
- Data Analytics:Performance dashboards and SLA transparency layers supporting hybrid contract models where owners retain strategic oversight.
Building Automation holds current share leadership. IoT Solutions are gaining share fastest as predictive capabilities compress response timelines.
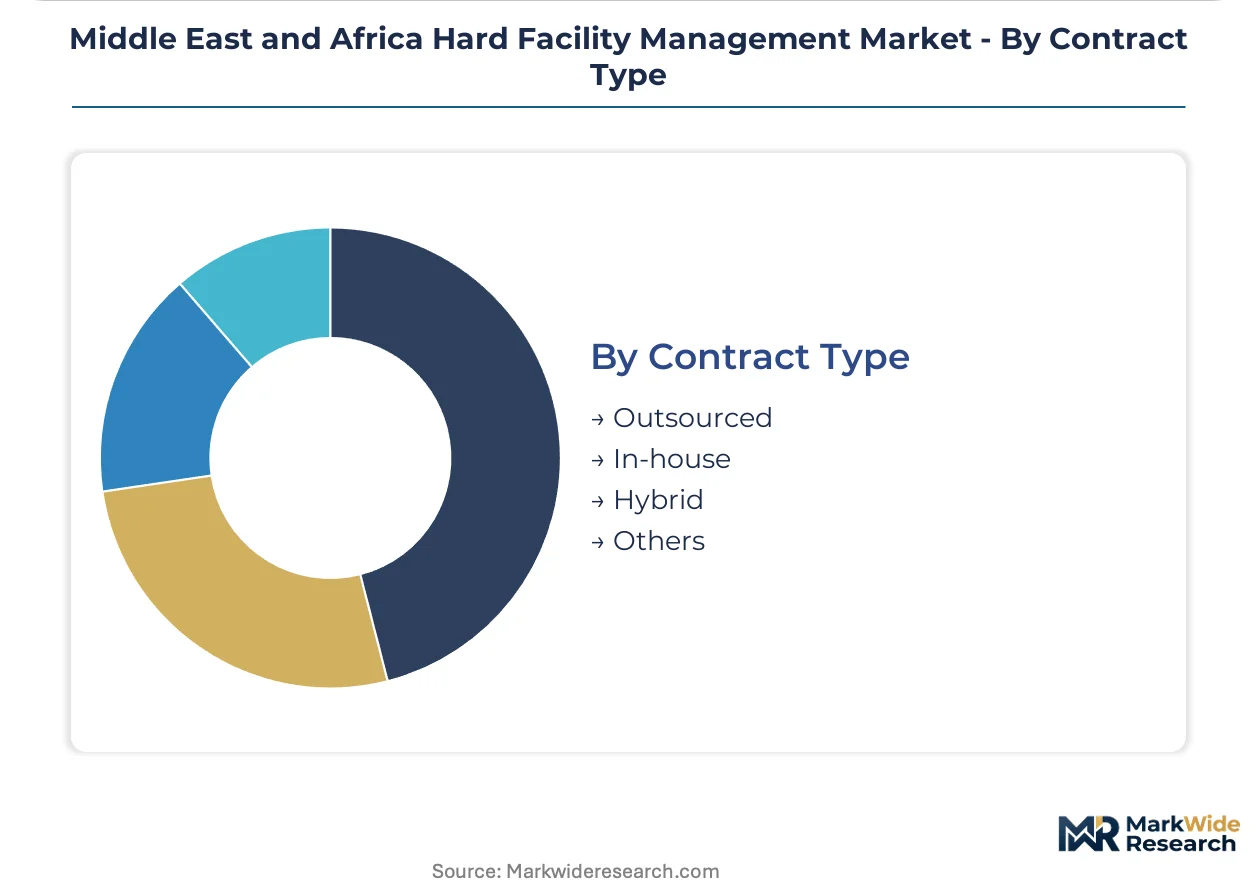
Contract Type:
Outsourced arrangements dominate volume, though hybrid structures are capturing margin from owners seeking control without technical execution burden.
- Outsourced:Full technical delegation to specialized facility management providers with certified labor pools and regulatory compliance infrastructure. This model dominates Dubai and Abu Dhabi commercial developments where developer exit strategies require operational handoff.
- Hybrid:Owners retain strategic oversight and capital planning while delegating technical execution to vendors offering transparent SLA dashboards. This structure is expanding fastest in Riyadh's economic zones where sovereign entities maintain asset control but lack specialized maintenance capacity.
- In-house:Captive technical teams, typically retained for critical infrastructure or government facilities with security sensitivities.
- Others:Managed equipment leases and performance-based arrangements with outcome-linked pricing.
Outsourced contracts anchor current volumes. Hybrid models represent the steepest expansion trajectory as procurement teams unbundle strategic from technical accountability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's giga-project pipeline generates deeper contract volumes than South Africa's established commercial stock, yet both markets now demand integrated hard services as construction phases conclude and operational compliance intensifies.
United Arab Emirates
Dubai's mega-project portfolios and Abu Dhabi's sovereign wealth-backed developments sustain outsourced contract demand for HVAC, electrical, and fire safety maintenance. MOHAP and civil defense authorities enforce building system certification requirements that disqualify uncertified contractors from healthcare and premium commercial assets. Riyadh-based specialists are extending UAE operations to capture hybrid contract models where owners retain strategic oversight.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya developments are transitioning from construction peaks into operational phases, forcing hard service providers toward long-term maintenance governed by SFDA safety mandates. SFDA certification requirements for mechanical and electrical systems create recurring demand for documented preventive schedules and specialized technical labor. Riyadh's economic zones are consolidating vendor relationships toward integrated specialists with established regulatory track records.
South Africa
Johannesburg and Cape Grade-A office towers require building automation retrofits as National Building Regulations tighten energy efficiency and fire safety compliance. The country's national building regulator enforces standards that shape procurement criteria for multinational facility operators. Durban's industrial corridor is generating maintenance demand for aging manufacturing infrastructure as owners unbundle after-sales service from original equipment procurement.
Kenya
Nairobi's emerging commercial stock lacks mature hard service provider networks, opening positioning for integrated maintenance platforms targeting healthcare and hospitality verticals. The country's energy management regulations mandate auditing capabilities that reward technology-led differentiation. Mombasa's port-related logistics facilities are specifying preventive maintenance contracts as regional trade volumes expand.
Egypt
New Administrative Capital construction is creating demand for hard facility management as government offices and commercial towers reach completion. The country's national building safety framework is tightening compliance requirements for mechanical and electrical systems in institutional assets. Cairo's healthcare infrastructure expansion is concentrating contract volumes for SFDA-aligned specialists extending operations from Gulf markets.
Middle East and Africa Hard Facility Management Market Competitive Landscape
Gulf-based providers anchor the premium tier; African specialists hold mid-market positioning through localized labor networks and regulatory familiarity. Market structure tilts toward consolidation as giga-project developers favor integrated hard service bundles over fragmented single-trade contracts. Three archetypes dominate: government-linked heritage operators securing long-term framework agreements, technology-led energy auditors capturing carbon disclosure mandates, and cross-border standardization platforms serving multinational clients. Dominant competitive moves include strategic partnerships for IoT-enabled predictive diagnostics and portfolio diversification into hybrid contract structures.
Among government-linked heritage operators, Emdad Facility Management occupies a position exemplifying regulatory-track-record advantage in Saudi Arabia's economic zones. Farnek Services LLC and Emrill Services LLC represent the technology-led tier, with Dubai-based positioning reflecting energy auditing and building automation specialization. CBRE Group Inc anchors the cross-border standardization archetype, extending platform presence across multiple African hubs to serve multinational facility operators seeking unified service levels.
| Leading Market Players |
|---|
| CBRE Group Inc |
| Emdad Facility Management |
| EFS Facilities Services Group |
| Musanadah Facilities Management |
| Farnek Services LLC |
| Emrill Services LLC |
| Broll Nigeria |
| AG Facilities Solutions |
| Sodexo Inc. |
| Others |
Supply & Pricing Matrix
Copper price volatility on the London Metal Exchange cascades through electrical distribution and HVAC component procurement, compressing margins for maintenance providers while forcing tiered service pricing that separates SFDA-certified specialists from uncertified contractors across Saudi Arabia and the UAE.
Pricing Analysis
Direct-to-developer contracting discounts dominate Dubai's mega-project portfolios, where bundled hard service agreements command premium positioning against fragmented single-trade competition. Price differentiation rests on certification tier — SFDA and UAE civil defense credentials — and technology integration depth, with IoT-enabled predictive platforms extracting 15-30% uplifts over reactive maintenance. Cost compression in mid-market office stock intensifies as cloud-based building automation subscriptions erode upfront capital barriers. Government-linked healthcare and education facilities show lowest price sensitivity due to compliance-driven procurement mandates, while Nairobi's emerging commercial landlords remain most cost-conscious.
Supply Chain Analysis
Saudi Vision 2030 local-content requirements are reshaping sourcing patterns for fire safety equipment and building automation components, mandating domestic assembly quotas that redirect procurement from traditional East Asian suppliers. Component supply draws from China for semiconductors and sensor networks, Germany for precision HVAC controls, and India for electrical distribution hardware. Single-source vulnerability concentrates in IoT chipsets subject to export licensing friction. Distribution runs through Dubai's Jebel Ali logistics hub for Gulf markets, with Riyadh's developing economic zones building captive supplier parks to shorten lead times for giga-project maintenance cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory deepening, with Saudi Arabia's SFDA building safety mandates creating recurring compliance demand that locks in vendor relationships across healthcare and institutional assets.
For Market Incumbents: Hedge against technical labor scarcity by anchoring long-term framework agreements with sovereign wealth-backed developers before giga-project construction peaks transition fully into operational phases. SFDA certification timeline compression threatens workforce onboarding velocity; counter through captive training academies partnered with Riyadh's economic zone authorities. Vertical integration into predictive analytics platforms preserves margin against commodity-driven cost volatility in copper and semiconductor replacement cycles. For New Entrants and Emerging Players: IoT-enabled energy auditing capabilities offer the clearest technology-first wedge into Nairobi's underpenetrated Grade-A office stock, where Kenya's Energy Management Regulations mandate auditing capabilities that incumbent generalists lack. Target healthcare verticals in Egypt's New Administrative Capital, where Cairo's hospital infrastructure expansion concentrates contract volumes for SFDA-aligned specialists extending from Gulf markets. Lead with transparent SLA dashboards supporting hybrid contract structures that sovereign entities favor for strategic oversight retention. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-led energy auditors possessing established regulatory track records across multiple Gulf jurisdictions, as carbon disclosure convergence and smart building code mandates deepen capability moats. Five-to-ten year viability favors platforms with demonstrated cross-border standardization for multinational clients rather than single-market labor arbitrage plays. Watch for hybrid contract model penetration rates in Riyadh's economic zones as the inflection signal — acceleration above current baselines indicates structural shift toward delegated technical execution with retained owner oversight.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Locks out uncertified competitors from Saudi healthcare and education facility contracts. |
| IoT Predictive Platform Deployment | Captures Dubai smart building code mandates while compressing client downtime penalty exposure. |
| Hybrid Contract Structure Rollout | Aligns with Riyadh economic zone procurement preferences for strategic oversight retention. |
| Cross-Border African Hub Expansion | Extends Gulf regulatory expertise into Nairobi and Cairo healthcare infrastructure buildouts. |
| Local-Content Partnership Formation | Satisfies Saudi Vision 2030 sourcing mandates while securing Jebel Ali logistics integration. |
Research Methodology
Bottom-up healthcare and commercial building modeling reconciled against top-down contractor capacity and certification tracking forms the analytical core. Primary interviews with facility management executives, SFDA compliance officers, sovereign wealth procurement directors, and building automation engineers combined with secondary validation against Saudi SFDA regulatory filings, UAE civil defense certification databases, MOHAP healthcare facility standards, and Gulf Cooperation Council trade flow records. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map service type, end-user vertical, technology tier, and contract structure against regional regulatory intensity and asset maturity gradients across the projection horizon. Modeled dimensions include maintenance versus specialized service mix, healthcare versus commercial asset concentration, IoT versus building automation technology penetration, and outsourced versus hybrid contract evolution. CAGRs derive from regression-based trend extrapolation adjusted for regulatory milestone impacts and construction-to-operations phase transitions in Saudi giga-projects.
The model holds under stable regulatory enforcement timelines and continued giga-project operational phase transitions; deviation in SFDA certification acceleration or copper price shock persistence would shift contractor margin trajectories and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Poland Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
South Africa Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Czech Republic Facility Management Market