
 Finland Facility Management Market | 2026-2036
Finland Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Facility Management Market Foresight
Finnish integrated FM providers is recalibrating service portfolios around energy performance contracting and smart building analytics. Caverion leverages its Nordic technical infrastructure footprint to capture complex industrial maintenance contracts. Lassila and Tikanoja anchors its competitive position through circular economy services embedded within waste and property maintenance operations. PHM Group differentiates via specialized healthcare facility management protocols that align with strict hygiene and operational continuity standards.
Facility management encompasses the professional coordination of building operations, maintenance, and support services to ensure functional, safe, and cost-effective environments for occupants and assets. Technical scope spans HVAC systems maintaining precise temperature and humidity parameters, electrical infrastructure monitoring, and preventive maintenance scheduling driven by IoT sensor data streams. Maintenance services within the Service Type dimension command the largest revenue share due to long-term contractual structures and regulatory compliance mandates. Energy Management Systems within the Technology dimension represent the fastest expansion trajectory as Finnish building operators face tightening carbon reduction obligations under national climate legislation.
Finland's Ministry of the Environment enforces building energy certificate requirements that directly shape FM procurement specifications and vendor qualification criteria. BSI Kitemark-aligned quality standards and EU Green Deal carbon reporting obligations further constrain operational practices and technology investment decisions. Stakeholders must monitor evolving municipal sustainability procurement rules and anticipate how digital building passport mandates will reshape asset data management requirements across the Nordic FM landscape.
Market Dynamics
Finland's facility management sector is undergoing structural transformation as building energy certificate mandates from the Ministry of the Environment force operators to integrate carbon performance into core service contracts. This regulatory pressure is compressing traditional maintenance margins while creating premium pricing power for providers capable of delivering verified energy outcomes.
Growth Catalysts
- EU Green Deal carbon reporting:Finnish municipal procurement rules now embed emissions disclosure requirements, expanding contract scopes for FM vendors with certified tracking capabilities.
- Healthcare facility expansion:Specialized hygiene protocols and operational continuity demands are pulling integrated service contracts toward dedicated healthcare FM providers.
- Smart building analytics:IoT sensor networks enabling predictive maintenance scheduling are reducing downtime costs and extending asset lifecycles for industrial clients.
Market Restraints
- Skilled technician scarcity:HVAC and building automation expertise concentrates in the Helsinki metropolitan area, constraining service expansion to peripheral municipalities.
- Input cost volatility:Electricity and district heating price fluctuations compress fixed-price contract margins during extreme weather periods.
- Regulatory compliance friction:BSI Kitemark-aligned quality standards impose documentation burdens that disproportionately burden mid-sized operators without dedicated compliance infrastructure.
Strategic Opportunities
- Tampere and Turku regional markets:Underpenetrated municipal building portfolios outside Helsinki present acquisition targets for integrated FM platforms.
- Digital building passports:Upcoming asset data management mandates will create first-mover advantages for operators with centralized building information modeling systems.
- Circular economy service bundling:Waste-to-resource conversion protocols aligned with national climate legislation open cross-selling opportunities within property maintenance contracts.
Industry Challenges
- Building automation integration complexity:Legacy HVAC control systems resist seamless connectivity with modern IoT platforms, requiring costly middleware development.
- Certification timeline compression:Accelerated energy efficiency amendments to the national building code demand rapid staff retraining on updated operational protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Facility Management Market |
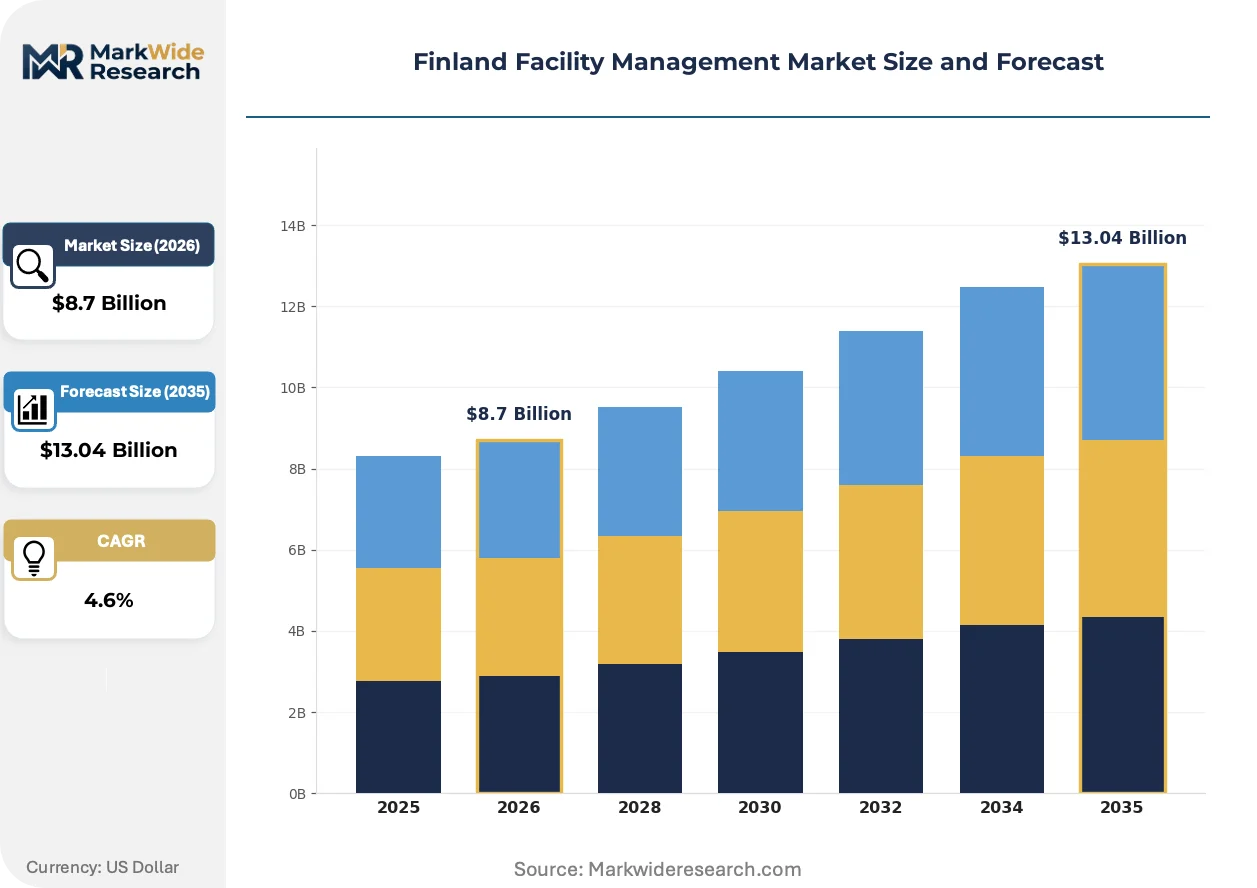
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Landscaping End User: Healthcare Facilities, Educational Institutions, Corporates, Retail Outlets Technology: IoT Solutions, Building Automation, Energy Management Systems, Environmental Monitoring Application: Commercial Buildings, Residential Areas, Industrial Sites, Government Facilities |
| Companies Covered | Caverion, Palmia Ltd, Lindstrom Group, Four FM, SOL Palvelut Oy, PHM Group, Lassila and Tikanoja, RTK Palvelu Oy, Coor Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Facility Management Market Shifts & Advancements
Technology convergence and regulatory digitization are compressing traditional service boundaries in Finnish facility management. Operators now compete on data transparency and carbon accountability rather than labor arbitrage alone.
Predictive maintenance platforms powered by machine learning algorithms are consolidating fragmented service workflows across HVAC, electrical, and plumbing systems. Industrial manufacturing facilities in the Helsinki-Tampere corridor are adopting these platforms fastest, driven by unplanned downtime costs. The technology is consolidating vendor relationships by bundling previously siloed technical specialties under single data-driven contracts.
Finland's Ministry of the Environment is tightening building energy certificate validity periods and disclosure requirements. This policy compresses the renovation cycle for commercial stock and mandates continuous operational optimization. Healthcare and educational facilities face the steepest compliance gradients, accelerating procurement of specialized energy performance contracting.
Public-private partnership structures are displacing traditional municipal tendering for building management. Finnish cities now prioritize long-term operational outcome guarantees over lowest-bid maintenance contracts. This behavioral shift is most visible in Helsinki metropolitan area schools and administrative buildings, where 10-15 year concession agreements are becoming standard.
Finland Facility Management Market Segmentation
Finnish facility management procurement patterns diverge sharply between high-volume standardized services and premium specialized contracts. Understanding these tiered demand structures reveals where margin compression concentrates and where pricing power persists.
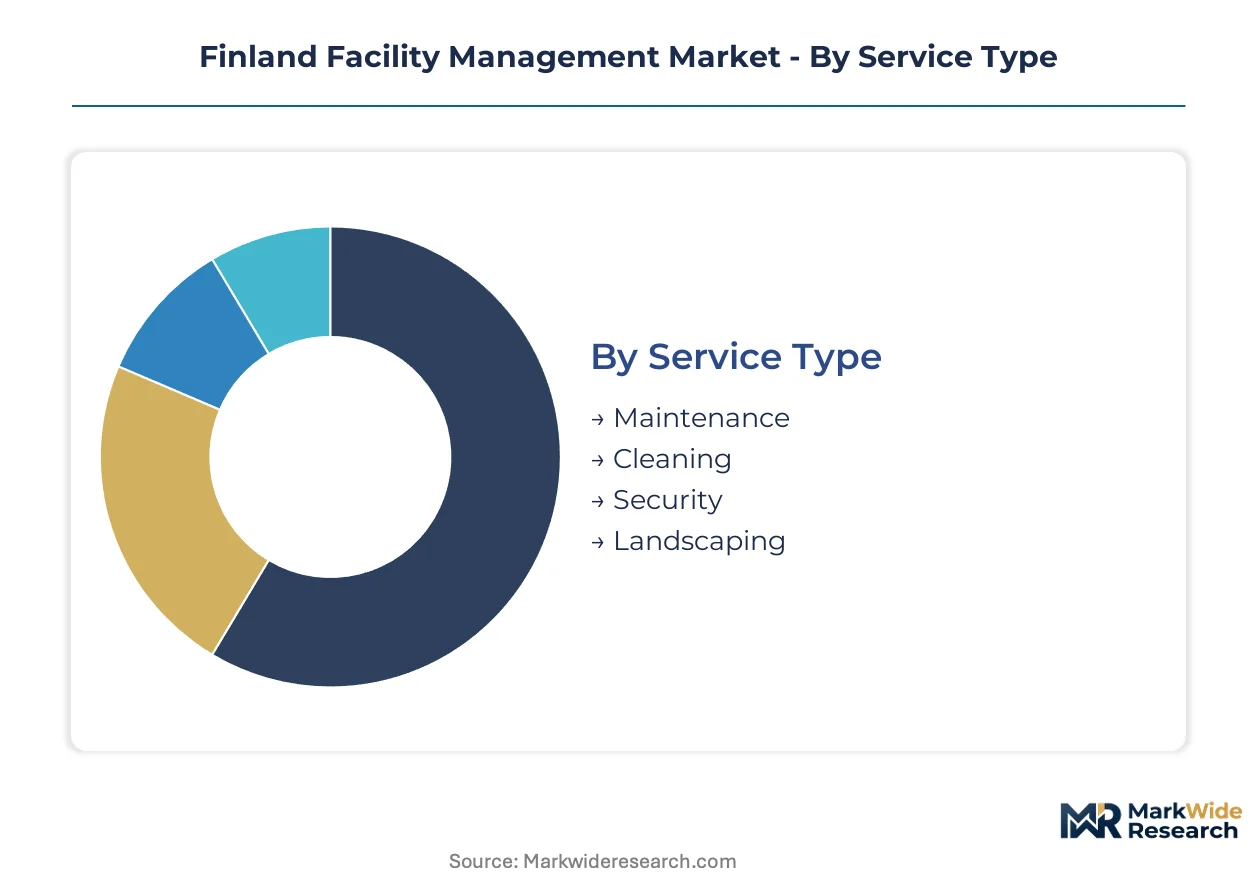
Service Type:
Maintenance commands the largest contract volume while energy performance contracting captures premium pricing. Cleaning and security services fragment across municipal tendering and private outsourcing respectively.
- Maintenance:Encompasses HVAC systems, electrical infrastructure, and preventive scheduling driven by IoT sensor data. Helsinki metropolitan area industrial facilities and healthcare campuses concentrate demand as regulatory compliance tightens operational protocols.
- Cleaning:Spans routine janitorial through specialized hygiene protocols for healthcare environments. Educational institutions and municipal buildings in the capital region anchor volume procurement, though margin pressure intensifies under fixed-price municipal contracts.
- Security:Includes physical guarding, access control systems, and surveillance integration. Retail outlets and corporate headquarters in Tampere and Turku drive adoption as asset protection requirements expand.
- Landscaping:Covers grounds maintenance, snow removal, and seasonal vegetation management. Residential area management companies and government facility portfolios sustain seasonal demand cycles.
Mature deployment sits with Maintenance. Newer deployment is concentrated in Security technology integration.
End User:
Healthcare and educational procurement channels operate through distinct tendering mechanisms with diverging contract tenures. Corporate and retail demand responds to occupancy cost optimization rather than regulatory mandate.
- Healthcare Facilities:Require specialized hygiene protocols, operational continuity guarantees, and 24/7 critical system redundancy. University hospitals in Helsinki and regional care networks drive contract consolidation toward integrated FM platforms.
- Educational Institutions:Span K-12 schools through university campuses with seasonal occupancy patterns. Municipal procurement reforms favoring 10-15 year concession agreements are reshaping vendor selection criteria across the Helsinki metropolitan area.
- Corporates:Prioritize workplace experience metrics and flexible space utilization. Technology sector offices in Espoo and Vantaa concentrate demand for smart building analytics.
- Retail Outlets:Focus on customer-facing cleanliness standards and energy cost control. Shopping centers and grocery chains anchor regional market penetration outside the capital.
Procurement maturity clusters in Healthcare Facilities. Digital transformation investment concentrates in Corporates.
Technology:
Building automation platforms command implementation premiums while environmental monitoring scales through sensor cost reduction. IoT and energy management systems occupy intermediate adoption phases.
- IoT Solutions:Sensor networks enabling predictive maintenance and real-time asset monitoring. Industrial manufacturing facilities in the Helsinki-Tampere corridor adopt fastest as unplanned downtime costs justify capital deployment.
- Building Automation:Integrated control systems spanning HVAC, lighting, and access management. Large commercial buildings and healthcare facilities concentrate demand where legacy system integration complexity creates vendor stickiness.
- Energy Management Systems:Software platforms for carbon tracking, consumption optimization, and regulatory reporting. These are expanding most quickly as EU Green Deal disclosure obligations tighten and municipal procurement rules embed emissions requirements.
- Environmental Monitoring:Air quality, occupancy sensing, and wellness metrics. Educational institutions and premium office developments pilot deployment as occupant health considerations reshape space design.
Legacy infrastructure dominance persists in Building Automation. Steepest expansion trajectory belongs to Energy Management Systems.
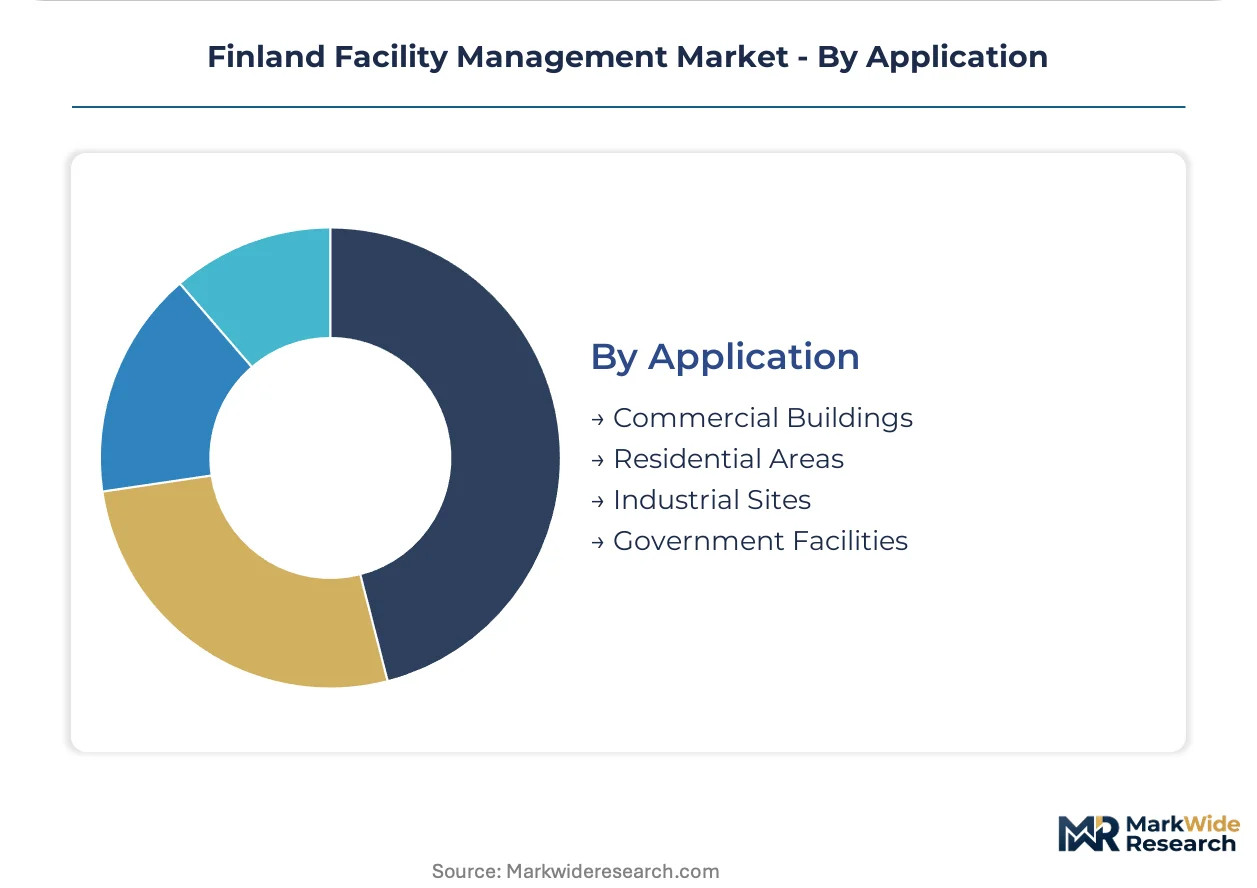
Application:
Commercial buildings generate the deepest contract pipelines while industrial sites command specialized technical capabilities. Residential and government segments operate through diverging procurement channels.
- Commercial Buildings:Office complexes, retail centers, and mixed-use developments requiring integrated service bundles. Helsinki central business district and emerging submarkets in Tampere anchor premium contract concentration.
- Industrial Sites:Manufacturing facilities, logistics hubs, and energy infrastructure demanding 24/7 operational continuity. Paper and pulp processing clusters in eastern Finland sustain specialized maintenance demand.
- Residential Areas:Multi-unit housing associations and property management portfolios. Volume concentrates in urban growth corridors where housing stock expansion outpaces professional management capacity.
- Government Facilities:Administrative buildings, courthouses, and military installations. Public-private partnership structures displace traditional tendering, favoring operators with long-term outcome guarantee capabilities.
Contract standardization is most advanced in Commercial Buildings. Procurement innovation concentrates in Government Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
District heating networks in the Helsinki metropolitan area anchor Finnish facility management demand. Municipal building stock concentration and public-private partnership structures concentrate procurement activity in southern Finland. Peripheral growth corridors in Tampere and Turku present expansion targets for integrated service platforms.
Helsinki Metropolitan Area
Healthcare campus expansions and university hospital networks drive specialized FM contract consolidation. Finland's Ministry of the Environment enforces building energy certificate requirements that reshape vendor qualification criteria. Espoo and Vantaa technology sector offices concentrate smart building analytics adoption as workplace experience metrics gain priority.
Tampere Region
Industrial manufacturing facilities along the Helsinki-Tampere corridor adopt predictive maintenance platforms fastest. EU Green Deal carbon reporting obligations embed emissions disclosure requirements into municipal procurement rules. Paper and pulp processing clusters sustain specialized maintenance demand for 24/7 operational continuity.
Turku and Southwest Finland
Retail outlet energy cost control requirements and customer-facing cleanliness standards anchor regional market penetration. National climate legislation tightens carbon reduction obligations for building operators. The Port of Turku logistics hub generates security and access control system demand as asset protection requirements expand.
Oulu and Northern Finland
Data center cooling infrastructure and telecommunications facilities create specialized technical service demand. Skilled HVAC and building automation expertise scarcity constrains service expansion to peripheral municipalities. Arctic climate conditions drive extreme weather period input cost volatility for fixed-price contract operators.
Eastern Finland Industrial Belt
Forest products and energy infrastructure sustain heavy industrial maintenance contract concentration. BSI Kitemark-aligned quality standards impose documentation burdens on mid-sized operators without dedicated compliance infrastructure. Legacy HVAC control systems resist seamless connectivity with modern IoT platforms across aging industrial stock.
Finland Facility Management Market Competitive Landscape
Global majors compete with regional champions across integrated service capabilities and energy performance contracting. The Finnish facility management sector exhibits tiered concentration where Nordic technical infrastructure operators capture complex industrial contracts alongside municipal service specialists. Three strategic archetypes dominate: integrated platforms bundling technical and soft services, circular economy specialists embedding waste-to-resource protocols, and healthcare-dedicated operators aligning with strict hygiene standards. Competitive dynamics center on public-private partnership concession bidding and regional acquisition targets outside Helsinki.
Within the integrated platform tier, Caverion leverages its Nordic footprint to anchor complex industrial maintenance positions. Lassila and Tikanoja exemplify circular economy archetypes through waste and property maintenance service bundling. PHM Group occupies a specialized position aligned with healthcare facility management protocols. These three operators represent distinct strategic vectors as municipal procurement reforms favor long-term outcome guarantees over lowest-bid maintenance contracts.
| Leading Market Players |
|---|
| Caverion |
| Palmia Ltd |
| Lindstrom Group |
| Four FM |
| SOL Palvelut Oy |
| PHM Group |
| Lassila and Tikanoja |
| RTK Palvelu Oy |
| Coor Group |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon reporting mandates embedded in Finnish municipal procurement rules are forcing facility management vendors to unbundle baseline maintenance from energy performance guarantees, compressing margins on standardized services while creating premium pricing tiers for verified outcome contracts. Supply responses concentrate in the Helsinki metropolitan area where integrated platforms capture economies of scope across technical and soft service bundles.
Pricing Analysis
Warranty and energy performance guarantee bundling separates premium integrated FM contracts from unbundled maintenance-only engagements. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic delivery cost, with BSI Kitemark-aligned operators commanding implementation premiums. Cost compression in municipal cleaning and security segments is intensifying because fixed-price tendering exposes operators to input cost volatility. Educational institutions anchor price-sensitive procurement, while healthcare facilities demonstrate lowest sensitivity due to operational continuity requirements.
Supply Chain Analysis
BSI Kitemark and EU Green Deal certification gating restricts qualified vendor pools to operators with dedicated compliance infrastructure and carbon tracking capabilities. Equipment and technology sourcing draws from Germany, Sweden, and Denmark, with building automation components and HVAC systems resting on Nordic technical infrastructure. Single-source vulnerability concentrates in specialized healthcare hygiene equipment where approved vendor lists limit substitution options. Distribution runs through direct municipal procurement channels and public-private partnership concession structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finnish facility management is consolidating around integrated platforms capable of delivering long-term outcome guarantees, with regulatory compliance friction forcing mid-sized operators toward acquisition or exit.
For Market Incumbents: Deploy energy performance contracting capabilities to capture premium pricing as EU Green Deal disclosure obligations tighten. Acquire specialized healthcare FM operators in Tampere and Turku to defend against PHM Group's regional expansion. Invest in centralized building information modeling systems to secure first-mover positioning on digital building passport mandates. For New Entrants and Emerging Players: Municipal housing associations in peripheral growth corridors offer the most penetrable entry point given professional management capacity constraints. Partner with district heating network operators to bundle energy optimization services with existing infrastructure relationships. Target circular economy service bundling as a differentiation vector against established waste-management incumbents. For Investors and Strategic Acquirers: The window for entry favors vertically integrated platforms with healthcare certification and Nordic technical infrastructure. Mid-sized operators with BSI Kitemark alignment but limited geographic scope represent prime acquisition targets. Monitor municipal sustainability procurement rule amendments as the inflection signal for accelerated contract consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Performance Contracting | Captures premium pricing as Finland's Ministry of the Environment tightens building energy certificate requirements. |
| Healthcare Certification Investment | Aligns vendor capabilities with university hospital operational continuity and hygiene protocol demands. |
| Building Information Modeling Integration | Positions operators for digital building passport mandates reshaping asset data management requirements. |
| Circular Economy Service Bundling | Embeds waste-to-resource protocols within property maintenance contracts per national climate legislation. |
| Regional Acquisition Program | Consolidates underpenetrated municipal portfolios in Tampere and Turku outside Helsinki market concentration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with facility management operations directors, municipal procurement officers, healthcare estates managers, and building automation engineers. Finland's Ministry of the Environment energy certificate databases, EU Green Deal implementation guidance, and municipal tendering records provided regulatory context. Bottom-up service type and end-user segmentation triangulated against top-down macroeconomic indicators across the Nordic region.
Segmentation granularity modeled service type, end user, technology, and application dimensions at the sub-regional level across Helsinki, Tampere, Turku, Oulu, and Eastern Finland industrial clusters. CAGRs derived from trend extrapolation of contract value growth and volume expansion across maintenance, cleaning, security, and energy management service lines. Forecast inputs incorporated district heating price trajectories and skilled technician availability constraints specific to Finnish building stock characteristics.
Caveats apply where regulatory timeline acceleration or municipal procurement reform pace could materially shift the outlook beyond modeled parameters. Forecasts reflect assumptions on public-private partnership adoption rates and carbon disclosure implementation stringency. A model refresh is warranted upon material change in EU Green Deal enforcement thresholds or national building code amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Canada Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
New Zealand Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Bahrain Facility Management Market