
 Avascular Necrosis Market | 2026-2036
Avascular Necrosis Market Size, Share, and Industry Trends Forecast 2026-2036
Avascular Necrosis Market Analysis
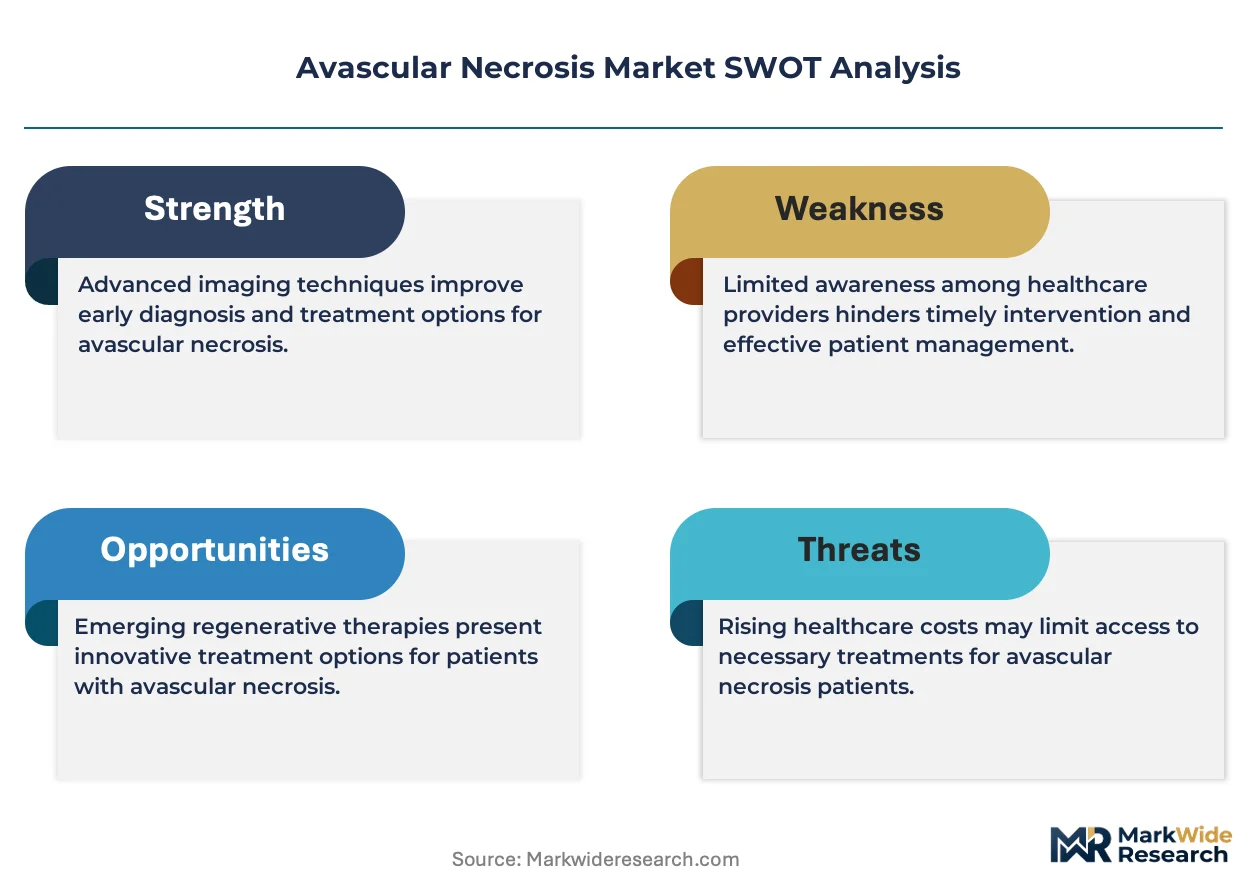
North American orthopedic implant manufacturers is repositioning production capacity toward patient-specific joint reconstruction systems. Stryker leverages its integrated surgical navigation platforms to sustain high-margin positioning in hip arthroplasty. Zimmer Biomet anchors its portfolio through ceramic-on-ceramic bearing surfaces that reduce revision rates in younger AVN patients. Smith & Nephew competes via its regenerative medicine pipeline targeting early-stage femoral head preservation.
Avascular necrosis denotes the ischemic death of bone tissue following interrupted blood supply, most commonly affecting the femoral head, with pathological progression measured through Ficat and ARCO staging systems that guide intervention thresholds. The condition demands intervention to prevent articular collapse and preserve joint function, with treatment selection hinging on lesion size, location, and patient age. Joint replacement commands the largest revenue pool among product categories, reflecting irreversible stage III and IV disease prevalence. Regenerative medicine represents the fastest-expanding segment, though margin capture remains constrained by mixed clinical evidence and payer hesitation. Diagnostic imaging through MRI technology leads detection protocols, enabling subchondral fracture identification before radiographic changes manifest.
The FDA's premarket notification and premarket approval pathways govern orthopedic device commercialization, while the Centers for Medicare & Medicaid Services sets reimbursement benchmarks that directly shape hospital procurement decisions. State-level certificate-of-need regulations in concentrated markets constrain capital expenditure for surgical infrastructure expansion. Stakeholders must monitor evolving health technology assessment criteria from private payers and integrated delivery networks as these entities increasingly precondition coverage on comparative effectiveness data.
Market Dynamics
Orthopedic surgery units in tertiary hospitals are consolidating purchasing power around integrated procedural platforms, forcing device manufacturers to bundle navigation systems with implant portfolios rather than sell components separately.
Growth Catalysts
- MRI Detection Protocols:Subchondral fracture identification before radiographic changes manifest enables earlier intervention thresholds. Tertiary hospitals in the United States deploy advanced imaging to stage disease progression.
- CMS Reimbursement Benchmarks:Medicare payment structures directly shape hospital procurement decisions for joint replacement procedures. The Centers for Medicare & Medicaid Services sets procedural volume incentives.
- Ceramic-on-Ceramic Bearings:Younger AVN patients demand bearing surfaces with demonstrated revision rate reductions. Implant manufacturers prioritize ceramic material science for femoral head preservation.
Market Restraints
- Regenerative Evidence Gaps:Mixed clinical data for cell-based therapies creates payer hesitation and coverage denials. Private insurers precondition reimbursement on comparative effectiveness thresholds.
- Certificate-of-Need Constraints:State-level CON regulations in concentrated United States markets limit surgical infrastructure expansion. Capital expenditure for new orthopedic surgery units faces approval bottlenecks.
- Allograft Supply Volatility:Bone graft material sourcing concentrates among limited tissue bank networks. Processing capacity constraints create procurement uncertainty for femoral head preservation procedures.
Strategic Opportunities
- Patient-Specific Reconstruction:Three-dimensional printing of custom joint components enables anatomical matching for complex AVN deformities. Additive manufacturing converges with preoperative planning software.
- Early-Stage Preservation:Core decompression combined with biologic adjuncts targets Ficat stage I and II lesions. This application segment remains underpenetrated relative to joint replacement volume.
- Integrated Delivery Networks:Hospital system consolidation creates centralized procurement leverage. Manufacturers must demonstrate total cost-of-care value to secure network-wide contracts.
Industry Challenges
- Orthopedic Surgeon Training:Navigation-assisted arthroplasty requires specialized fellowship exposure. Academic medical centers struggle to scale procedural education for emerging platforms.
- Health Technology Assessment Burden:Private payers demand real-world evidence generation for novel preservation therapies. Manufacturers face extended timelines for coverage determination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Avascular Necrosis Market |
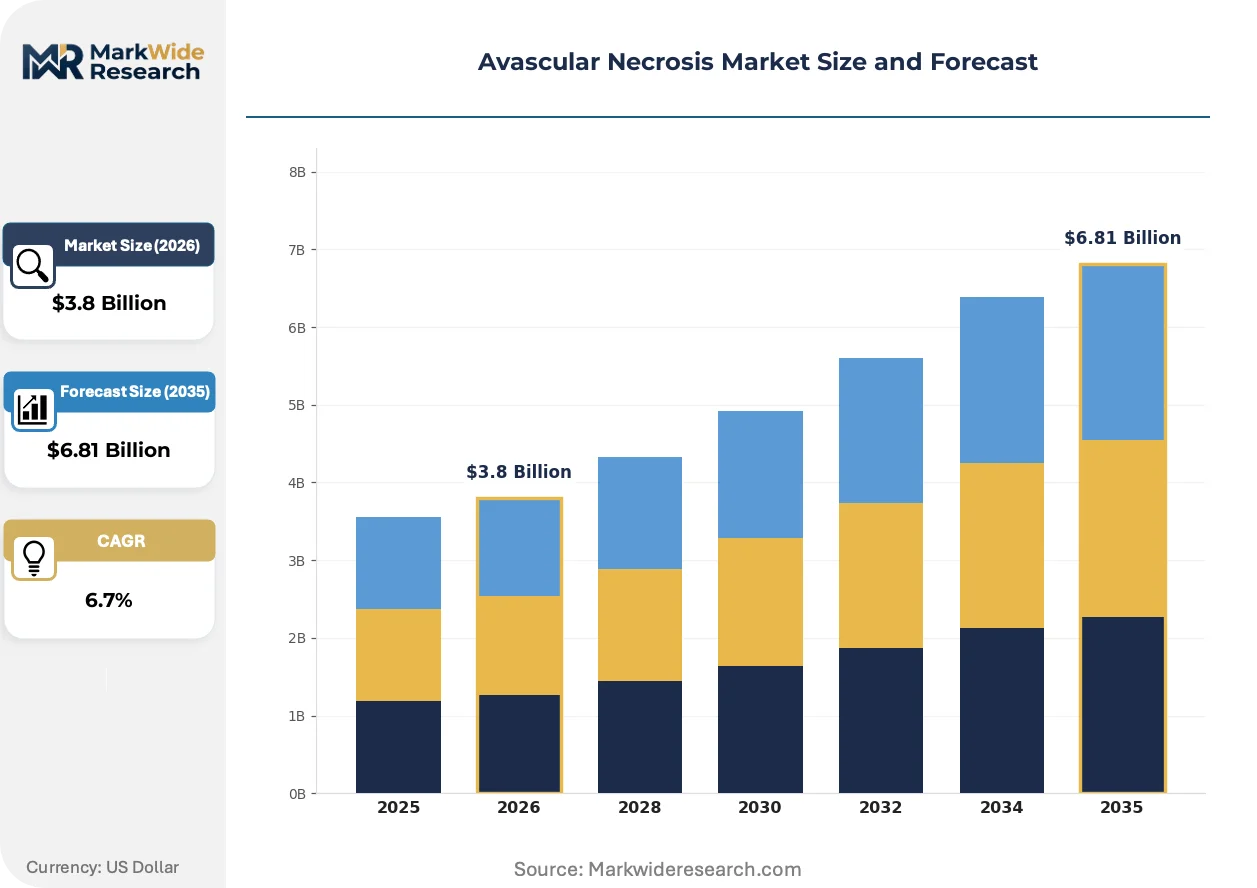
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bisphosphonates, Corticosteroids, Joint Replacement, Regenerative Medicine Application: Orthopedic Surgery, Pain Management, Rehabilitation, Diagnostic Imaging End User: Hospitals, Specialty Clinics, Rehabilitation Centers, Home Care Technology: Magnetic Resonance Imaging, X-Ray, CT Scan, Ultrasound |
| Companies Covered | Stryker, Zimmer Biomet, Smith & Nephew, Medtronic, Teva Pharmaceutical Industries Ltd., Bayer AG, Pfizer Inc., Novartis AG, Wright Medical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Avascular Necrosis Market Emerging Trajectories
Surgical navigation platforms are reshaping how orthopedic procedures are planned, executed, and reimbursed. Technology vendors must integrate hardware, software, and implant portfolios to maintain hospital system relationships.
Robotic-assisted hip arthroplasty is consolidating market positioning among high-volume orthopedic surgery units. Tertiary hospitals in the United States adopt these platforms to standardize component placement accuracy. The technology is consolidating purchasing decisions around vendors offering complete procedural ecosystems rather than standalone devices.
The FDA's premarket approval pathway for novel bearing surfaces has tightened evidentiary requirements for long-term wear data. Ceramic and cross-linked polyethylene submissions now require extended follow-up protocols. Implant manufacturers respond by front-loading clinical trial investment to preempt regulatory delays.
Hospital procurement committees increasingly bundle device selection with service and training contracts. Traditional distributor relationships face compression as integrated delivery networks centralize vendor management. This pattern concentrates most visibly in United States metropolitan markets where health system consolidation has advanced furthest.
Avascular Necrosis Market Segmentation
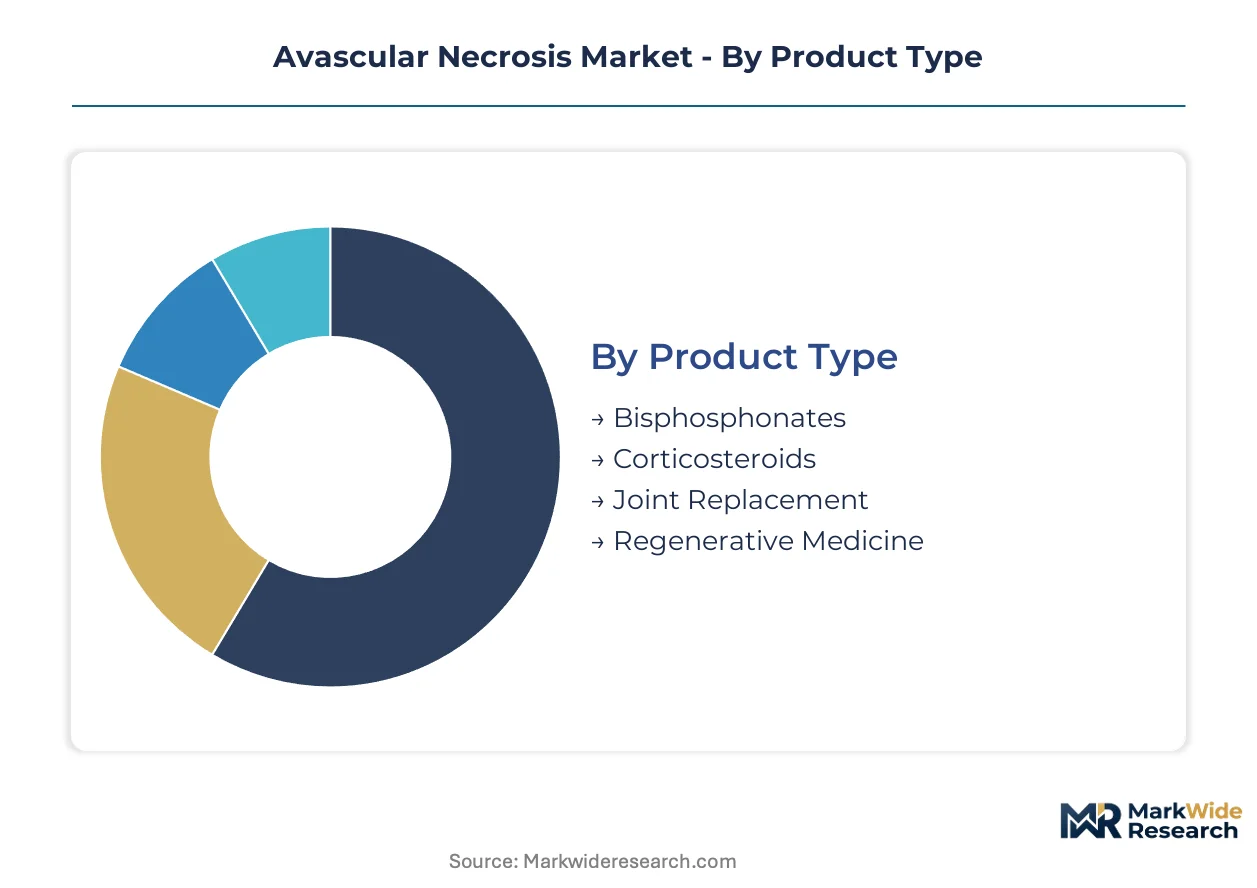
Product differentiation in avascular necrosis care follows distinct clinical pathways, from pharmaceutical management of early-stage disease to surgical intervention for femoral head collapse. Segmentation reveals how procurement decisions split between preservation economics and replacement necessity across healthcare settings.
Product Type:
Upgrade cycles vary dramatically across this category, with joint replacement hardware demanding decade-long revision schedules while pharmaceutical regimens turn over within treatment protocols.
- Joint Replacement:Femoral head and acetabular components manufactured from cobalt-chrome, ceramic, or cross-linked polyethylene address irreversible stage III and IV disease. Tertiary hospitals in the United States anchor procurement volume, driven by Medicare reimbursement benchmarks for arthroplasty procedures.
- Regenerative Medicine:Cell-based therapies and biologic adjuncts target femoral head preservation through core decompression enhancement. Demand concentrates among academic medical centers pursuing early-stage intervention, though payer coverage remains inconsistent pending comparative effectiveness data.
- Bisphosphonates:Alendronate and zoledronic acid formulations slow osteoclast-mediated bone resorption in pre-collapse lesions. Rheumatology and orthopedic practices prescribe these for Ficat stage I and II patients.
- Corticosteroids:Intra-articular and systemic formulations manage inflammatory symptoms despite their documented role as an AVN etiological factor. Pain management clinics utilize these for palliative care in non-surgical candidates.
Joint replacement sits at the top of the volume ranking, with regenerative medicine climbing the fastest.
Application:
Cost tier separation distinguishes emergency surgical intervention from longitudinal diagnostic monitoring across care episodes.
- Orthopedic Surgery:Arthroplasty and joint-preserving procedures command premium reimbursement codes. High-volume surgical centers in metropolitan United States markets drive procedural concentration.
- Diagnostic Imaging:MRI protocols enable subchondral fracture detection before radiographic manifestation. Tertiary hospitals deploy advanced imaging to stage disease progression and guide intervention timing.
- Pain Management:Multimodal analgesic protocols address symptomatic progression in non-operative candidates. Interventional pain practices coordinate with orthopedic referral networks.
- Rehabilitation:Post-surgical physical therapy and joint protection education optimize functional outcomes. Outpatient rehabilitation centers extend care continuity following hospital discharge.
Orthopedic surgery captures the highest revenue per episode, while diagnostic imaging expands most quickly through staging protocol adoption.
End User:
Customer type fragmentation reflects divergent purchasing authority between integrated delivery networks and independent practice settings.
- Hospitals:Inpatient and outpatient surgical units consolidate implant procurement through value analysis committees. The Centers for Medicare & Medicaid Services reimbursement structures directly shape device selection and procedural volume.
- Specialty Clinics:Orthopedic and rheumatology practices manage early-stage disease through pharmaceutical and injection-based protocols. These settings drive diagnostic imaging referral patterns.
- Rehabilitation Centers:Post-acute facilities deliver physical therapy following surgical intervention or for conservative management candidates.
- Home Care:Durable medical equipment and remote monitoring support mobility preservation for advanced disease patients.
Hospitals dominate absolute procedure volume, with specialty clinics gaining share fastest through outpatient migration.
Technology:
Margin structures diverge between capital-intensive imaging platforms and disposable radiographic consumables.
- Magnetic Resonance Imaging:High-field systems detect bone marrow edema and subchondral fractures with superior sensitivity to radiography. Academic medical centers in the United States deploy these for ARCO staging precision.
- X-Ray:Plain radiography remains the initial screening modality despite limited sensitivity for early disease. Community hospitals and outpatient clinics utilize these for cost-effective fracture assessment.
- CT Scan:Three-dimensional reconstruction quantifies lesion size and femoral head involvement for surgical planning.
- Ultrasound:Point-of-care applications guide injection procedures and monitor soft tissue complications.
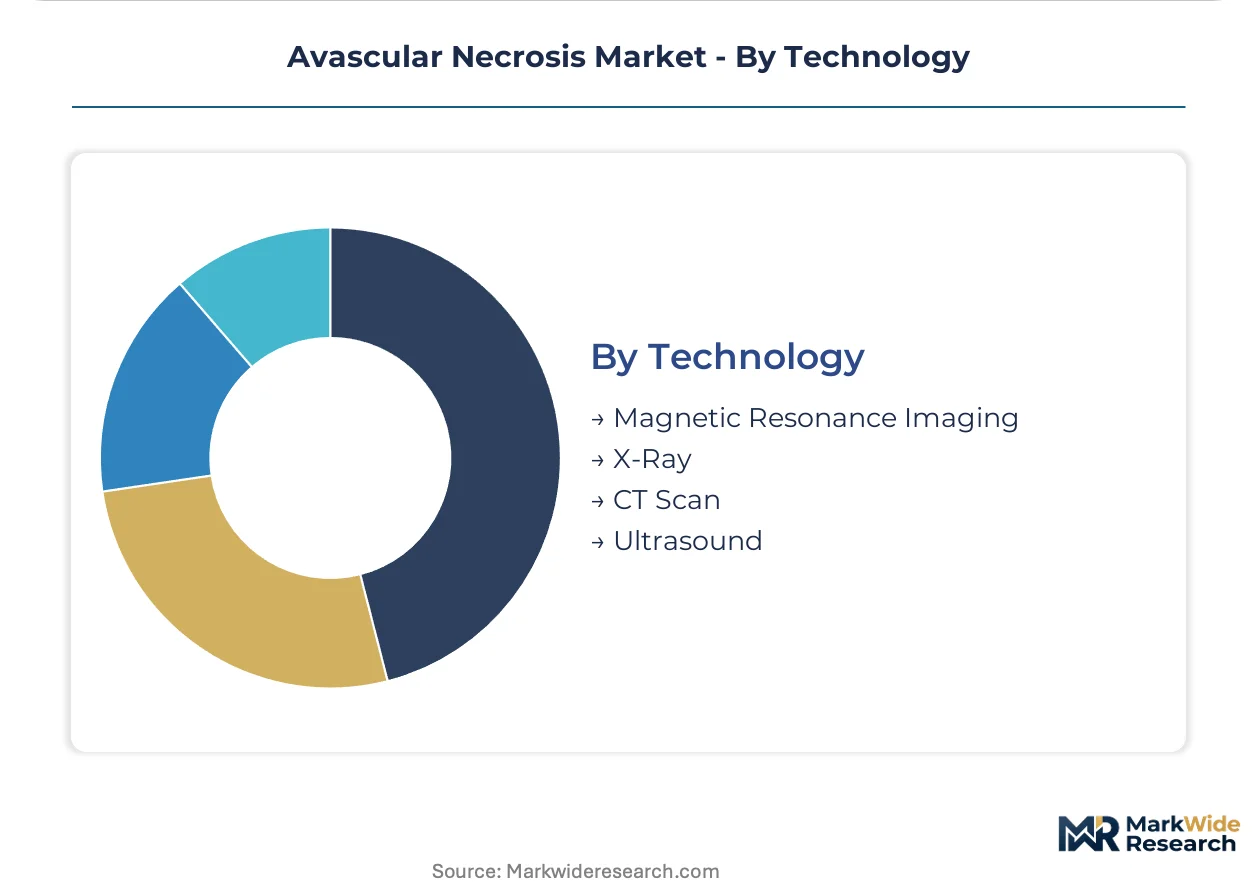
MRI holds the top position in diagnostic value per scan, with CT applications expanding most rapidly through preoperative planning integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic device manufacturers are arbitraging regulatory compliance costs across jurisdictions, with production capacity migrating toward markets offering streamlined premarket pathways and favorable reimbursement frameworks. The United States maintains the steepest cost-of-compliance environment, while select European and Asian markets attract manufacturing investment through accelerated approval timelines.
United States
Tertiary hospitals in metropolitan clusters drive procedural volume through Medicare reimbursement incentives. The FDA's premarket notification and premarket approval pathways govern orthopedic device commercialization timelines. Academic medical centers in Boston and Rochester anchor hip arthroplasty innovation through integrated surgical navigation adoption.
Germany
University hospitals in Bavaria and North Rhine-Westphalia concentrate ceramic-on-ceramic bearing research. The EU Medical Device Regulation (MDR) and CE marking requirements shape product launch schedules for implant manufacturers. The Baden-Württemberg medical technology cluster around Tübingen and Stuttgart supports precision manufacturing for patient-specific joint components.
Japan
Aging demographics and high hip osteoarthritis prevalence sustain demand for femoral head preservation procedures. The Pharmaceuticals and Medical Devices Agency (PMDA) operates Sakigake designation pathways for regenerative medicine products. Tokyo and Osaka metropolitan areas host concentrated orthopedic surgery capacity with advanced MRI staging protocols.
China
Domestic orthopedic implant production scales through volume-based procurement reforms in provincial hospital systems. The National Medical Products Administration (NMPA) governs Class III device registration with increasing alignment to international standards. The Yangtze River Delta medical device corridor around Shanghai attracts joint venture manufacturing for ceramic bearing surfaces.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex arthroplasty at designated tertiary centers. The Medicines and Healthcare products Regulatory Agency (MHRA) operates post-Brexit device approval pathways with transitional recognition arrangements. The Oxford and London orthopedic clusters lead health technology assessment integration for novel preservation therapies.
Avascular Necrosis Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue regenerative medicine adjacencies with mixed clinical evidence profiles. The orthopedic implant segment consolidates around integrated procedural platform vendors, while pharmaceutical and biologic suppliers fragment across preservation therapy niches. Three archetypes dominate: diversified medtech conglomerates with navigation-implant bundles, specialized orthopedic pure-plays with ceramic bearing expertise, and regenerative medicine developers targeting early-stage intervention. Competitive moves center on hospital system contract consolidation and health technology assessment evidence generation for payer coverage.
Among diversified medtech conglomerates, Stryker, Zimmer Biomet, and Smith & Nephew represent distinct positioning archetypes within the hip arthroplasty ecosystem. Stryker exemplifies the integrated platform strategy through its navigation-surgical ecosystem bundling. Zimmer Biomet anchors the ceramic bearing specialization vector with material science differentiation. Smith & Nephew occupies the preservation therapy development tier through regenerative medicine pipeline investment. Each represents a competitive response to hospital procurement committee demands for total cost-of-care contracting and service integration.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Medtronic |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| Pfizer Inc. |
| Novartis AG |
| Wright Medical Group |
| Others |
Supply Flow & Price Mechanics
Captive manufacturing of ceramic bearing substrates anchors supply positions for orthopedic implant leaders while simultaneously defending premium pricing tiers against commoditization pressure from Asian competitors. The FDA's premarket approval timelines for novel bearing surfaces create regulatory moats that reinforce pricing power for incumbent manufacturers with established clinical datasets.
Pricing Analysis
Distributor margin compression is accelerating as integrated delivery networks consolidate vendor management and demand direct contracting. Three-tier pricing structure across premium, standard, and economy levels separates navigation-integrated arthroplasty systems from bare implant components and generic alternatives. Price differentiation hinges on ceramic material certification grades and bundled service contracts. Cost compression in standard-tier implants is intensifying because volume-based procurement reforms in China and provincial hospital systems are exporting price benchmarks globally. Academic medical centers show least price sensitivity due to research funding offsets, while community hospitals in competitive metropolitan markets face acute procurement pressure.
Supply Chain Analysis
Regional distribution centers in Memphis, Indianapolis, and Rotterdam anchor hub-and-spoke patterns for implant logistics, with same-day delivery contracts to high-volume orthopedic surgery units. Manufacturing concentration in Ireland, Switzerland, and the United States reflects proximity to regulatory agencies and precision machining expertise. Raw material dependencies span medical-grade alumina powder, cobalt-chrome alloys, and cross-linked polyethylene resin. Single-source vulnerability concentrates in ceramic powder processing, where three European suppliers control pharmaceutical-grade material flows. Distribution runs through specialized orthopedic distributors with sterile field service capabilities, though hospital system consolidation is compressing intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between the FDA's extended PMA timelines and Japan's PMDA Sakigake fast-track creates geographic cost differentials for regenerative medicine developers seeking earliest revenue recognition.
For Market Incumbents: Deepen backward integration into ceramic powder processing to secure supply continuity and capture margin from upstream material science. Prioritize CE marking investment for EU MDR compliance ahead of competitors facing recertification bottlenecks. Navigation-assisted platform bundling remains the priority lever against pure-play implant commoditization. For New Entrants and Emerging Players: The premium-to-economy price-point gap in hip arthroplasty exposes white-space opportunity for mid-tier ceramic-on-polyethylene systems with simplified instrumentation. Target early-stage preservation therapies in Japanese and German markets where regenerative medicine reimbursement frameworks are advancing fastest. Pursue hospital system partnership models with total cost-of-care guarantees rather than per-procedure pricing. For Investors and Strategic Acquirers: Roll-up economics work for regenerative medicine platform consolidation because fragmented cell-therapy developers lack standalone commercial infrastructure and payer negotiation scale. Focus on five-to-ten year viability for preservation therapy portfolios as joint replacement volumes plateau in aging populations. Watch for FDA breakthrough device designations as inflection signals for coverage determination acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extended follow-up protocols for ceramic bearings delay competitor entry and protect incumbent revenue streams. |
| Hospital System Partnership | Integrated delivery network contracts with Stryker and Zimmer Biomet consolidate procurement around navigation-implant bundles. |
| CE Marking Pathway | EU MDR compliance investment separates certified manufacturers from recertification-constrained competitors in European markets. |
| Reimbursement Strategy | CMS benchmark alignment determines procedural volume incentives and shapes hospital value analysis committee decisions. |
| Software Companion Development | Preoperative planning platforms from Stryker's navigation ecosystem tighten customer switching costs and service contract renewal rates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining orthopedic surgeon interviews, hospital purchasing committee discussions, and biomedical engineering consultations with secondary validation from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up implant volume modeling and top-down market sizing triangulated across analysis window.
Comparable-period anchoring tied projection horizon to historical arthroplasty procedure volumes, ceramic bearing adoption curves, and regenerative medicine clinical trial enrollment patterns. Segmentation dimensions spanned product type, application setting, end-user facility tier, and imaging technology deployment. CAGRs derived from procedure volume elasticity to demographic aging and reimbursement rate adjustments, with ceramic material cost trajectories and navigation system replacement cycles as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted hip arthroplasty would alter the outlook if hospital capital expenditure constraints relax faster than projected. Forecasts reflect documented assumptions regarding FDA approval timelines, CMS reimbursement stability, and ceramic supply chain continuity. Payer coverage reversals for cell-based therapies or sudden ceramic powder supply disruptions could materially revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market