
 Intraductal Papilloma Market | 2026-2036
Intraductal Papilloma Market Size, Share, and Industry Trends Forecast 2026-2036
Intraductal Papilloma Market Outlook
Hospital procurement of intraductal papilloma diagnostic systems is consolidating toward integrated imaging-biopsy platforms. Hologic, Inc. dominates breast imaging modality placements across United States health systems. Siemens Healthineers leverages its MRI-guided biopsy portfolio to anchor premium hospital contracts. Boston Scientific competes in the therapeutic intervention segment with ductoscopy-compatible devices.
Intraductal papilloma denotes a benign epithelial tumor arising within breast ductal structures, characterized by arborizing fibrovascular cores lined by myoepithelial and luminal epithelial cells, with primary clinical purpose of differentiating benign proliferative lesions from malignant transformation requiring surgical excision. Diagnostic imaging leads segment value contribution due to recurring capital replacement cycles and software upgrade revenue, while biopsy devices represent the fastest-growing product category driven by vacuum-assisted and core needle platform adoption. Ultrasound technology occupies the dominant modality position for initial lesion characterization, though MRI is displacing conventional imaging in high-risk patient surveillance protocols.
FDA premarket notification requirements under 21 CFR 892 shape device clearance timelines for ultrasound and MRI biopsy systems, while HIPAA privacy frameworks govern cross-institutional imaging data sharing for multicenter clinical research. The Centers for Medicare and Medicaid Services reimbursement determinations for image-guided breast procedures directly influence hospital capital allocation toward integrated diagnostic platforms. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled lesion detection algorithms and their classification as Software as a Medical Device.
Market Dynamics
Hospital procurement of intraductal papilloma diagnostic systems is consolidating toward integrated imaging-biopsy platforms, compressing vendor margins while elevating technical performance requirements for equipment suppliers.
Growth Catalysts
- FDA 21 CFR 892 pathways:Tightened premarket notification requirements for breast biopsy devices are accelerating hospital investment in next-generation diagnostic platforms that preempt compliance risks.
- Ultrasound-guided vacuum-assisted biopsy:Tertiary hospital networks across the United States are replacing legacy core needle systems with integrated platforms that reduce procedure time and sampling error rates.
- High-risk patient surveillance protocols:MRI displacement of conventional imaging in hereditary breast cancer screening programs is expanding addressable procedure volumes in academic medical centers.
Market Restraints
- Capital equipment replacement cycles:Extended depreciation schedules for mammography and ultrasound systems in community hospital settings delay platform upgrade decisions beyond typical seven-year windows.
- Reimbursement compression:CMS determinations for image-guided breast procedures create pricing ceilings that constrain hospital capital allocation toward premium integrated systems.
- Radiologist workforce density:Geographic maldistribution of breast imaging specialists limits throughput capacity for advanced diagnostic protocols in non-metropolitan service areas.
Strategic Opportunities
- Artificial intelligence lesion detection:FDA guidance on Software as a Medical Device classification for AI-enabled algorithms creates first-mover advantage for vendors with validated training datasets.
- Specialty clinic expansion:Freestanding breast imaging centers in Texas, Florida, and California are deploying compact ultrasound-biopsy systems to capture patient volumes outside hospital networks.
- HIPAA-compliant multicenter data sharing:Cross-institutional imaging repositories enable pooled clinical research that accelerates evidence generation for novel diagnostic indications.
Industry Challenges
- Interoperability with legacy PACS:Hospital IT departments face integration complexity when connecting new biopsy platforms to decade-old picture archiving systems without native DICOM conformance.
- AI algorithm validation timelines:Retrospective clinical studies required for FDA submission of machine learning-based lesion detection extend development cycles by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraductal Papilloma Market |
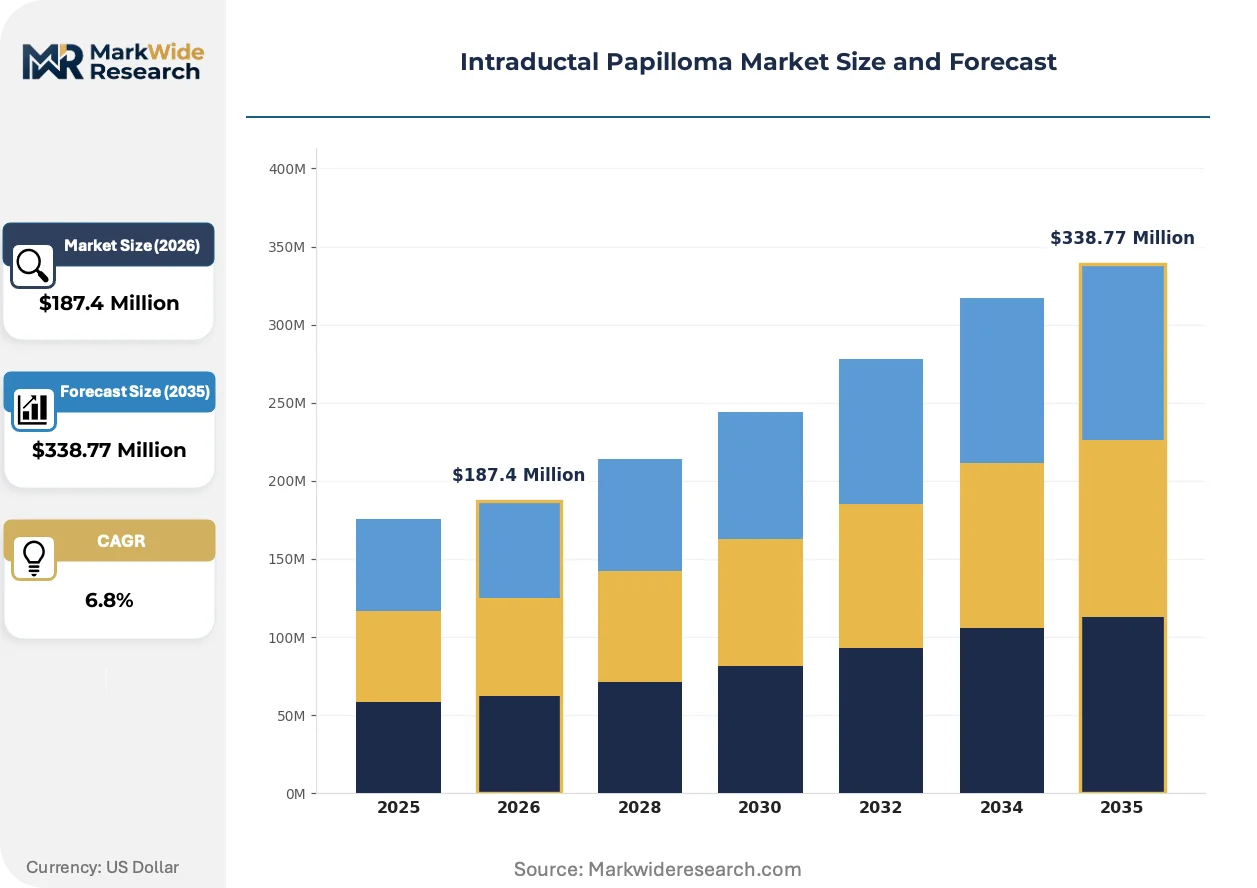
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical, Diagnostic Imaging, Biopsy Devices, Therapeutics End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutions Application: Breast Cancer Diagnosis, Surgical Procedures, Patient Monitoring, Clinical Research Technology: Ultrasound, MRI, CT Scanning, Endoscopy |
| Companies Covered | Johnson & Johnson, Boston Scientific, Pfizer Inc., Siemens Healthineers, Hologic, Inc., Bayer AG, Medtronic, Olympus Corporation, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraductal Papilloma Market Strategic Shifts
Digital pathology workflows and machine learning augmentation are restructuring how intraductal papilloma specimens are analyzed, shifting diagnostic value from hardware placement toward software-enabled interpretation services.
Contrast-enhanced spectral mammography is integrating iodine-based lesion characterization into routine screening protocols. Academic medical centers in Massachusetts and New York are piloting dual-energy systems that reduce false-positive biopsy rates. This technology is integrating quantitative perfusion mapping with conventional architectural distortion assessment.
FDA guidance documents on AI-enabled medical devices are clarifying predicate device pathways for lesion detection algorithms. Device manufacturers must now submit standalone performance validation rather than piggybacking on parent imaging system clearances. Breast imaging subspecialists in tertiary hospitals are demanding transparency in algorithm training datasets before clinical adoption.
Hospital purchasing committees are unbundling service contracts from capital equipment acquisitions. Independent service organizations are capturing preventive maintenance revenue previously retained by original equipment manufacturers. This shift is most visible in California and Illinois health systems where total cost of ownership modeling dominates procurement decisions.
Intraductal Papilloma Market Segmentation
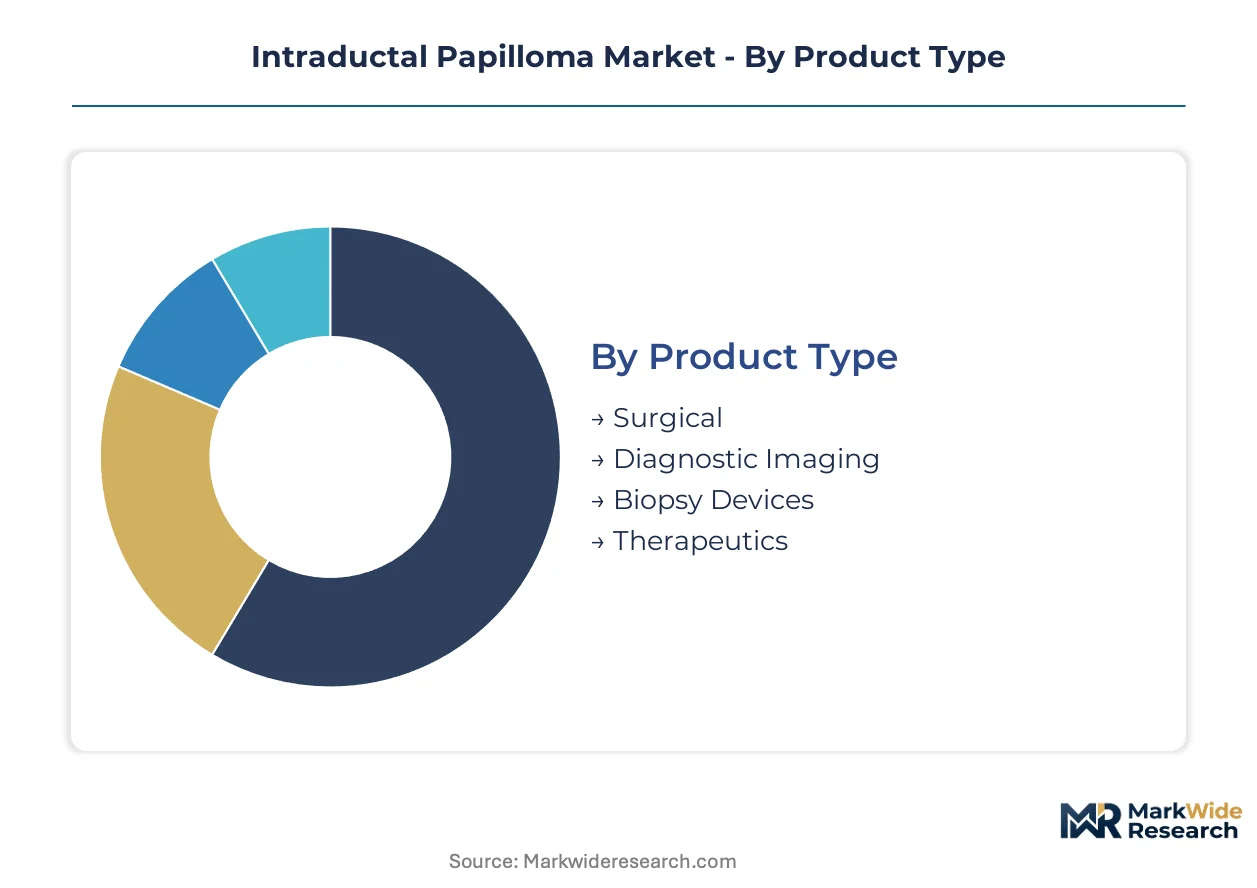
Intraductal papilloma diagnostic workflows fragment across four distinct axes, each governed by different procurement timelines and reimbursement logic. Product type segmentation determines capital allocation cycles, while end-user stratification reveals where integrated platform adoption outpaces standalone device replacement.
Product Type:
Supply concentration clusters around integrated imaging-biopsy platforms that bundle hardware, software, and service contracts into single-vendor relationships.
- Diagnostic Imaging:Ultrasound and mammography systems with lesion characterization software dominate hospital capital budgets through recurring replacement cycles and upgrade revenue streams. Tertiary hospital networks in the United States concentrate procurement authority for these platforms within centralized imaging departments that negotiate enterprise-wide service agreements.
- Biopsy Devices:Vacuum-assisted and core needle platforms are displacing legacy surgical excision for initial tissue acquisition. Specialty clinics across Texas and Florida deploy compact ultrasound-guided systems to capture outpatient volumes outside hospital networks, with device selection driven by procedure throughput targets and disposable consumable economics.
- Surgical:Excisional biopsy and ductoscopy instruments serve definitive therapeutic intervention when imaging suggests malignant transformation. Demand concentrates in academic medical centers with dedicated breast surgery divisions.
- Therapeutics:Pharmacological management of associated symptoms represents a narrow segment with limited device integration potential.
Today's leader: Diagnostic Imaging. Tomorrow's challenger: Biopsy Devices.
End User:
Procurement authority is migrating from hospital imaging departments toward freestanding specialty clinics that optimize throughput through dedicated patient flows.
- Hospitals:Tertiary hospital networks anchor demand for premium integrated platforms that support multidisciplinary tumor board workflows. Capital allocation decisions hinge on CMS reimbursement determinations for image-guided breast procedures and seven-year depreciation schedules for mammography systems.
- Specialty Clinics:Freestanding breast imaging centers in California, Illinois, and New York metropolitan areas deploy compact diagnostic systems to capture screening volumes outside hospital networks. These facilities prioritize equipment with rapid patient turnaround and minimal radiologist staffing requirements.
- Diagnostic Laboratories:Pathology services for intraductal papilloma specimen analysis operate on fee-for-service contracts with referring physicians.
- Research Institutions:Academic medical centers pilot novel imaging modalities and AI-enabled lesion detection algorithms under FDA investigational device exemptions.
Procurement gravity centers on Hospitals. Volume expansion accelerates fastest at Specialty Clinics.
Application:
Clinical utility stratifies by whether the intervention aims to rule out malignancy or guide definitive therapy.
- Breast Cancer Diagnosis:Differentiation of benign intraductal papilloma from ductal carcinoma in situ drives the majority of imaging-guided procedures. Massachusetts General Hospital and Memorial Sloan Kettering anchor validation studies for novel diagnostic protocols that filter down to community practice.
- Surgical Procedures:Definitive excision following core needle biopsy confirmation occupies operating room capacity in hospital-based breast centers.
- Patient Monitoring:Surveillance protocols for high-risk patients with hereditary breast cancer syndromes expand MRI procedure volumes.
- Clinical Research:Multicenter imaging repositories enable pooled analysis of intraductal papilloma natural history under HIPAA-compliant data sharing frameworks.
Revenue concentration sits with Breast Cancer Diagnosis. Procedure volume expansion favors Patient Monitoring.
Technology:
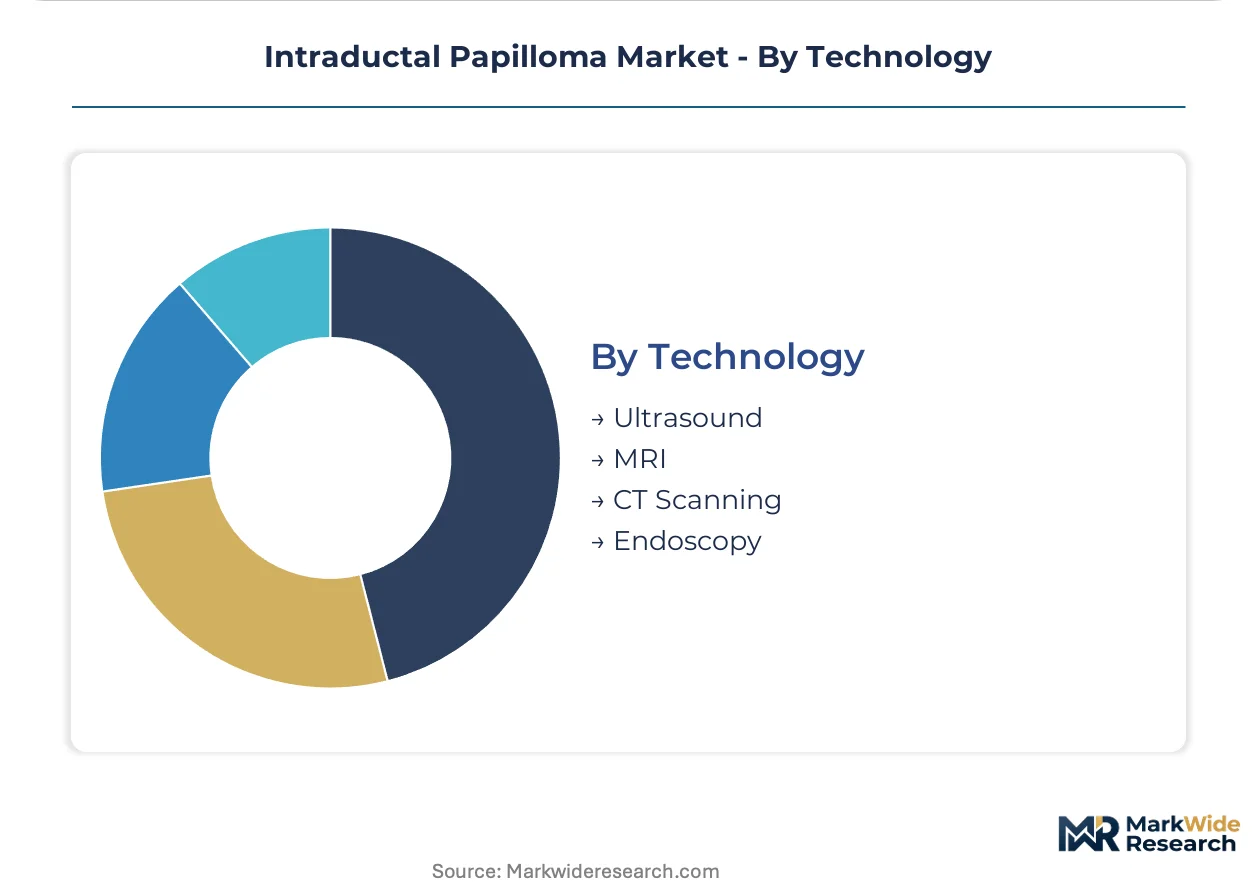
Modality selection follows risk stratification, with ultrasound anchoring initial workup and MRI displacing conventional imaging in surveillance protocols.
- Ultrasound:First-line lesion characterization for palpable and mammographically detected abnormalities. Community hospital adoption of handheld portable systems extends diagnostic access to non-metropolitan service areas where radiologist workforce density limits throughput.
- MRI:Contrast-enhanced breast MRI dominates high-risk patient surveillance and preoperative staging for known malignancies. Academic medical centers pilot abbreviated MRI protocols that reduce scan time and cost to expand screening eligibility.
- CT Scanning:Limited role in intraductal papilloma-specific diagnosis; occasional use for metastatic workup when malignancy is confirmed.
- Endoscopy:Ductoscopy enables direct visualization of intraductal lesions but requires specialized operator training that restricts deployment to tertiary referral centers.
Ultrasound commands installed base. MRI claims steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major metropolitan cancer centers in the United States concentrate procurement authority for intraductal papilloma diagnostic platforms. Hospital networks in Massachusetts, Texas, and California anchor demand for integrated imaging-biopsy systems. Regulatory frameworks and reimbursement policies in select countries shape capital allocation patterns across developed markets.
United States
Tertiary hospital networks clustered around Boston, Houston, and Los Angeles drive demand for MRI-guided biopsy platforms. FDA premarket notification requirements under 21 CFR 892 compress vendor clearance timelines while elevating technical performance standards. Massachusetts General Hospital and Memorial Sloan Kettering anchor validation studies for novel diagnostic protocols that diffuse to community practice.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia pilot contrast-enhanced spectral mammography systems for lesion characterization. EU Medical Device Regulation (MDR) compliance requirements extend certification timelines for breast biopsy devices entering the European market. The Munich and Berlin hospital clusters concentrate procurement authority for premium integrated diagnostic platforms.
United Kingdom
NHS England screening program expansions drive demand for ultrasound-guided vacuum-assisted biopsy systems in London and Southeast England. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines for device manufacturers. The Cambridge and Oxford academic medical centers anchor clinical research for AI-enabled lesion detection algorithms.
Japan
PMDA accelerated approval pathways for breakthrough medical devices attract vendors with novel biopsy platform innovations. Tokyo and Osaka metropolitan hospital networks concentrate demand for compact diagnostic systems serving aging patient populations. METI funding programs for digital health infrastructure support AI integration into breast imaging workflows.
Australia
TGA priority review pathways for breast cancer diagnostic devices compress market entry timelines for innovative biopsy systems. Sydney and Melbourne specialist breast imaging centers deploy compact ultrasound platforms to capture outpatient screening volumes. Medicare reimbursement determinations for image-guided procedures influence hospital capital allocation toward integrated systems.
Intraductal Papilloma Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to bundle imaging hardware with software-enabled interpretation services. The vendor base stratifies across three tiers: multinational conglomerates with full diagnostic portfolios, mid-cap specialists in biopsy device innovation, and regional distributors serving non-metropolitan service areas. Two archetypes anchor competitive positioning: integrated platform providers capturing hospital enterprise contracts, and focused biopsy specialists penetrating specialty clinic channels. Portfolio diversification and technology licensing represent the dominant competitive moves, with vendors seeking AI algorithm partnerships to differentiate hardware offerings.
Among diversified health technology conglomerates, Siemens Healthineers and Hologic, Inc. exemplify the integrated platform archetype, anchoring hospital procurement relationships through bundled imaging-biopsy-service contracts. Boston Scientific occupies a position within the interventional therapeutics tier, with its corporate structure reflecting a focused specialization in minimally invasive surgical technologies. These three entities collectively represent the competitive spectrum spanning diagnostic imaging dominance through therapeutic intervention capability.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Boston Scientific |
| Pfizer Inc. |
| Siemens Healthineers |
| Hologic, Inc. |
| Bayer AG |
| Medtronic |
| Olympus Corporation |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive service integration by original equipment manufacturers anchors both supply positioning and pricing power in the intraductal papilloma diagnostic market. Hologic and Siemens Healthineers bundle imaging hardware with preventive maintenance contracts that lock hospitals into multi-year pricing schedules, while independent service organizations in California and Illinois erode this control through unbundled aftermarket offerings.
Pricing Analysis
Input-cost pass-through from rare-earth magnet and semiconductor component inflation is compressing margins on MRI-guided biopsy platforms while elevating price points for ultrasound systems. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center contracts from community hospital procurements and specialty clinic deployments. Pricing pressure stems from CMS reimbursement compression on image-guided breast procedures. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while tertiary networks prioritize technical performance over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific shipping lanes is elevating landed costs for vacuum-assisted biopsy consumables manufactured in China and South Korea. Component sourcing draws from Japanese precision optics for ductoscopy systems, German sensor arrays for spectral mammography, and Taiwanese semiconductor foundries for imaging processing units. Single-source vulnerability concentrates in MRI magnet production anchored to Siemens Healthineers' Erlangen facility. Distribution runs through hospital purchasing committees and GPO contracts that consolidate procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intraductal papilloma market functions as a regulatory compounder where FDA 21 CFR 892 pathway tightening accelerates hospital capital replacement cycles. Pre-market notification requirements for breast biopsy devices create structural demand for next-generation platforms that preempt compliance risk.
For Market Incumbents: Extend AI-enabled lesion detection software capabilities to defend against emerging digital health entrants. Deepen backward integration into imaging sensor manufacturing to capture margin compression from semiconductor supply constraints. Anchor hospital enterprise contracts through bundled service agreements that independent service organizations cannot replicate.
For New Entrants and Emerging Players: Launch via compact ultrasound-biopsy systems targeting freestanding specialty clinics in Texas and Florida metropolitan corridors. Specialty clinic channels offer lowest competitive density against integrated platform incumbents. Prioritize rapid patient throughput specifications and minimal radiologist staffing requirements in product design.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap biopsy device specialists because hospital procurement consolidation favors vendors with full imaging-to-intervention portfolios. Five-to-ten year viability hinges on FDA Software as a Medical Device clearance capabilities. Monitor PMDA breakthrough device designations as signal for platform technology inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for vacuum-assisted biopsy platforms under tightened 21 CFR 892 requirements. |
| Hospital System Partnership | Locks procurement authority through enterprise-wide imaging-biopsy-service contracts with tertiary networks. |
| Software Companion Development | Positions AI lesion detection algorithms for SaMD classification ahead of FDA guidance finalization. |
| Reimbursement Strategy | Aligns platform pricing with CMS determinations for image-guided breast procedure coverage. |
| CE Marking Pathway | Opens EU MDR-compliant market access for contrast-enhanced spectral mammography systems. |
Study Parameters
Direct dialogue with breast imaging subspecialists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and academic medical center pilot study disclosures. Bottom-up and top-down triangulation cross-checked equipment placement data against procedure volume estimates.
Analytical lens combined bottom-up vendor shipment tracking with top-down hospital capital expenditure modeling across the projection horizon. Segmentation dimensions spanned product type, end-user archetype, application purpose, and imaging modality technology. CAGRs were derived from fitted growth curves anchored to replacement cycle timing and regulatory milestone impacts. Forecast inputs incorporated radiologist workforce density constraints and AI algorithm validation timeline uncertainties.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance acceleration or reimbursement policy reversal scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Acute Lymphoblastic Leukemia Therapeutics Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market