
 Global Air Cooled Condenser Market | 2026-2036
Global Air Cooled Condenser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Cooled Condenser Market Analysis
Aluminum fin stock is shifting toward enhanced corrosion-resistant alloys in air cooled condenser manufacturing, reducing total installed weight and improving thermal transfer coefficients. SPG Dry Cooling leverages its European engineering base to sustain premium positioning in large-scale power projects. Shuangliang Group anchors cost-competitive production through integrated aluminum supply chains in Jiangsu province. Thermax dominates the Indian subcontinent with localized fabrication capabilities and aftermarket service networks.
An air cooled condenser is a heat rejection device that condenses exhaust steam from turbines or process vapor into liquid using ambient air as the cooling medium, typically employing finned-tube bundles with forced-draft or induced-draft fans achieving heat duties from 50 MW to 1000 MW. Its primary purpose is to eliminate water consumption in thermoelectric power generation and industrial processes where water scarcity or discharge restrictions apply. Shell & Tube designs occupy the mature utility segment where margin pools have compressed to maintenance and retrofit cycles. Fin Fan configurations lead growth in oil & gas applications across arid basins. Hybrid Systems command premium pricing where ambient temperature swings exceed design thresholds.
The US EPA regulates cooling water intake structures under Section 316(b) of the Clean Water Act, compelling coastal and riverine power plants to evaluate dry cooling retrofits. China's MEE enforces GB standards for thermal power plant water consumption that favor air cooled technology in northern provinces. The EU F-Gas Regulation indirectly shapes condenser demand by restricting synthetic refrigerants in cooling systems. Stakeholders must monitor how carbon border adjustments and water stress indices redirect procurement criteria for new capacity additions.
Market Dynamics
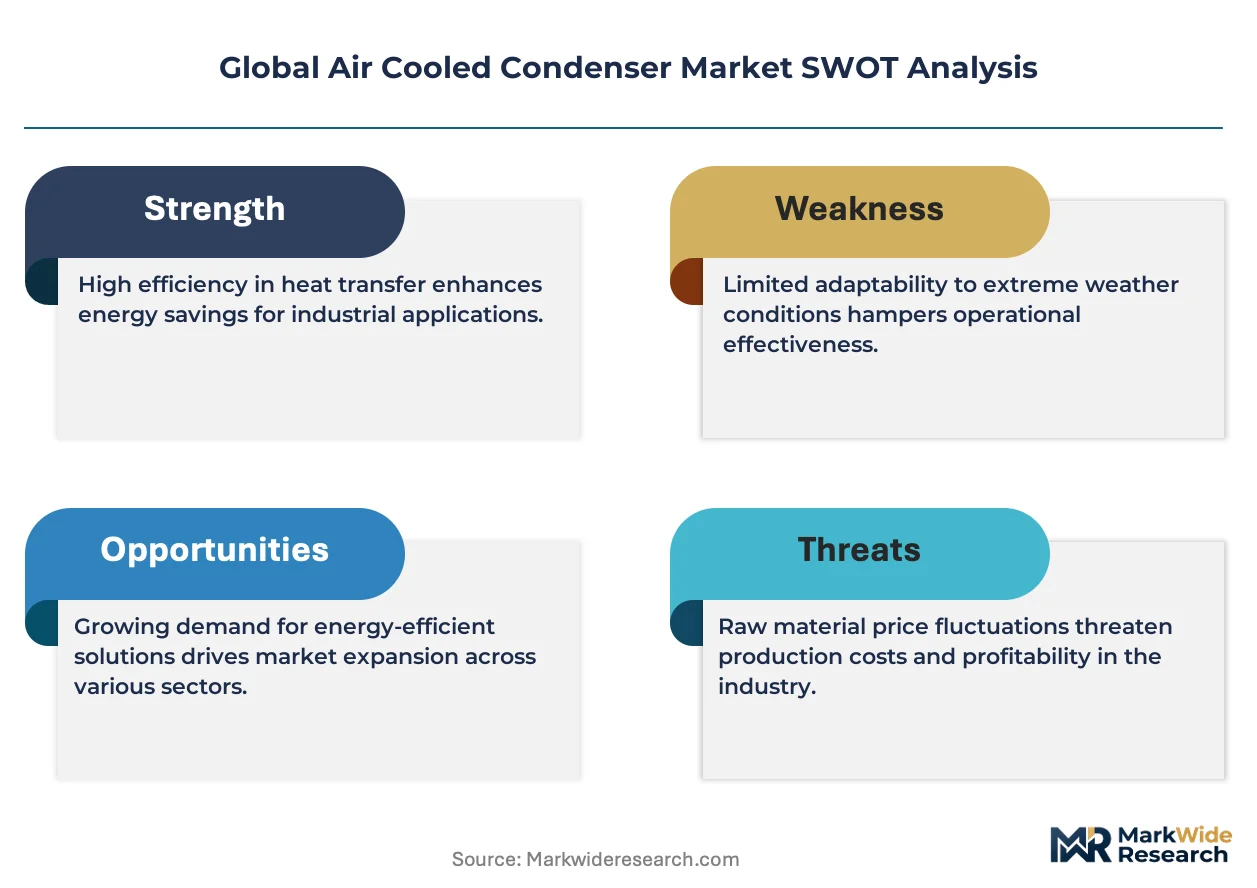
Water stress indices and cooling water discharge restrictions are compressing the addressable market for wet cooling systems while expanding the specification envelope for air cooled alternatives in thermal power generation.
Growth Catalysts
- EPA Section 316(b) Compliance:US coastal and riverine power plants face mandated cooling water intake structure retrofits, accelerating dry cooling evaluations in the Northeast and Great Lakes corridors.
- Aluminum-Lithium Alloy Adoption:Advanced fin stock materials reduce condenser bundle weight by 15-20% while improving thermal conductivity, lowering transport and installation logistics costs for remote site deployments.
- China Northern Province Expansion:GB standards enforcement by MEE restricts water consumption in Inner Mongolia and Shanxi thermal clusters, mandating air cooled systems for new coal and combined-cycle capacity.
Market Restraints
- Aluminum Price Volatility:LME aluminum fluctuations compress fabrication margins and destabilize project quoting cycles for EPC contractors bidding multi-year utility contracts.
- Jiangsu Supply Concentration:Integrated aluminum smelting and fin stock rolling capacity clusters in eastern China create single-source dependency risks for European and North American project developers.
- Ambient Temperature Performance Ceiling:Air cooled condensers experience 8-12% efficiency degradation when dry-bulb temperatures exceed 40°C, limiting dispatch economics in Gulf Cooperation Council thermal markets.
Strategic Opportunities
- Saudi Arabia Industrial Diversification:NEOM and Red Sea Project thermal desalination-power integration schemes specify dry cooling to preserve scarce groundwater reserves, opening premium project pipelines.
- EU F-Gas Regulation Convergence:Synthetic refrigerant phase-down mandates under the EU Green Deal accelerate hybrid air-cooled system adoption in data center and chemical process cooling applications.
- Digital Twin Integration:Real-time performance optimization software layered onto existing condenser infrastructure creates aftermarket service revenue streams independent of new equipment sales.
Industry Challenges
- Thermal-Hydraulic Modeling Expertise Gap:Utilities lack in-house capability to validate air cooled condenser performance guarantees against actual operating conditions, forcing reliance on vendor-provided simulation tools.
- Legacy Steam Turbine Interface Complexity:Retrofit projects require custom exhaust hood modifications and vacuum system rebalancing, extending commissioning timelines and warranty dispute exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Cooled Condenser Market |
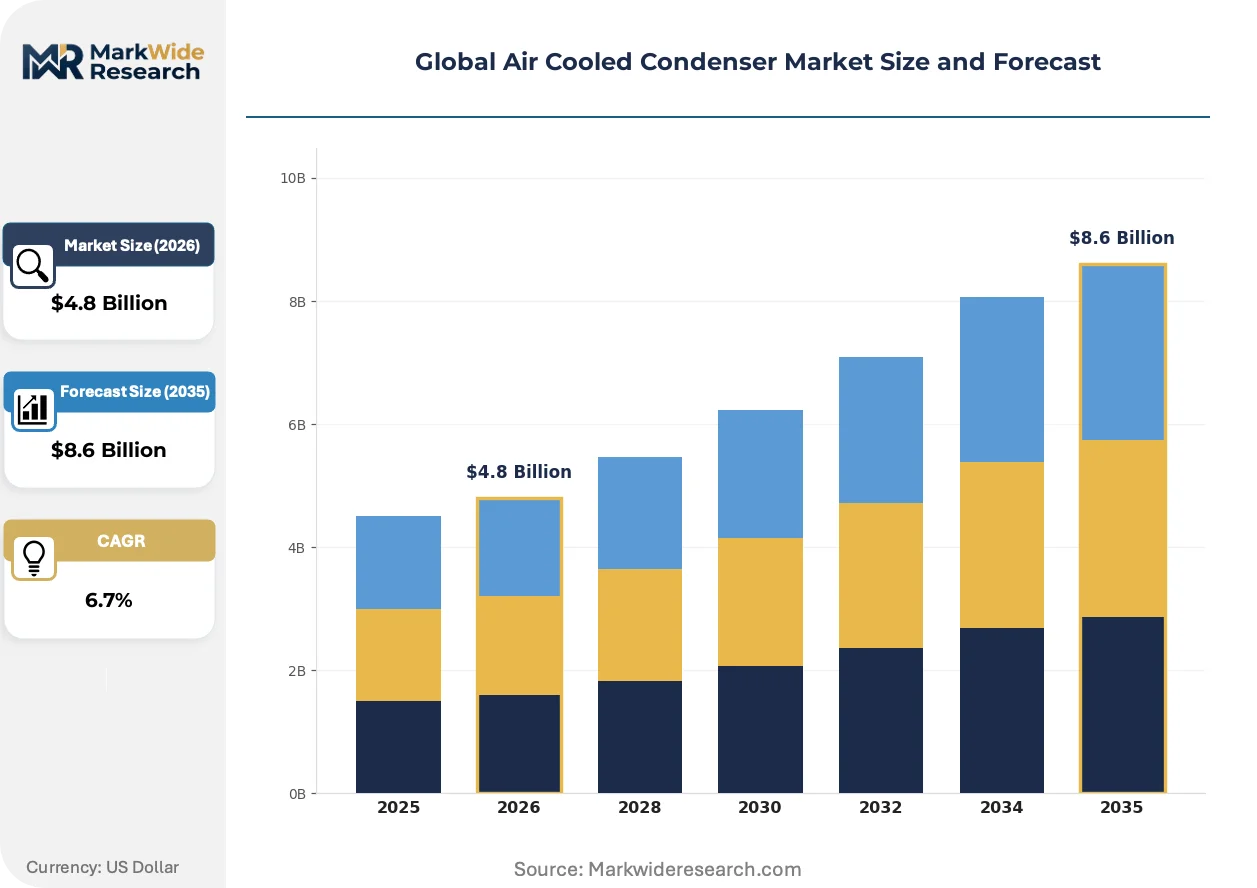
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
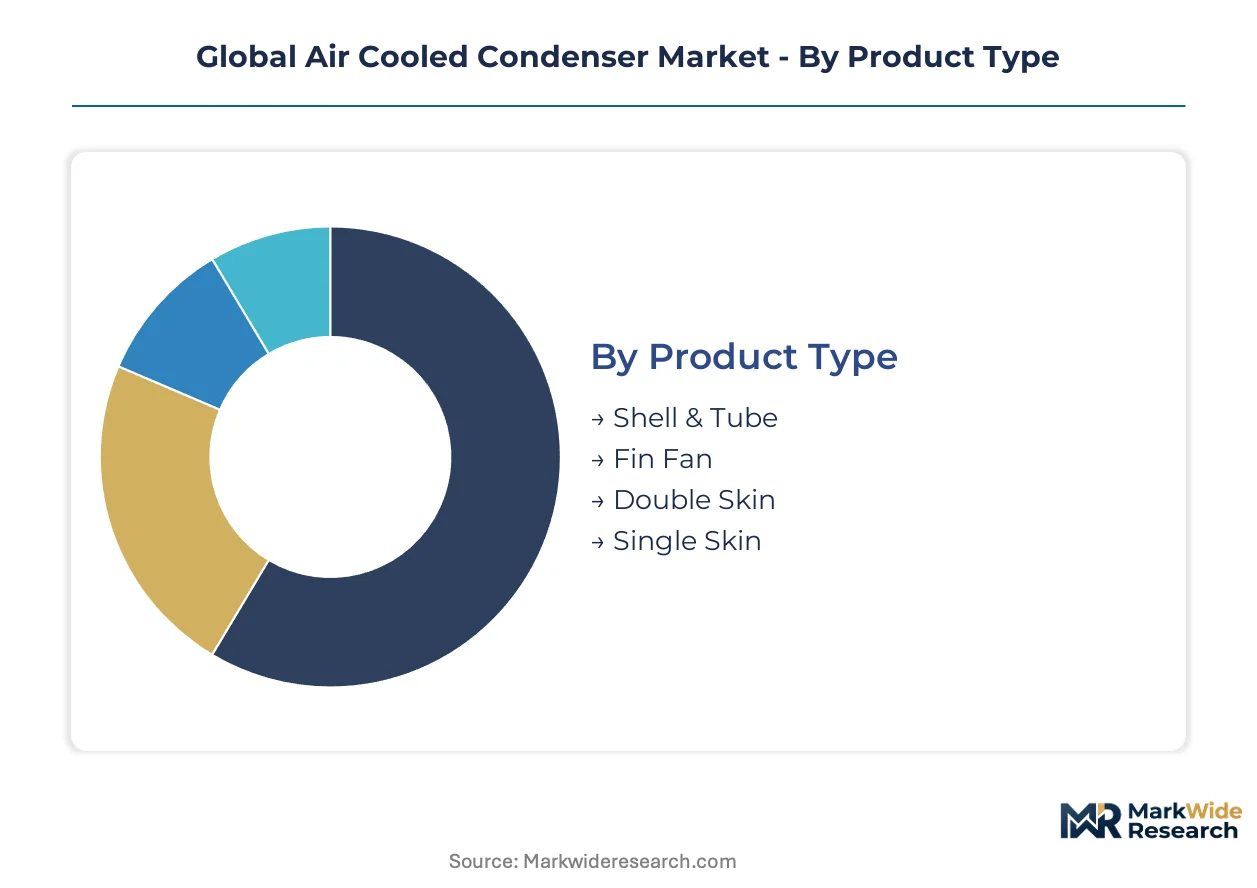
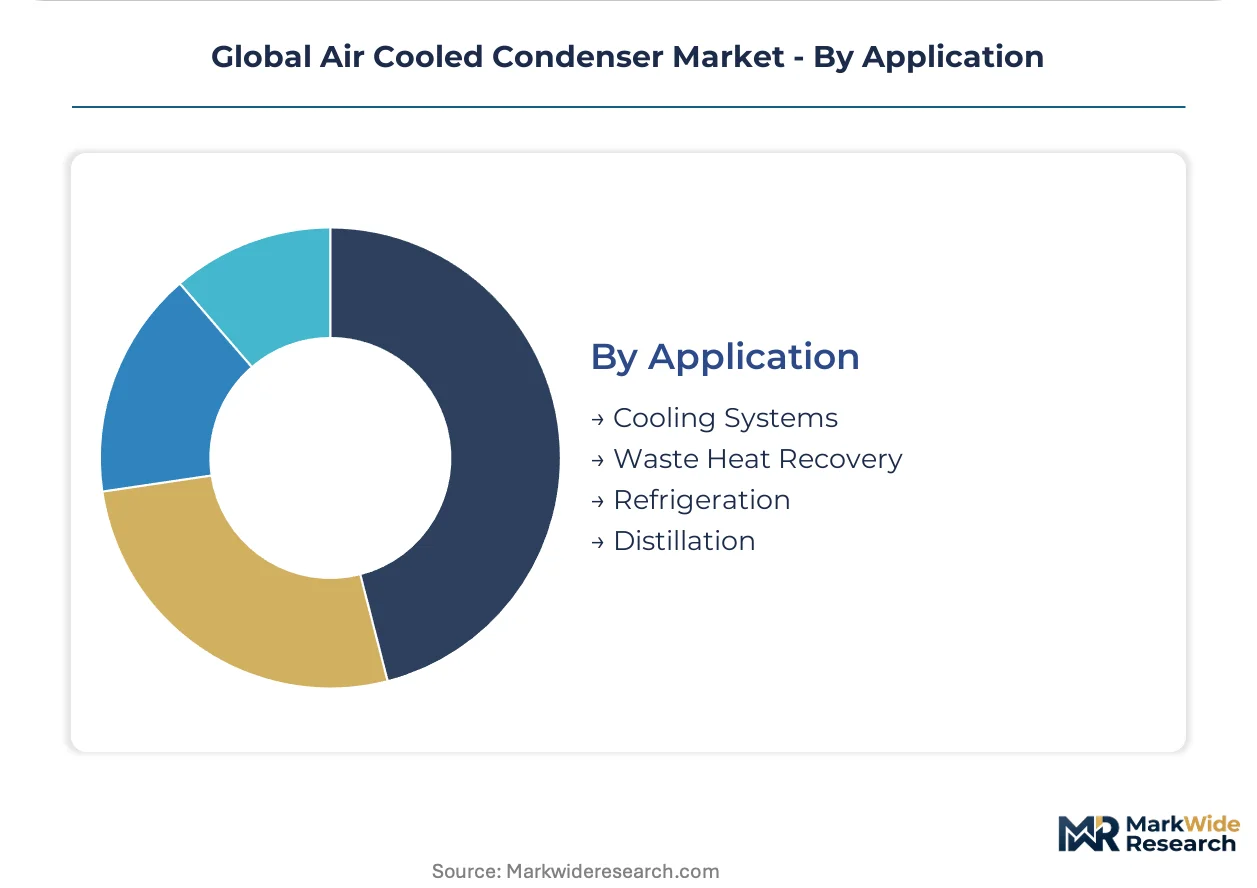
| Segmentation | Product Type: Shell & Tube, Fin Fan, Double Skin, Single Skin End User: Power Generation, Oil & Gas, Chemical Processing, Food & Beverage Technology: Direct Air Cooled, Indirect Air Cooled, Hybrid Systems, Heat Recovery Application: Cooling Systems, Waste Heat Recovery, Refrigeration, Distillation |
| Companies Covered | Holtec International, EVAPCO Inc., SPG Dry Cooling, Shuangliang Group, Shouhang High-Tech Energy Technology, SPX Cooling Technologies, Longhua Technology Group (Luoyang) Co., Ltd, Thermax, Enexio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Cooled Condenser Market Emerging Trajectories
Modular fabrication methods and predictive maintenance architectures are compressing project delivery cycles while extending operational lifespans in harsh ambient environments.
Microchannel aluminum tubing is unifying heat transfer and structural functions in finned-tube bundles, eliminating separate header welding operations. Saudi Aramco and ADNOC process cooling divisions specify microchannel configurations for Red Sea and Rub al Khali gas processing trains. This unifying architecture reduces field assembly labor by 30% and enables containerized shipment of pre-tested modules.
China's MEE is tightening GB 13223 emission and water consumption standards for thermal power plants, forcing northern provincial operators to pre-commit dry cooling in environmental impact assessments. Shanxi and Shaanxi provincial environmental bureaus now reject wet cooling proposals for coal units above 600 MW. Equipment vendors are responding with standardized 1000 MW air cooled condenser platforms certified to MEE Type Approval.
Long-term service agreements are displacing transactional spare parts purchasing in Middle Eastern and Indian utility fleets. SPG Dry Cooling and Hamon now bundle 15-year thermal performance guarantees with initial equipment supply, transferring operational risk from plant operators to OEM balance sheets. This contracting shift is most advanced in Saudi Arabia's SEC and India's NTPC tender frameworks.
Global Air Cooled Condenser Market Segmentation
Air cooled condenser procurement hinges on thermal duty specifications, ambient climate conditions, and water availability constraints that vary sharply across power generation, oil and gas, and industrial process applications. Buyers evaluate capital expenditure against lifecycle thermal performance, particularly in regions where cooling water discharge restrictions or groundwater scarcity elevate dry cooling economics.
Product Type:
Capital intensity and site-specific thermal duty requirements drive product selection, with utilities prioritizing proven reliability for baseload operations while industrial buyers optimize for footprint and modularity.
- Shell & Tube:Mature utility-grade configuration employing cylindrical pressure vessels with internal tube bundles handling exhaust steam condensation at 50-1000 MW thermal duties. Demand concentrates in US Great Lakes and Northeast coastal corridors where EPA Section 316(b) compliance deadlines force wet-to-dry cooling retrofits at legacy coal and nuclear stations.
- Fin Fan:Finned-tube bundles with forced-draft or induced-draft fans dominate oil and gas process cooling in arid basins. Aramco and ADNOC process cooling divisions specify these configurations for Rub al Khali and Red Sea gas processing trains where ambient temperatures exceed 40°C design thresholds.
- Double Skin:Dual-wall construction provides containment redundancy for hazardous vapor streams in chemical processing applications.
- Single Skin:Lightweight construction reduces installed cost for non-hazardous refrigeration and HVAC applications.
Shell & Tube leads on scale; Fin Fan leads on momentum.
End User:
Water stress indices and regulatory enforcement intensity create divergent specification requirements across thermal power, hydrocarbon processing, and manufacturing verticals.
- Power Generation:Thermoelectric utilities deploying air cooled condensers to eliminate cooling water consumption in coal, combined-cycle, and concentrated solar thermal plants. China's MEE GB standards enforcement in Shanxi and Inner Mongolia provinces mandates dry cooling for all new coal units above 600 MW capacity.
- Oil & Gas:Upstream and midstream operators specify modular dry cooling for gas processing, LNG liquefaction, and refining applications in water-scarce basins. Saudi Arabia's NEOM and Red Sea Project thermal desalination-power integration schemes specify dry cooling to preserve groundwater reserves.
- Chemical Processing:Process cooling for exothermic reactions and solvent recovery operations where discharge restrictions apply.
- Food & Beverage:Hygienic refrigeration and process cooling applications with moderate thermal duties.
Power Generation commands the largest installed base; Oil & Gas exhibits the steepest expansion trajectory.
Technology:
Thermodynamic efficiency trade-offs against ambient temperature volatility shape technology selection, with premium hybrid configurations gaining traction in climates with extreme seasonal swings.
- Direct Air Cooled:Exhaust steam passes directly through finned-tube bundles with ambient air as sole cooling medium, achieving simplest configuration and lowest operating cost. Dominates Chinese northern province thermal clusters where MEE water consumption restrictions are most stringent.
- Indirect Air Cooled:Closed-loop water circulation through surface condensers and dry cooling towers provides freeze protection and improved vacuum stability. Preferred for combined-cycle plants in continental climates with sub-zero winter minimums.
- Hybrid Systems:Parallel wet-dry operation commands premium pricing where ambient temperature swings exceed single-mode design thresholds.
- Heat Recovery:Cogeneration configurations capture low-grade waste heat for district heating or industrial process preheating.
Direct Air Cooled dominates unit volume; Hybrid Systems capture the highest margin per megawatt.
Application:
Process integration requirements and heat sink availability determine whether condensers serve primary cooling, energy recovery, or purification functions.
- Cooling Systems:Primary heat rejection for steam turbine exhaust and process vapor condensation across power and industrial applications. Represents the foundational use case driving standardized platform development.
- Waste Heat Recovery:Cogeneration and bottoming cycle applications capturing thermal energy for process heating or power generation augmentation. Expanding in EU industrial decarbonization schemes under Green Deal funding mechanisms.
- Refrigeration:Condensing duties for industrial cold chain and chemical process cooling.
- Distillation:Overhead vapor condensation in petrochemical and specialty chemical separation trains.
Cooling Systems anchors current procurement volumes; Waste Heat Recovery is gaining share fastest in EU sustainability-driven retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shuangliang Group's Jiangsu manufacturing cluster anchors global air cooled condenser fabrication capacity, with procurement patterns diverging sharply across water-stressed thermal corridors and regulatory enforcement zones.
United States
Great Lakes and Northeast coastal utilities face EPA Section 316(b) compliance deadlines for cooling water intake structure retrofits. The agency's 2014 rule implementation is forcing dry cooling evaluations at legacy coal and nuclear stations in Illinois, Ohio, and New York. Chicago-based engineering procurement contractors are bundling air cooled condenser packages with turbine exhaust hood modifications for 600 MW+ retrofits.
China
Inner Mongolia and Shanxi thermal clusters drive procurement volume under MEE GB 13223 water consumption enforcement. The ministry's Type Approval certification now mandates dry cooling for all new coal units above 600 MW capacity in northern provinces. Shouhang High-Tech Energy Technology anchors fabrication capacity in Beijing-Tianjin-Hebei corridor for standardized 1000 MW platforms.
Saudi Arabia
NEOM and Red Sea Project thermal desalination-power integration schemes specify dry cooling to preserve scarce groundwater reserves. The kingdom's SEC tender frameworks now bundle 15-year thermal performance guarantees with initial equipment supply. Eastern Province gas processing trains in Rub al Khali basin specify modular configurations for ambient temperatures exceeding 40°C design thresholds.
India
Maharashtra and Gujarat thermal utilities expand dry cooling adoption under CEA water consumption guidelines for new coal and combined-cycle capacity. Thermax dominates localized fabrication through captive facilities in Pune and Ahmedabad corridors. NTPC tender frameworks are shifting from transactional spare parts purchasing toward long-term service agreements with performance guarantees.
Germany
Rhineland and Lusatia lignite regions evaluate dry cooling retrofits under EU F-Gas Regulation convergence with national coal phase-out timelines. The ECHA restriction roadmap on synthetic refrigerants indirectly shapes condenser demand in chemical process cooling applications. SPG Dry Cooling leverages its European engineering base to sustain premium positioning in utility-scale projects.
Global Air Cooled Condenser Market Vendor Landscape
Long-term service agreements dominate the current landscape as competitive differentiation shifts from equipment sales to operational risk transfer. The vendor base stratifies between integrated aluminum supply chain operators, European engineering specialists, and regional fabrication champions. Three archetypes define positioning: scale-driven platform standardizers, premium-tier performance guarantors, and cost-competitive modular fabricators. Portfolio diversification into digital twin services and hybrid system architectures represents the dominant competitive move alongside geographic expansion into Middle Eastern utility frameworks.
Among Chinese integrated manufacturers, Shuangliang Group and Shouhang High-Tech Energy Technology exemplify the scale-driven archetype through captive aluminum fin stock rolling and standardized platform certification. SPG Dry Cooling occupies a position within the premium-tier vector, leveraging European engineering heritage for large-scale power project positioning. Thermax represents the regional fabrication champion model, anchoring Indian subcontinent presence through localized manufacturing and aftermarket service density.
| Leading Market Players |
|---|
| Holtec International |
| EVAPCO Inc. |
| SPG Dry Cooling |
| Shuangliang Group |
| Shouhang High-Tech Energy Technology |
| SPX Cooling Technologies |
| Longhua Technology Group (Luoyang) Co., Ltd |
| Thermax |
| Enexio |
| Others |
Supply Flow & Price Mechanics
LME aluminum spot pricing cascades through air cooled condenser manufacturing tiers, compressing fabrication margins for EPC contractors bidding multi-year utility contracts while amplifying cost advantages for integrated producers with captive fin stock rolling capacity.
Pricing Analysis
Input-cost pass-through dominates project-based contract structures where aluminum fin stock constitutes the largest variable cost component. Pricing stratifies across premium European engineering tiers, standardized Chinese platform offerings, and regional fabrication champions competing on localized delivery. Cost compression in the mid-market tier is intensifying because LME volatility destabilizes multi-year quoting cycles. Independent EPC contractors exhibit highest price sensitivity, while national utilities under MEE or EPA mandates absorb premium positioning for guaranteed thermal performance.
Supply Chain Analysis
Domestic-content mandates under China's GB certification framework and India's CEA procurement guidelines are reshaping sourcing patterns toward localized fabrication clusters. Manufacturing gravity centers on China, India, and Germany, with Jiangsu province anchoring integrated aluminum smelting and fin stock rolling. The supply chain draws from primary aluminum ingots, microchannel tubing alloys, and forced-draft fan assemblies. Single-source vulnerability concentrates in eastern China's aluminum processing corridor. Distribution runs through EPC contractor consortiums and direct OEM relationships with national utility frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air cooled condenser market functions as a regulatory compounder where EPA Section 316(b) compliance deadlines and China's MEE GB 13223 enforcement create non-discretionary procurement cycles for thermal power operators.
For Market Incumbents: Cement market position through captive aluminum supply chain control and MEE Type Approval certification for standardized 1000 MW platforms. SPG Dry Cooling and Shuangliang Group anchor defensive positioning by bundling 15-year thermal performance guarantees that transfer operational risk from plant operators. Threats from modular microchannel fabricators require aftermarket service network densification in Middle Eastern and Indian utility corridors.
For New Entrants and Emerging Players: Begin with digital twin integration services layered onto existing condenser infrastructure, creating recurring revenue independent of equipment sales cycles. White-space opportunity concentrates in hybrid system architectures for Gulf Cooperation Council markets where ambient temperature swings exceed single-mode design thresholds. NEOM and Red Sea Project thermal desalination-power integration schemes offer premium project pipelines with performance-guarantee contracting frameworks.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabrication champions possessing localized MEE or EPA certification pathways and dense aftermarket service networks. Long-term viability hinges on exposure to water-stressed thermal corridors with enforced consumption restrictions. Acquisition target archetype: mid-scale fabricators with CEA compliance in Maharashtra and Gujarat or MEE Type Approval in Shanxi corridor. Watch for carbon border adjustment mechanism implementation as demand inflection trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Fin Stock | Shuangliang Group's Jiangsu smelting-rolling integration insulates margin from LME volatility. |
| Digital Twin Platform Development | Real-time performance optimization creates aftermarket revenue independent of new equipment sales. |
| Hybrid System Architecture Certification | EU F-Gas Regulation convergence accelerates premium positioning in data center cooling applications. |
| Long-term Service Agreement Bundling | Saudi SEC and Indian NTPC frameworks now mandate 15-year thermal performance guarantees. |
| Microchannel Modular Fabrication | Containerized pre-tested modules reduce field assembly labor for Aramco Red Sea gas processing trains. |
Methodological Framework
Direct dialogue with EPC procurement directors, utility planning officers, aluminum supply chain managers, and aftermarket service heads grounded the qualitative foundation. Secondary validation drew from EPA Section 316(b) implementation records, MEE GB 13223 Type Approval databases, EIA thermal power plant cooling system disclosures, and customs trade data for aluminum fin stock flows. Bottom-up project pipeline assessment triangulated against top-down regulatory mandate quantification.
Bottom-up modeling aggregated individual project announcements across EPA compliance corridors, MEE enforcement zones, and GCC diversification schemes. Segmentation dimensions spanned product configuration, end-use vertical, cooling technology architecture, and regional regulatory framework. CAGRs were derived from installation run-rate projections against mandated retrofit deadlines. Forecast inputs incorporated aluminum price scenario bands and ambient temperature performance degradation curves.
Several conditions sit outside the modeled scope, including unannounced regulatory deadline extensions, breakthroughs in wet cooling water treatment technologies, and geopolitical disruptions to aluminum supply chains. Forecasts reflect documented assumptions about enforcement continuity and commodity price bands. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Thawing System Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Solar Refrigerators Market