
 South America CNG and LPG Vehicle Market | 2026-2036
South America CNG and LPG Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
South America CNG and LPG Vehicle Market Analytics
Dealership networks across Brazil and Argentina is fragmenting as fleet buyers and independent conversion shops bypass traditional channels for direct retrofit contracts. Fiat dominates factory-installed CNG passenger car supply through its Brazilian manufacturing base. BRC Gas Equipment anchors aftermarket conversion kit distribution with dense service center coverage across the Southern Cone. Landi Renzo competes through specialized dual-fuel system integration for heavy commercial vehicles.
CNG and LPG vehicles utilize compressed or liquefied petroleum gas stored in high-pressure cylinders ranging from 200 to 250 bar, feeding modified internal combustion engines through dedicated fuel injection or mixer-based delivery systems designed to reduce particulate emissions and lower per-kilometer fuel expenditure. Passenger cars lead unit volume through factory-fit CNG options, while commercial trucks generate the strongest margin pools due to higher conversion values and recurring maintenance contracts. The dual-fuel engine configuration segment is expanding fastest as operators seek operational flexibility between diesel and gas modes during price volatility.
ANVISA in Brazil and Argentina's national transport safety authority enforce cylinder recertification protocols and installation technician licensing that directly shape aftermarket service capacity and conversion cost structures. Brazil's PROCONVE standards and Argentina's GNC incentive frameworks collectively push OEMs toward cleaner-burning factory configurations while restricting uncertified retrofit imports. Stakeholders must monitor pending regulatory harmonization talks between Mercosur members that could unify conversion standards or fragment compliance costs across borders.
Market Dynamics
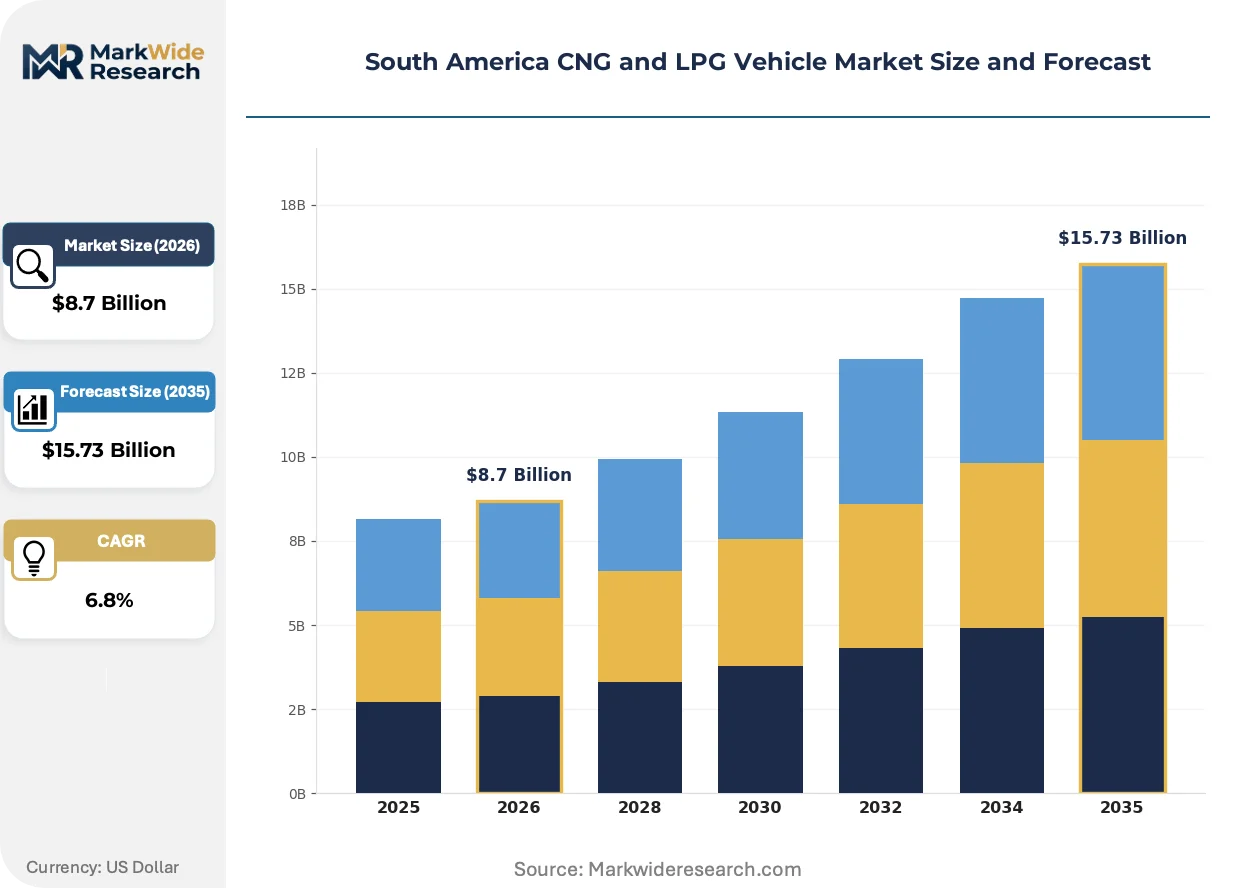
Fleet operators across Brazil and Argentina are accelerating dual-fuel conversions as diesel price volatility compresses operating margins and PROCONVE emission deadlines approach. The conversion ecosystem is fragmenting traditional dealership networks as direct retrofit contracts bypass factory channels.
Growth Catalysts
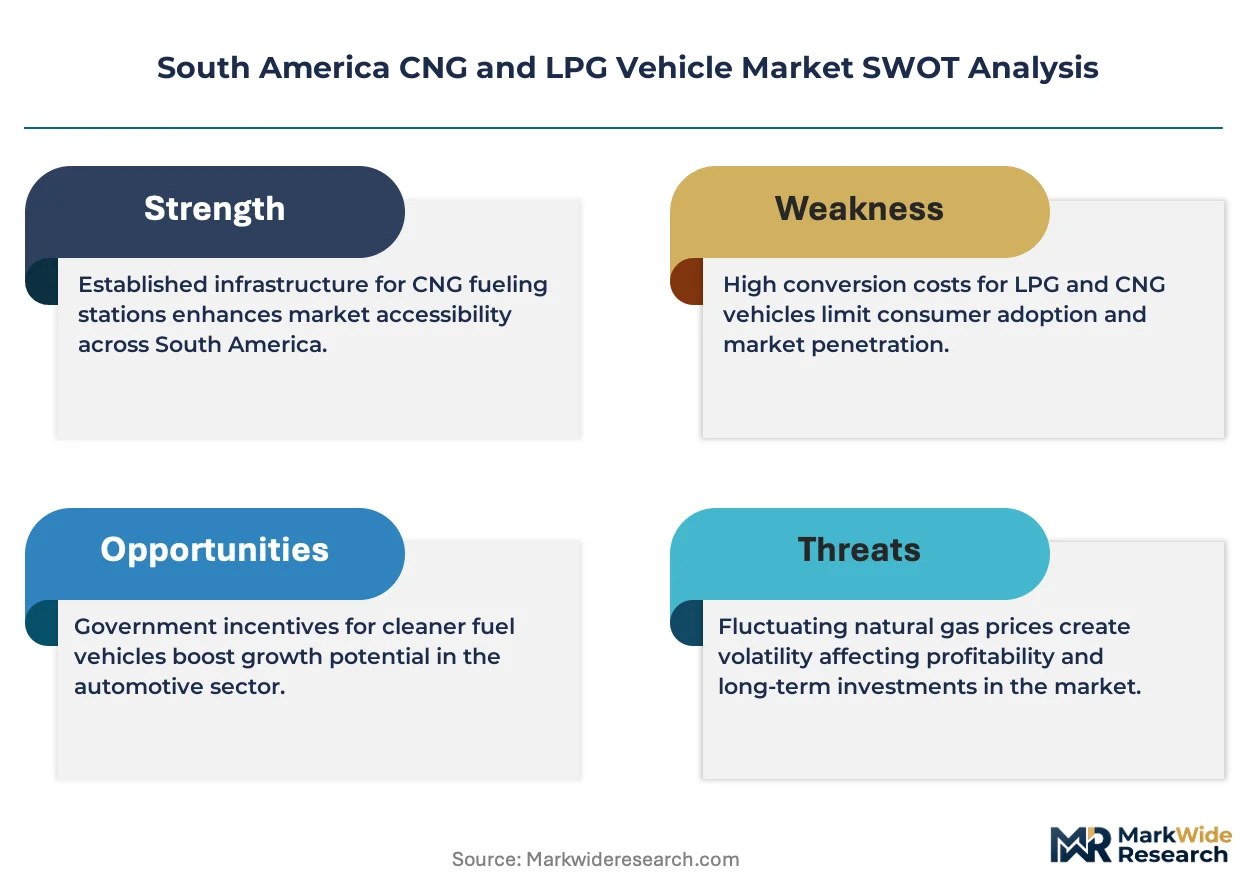
- PROCONVE Standards:Brazil's tightening tailpipe regulations are forcing diesel fleet operators toward cleaner-burning gas configurations before compliance deadlines.
- Buenos Aires Freight Corridors:Argentina's GNC subsidy frameworks are lowering conversion barriers for heavy commercial vehicles serving the capital's logistics zones.
- Dual-Fuel Flexibility:Mixer-based delivery systems are enabling operational switching between diesel and CNG modes during fuel price spikes.
Market Restraints
- Steel Cylinder Costs:High-pressure storage tank fabrication depends on specialized alloy supply concentrated in East Asian foundries.
- ANVISA Recertification Burden:Brazil's cylinder inspection protocols create recurring compliance costs that deter small fleet operators.
- Battery Electric Substitution:São Paulo's metropolitan bus procurement is pivoting toward full-electric alternatives for route electrification mandates.
Strategic Opportunities
- Uruguay Conversion Gap:The Montevideo metropolitan corridor lacks dense aftermarket service coverage for heavy truck retrofits.
- Paraguay Border Fleets:Cross-border logistics operators serving the Brazil-Paraguay corridor face limited certified conversion shop access.
- Sequential Injection Convergence:Integration of electronic fuel injection with OEM engine management systems is opening factory-fit channels.
Industry Challenges
- Certified Technician Scarcity:ANVISA's licensing requirements for high-pressure system installers outstrip vocational training program output.
- Harmonization Delays:Pending Mercosur conversion standard talks are fragmenting compliance costs across Brazilian and Argentine borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America CNG and LPG Vehicle Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: CNG, LPG, Biogas, Compressed Natural Gas Vehicle Type: Passenger Cars, Commercial Trucks, Buses, Two-Wheelers Engine Configuration: Diesel, Petrol, Hybrid, Dual-Fuel Sales Channel: Dealerships, Online Platforms, Direct Sales, Fleet Sales |
| Companies Covered | TA Gas Technology, Fiat, Encava, Cummins, BRC Gas Equipment, Valtec, Zavoli, EMER, Landi Renzo, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America CNG and LPG Vehicle Market Evolving Landscape
Conversion technology is advancing from mechanical mixer systems toward electronic fuel injection integration. Regulatory pressure and fleet cost optimization are compressing adoption timelines across the Southern Cone.
Sequential gas injection technology is migrating from aftermarket retrofit applications toward factory-installed configurations on Fiat's Brazilian assembly lines. São Paulo metropolitan bus operators are specifying these systems for PROCONVE L-6 compliance. The shift is compressing margin pools for independent conversion shops while elevating OEM service contract values.
Argentina's GNC subsidy framework is tightening installation quality requirements through its national transport safety authority certification mandates. The industrial consequence is consolidation among conversion kit distributors as uncertified imports face import restriction. Heavy commercial segments in Buenos Aires and Córdoba freight corridors are responding by pre-qualifying BRC Gas Equipment and Landi Renzo authorized service centers.
Fleet procurement patterns are fragmenting across vehicle lifecycle stages rather than concentrating at original purchase. São Paulo and Buenos Aires logistics operators are unbundling conversion decisions from new vehicle acquisition, deferring retrofits to mid-life overhaul windows. This behavioral shift is most visible in the São Paulo metropolitan bus corridor where municipal tender specifications now permit post-delivery conversion certification.
South America CNG and LPG Vehicle Market Segmentation
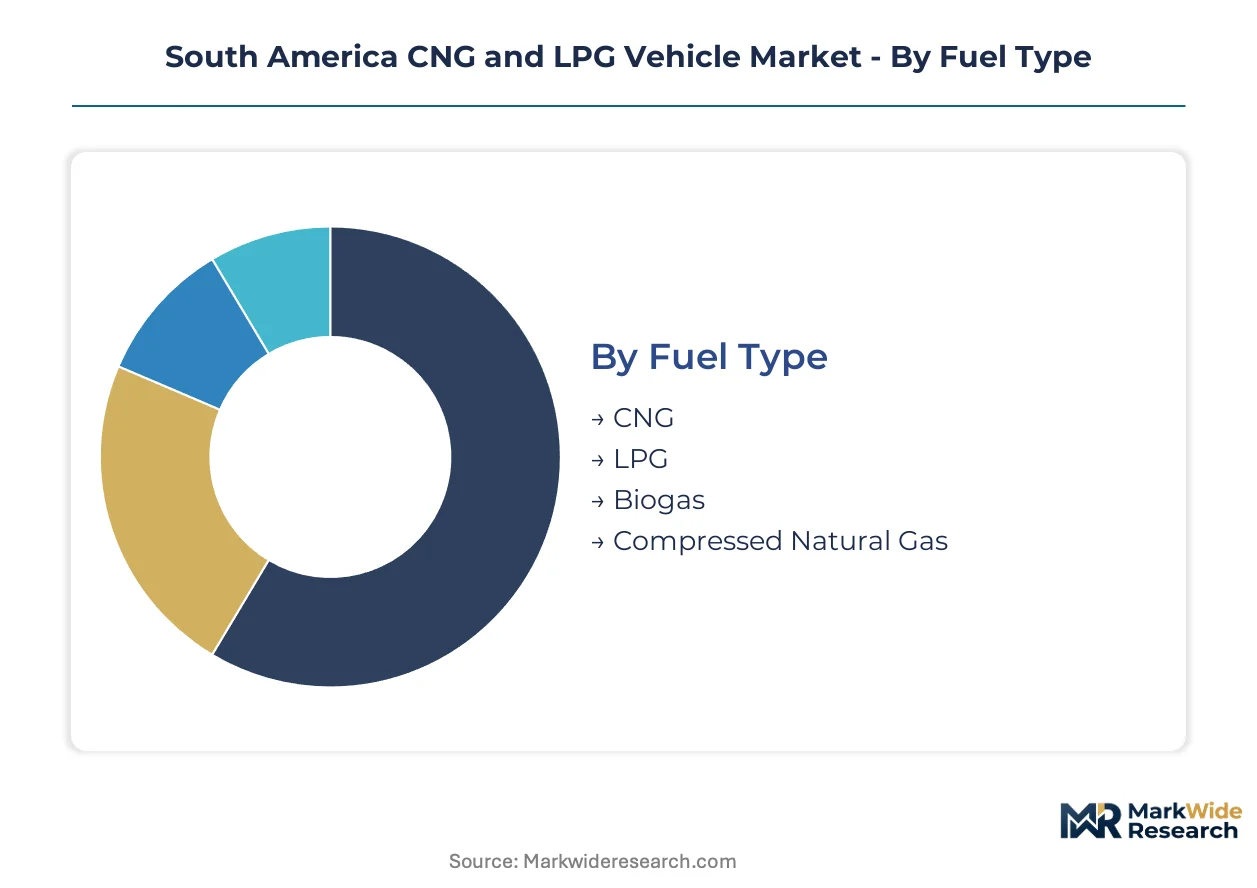
Segmentation in the South America CNG and LPG vehicle market reveals how fuel choice, vehicle class, and procurement channel shape margin structures and regulatory exposure across Brazil and Argentina. Understanding these divisions clarifies where conversion economics work and where factory-fit systems dominate.
Fuel Type:
Use cases span from municipal fleet compliance to long-haul freight cost management, with each fuel carrying distinct infrastructure dependencies and subsidy eligibility.
- CNG:Compressed natural gas at 200-250 bar serves high-mileage urban fleets through dedicated filling networks concentrated in São Paulo and Buenos Aires corridors. Brazilian PROCONVE standards and Argentine GNC subsidies concentrate demand here for heavy commercial compliance.
- LPG:Liquefied petroleum gas operates at lower pressure thresholds, enabling simpler retrofit logistics for passenger vehicles and light commercial fleets. Demand clusters in Argentina's interior provinces where distribution infrastructure predates CNG network buildouts.
- Biogas:Renewable methane from agricultural and waste digestion processes attracts sustainability-linked procurement tenders in Brazil's sugarcane belt.
- Compressed Natural Gas:Factory-certified CNG configurations from Fiat's Brazilian assembly lines dominate OEM channel volume through warranty-integrated service contracts.
The dominant share belongs to CNG, while biogas is closing the gap fastest through renewable fuel certificate programs in Brazilian municipal tenders.
Vehicle Type:
Volume concentration and margin capture diverge sharply between factory-fit passenger segments and aftermarket-heavy commercial retrofits.
- Passenger Cars:Fiat's Brazilian manufacturing base supplies factory-installed CNG options through dealership networks, capturing warranty-integrated service revenue. São Paulo metropolitan households and ride-hail operators generate the densest demand clusters for OEM-channel acquisition.
- Commercial Trucks:Heavy freight operators across Argentina's Buenos Aires-Córdoba corridor and Brazil's Santos port logistics zone drive dual-fuel retrofit economics. ANVISA cylinder recertification requirements and PROCONVE emission deadlines compress conversion decision windows for diesel fleet owners.
- Buses:São Paulo metropolitan corridor specifications increasingly permit post-delivery conversion certification, fragmenting procurement timing across vehicle lifecycle stages.
- Two-Wheelers:Motorcycle and scooter conversions remain marginal, limited by cylinder packaging constraints and lower per-kilometer fuel cost sensitivity.
Commercial trucks generate the strongest margin pools, while buses are expanding most quickly through municipal electrification mandate exemptions for dual-fuel configurations.
Engine Configuration:
Technology migration from mechanical mixer systems toward electronic integration shapes competitive positioning across aftermarket and OEM channels.
- Diesel:Compression-ignition platforms anchor heavy commercial retrofit demand, with dual-fuel diesel-CNG systems enabling operational flexibility during fuel price volatility.
- Petrol:Spark-ignition engines dominate light vehicle CNG integration, with sequential injection technology migrating from aftermarket to factory-fit Brazilian production.
- Hybrid:Gas-electric configurations remain nascent, constrained by powertrain complexity and limited certified technician capacity for high-pressure system integration.
- Dual-Fuel:Switchable diesel-gas operation is gaining share fastest among Argentine heavy fleet operators seeking fuel arbitrage protection.
Diesel configurations retain the dominant installed base, though dual-fuel systems are climbing the fastest through fleet procurement pattern shifts.
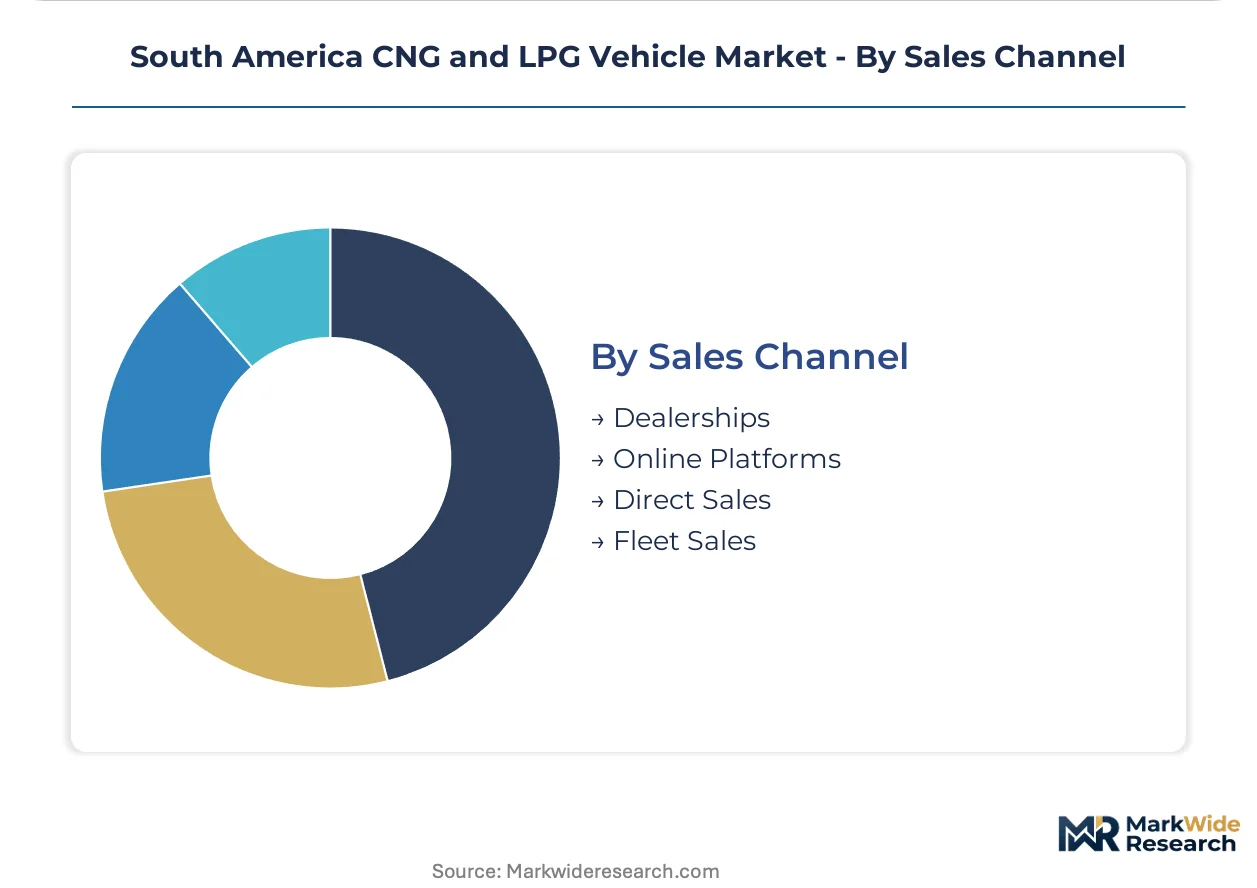
Sales Channel:
Procurement fragmentation is compressing traditional dealership margins as direct retrofit contracts bypass factory channels.
- Dealerships:Fiat-affiliated networks control factory-installed CNG passenger car distribution, with warranty-integrated service contracts defending margin positions against independent shops.
- Online Platforms:Digital procurement of conversion kits and certified installer matching is emerging for light commercial segments, though ANVISA technician licensing requirements limit full transaction completion online.
- Direct Sales:Fleet operators in São Paulo and Buenos Aires logistics zones are negotiating direct retrofit contracts with BRC Gas Equipment and Landi Renzo authorized service centers, bypassing dealership markups.
- Fleet Sales:Municipal and corporate fleet tenders specify conversion-ready chassis or post-delivery certification, unbundling fuel system decisions from original vehicle acquisition.
Fleet sales command the dominant volume position, while direct sales are gaining share fastest through large operator bypass of traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bolivia-Brazil natural gas pipeline anchors South American CNG infrastructure, with compressor stations along the route feeding distribution networks that concentrate vehicle conversion demand in terminal cities. Argentina's Neuquén shale formations and Brazil's Santos Basin pre-salt reserves provide feedstock proximity that shapes regional adoption patterns. Fleet operators calibrate conversion decisions against pipeline access and local subsidy regimes.
Brazil
São Paulo's metropolitan bus corridor and Santos port logistics zone generate the densest conversion demand as PROCONVE L-6 deadlines approach. ANVISA enforces cylinder recertification protocols that shape aftermarket service capacity and technician licensing requirements. Minas Gerais and Rio Grande do Sul host secondary conversion clusters serving intra-regional freight routes.
Argentina
Buenos Aires freight corridors and Córdoba logistics zones drive heavy commercial dual-fuel retrofits under GNC subsidy frameworks. The national transport safety authority certifies installation quality, consolidating kit distribution among authorized service networks. Interior provinces maintain LPG preference where CNG pipeline coverage remains sparse.
Chile
Antofagasta mining corridors and Santiago metropolitan freight routes anchor commercial vehicle interest, though CNG infrastructure lags Brazilian and Argentine density. The Ministry of Energy's electromobility strategy competes for fleet capital allocation. Valparaíso port logistics operators evaluate conversion economics against diesel price volatility.
Colombia
Bogotá's TransMilenio bus system and Medellín metropolitan transport tenders specify alternative fuel compliance, creating procurement pressure. The national mining and energy planning unit regulates CNG station licensing, constraining network expansion pace. Caribbean coast freight operators face infrastructure gaps that limit heavy truck conversion viability.
Uruguay
Montevideo's metropolitan corridor lacks dense aftermarket service coverage for heavy truck retrofits, creating conversion capacity gaps. The state petroleum refinery's CNG distribution network remains concentrated in capital-region corridors. Cross-border logistics operators serving Brazil-Uruguay routes source conversion services from Porto Alegre shops.
South America CNG and LPG Vehicle Market Competitive Landscape
On the supply side, the industry is bifurcated between factory-fit OEM configurations and fragmented aftermarket conversion networks. Fiat controls passenger car factory installations through Brazilian assembly line integration, while independent shops capture commercial retrofit volume. Two strategic archetypes dominate: integrated OEM-service contract bundlers and specialized dual-fuel system integrators. Competitive positioning hinges on ANVISA certification density and PROCONVE compliance timing.
Among conversion equipment specialists, BRC Gas Equipment and Landi Renzo anchor the aftermarket tier with authorized service center networks across the Southern Cone. Fiat occupies the factory-fit vector through Brazilian manufacturing base integration. These three exemplify how regulatory certification requirements and geographic service coverage determine competitive boundaries in a market where fleet procurement increasingly unbundles vehicle acquisition from fuel system decisions.
| Leading Market Players |
|---|
| TA Gas Technology |
| Fiat |
| Encava |
| Cummins |
| BRC Gas Equipment |
| Valtec |
| Zavoli |
| EMER |
| Landi Renzo |
| Others |
Value Network & Pricing Analysis
São Paulo's metropolitan bus corridor compresses conversion margins as fleet procurement unbundles fuel system decisions from chassis acquisition, concentrating pricing power among authorized service networks while fragmenting buyer leverage across mid-life overhaul windows.
Pricing Analysis
Volume-discount tiering separates municipal fleet tenders from individual owner-operator retrofits, with ANVISA-certified installations commanding premium positioning over uncertified imports. Price differentiation rests on technician licensing density and warranty-integrated service bundling. Cost compression in the independent shop tier is intensifying as BRC Gas Equipment and Landi Renzo authorized networks consolidate kit distribution. Small fleet operators exhibit acute price sensitivity, while municipal procurement committees prioritize compliance certainty over unit economics.
Supply Chain Analysis
Contract manufacturing for high-pressure cylinders concentrates in East Asian specialty alloy foundries, with limited alternative sourcing for 200-250 bar storage tank fabrication. Raw material dependencies span chromium-molybdenum steel alloys, precision fuel injection components, and electronic control modules. Single-source vulnerability runs through East Asian cylinder supply, exposing Brazilian and Argentine conversion markets to logistics chokepoints at Pacific port terminals. Distribution feeds from authorized service center networks into direct fleet contracts, bypassing traditional dealership markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet buyer consolidation across São Paulo and Buenos Aires logistics corridors is shifting negotiation leverage toward large operators, fragmenting pricing power among conversion equipment suppliers and compressing margin pools for independent service shops.
For Market Incumbents: Harden ANVISA certification density in Minas Gerais and Rio Grande do Sul corridors to defend against emerging battery-electric substitution in metropolitan bus tenders. Deepen backward integration into high-pressure cylinder supply through captive sourcing agreements with East Asian foundries, reducing exposure to alloy price volatility and logistics disruptions.
For New Entrants and Emerging Players: Pursue Uruguay's Montevideo metropolitan corridor and Paraguay border fleet corridors where aftermarket service coverage remains sparse and certified technician capacity lags demand. Target heavy commercial dual-fuel retrofits through direct contracting relationships with cross-border logistics operators, bypassing established BRC Gas Equipment and Landi Renzo distribution layers.
For Investors and Strategic Acquirers: PROCONVE L-6 compliance deadlines reshape the acquisition landscape toward ANVISA-certified conversion networks with dense technician licensing and municipal service contracts. Long-term viability hinges on positioning for regulatory harmonization across Mercosur borders, with sequential injection technology convergence serving as the critical inflection signal for factory-fit channel displacement of aftermarket retrofits.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Expansion | Authorized service center licensing in secondary corridors defends margin pools against independent shop competition. |
| Sequential Injection Technology Migration | Electronic fuel injection integration with OEM engine management systems opens factory-fit channels for Fiat partnerships. |
| East Asian Cylinder Supply Agreement | Long-term alloy sourcing contracts reduce exposure to high-pressure storage tank fabrication bottlenecks. |
| Uruguay-Paraguay Service Network Buildout | First-mover certification density in underserved corridors captures cross-border logistics operator demand. |
| Municipal Fleet Direct Contracting | Bypassing dealership layers captures procurement unbundling toward post-delivery conversion certification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across fleet procurement directors at São Paulo metropolitan bus operators, ANVISA-certified installation technicians, BRC Gas Equipment and Landi Renzo regional service managers, Fiat platform engineering leads, and Argentine national transport safety authority certification officers. Secondary validation drew from PROCONVE regulatory filings, ANVISA cylinder recertification databases, Mercosur harmonization negotiation records, and vehicle registration data from Brazilian and Argentine transport ministries. Bottom-up fleet conversion volume estimates triangulated against top-down fuel consumption projections across the analysis window.
Calibration anchored volume and value outputs to historical conversion kit shipments, OEM factory-fit penetration rates, and municipal tender award patterns across the projection horizon. Segmentation dimensions spanned fuel type, vehicle class, engine configuration, and procurement channel, with CAGRs derived from regression analysis of fleet operator conversion decision timing against diesel price volatility and emission compliance deadlines. Industry-specific inputs included ANVISA technician licensing program output rates and GNC subsidy framework revision cycles.
Sensitivities concentrate around PROCONVE deadline acceleration, Mercosur harmonization agreement outcomes, and battery-electric bus procurement pivot rates in São Paulo. Forecasts reflect documented assumptions regarding fleet operator fuel arbitrage behavior and aftermarket service capacity expansion trajectories. Quarterly review of municipal tender specifications and ANVISA certification issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
India CNG Market