
 Brazil Alternative Fuel Vehicles Market | 2026-2036
Brazil Alternative Fuel Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Alternative Fuel Vehicles Market Outlook
Lithium iron phosphate chemistry is pivoting product economics as Brazilian assemblers reduce cobalt dependence. BYD Auto Co. Ltd. leverages its in-house cell production to anchor cost structures in the battery-electric segment. Toyota sustains hybrid leadership through ethanol-compatible powertrains developed for Brazilian flex-fuel infrastructure. Volkswagen competes by extending its modular electric drive matrix to local assembly lines.
Alternative fuel vehicles integrate powertrains utilizing non-petroleum energy carriers including battery-electric systems, hydrogen fuel cells, ethanol combustion, and compressed natural gas engines, with energy storage specifications ranging from 40 kWh lithium-ion packs to 700-bar hydrogen tanks designed for commercial duty cycles. Electric vehicles dominate unit volume as government fleets and ride-sharing services scale procurement under federal incentive thresholds. Hydrogen fuel cell vehicles represent the fastest-growing structural category despite nascent refueling infrastructure, while compressed natural gas retains mature penetration in heavy-duty public transport where total cost of ownership calculations favor established tank and compressor supply chains.
ANVISA governs hydrogen system safety certifications for commercial vehicle deployment, while the Rota 2030 framework from the Ministry of Economy structures tax abatements contingent on local R&D spending and fuel efficiency benchmarks. INMETRO efficiency labeling shapes consumer comparison points for plug-in hybrid and battery-electric models. Stakeholders must weigh ethanol infrastructure leverage against battery supply chain localization requirements as regulatory thresholds tighten.
Market Dynamics
Brazil's alternative fuel vehicle landscape is being fundamentally restructured by the Rota 2030 policy framework, which ties tax abatements to localized R&D spending and escalating fuel efficiency benchmarks. This regulatory architecture is forcing assemblers to rebalance ethanol-compatible powertrains against battery-electric localization requirements.
Growth Catalysts
- Rota 2030 Tax Incentives:The Ministry of Economy's framework rewards manufacturers meeting local content thresholds, accelerating flex-fuel hybrid development and battery pack assembly investments in São Paulo state industrial corridors.
- Municipal Fleet Electrification:São Paulo and Rio de Janeiro transit authorities are expanding ethanol and CNG procurement for bus fleets, creating guaranteed offtake volumes that de-risk supplier capital commitments.
- Lithium Iron Phosphate Chemistry:Cobalt-free cell formulations are reducing import dependency and enabling Brazilian assemblers to source cathode materials through regional supply partnerships rather than distant concentrate markets.
Market Restraints
- Limited Hydrogen Distribution Infrastructure:700-bar refueling stations remain concentrated in southeastern pilot corridors, constraining fuel cell commercial vehicle deployment to captive fleet routes with guaranteed return-to-base patterns.
- Charging Network Asymmetry:Battery-electric ride-sharing demand clusters in state capitals where grid capacity and fast-charger density suffice, leaving interior municipalities underserved and compressing addressable market geography.
- ANVISA Certification Timelines:Hydrogen system safety approvals for commercial vehicle deployment involve extended validation cycles that delay platform launches and extend capital lock-up periods for developers.
Strategic Opportunities
- Northeast Corridor Electrification:Bahia and Pernambuco state capitals present underpenetrated demand for battery-electric ride-sharing platforms as charging infrastructure investments follow federal development zone incentives.
- Ethanol-to-Hydrogen Pathways:Convergence of biomass gasification with electrolysis leveraging Brazil's sugarcane ethanol infrastructure could establish competitive green hydrogen production for heavy-duty fuel cell applications.
- INMETRO Labeling Differentiation:Efficiency rating systems for plug-in hybrids create consumer comparison frameworks that reward manufacturers investing in localized powertrain calibration and thermal management optimization.
Industry Challenges
- Battery Supply Chain Localization:Cell manufacturing equipment and precursor chemical supply chains require substantial capital deployment with extended payback periods given current import tariff structures.
- Powertrain Integration Complexity:Flex-fuel hybrid architectures demand simultaneous optimization of ethanol combustion thermal efficiency, electric motor torque mapping, and battery thermal management across variable ambient conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Alternative Fuel Vehicles Market |
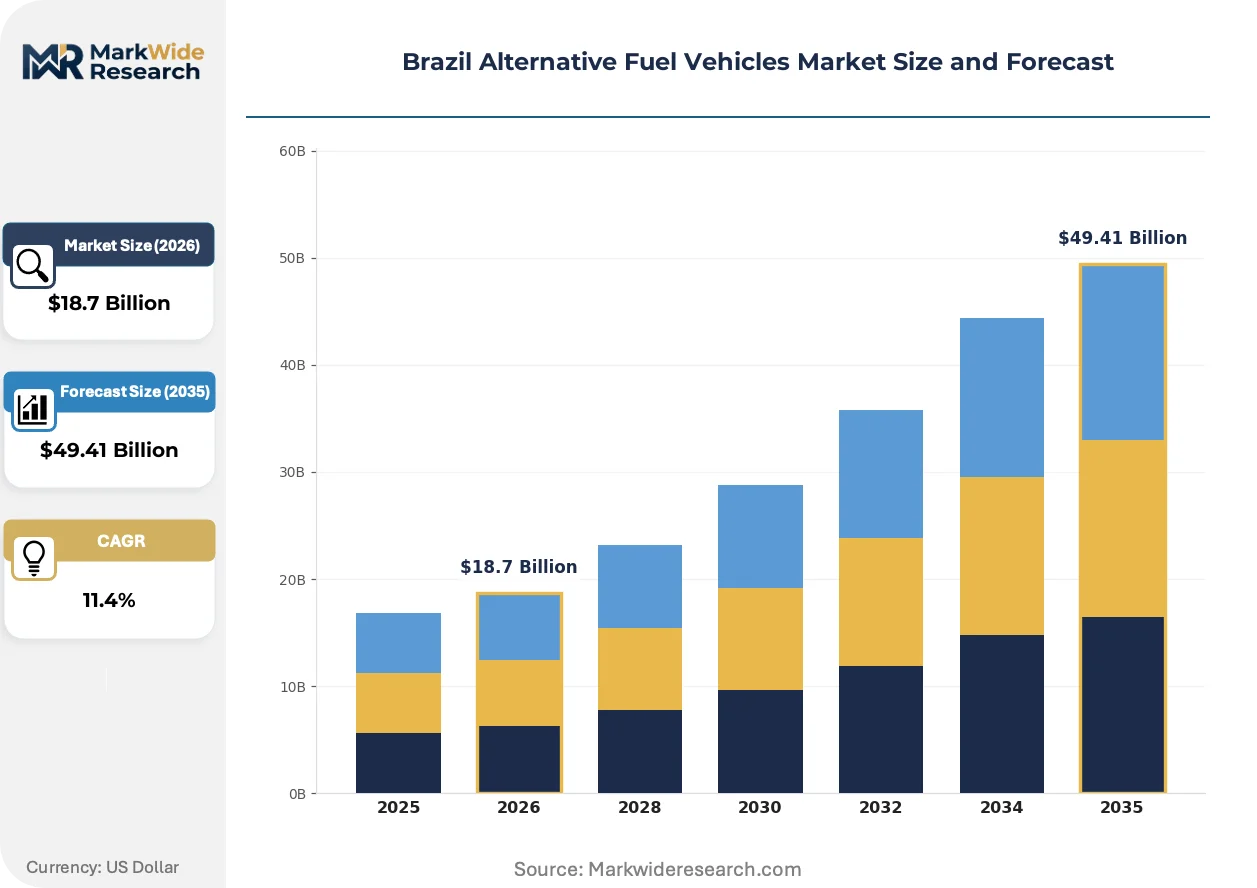
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Vehicles, Hydrogen Fuel Cell Vehicles, Plug-in Hybrid Vehicles, Biodiesel Vehicles Fuel Source: Battery Electric, Hydrogen, Ethanol, Compressed Natural Gas End User: Government Fleets, Public Transport, Ride Sharing Services, Personal Use Charging Infrastructure: Fast Chargers, Home Chargers, Public Charging Stations, Fleet Charging Facilities |
| Companies Covered | Nissan Motor Co. Ltd., Volkswagen, Anhui Jianghuai Automobile (JAC), Toyota, Great Wall Motor, Bayerische Motoren Werke AG, Renault do Brasil S/A, Stellantis, BYD Auto Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Alternative Fuel Vehicles Market Strategic Shifts
Technology convergence and regulatory calibration are actively reshaping competitive positioning in Brazil's alternative fuel vehicle sector. Three developments merit particular attention for their structural implications.
Lithium iron phosphate battery chemistry is integrating into Brazilian assembly lines as assemblers seek cobalt independence and supply chain resilience. Municipal bus operators and ride-sharing platforms are adopting these cell formulations at accelerating pace due to improved thermal stability in tropical climates. This chemistry shift is compressing cost structures for battery-electric segments while enabling longer duty cycles for commercial applications.
ANVISA's hydrogen system safety certification protocols are tightening validation requirements for commercial vehicle deployment. The regulatory friction is extending product development timelines and concentrating initial fuel cell rollouts in captive fleet applications with controlled duty cycles. Heavy-duty transit operators in southeastern corridors are responding by partnering with equipment suppliers on pilot programs that generate operational data for subsequent certification submissions.
Fleet procurement models are evolving from unit sales toward performance-based service contracts with guaranteed uptime and energy cost ceilings. Transit authorities and logistics operators are displacing traditional capital acquisition with total cost of ownership agreements that bundle vehicles, maintenance, and energy supply. This restructuring is most visible in São Paulo metropolitan bus concessions where operators assume technology transition risk in exchange for long-term operational contracts.
Brazil Alternative Fuel Vehicles Market Segmentation
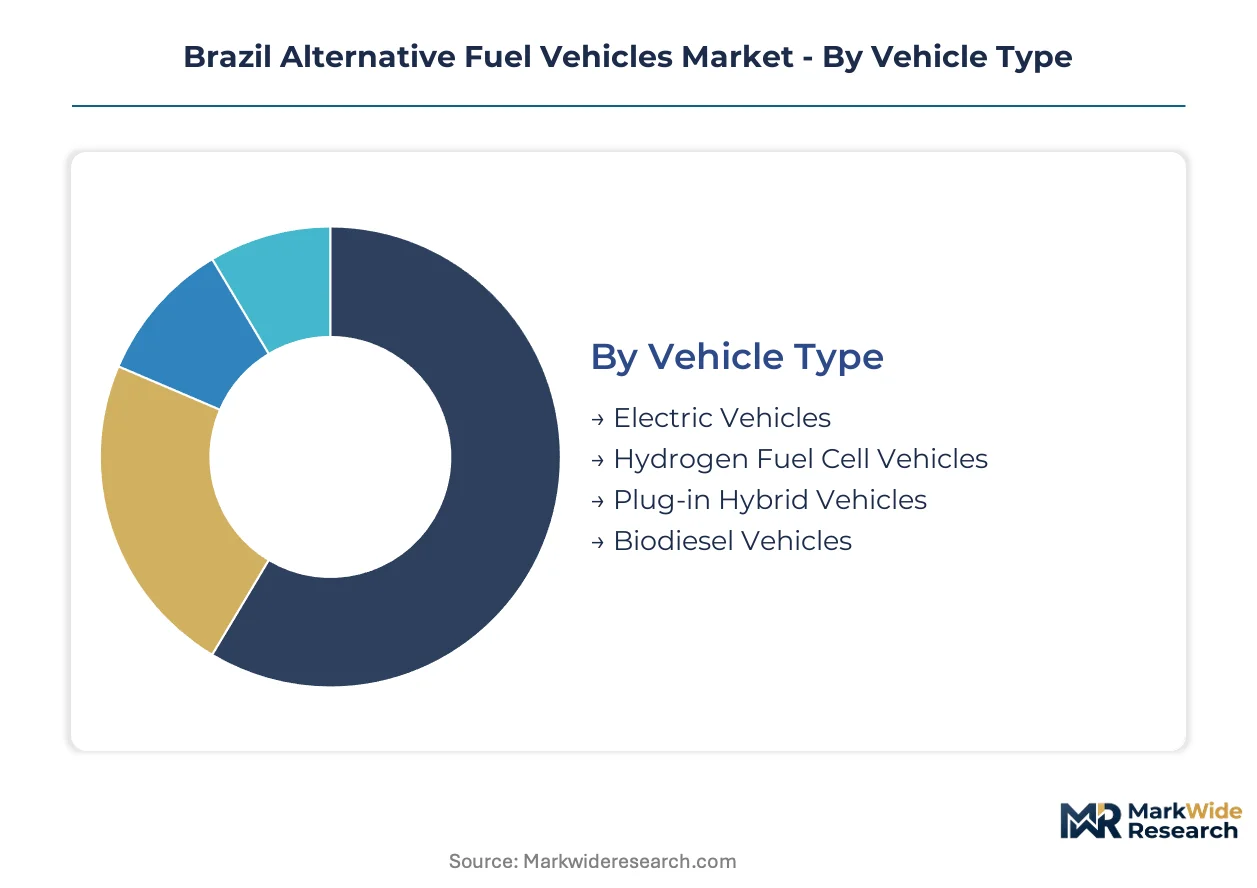
Brazil's alternative fuel vehicle market segments reflect distinct infrastructure dependencies and procurement cycles. Fleet operators and individual consumers face fundamentally different upgrade timelines shaped by Rota 2030 incentives and municipal electrification schedules.
Vehicle Type:
Replacement cycles vary dramatically across powertrain architectures, with commercial fleets driving faster turnover than personal ownership patterns.
- Electric Vehicles:Battery-electric platforms with lithium iron phosphate chemistry dominate São Paulo and Rio de Janeiro ride-sharing procurement. Municipal bus electrification programs in southeastern state capitals accelerate fleet replacement under guaranteed offtake contracts.
- Hydrogen Fuel Cell Vehicles:Heavy-duty commercial platforms utilizing 700-bar storage systems serve captive routes with return-to-base refueling. ANVISA certification timelines constrain deployment to pilot corridors where infrastructure investment precedes vehicle procurement.
- Plug-in Hybrid Vehicles:Ethanol-compatible architectures bridge flex-fuel infrastructure with electric range extension for consumers in charging-underserved interior municipalities.
- Biodiesel Vehicles:Compression-ignition platforms adapted for fatty acid methyl ester blends retain relevance in agricultural logistics where feedstock proximity reduces fuel cost volatility.
Volume placements concentrate in Electric Vehicles; the faster expansion belongs to Hydrogen Fuel Cell Vehicles.
Fuel Source:
Cost tier differentiation separates segments by capital intensity and operating expense structure across Brazilian industrial corridors.
- Battery Electric:Grid-dependent systems with 40-80 kWh lithium-ion configurations anchor ride-sharing and last-mile delivery economics. Charging infrastructure density in southeastern state capitals determines viable deployment geography.
- Hydrogen:Electrolysis and steam methane reforming pathways supply 700-bar compressed gas for heavy-duty transit. Ethanol-to-hydrogen biomass gasification projects in São Paulo state could localize green hydrogen production.
- Ethanol:Sugarcane-derived hydrous ethanol powers flex-fuel hybrid combustion engines through Brazil's established distribution network of 27,000 retail stations.
- Compressed Natural Gas:Mature infrastructure serving metropolitan bus fleets in Rio de Janeiro and Belo Horizonte with total cost of ownership advantages over diesel equivalents.
Ethanol retains the largest installed base; Battery Electric systems are climbing the fastest in new registrations.
End User:
Customer type dictates procurement scale, financing structure, and technology risk tolerance across Brazilian market participants.
- Government Fleets:Federal and state procurement under Rota 2030 local content requirements drives battery-electric and flex-fuel hybrid adoption. INMETRO efficiency labeling shapes competitive bidding criteria for ministerial vehicle pools.
- Public Transport:Metropolitan bus operators in São Paulo and Rio de Janeiro execute multi-year concessions with performance-based service contracts bundling vehicles, maintenance, and energy supply.
- Ride Sharing Services:Platform economics favor battery-electric vehicles where charging infrastructure density supports high-utilization duty cycles in state capitals.
- Personal Use:Individual consumers balance purchase price sensitivity against fuel cost savings, with ethanol-compatible hybrids penetrating interior municipalities lacking reliable charging networks.
Public Transport commands the largest unit volumes; Ride Sharing Services are gaining share fastest among end-user categories.
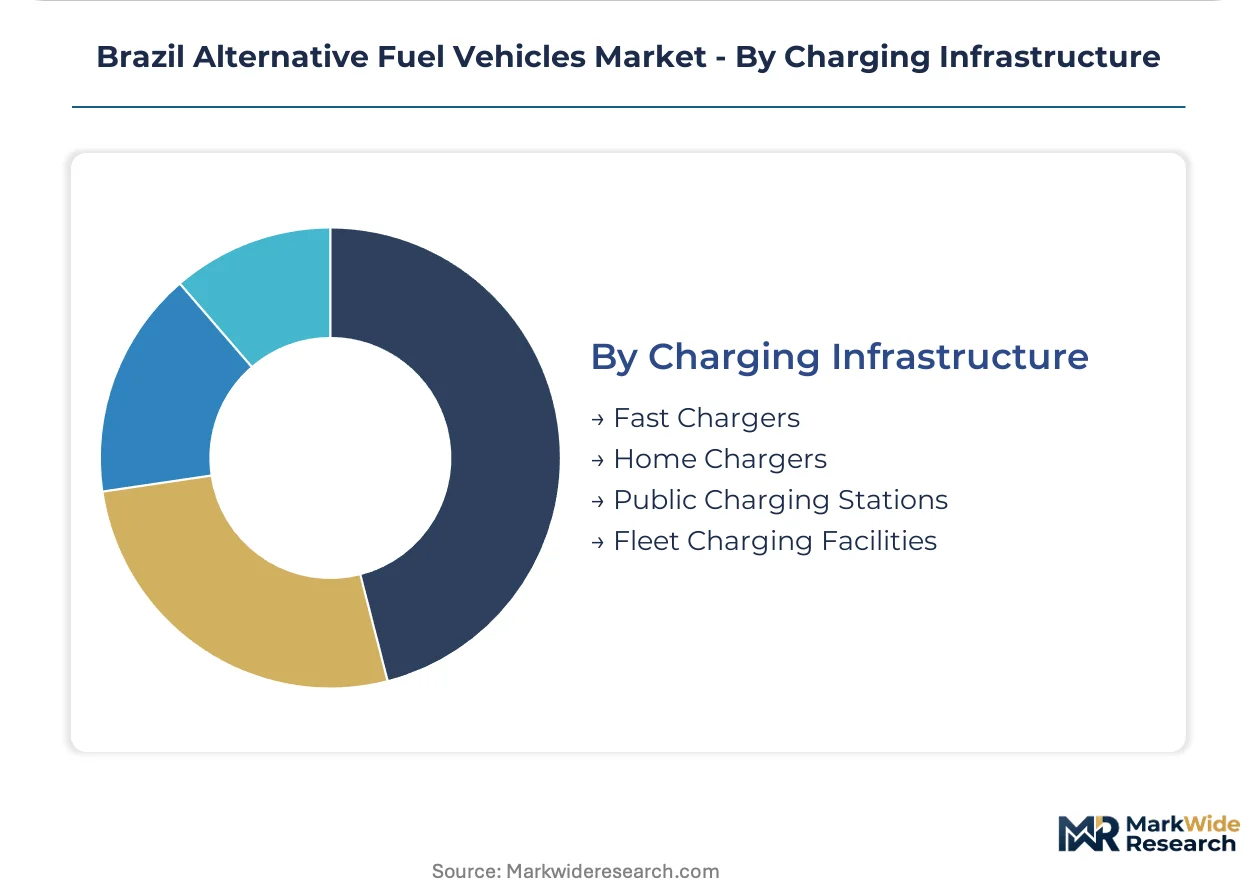
Charging Infrastructure:
Supply concentration in equipment manufacturing and installation services creates geographic asymmetry in network deployment.
- Fast Chargers:DC rapid charging systems with 150-350 kW capacity enable ride-sharing fleet turnaround and highway corridor electrification. Grid capacity constraints in northeastern state capitals limit deployment pace.
- Home Chargers:Level 2 alternating current systems serve residential customers in affluent São Paulo neighborhoods with dedicated parking infrastructure.
- Public Charging Stations:Curbside and retail location installations concentrate in southeastern metropolitan areas where municipal permitting processes have standardized.
- Fleet Charging Facilities:Depot-based systems with managed charging software optimize electricity demand profiles for bus and delivery operators under time-of-use rate structures.
Fast Chargers absorb the greatest capital deployment; Fleet Charging Facilities show the steepest expansion trajectory as municipal electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for alternative fuel vehicles concentrates in Brazil's southeastern industrial corridor, where charging infrastructure density and municipal fleet procurement create viable deployment economics for battery-electric platforms.
São Paulo
São Paulo anchors national demand through metropolitan bus electrification programs and ride-sharing platform procurement. Rota 2030 tax abatements reward manufacturers meeting local content thresholds in São Paulo state industrial corridors. The ABC Paulista manufacturing cluster hosts battery pack assembly investments serving flex-fuel hybrid and battery-electric production lines.
Rio de Janeiro
Rio de Janeiro transit authorities expand compressed natural gas and ethanol procurement for municipal fleets under guaranteed offtake contracts. ANVISA governs hydrogen system safety certifications for commercial vehicle deployment in the state. The metropolitan region's bus concessions bundle vehicles, maintenance, and energy supply through performance-based service contracts.
Minas Gerais
Minas Gerais leverages proximity to southeastern supply chains for flex-fuel hybrid component manufacturing. INMETRO efficiency labeling shapes competitive bidding criteria for state government vehicle pools. Belo Horizonte's metropolitan bus operators execute multi-year concessions with technology transition risk allocated to private operators.
Bahia
Bahia presents underpenetrated demand for battery-electric ride-sharing platforms as charging infrastructure investments follow federal development zone incentives. The state's sugarcane ethanol infrastructure supports biomass gasification pathways for green hydrogen production. Salvador's port logistics create potential for hydrogen fuel cell commercial vehicle pilot corridors.
Rio Grande do Sul
Rio Grande do Sul's automotive supplier base extends into battery-electric thermal management and powertrain calibration services. State procurement under Rota 2030 local content requirements drives flex-fuel hybrid adoption for government fleets. Porto Alegre's industrial corridor concentrates on ethanol-compatible powertrain component manufacturing.
Brazil Alternative Fuel Vehicles Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated assemblers commanding battery-electric platforms while component suppliers capture flex-fuel hybrid subsystems. Market structure tilts toward consolidation among multinational OEMs with established Brazilian assembly presence, though Chinese entrants are compressing pricing in the battery-electric segment. Three archetypes dominate: legacy OEMs with ethanol-compatible hybrid portfolios, battery-electric specialists with in-house cell production, and flex-fuel powertrain component suppliers. Competitive moves concentrate on strategic partnerships for charging infrastructure and portfolio diversification across powertrain chemistries.
Within the battery-electric specialist tier, BYD Auto Co. Ltd. exemplifies vertical integration through in-house lithium iron phosphate cell production. Toyota occupies a position anchored to ethanol-compatible hybrid powertrains calibrated for Brazilian flex-fuel infrastructure. Volkswagen sits within the modular platform archetype, extending electric drive matrix architectures to localized assembly lines. These three represent distinct strategic postures: cobalt-independent battery economics, legacy ethanol infrastructure leverage, and scalable modular electrification.
| Leading Market Players |
|---|
| Nissan Motor Co. Ltd. |
| Volkswagen |
| Anhui Jianghuai Automobile (JAC) |
| Toyota |
| Great Wall Motor |
| Bayerische Motoren Werke AG |
| Renault do Brasil S/A |
| Stellantis |
| BYD Auto Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed battery cell producers and family-owned flex-fuel component specialists anchor supply discipline in Brazil's alternative fuel vehicle sector, translating Rota 2030 local content thresholds into pricing power for compliant assemblers while squeezing import-dependent competitors.
Pricing Analysis
Volume placements favor battery-electric platforms while margin capture concentrates in flex-fuel hybrid powertrains. Three-tier pricing structure across premium, standard, and economy levels separates lithium iron phosphate battery packs from cobalt-dependent alternatives from entry-level CNG conversions. Price differentiation hinges on INMETRO efficiency certification tier and local content compliance under Rota 2030 tax abatement rules. Cost compression in battery-electric segments is intensifying because Chinese cell manufacturers are scaling São Paulo state assembly lines.
Supply Chain Analysis
Freight costs for lithium carbonate and cathode precursor chemicals from Chile and Argentina compress margins for Brazilian battery pack assemblers dependent on Andean mining corridors. The supply chain draws from China for cell manufacturing equipment, South Korea for electrolyte formulations, and domestic São Paulo state industrial corridors for flex-fuel engine component machining. Single-source vulnerability concentrates in lithium refining capacity. Distribution runs through OEM captive channels for battery-electric platforms and independent aftermarket networks for CNG conversion kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's alternative fuel vehicle market operates as a cost-of-compliance arena where Rota 2030 local content thresholds erect barrier-to-entry moats favoring assemblers with established São Paulo state manufacturing footprints.
For Market Incumbents: Deploy backward integration into lithium iron phosphate cathode material processing to offset cobalt price volatility and secure ANVISA certification timelines. Consolidate flex-fuel hybrid powertrain calibration capabilities against Chinese battery-electric entrants compressing southeastern ride-sharing pricing. Anchor dealership service networks in charging-underserved interior municipalities to defend ethanol-compatible hybrid positioning. For New Entrants and Emerging Players: Enter via fleet charging facility construction and software-managed demand optimization serving municipal bus electrification programs in Bahia and Pernambuco. Target public transport performance-based service contracts where incumbent operators assume technology transition risk. Pursue white-label battery pack assembly partnerships with established OEMs lacking captive cell production. For Investors and Strategic Acquirers: Distressed-cycle entries favor flex-fuel powertrain component specialists with established ethanol engine calibration IP in Minas Gerais and Rio Grande do Sul industrial corridors. Long-term viability centers on regulatory persistence of Rota 2030 frameworks and sugarcane ethanol infrastructure durability. Monitor ANVISA hydrogen certification acceleration as inflection signal for fuel cell commercial vehicle capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Lithium iron phosphate cell procurement from BYD Auto Co. Ltd. anchors cost structures for São Paulo ride-sharing platforms. |
| Charging Infrastructure Partnership | Fast-charger deployment with municipal transit authorities de-risks fleet electrification capital commitments in Rio de Janeiro. |
| Platform Standardization | Volkswagen's modular electric drive matrix extension to local assembly lines compresses powertrain development cycles. |
| Geographic Manufacturing Footprint | ABC Paulista battery pack assembly investments satisfy Rota 2030 local content thresholds for tax abatement eligibility. |
| Software-Defined Vehicle Investment | Thermal management optimization for tropical climates differentiates ethanol-compatible hybrid offerings against imported battery-electric alternatives. |
Study Parameters
ANVISA regulatory filings, INMETRO efficiency certification databases, and Rota 2030 tax abatement disclosure records formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, Tier 1 supplier procurement leads, municipal transit authority fleet managers, and charging infrastructure EPC contractors. Bottom-up and top-down triangulation validated vehicle registration data against production line utilization reported in trade association filings.
Bottom-up unit economics modeling of battery pack assembly costs and flex-fuel powertrain component sourcing fed into top-down market sizing anchored to federal incentive program budgets. Segmentation dimensions spanned vehicle class, propulsion architecture, fuel source chemistry, and regional charging infrastructure density across the analysis window. CAGRs derived from S-curve adoption modeling calibrated to municipal fleet replacement cycles and ride-sharing platform procurement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA certification timeline extensions or lithium carbonate supply disruptions from Andean mining jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Ethanol Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market