
 Fuel Caddy Market | 2026-2036
Fuel Caddy Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Caddy Market Analytics
Aftermarket service revenue for fuel containment systems is reconfiguring competitive economics across the value chain. Scepter Corporation leverages rotational molding expertise to dominate portable caddy production. No-Spill Inc. differentiates through CARB-certified spout technology that sustains premium positioning in California markets. Midwest Can Company anchors Midwest distribution through retail channel control.
A fuel caddy is a portable or semi-portable container system designed for safe transport and dispensing of gasoline, diesel, or kerosene, typically constructed from high-density polyethylene or welded steel with integrated pumps, hoses, and spill-containment features. These systems serve construction crews, agricultural operators, and fleet maintenance teams requiring refueling capability at remote or temporary worksites. Portable caddies command the largest volume share due to OSHA mobility requirements for construction environments. Steel construction in the 20-50 gallon capacity band captures the strongest margin pool because fabrication complexity limits supplier entry. Gravity feed systems face structural decline as electric pump adoption accelerates among emergency services and municipal fleets.
EPA spill prevention regulations under 40 CFR 112 and OSHA 29 CFR 1926.152 workplace fuel handling standards mandate secondary containment and grounding provisions, directly shaping product design requirements and certification costs. DOT hazardous materials transport rules further constrain portable caddy dimensions and closure mechanisms for highway mobility. Stakeholders must monitor state-level CARB amendments and pending EPA updates to small container emission thresholds.
Market Dynamics
Electric pump technology is displacing gravity feed systems across municipal and emergency fleet operations, compressing supplier margins on legacy mechanical designs while creating certification barriers for new entrants lacking UL and CSA electrical approvals.
Growth Catalysts
- OSHA 29 CFR 1926.152:Workplace fuel handling standards mandate secondary containment and grounding provisions on construction sites, forcing fleet operators toward certified portable caddy procurement.
- Rotational molding:High-density polyethylene fabrication advances enable lighter, corrosion-resistant caddy construction that reduces transport costs for agricultural operators.
- Texas oilfield services:Remote drilling and fracking operations require mobile refueling infrastructure that standard fixed tanks cannot address.
Market Restraints
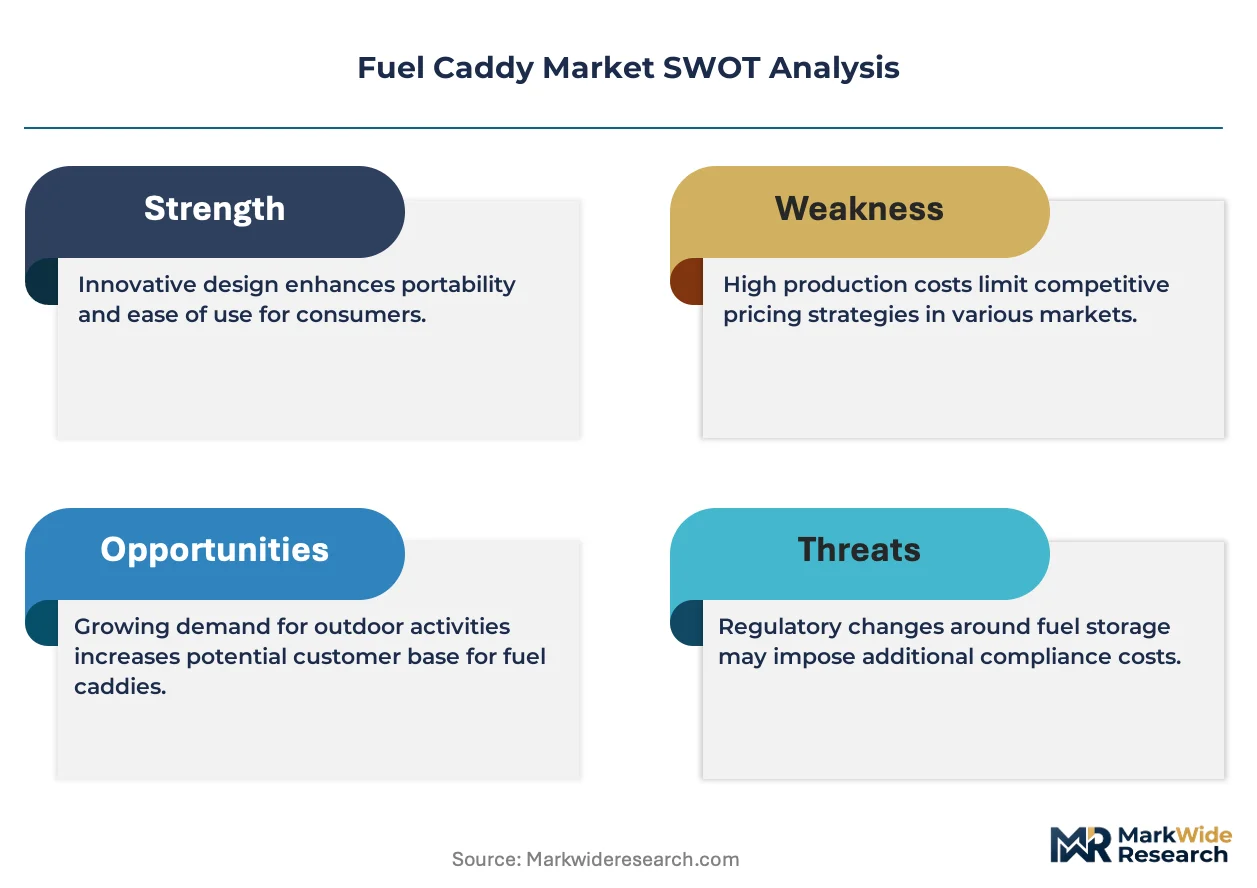
- Steel input volatility:Welded steel caddy fabrication faces margin compression from scrap metal price swings and domestic mill capacity constraints.
- CARB certification friction:California Air Resources Board spout emission standards create 12-18 month approval timelines that freeze product launches for non-specialist manufacturers.
- Battery-powered equipment substitution:Electric construction machinery and battery-swapping systems threaten diesel caddy demand in urban municipal fleets.
Strategic Opportunities
- Great Lakes manufacturing corridors:Underpenetrated tier-two automotive suppliers lack dedicated fuel containment infrastructure for backup generator operations.
- IoT sensor convergence:Integration of level monitoring and leak detection telemetry creates recurring revenue streams through predictive maintenance contracts.
- EPA 40 CFR 112 amendments:Pending small container emission threshold reductions will force older caddy replacement cycles across existing installed base.
Industry Challenges
- Rotational molding technician scarcity:Specialized HDPE welding and mold maintenance skills concentrate at Scepter Corporation and a handful of Midwest fabricators.
- UL 142 certification timelines:Aboveground tank electrical and fire safety approvals stretch 14-20 months, freezing capital deployment for product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Caddy Market |
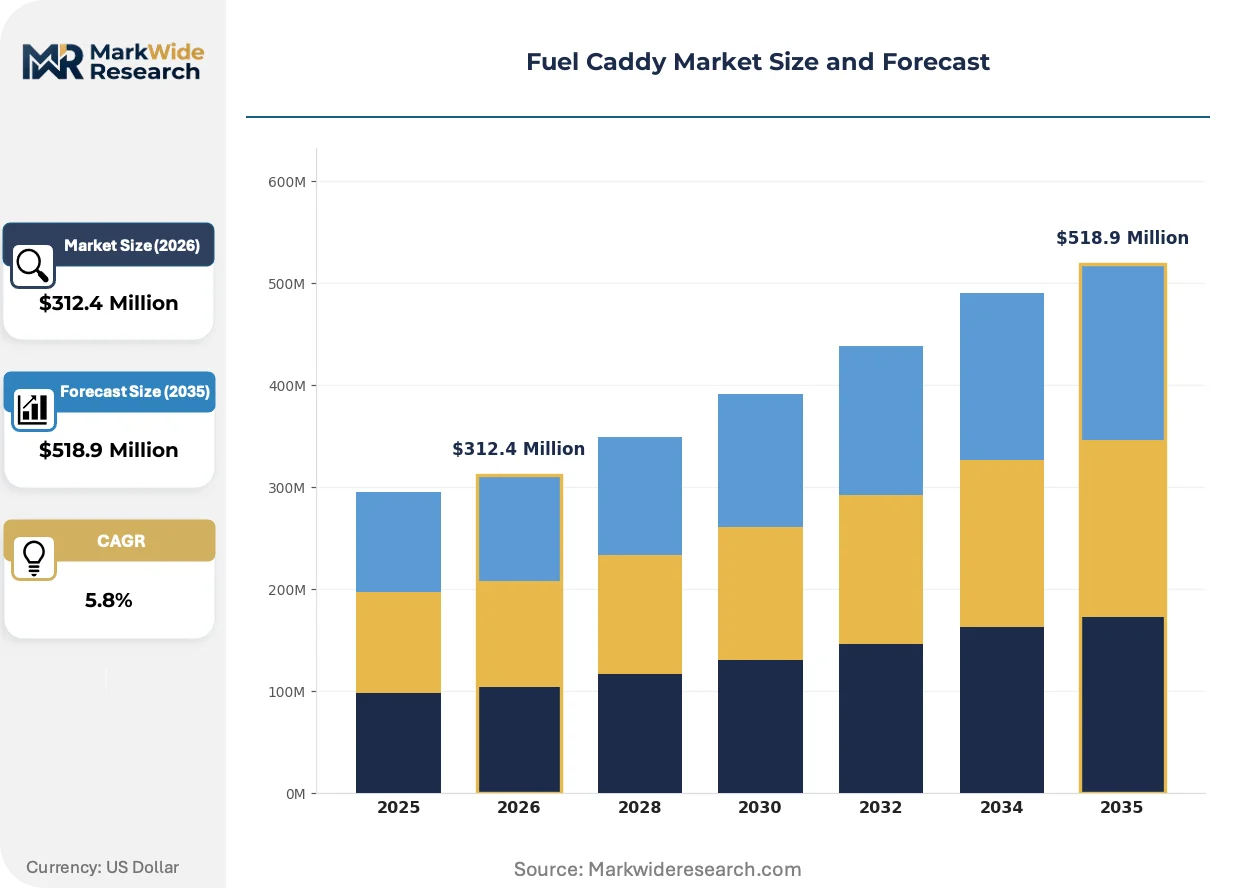
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Caddies, Stationary Tanks, Fuel Transfer Pumps, Gravity Feed Systems End User: Construction Sites, Agricultural Operations, Automotive Industry, Emergency Services Capacity: Below 20 Gallons, 20-50 Gallons, 51-100 Gallons, Above 100 Gallons Material: Plastic, Steel, Aluminum, Composite |
| Companies Covered | Scepter Corporation, No-Spill Inc., Midwest Can Company, FLO-FAST, John Dow Industries, Garage Boss, RotopaX Legacy LLC, ARKSEN, VEVOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Caddy Market Evolving Landscape
Electrification of dispensing systems and embedded telemetry are compressing the traditional mechanical caddy value chain while opening subscription revenue pools. These shifts favor suppliers with electrical engineering capabilities over legacy rotational molders.
Electric pump systems are migrating from niche emergency services applications toward mainstream construction and agricultural fleets. Municipal procurement departments now specify 12V or 110V pump compatibility as standard, forcing gravity feed specialists to outsource electrical subassembly production. This technology migration is compressing the addressable market for purely mechanical caddy suppliers while expanding margin capture for integrated pump manufacturers.
EPA spill prevention enforcement under 40 CFR 112 is tightening secondary containment specifications for portable fuel containers under 55 gallons. Fabricators must now engineer double-wall construction or external containment basins into compact form factors. Agricultural cooperatives in Iowa and Illinois face the steepest compliance costs due to dispersed equipment footprints and limited on-site technical support.
Fleet maintenance departments are consolidating vendor relationships and demanding bundled fuel containment, dispensing, and monitoring solutions. Distributors with single-product caddy lines lose shelf space to integrated industrial supply houses. This consolidation pattern concentrates in Texas oilfield services and Great Lakes manufacturing corridors where procurement standardization reduces supplier management overhead.
Fuel Caddy Market Segmentation
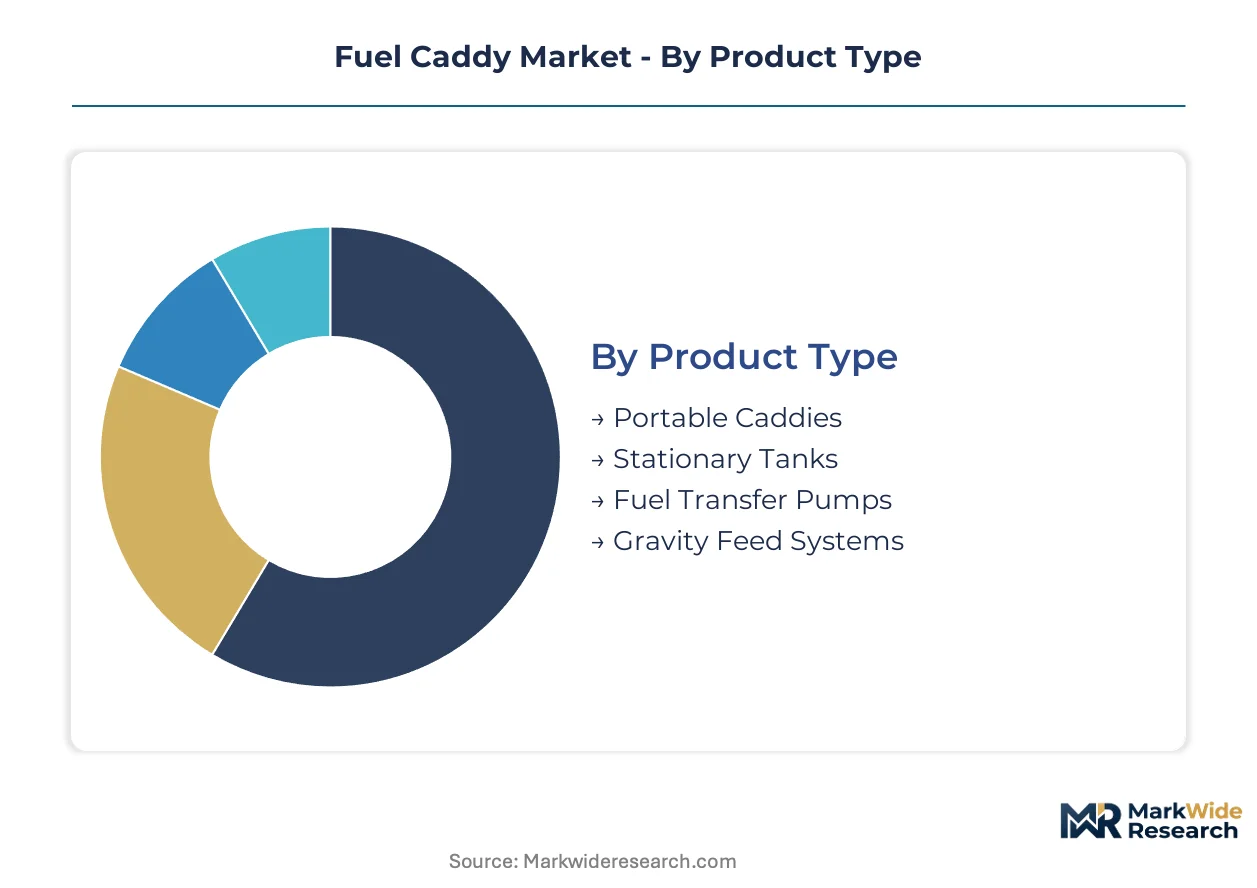
Fuel caddy segmentation reveals distinct procurement cycles across product architectures and use environments. Construction fleet managers rotate portable units on 3-5 year replacement schedules while agricultural operators extend stationary tank lifecycles beyond a decade.
Product Type:
Portable caddies turn over fastest due to OSHA mobility mandates and jobsite damage, while stationary tanks depreciate slowly with minimal regulatory pressure for replacement.
- Portable Caddies:High-density polyethylene or welded steel containers with integrated wheels, pumps, and spill containment. Demand concentrates in Texas oilfield services where remote drilling sites require daily repositioning and EPA 40 CFR 112 secondary containment compliance drives certified unit procurement.
- Stationary Tanks:Fixed-position aboveground storage systems with UL 142 fire safety certification. Agricultural cooperatives in Iowa and Illinois anchor demand for 500+ gallon installations serving dispersed equipment fleets.
- Fuel Transfer Pumps:Electric or manual dispensing mechanisms sold as standalone accessories or integrated systems.
- Gravity Feed Systems:Mechanical dispensing without powered pumps, facing structural decline as municipal fleets mandate electric alternatives.
Portable caddies anchor the volume base while fuel transfer pumps gain share at the steepest rate through fleet bundling requirements.
End User:
Customer procurement sophistication varies sharply—emergency services specify telemetry-integrated systems while agricultural buyers prioritize upfront cost over feature depth.
- Construction Sites:OSHA 29 CFR 1926.152 mandates secondary containment and grounding on temporary worksites. Great Lakes manufacturing corridors drive replacement demand as tier-two automotive suppliers upgrade backup generator fuel infrastructure.
- Agricultural Operations:Seasonal equipment refueling across dispersed farm footprints. Iowa and Illinois cooperatives face steepest EPA compliance costs due to limited on-site technical support for spill prevention system maintenance.
- Automotive Industry:Fleet maintenance departments and manufacturing facility backup power operations.
- Emergency Services:Fire departments and disaster response units requiring 12V/110V pump compatibility and rapid deployment certification.
Construction sites anchor the volume base while emergency services gain share at the steepest rate through municipal procurement standardization.
Capacity:
Mid-range capacities command premium positioning through fabrication complexity barriers, while small-format units face commoditization from retail channel saturation.
- Below 20 Gallons:Compact containers for light-duty consumer and small contractor use. California CARB spout emission standards constrain product launches with 12-18 month approval timelines freezing non-specialist manufacturer entry.
- 20-50 Gallons:Welded steel construction in this band captures the strongest margin pool. Texas oilfield services and Great Lakes manufacturing corridors concentrate demand where transport weight limits and OSHA mobility requirements intersect.
- 51-100 Gallons:Intermediate commercial and light industrial applications.
- Above 100 Gallons:Large-scale agricultural and fixed industrial installations with extended depreciation schedules.
20-50 gallon units anchor the volume base while below 20 gallon segments gain share at the steepest rate through retail channel expansion.
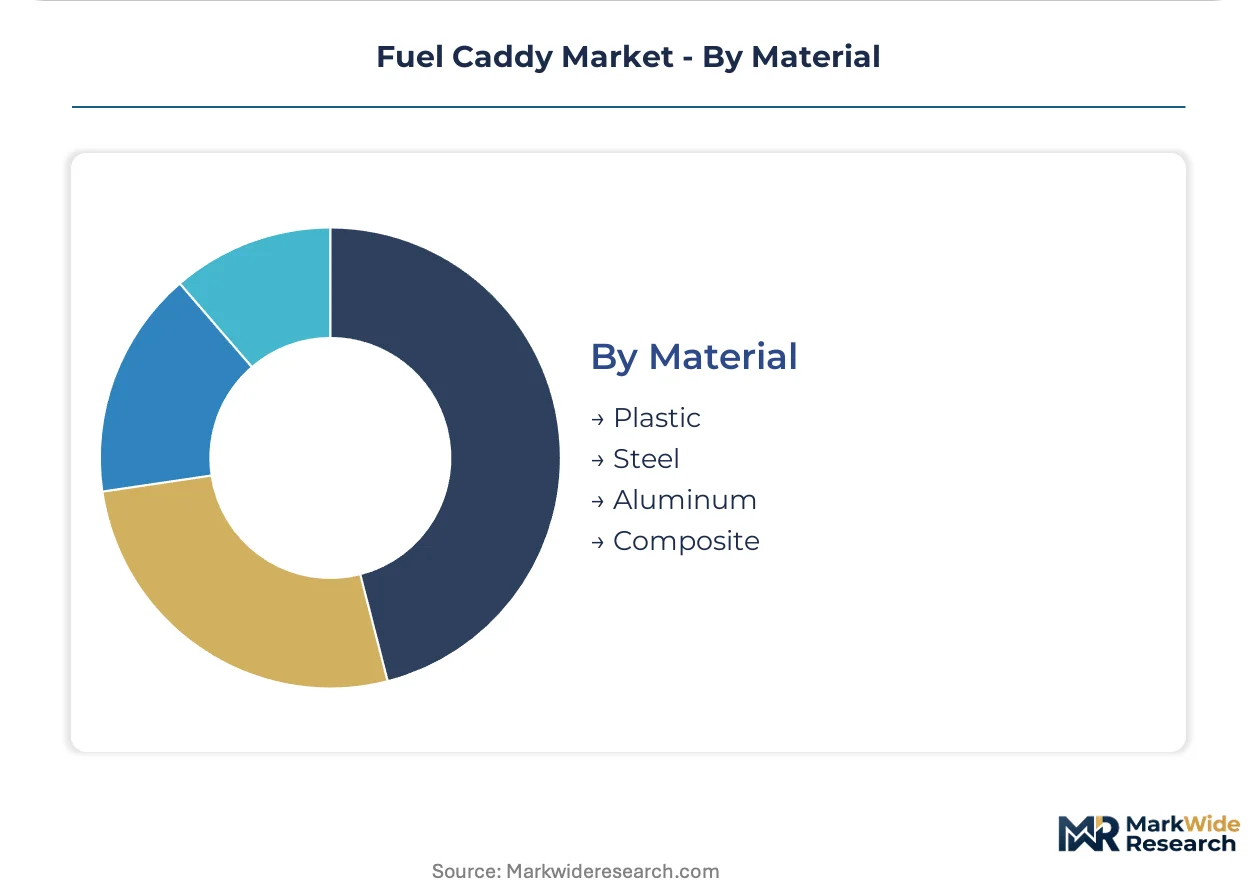
Material:
Material selection trades corrosion resistance against structural integrity, with fabrication technique scarcity determining supplier concentration.
- Plastic:Rotational-molded high-density polyethylene enabling lighter transport weights and chemical resistance. Scepter Corporation and Midwest fabricators concentrate specialized HDPE welding and mold maintenance capabilities.
- Steel:Welded fabrication for high-capacity and high-pressure applications. Scrap metal price volatility and domestic mill capacity constraints compress margins for non-vertically integrated suppliers.
- Aluminum:Lightweight alternative for aviation and specialized transport applications with premium positioning.
- Composite:Emerging multi-material constructions combining structural and corrosion-resistant properties.
Plastic construction anchors the volume base while composite materials gain share at the steepest rate through performance-tier differentiation efforts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize OSHA-compliant mobility for construction sites, while European buyers emphasize REACH-certified stationary containment for agricultural cooperatives, and Canadian procurement focuses on extreme-climate durability specifications.
United States
Texas oilfield services and Great Lakes manufacturing corridors drive portable caddy procurement for remote drilling and backup generator operations. EPA 40 CFR 112 spill prevention rules mandate secondary containment for containers under 55 gallons, forcing fleet operators toward certified units. Houston-based drilling contractors rotate equipment daily across dispersed fracking sites.
Germany
Industrial machinery exporters and agricultural cooperatives anchor demand for high-capacity stationary tanks with integrated pump systems. REACH chemical safety regulations and ADR transport standards constrain portable caddy dimensions for cross-border highway mobility. Bavarian automotive tier-two suppliers upgrade fuel containment infrastructure for emergency power systems.
Canada
Mining operations in Alberta and remote construction projects in northern territories require cold-weather-rated polyethylene construction. Transport Canada TDG regulations and provincial workplace safety standards govern highway transport and secondary containment. Calgary-based oilfield services firms procure heated tank systems for sub-zero deployment.
Australia
Drought-resistant agricultural operations in Queensland and Western Australia drive demand for corrosion-resistant stationary tanks with extended depreciation schedules. Work Health and Safety regulations and EPA state-level spill prevention mandates shape certification requirements. Perth-based mining contractors specify heavy-duty steel construction for fly-in-fly-out remote site operations.
Brazil
Soybean and sugarcane cooperatives in Mato Grosso and São Paulo states require large-capacity fuel storage for seasonal equipment fleets. ANVISA industrial safety standards and CONTRAN transport regulations govern tank fabrication and highway mobility. Campinas-region agricultural equipment distributors bundle containment systems with tractor procurement packages.
Fuel Caddy Market Competitive Landscape
Capability concentration sits with rotational molding specialists; scale advantage sits with integrated pump manufacturers. The vendor base organizes into three tiers: HDPE fabrication specialists with captive mold maintenance capabilities, steel tank fabricators exposed to scrap metal volatility, and electrical subsystem integrators capturing margin from pump-integrated bundling. Dominant competitive moves include backward integration into pump manufacturing and geographic expansion through distributor acquisition.
Within the rotational molding tier, Scepter Corporation exemplifies specialized HDPE fabrication capability concentration. No-Spill Inc. occupies a position within emission-certified spout technology, representing California-market premium positioning. Midwest Can Company anchors Midwest distribution archetype through retail channel relationships. These three players illustrate how material expertise, regulatory certification, and geographic channel control segment competitive positioning.
| Leading Market Players |
|---|
| Scepter Corporation |
| No-Spill Inc. |
| Midwest Can Company |
| FLO-FAST |
| John Dow Industries |
| Garage Boss |
| RotopaX Legacy LLC |
| ARKSEN |
| VEVOR |
| Others |
Value Network & Pricing Analysis
Overcapacity in rotational-molded HDPE fabrication across the US Midwest compresses supplier margins while concentrating pricing power with integrated pump manufacturers who bundle electrical subsystems. Texas oilfield services procurement teams exploit this fragmentation through consolidated vendor negotiations, forcing pure-play fabricators toward cost-plus contract structures.
Pricing Analysis
Long-term offtake agreements dominate Texas oilfield services procurement, with Houston-based drilling contractors locking in 3-5 year supply contracts for certified portable caddies. Three-tier pricing structure across premium, standard, and economy levels separates UL-listed electric pump systems from CARB-certified gravity feed units and uncertified imports. Cost compression in steel-fabricated caddies intensifies because domestic mill capacity constraints and scrap metal volatility squeeze non-vertically integrated suppliers. Agricultural cooperatives in Iowa and Illinois exhibit highest price sensitivity due to seasonal cash flow patterns, while emergency services municipal procurement shows lowest sensitivity given federal grant funding availability.
Supply Chain Analysis
Upstream HDPE resin supply draws from Gulf Coast petrochemical complexes, Canadian Alberta feedstock, and imported Asian polymer grades. Raw material dependencies center on high-density polyethylene pellets, 12V/110V pump subassemblies from Chinese electrical manufacturers, and precision mold tooling from German and Japanese suppliers. Single-source vulnerability concentrates in rotational molding technician labor pools, where Scepter Corporation and a handful of Midwest fabricators hold captive mold maintenance capabilities. Distribution runs through industrial supply houses consolidating fuel containment, dispensing, and monitoring solutions, squeezing single-product caddy distributors out of shelf space in Texas and Great Lakes corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel caddy demand sits in early-cycle expansion as EPA 40 CFR 112 amendments force replacement cycles across existing installed base, with pending small container emission threshold reductions accelerating certified unit procurement ahead of compliance deadlines.
For Market Incumbents: Pre-empt battery-powered equipment substitution by accelerating backward integration into electric pump manufacturing and securing UL/CSA electrical approvals before certification timelines freeze competitor entry. Anchor capacity addition in Texas to capture oilfield services consolidation, while deepening channel control through distributor acquisition in underpenetrated Great Lakes manufacturing corridors. For New Entrants and Emerging Players: Pursue white-space opportunity in IoT sensor convergence for predictive maintenance contracts, targeting municipal emergency services fleets standardizing on telemetry-integrated systems. The most penetrable entry point lies in 20-50 gallon welded steel caddies for Great Lakes tier-two automotive suppliers lacking dedicated fuel containment infrastructure. Go-to-market execution should emphasize bundled fuel containment and monitoring solutions rather than single-product lines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrical subsystem integrators capturing margin from pump-integrated bundling, positioning these archetypes for superior cash flow quality across a 5-10 year viability window. Acquisition targets should concentrate on rotational molding specialists with captive mold maintenance capabilities and established CARB certification track records. The signal to watch is EPA small container emission threshold amendment timing, which will trigger accelerated replacement demand across agricultural and construction installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Manufacturing | Captures margin from electrical subsystem bundling demanded by municipal procurement standardization. |
| CARB Certification Investment | Unlocks premium positioning in California markets where 12-18 month approval timelines freeze non-specialist entry. |
| IoT Sensor Platform Development | Creates predictive maintenance subscription revenue streams through level monitoring and leak detection telemetry. |
| Distributor Acquisition in Great Lakes | Consolidates channel control for tier-two automotive supplier backup generator fuel infrastructure upgrades. |
| Rotational Molding Technician Training | Addresses specialized HDPE welding scarcity concentrating at incumbent fabricators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, OSHA regulatory filings, and customs trade records. Primary interviews engaged procurement directors at Texas oilfield services firms, maintenance supervisors at Iowa and Illinois agricultural cooperatives, and compliance officers at Great Lakes manufacturing facilities. Secondary validation drew from DOT hazardous materials transport rulemakings, CARB certification registries, and UL/CSA electrical approval databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across product type, capacity band, and end-use segment dimensions.
Forecast inputs span electric pump technology penetration rates, EPA 40 CFR 112 amendment implementation timelines, and steel input price volatility indices. Segmentation modeling covers portable versus stationary architecture, 20-50 gallon versus below-20-gallon capacity tiers, plastic versus steel material construction, and construction versus agricultural versus emergency services end-use categories. CAGRs derive from regression analysis of historical replacement cycles against regulatory compliance deadline clustering.
Sensitivities concentrate around EPA small container emission threshold finalization dates, battery-powered construction equipment substitution velocity, and rotational molding labor pool expansion. Cross-checking against OSHA construction site inspection citation rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market