
 Capillary Underfill Material Market | 2026-2036
Capillary Underfill Material Market Size, Share, and Industry Trends Forecast 2026-2036
Capillary Underfill Material Market Analysis
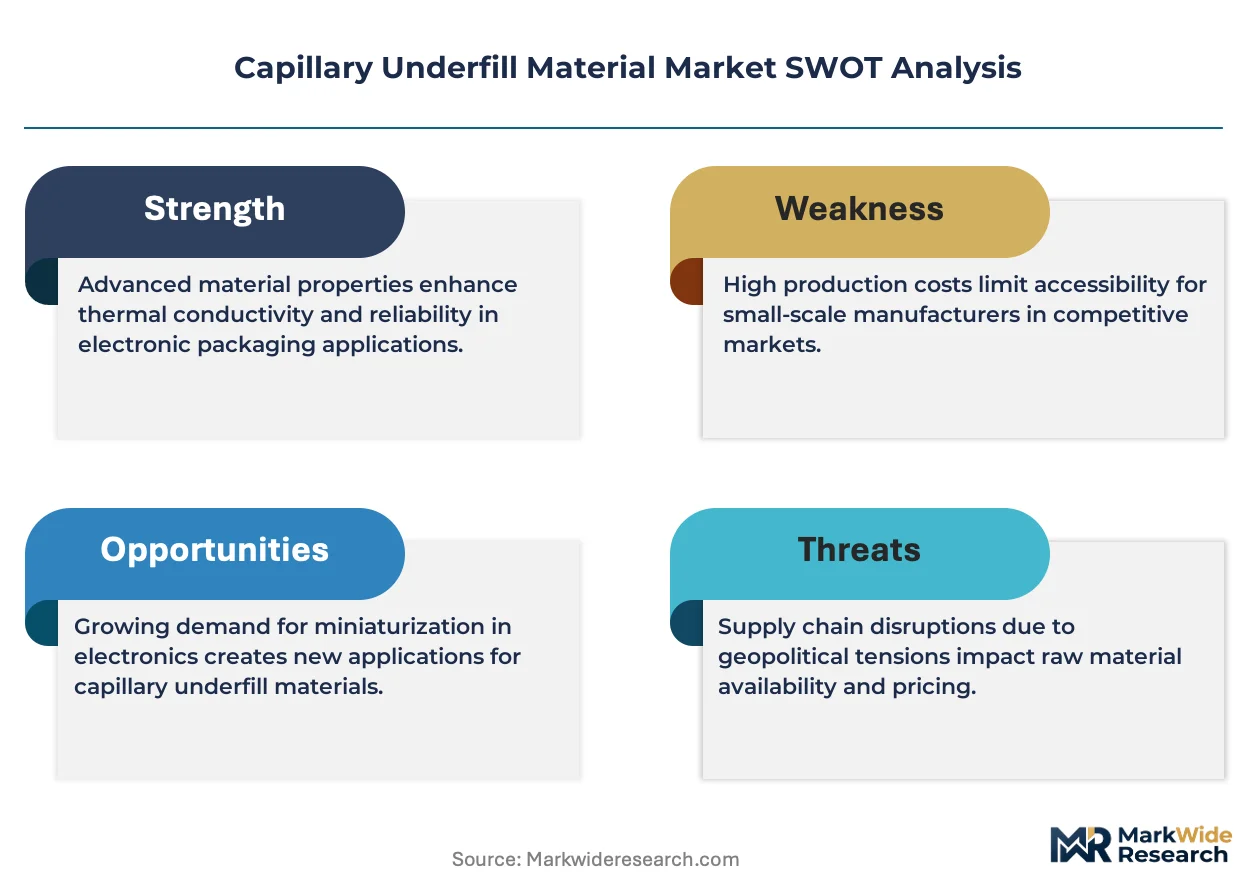
JEDEC J-STD-030 qualification for capillary underfill materials is reorganizing competitive access, as only formulations passing thermal cycling and moisture resistance benchmarks qualify for high-reliability semiconductor packaging. Henkel AG & Co. KGaA leverages its adhesive chemistry heritage to dominate automotive-grade underfill supply chains. H.B. Fuller anchors North American electronics manufacturing through localized production and technical service density. YINCAE Advanced Material specializes in ultra-low viscosity formulations for fine-pitch flip-chip applications.
Capillary underfill material denotes a liquid encapsulant dispensed into the gap between a silicon die and substrate, typically an epoxy resin system with silica filler loading of 50-70% by weight, designed to mitigate thermal-mechanical stress through coefficient of thermal expansion matching. The material flows via capillary action after die attach, then cures to protect solder interconnects from fatigue failure during temperature cycling. Epoxy formulations occupy the largest volume share due to proven adhesion and reworkability, while silicone segments capture premium positioning in high-temperature automotive modules. Ultra-low viscosity grades represent the fastest-growing viscosity tier, driven by shrinking bump pitches below 40 micrometers in advanced packaging.
REACH registration requirements in Europe and China's GB standards administered by SAMR constrain formulation chemistry, particularly restricting certain halogenated flame retardants and phthalate plasticizers in consumer electronics applications. The EPA's TSCA Section 5 premanufacture notification framework in the United States adds another gate for novel resin chemistries seeking commercial introduction. Stakeholders must monitor evolving halogen-free mandates across multiple jurisdictions and pre-qualify alternative chemistries before existing formulations face sunset provisions.
Market Dynamics
Flip-chip packaging architectures below 40 micrometer bump pitch are compressing traditional underfill viscosity specifications and forcing reformulation cycles across epoxy resin suppliers.
Growth Catalysts
- Advanced packaging proliferation:2.5D and 3D integration in high-performance computing is multiplying die-to-substrate gap control requirements. Taiwan's foundry cluster anchors this demand concentration.
- Automotive electrification:Power module reliability standards under AEC-Q100 are mandating capillary underfill for inverter and onboard charger assemblies. This creates qualified material pull-through from tier-1 automotive electronics suppliers.
- China's dual carbon goals:MEE-administered carbon intensity targets are accelerating domestic OSAT adoption of low-cure-temperature formulations to reduce process energy consumption.
Market Restraints
- Silica filler supply concentration:High-purity spherical silica for 50-70% loading grades concentrates among Japanese and Chinese suppliers, creating input cost volatility during semiconductor cycle downturns.
- REACH registration friction:ECHA's Substance of Very High Concern listings are forcing halogen-free flame retardant qualification timelines that extend 18-24 months beyond traditional development cycles.
- Epoxy resin reworkability limits:Thermoset chemistry prevents die-level repair in high-value advanced packages, constraining adoption in prototyping and low-volume aerospace applications where silicone alternatives penetrate.
Strategic Opportunities
- India OSAT buildout:PLI scheme incentives for semiconductor assembly and testing are creating greenfield demand for localized underfill technical service and inventory positioning.
- Photonics packaging convergence:Co-packaged optics in AI accelerators is opening sub-20 micrometer gap control applications requiring refractive index-matched underfill formulations.
- EU Green Deal chemistry pivot:Bio-based epoxy precursors and recycled silica feedstocks qualify for CSRD-aligned procurement preferences among European automotive electronics buyers.
Industry Challenges
- JEDEC J-STD-030 certification timelines:Thermal cycling and moisture resistance qualification protocols require 12-18 month test matrices that compress product launch windows against foundry node transitions.
- Formulation IP fragmentation:Patent thickets around low-alpha particle silica surface treatments and anhydride curing agents complicate freedom-to-operate analysis for new market entrants.
- Process engineering talent scarcity:Capillary flow modeling and dispense pattern optimization expertise concentrates among senior technologists at established OSATs, constraining knowledge transfer to emerging packaging houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capillary Underfill Material Market |
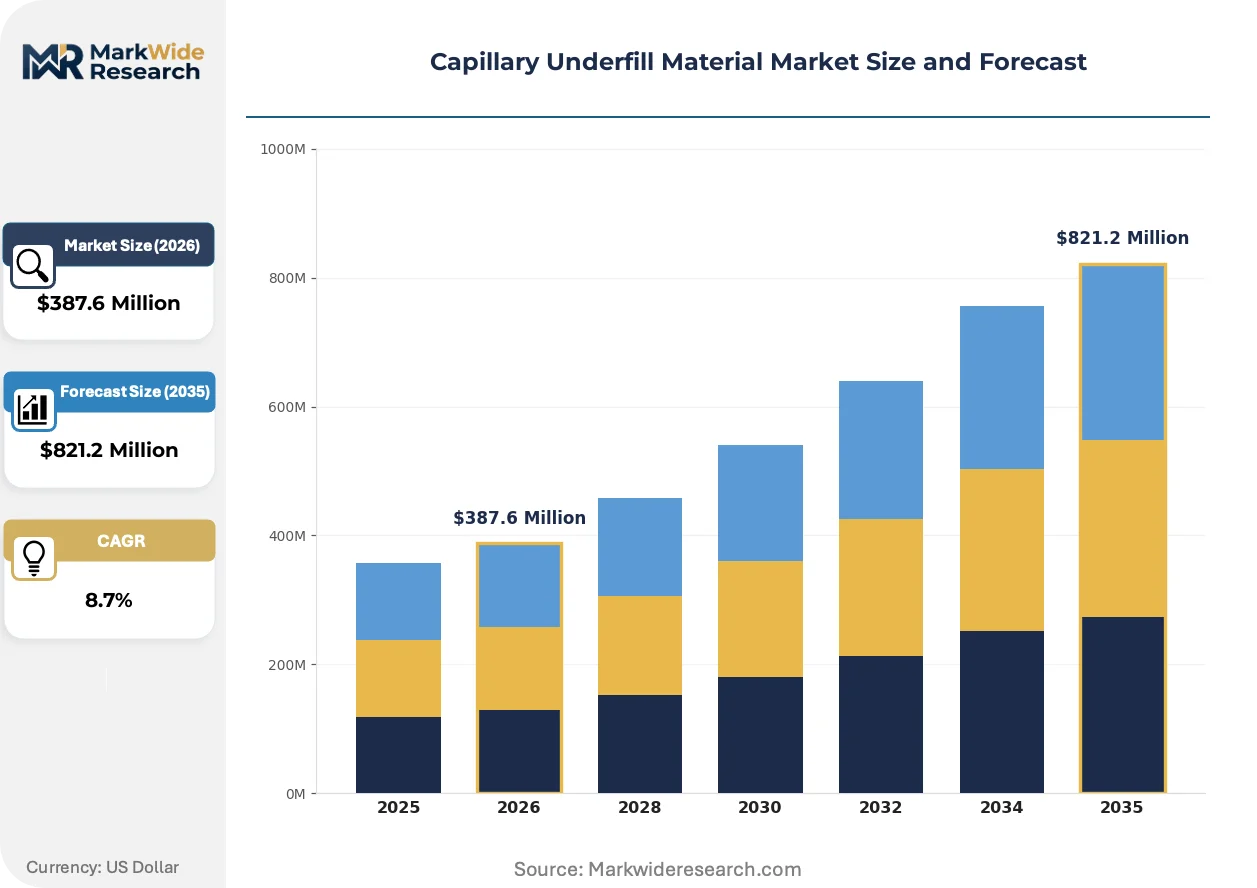
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyimide, Urethane Application: Semiconductors, Electronics, Automotive, Consumer Devices Viscosity: Low, Medium, High, Ultra-Low Packaging Type: Cartridge, Bulk, Single Dose, Drum |
| Companies Covered | H.B. Fuller, Zymet Inc., Nordson Corporation, Epoxy Technology Inc., YINCAE Advanced Material, Henkel AG & Co. KGaA, Master Bond Inc., WON CHEMICAL, NAMICS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capillary Underfill Material Market Emerging Trajectories
Material science and regulatory chemistry are converging to redefine performance benchmarks across semiconductor packaging tiers, with viscosity engineering and sustainability compliance emerging as the primary vectors of competitive differentiation.
Nano-silica-filled epoxy systems with particle size distributions below 100 nanometers are decomposing the traditional trade-off between flowability and mechanical reinforcement. Leading memory and logic packaging houses in South Korea and Taiwan are qualifying these formulations for 25 micrometer bump pitch applications. The technology is decomposing incumbent mid-viscosity product lines by enabling single-material coverage across previously segmented gap height ranges.
REACH authorization requirements for certain aromatic amine curing agents are restructuring European supply chains for high-reliability automotive underfill. Formulators must pre-register alternative latent curing chemistries before 2026 sunset provisions take effect. German automotive electronics suppliers are accelerating halogen-free qualification programs to maintain CE marking continuity under evolving RoHS delegated acts.
Consolidated procurement through foundry-direct material qualification programs is displacing traditional distributor-led technical selling in advanced packaging. OSATs in the United States are negotiating multi-year supply agreements with locked formulation specifications to reduce process variation. This pattern concentrates supplier relationships among three to four qualified vendors per packaging node, compressing competitive access for regional formulators.
Capillary Underfill Material Market Segmentation
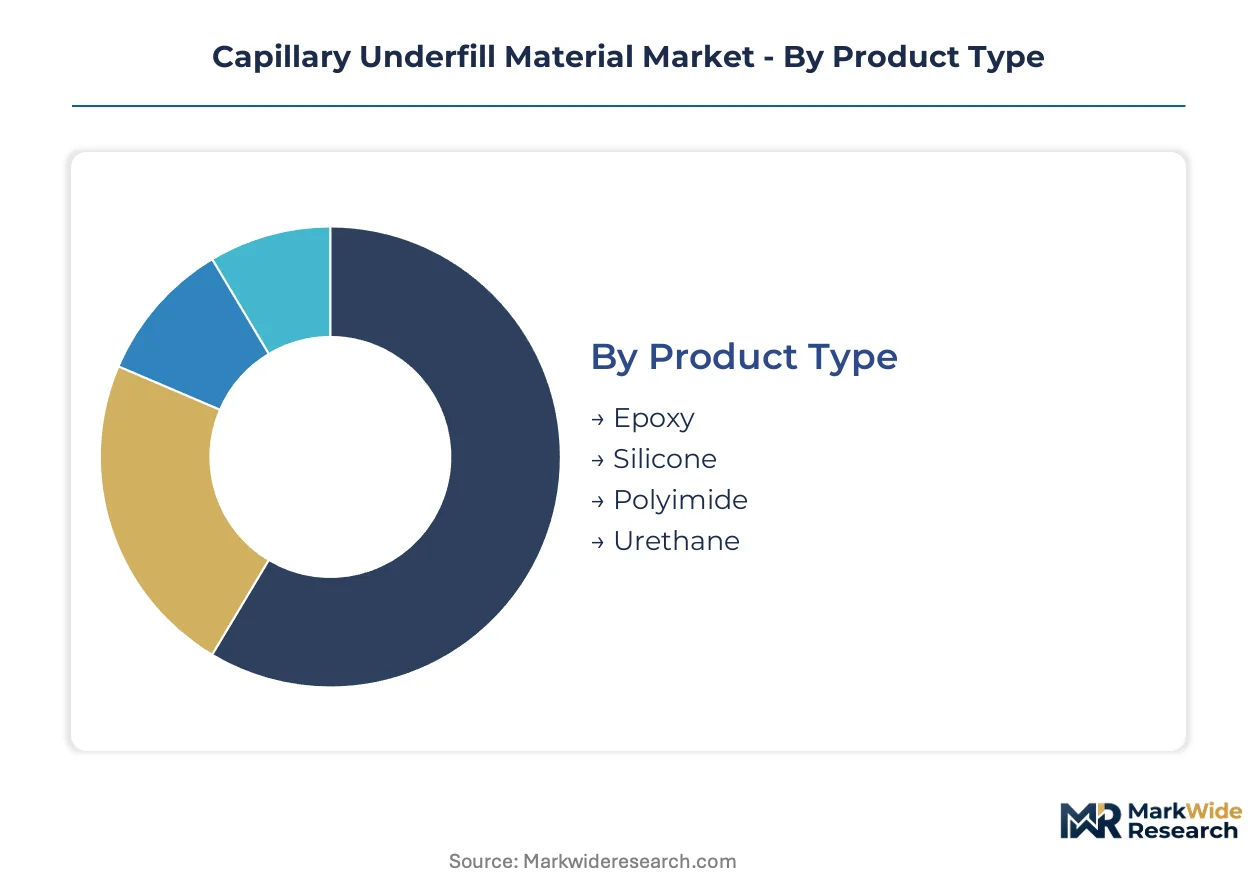
Capillary underfill material selection hinges on gap geometry, thermal cycling severity, and rework requirements that vary sharply across packaging architectures. Segmentation reveals where formulation chemistry faces displacement pressure from emerging alternatives and process innovations.
Product Type:
Silicone and polyimide formulations exert mounting substitution pressure on epoxy dominance, particularly in high-temperature and flexible substrate applications where thermoset limitations constrain design freedom.
- Epoxy:Thermoset resin systems loaded with 50-70% spherical silica by weight deliver proven adhesion and coefficient of thermal expansion matching for standard flip-chip assemblies. Taiwan's foundry cluster consumes the largest epoxy volumes as 2.5D packaging proliferation multiplies die-to-substrate gap control requirements. REACH authorization timelines for aromatic amine curing agents compress supplier margins and force pre-qualification of latent curing alternatives.
- Silicone:Elastomeric chemistry enables operation above 150°C continuous exposure with dielectric stability unmatched by epoxy alternatives. Automotive inverter modules under AEC-Q100 qualification pull silicone formulations into power electronics where thermal cycling extremes degrade conventional encapsulants. German automotive electronics suppliers accelerate halogen-free programs to maintain CE marking continuity.
- Polyimide:Aromatic heterocyclic backbone delivers the highest glass transition temperature among commercial underfill chemistries for aerospace and defense substrates.
- Urethane:Aliphatic isocyanate systems offer reworkability through controlled thermal depolymerization for prototyping and low-volume medical device packaging.
Epoxy anchors the volume base while silicone gains share at the steepest rate.
Application:
Automotive electrification is restructuring demand concentration as power module reliability standards displace consumer electronics from the top revenue tier.
- Semiconductors:Logic and memory packaging houses in South Korea and Taiwan drive ultra-low viscosity qualification for bump pitches below 40 micrometers. Nano-silica-filled systems decompose the flowability-mechanical reinforcement trade-off across previously segmented gap height ranges. JEDEC J-STD-030 certification timelines compress product launch windows against foundry node transitions.
- Automotive:Onboard charger and DC-DC converter assemblies mandate capillary underfill for solder joint fatigue resistance under AEC-Q100 thermal cycling protocols. Tier-1 electronics suppliers in Germany and Japan qualify materials through locked specification multi-year agreements. China's dual carbon goals accelerate domestic OSAT adoption of low-cure-temperature formulations.
- Electronics:Industrial control modules and telecommunications infrastructure represent stable demand for mid-viscosity epoxy grades with proven field reliability.
- Consumer Devices:Smartphone and wearable packaging prioritizes cost-optimized formulations where miniaturization pressures meet compressed development cycles.
Semiconductor applications concentrate the highest absolute volumes while automotive expands most quickly.
Viscosity:
Shrinking bump pitches are collapsing the addressable market for high-viscosity grades as gap control requirements fragment the specification landscape.
- Ultra-Low:Formulations below 500 centipoise enable complete gap fill in sub-25 micrometer bump pitch applications for AI accelerator co-packaged optics. South Korean memory packaging houses qualify these grades for heterogeneous integration where refractive index matching becomes critical. Photonics packaging convergence opens sub-20 micrometer gap control applications requiring optical property engineering.
- Low:Standard fine-pitch flip-chip coverage dominates mobile processor and baseband packaging with balanced flow speed and filler suspension stability.
- Medium:Legacy bump pitch ranges above 80 micrometers sustain demand in automotive radar and industrial sensor modules.
- High:Restricted to large die applications with gap heights exceeding 100 micrometers where sag resistance outweighs flow speed requirements.
Ultra-Low viscosity climbs the fastest while Medium viscosity retains the largest installed base.
Packaging Type:
Consolidated foundry-direct procurement is displacing distributor-led technical selling and concentrating volume in bulk and cartridge formats.
- Cartridge:30cc and 55cc syringe barrels dominate high-mix OSAT environments where rapid material changeover minimizes line downtime. United States-based packaging houses negotiate multi-year supply agreements with locked formulation specifications to reduce process variation.
- Bulk:Pail and pail-liner systems serve high-volume memory packaging lines in Taiwan with automated dispense systems and integrated degassing.
- Single Dose:Pre-measured pouches eliminate operator weighing errors in aerospace and medical device prototyping where batch traceability is mandatory.
- Drum:200-liter containers anchor raw material supply for captive formulation operations at integrated device manufacturers.
Cartridge formats dominate technical service relationships while bulk packaging captures the steepest volume expansion in foundry-direct programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung harbor complex underwrites Taiwan's dominance in semiconductor packaging logistics, with dedicated chemical terminals serving foundry clusters. This infrastructure anchors the highest-volume consumption node for capillary underfill materials worldwide.
Taiwan
Taiwan's foundry cluster drives ultra-low viscosity qualification for sub-40 micrometer bump pitch architectures. The Ministry of Economic Affairs enforces GB-aligned chemical substance reporting through its Industrial Development Bureau. Hsinchu Science Park concentrates captive formulation operations where leading OSATs negotiate multi-year supply agreements with locked specifications.
South Korea
South Korean memory packaging houses qualify nano-silica-filled systems for heterogeneous integration applications. The Ministry of Trade, Industry and Energy administers K-REACH registration requirements that parallel European chemical safety frameworks. Seoul Capital Area packaging facilities consume the largest regional volumes of ultra-low viscosity grades for AI accelerator production.
United States
United States-based advanced packaging operations concentrate demand for automotive-grade underfill under AEC-Q100 protocols. The EPA's TSCA Section 5 framework gates novel resin chemistry introductions through premanufacture notification requirements. Arizona and Texas foundry buildouts are creating greenfield demand for localized technical service and inventory positioning.
China
China's domestic OSAT expansion accelerates adoption of low-cure-temperature formulations to meet MEE-administered carbon intensity targets. SAMR-enforced GB standards restrict halogenated flame retardants in consumer electronics applications. Yangtze River Delta packaging clusters anchor the steepest volume growth as dual carbon goals reshape process energy consumption profiles.
Germany
German automotive electronics suppliers mandate halogen-free qualification programs to maintain CE marking continuity under evolving RoHS delegated acts. ECHA's Substance of Very High Concern listings force 18-24 month alternative chemistry qualification timelines. Bavaria-based tier-1 suppliers concentrate multi-year locked specification agreements for power module reliability standards.
Capillary Underfill Material Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and technical service density. The supplier base concentrates around three to four qualified vendors per packaging node, compressing access for regional formulators. Strategic archetypes include diversified adhesive conglomerates, captive electronics chemical divisions, and pure-play packaging material specialists. Competitive moves center on foundry-direct qualification programs and multi-year supply agreements with locked specifications.
Within the diversified adhesive tier, Henkel AG & Co. KGaA and H.B. Fuller exemplify scale-driven positions anchored by heritage chemistry capabilities and geographic production footprints. YINCAE Advanced Material occupies a specialist position focused on viscosity-engineered formulations for fine-pitch applications. These three entities represent the core competitive set across automotive-grade qualification and advanced packaging nodes.
| Leading Market Players |
|---|
| H.B. Fuller |
| Zymet Inc. |
| Nordson Corporation |
| Epoxy Technology Inc. |
| YINCAE Advanced Material |
| Henkel AG & Co. KGaA |
| Master Bond Inc. |
| WON CHEMICAL |
| NAMICS Corporation |
| Others |
Supply Flow & Price Mechanics
Multi-year locked specification agreements between OSATs and qualified formulators anchor both supply security and price predictability across Taiwan's foundry cluster, compressing spot market liquidity while embedding silica filler cost pass-through mechanisms into contract structures.
Pricing Analysis
Three-tier pricing structure across JEDEC-certified automotive grades, industrial reliability tiers, and consumer electronics formulations segments buyer access. Price differentiation hinges on AEC-Q100 qualification status and spherical silica purity grades sourced from Japanese suppliers. Cost compression in standard epoxy grades intensifies as Chinese OSATs scale low-cure-temperature formulations under carbon intensity mandates. Automotive electronics suppliers exhibit lowest price sensitivity due to locked multi-year agreements, while consumer device packagers face acute margin pressure from foundry-direct procurement consolidation.
Supply Chain Analysis
Japan and China anchor spherical silica production for 50-70% filler loading grades, with high-purity spherical material concentrating among specialized chemical processors. Raw material dependencies extend to aromatic amine curing agents and latent epoxy hardeners subject to REACH authorization timelines. Single-source vulnerability in nano-silica surface treatment IP creates formulation lock-in risks for advanced packaging nodes. Distribution runs through foundry-direct technical service programs that displace traditional distributor relationships in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capillary underfill material demand sits in early-cycle expansion as sub-40 micrometer bump pitch architectures multiply die-to-substrate gap control requirements across AI accelerator and heterogeneous integration applications.
For Market Incumbents: Fortify JEDEC J-STD-030 certification portfolios through accelerated thermal cycling qualification to preempt emerging silicone formulation substitutes in automotive power modules. Deepen backward integration into spherical silica surface treatment capabilities to offset Japanese supplier concentration and capture margin from nano-filled grade premiums. Lock multi-year specification agreements with Arizona and Texas foundry buildouts before regional formulators establish technical service density. For New Entrants and Emerging Players: JEDEC J-STD-030 fast-track qualification programs open access to automotive electronics supply chains where incumbent relationships concentrate among three to four vendors per node. White-space targets include India OSAT greenfield operations under PLI scheme incentives and photonics packaging applications requiring refractive index-matched formulations for co-packaged optics. Pursue technical service partnerships with emerging memory packaging houses in South Korea seeking second-source qualification for ultra-low viscosity grades. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play packaging material specialists with captive nano-silica formulation capabilities and existing foundry-direct relationships. Long-term viability centers on qualification moats that extend 12-18 months beyond product development cycles, creating sticky revenue visibility across semiconductor node transitions. Monitor AEC-Q100 qualification pipeline velocity at German tier-1 automotive electronics suppliers as inflection indicator for automotive-grade material pull-through acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spherical Silica | Captive supply of high-purity filler reduces Japanese supplier dependency and secures nano-silica surface treatment IP. |
| JEDEC J-STD-030 Fast-Track Qualification | Compressed 12-18 month certification timelines enable foundry node alignment and preempt competitor lock-in. |
| Low-Cure-Temperature Formulation Launch | China MEE carbon intensity compliance positions products for domestic OSAT expansion under dual carbon goals. |
| Photonics Packaging Technical Partnership | Refractive index engineering capabilities capture co-packaged optics demand from AI accelerator architectures. |
| India OSAT Technical Service Expansion | PLI scheme incentives create greenfield demand for localized inventory positioning and application engineering. |
Methodological Framework
Cross-validation between primary interviews with OSAT process engineers, automotive electronics procurement leads, and epoxy resin R&D directors and secondary validation through SEMI shipment data, ECHA REACH registration filings, and foundry capex disclosures anchors the qualitative findings. Technical discussions with capillary dispense equipment specialists and spherical silica suppliers informed flowability-mechanical reinforcement trade-off analysis. Bottom-up demand modeling triangulates against top-down semiconductor packaging equipment spend patterns.
Sensitivity analysis across silica filler loading specifications, cure temperature requirements, and automotive certification tiers informs volume projections over the analysis window. Segmentation dimensions include resin chemistry, viscosity grade, packaging format, and regional foundry cluster concentration. CAGRs derive from packaging node transition timelines and AEC-Q100 qualification velocity. Forecast inputs incorporate MEE carbon intensity target enforcement and ECHA SVHC listing sunset provisions.
Underlying assumptions cover REACH authorization timeline adherence and foundry node transition schedules, with deviation risk concentrated in silica supply disruptions during semiconductor cycle downturns and alternative curing chemistry qualification delays. Recalibration cycles align with material shifts in JEDEC specification revisions and automotive electrification penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Asia-Pacific Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
South America Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
EV Adhesives Market