
 DLIF and XLIF Implants Market | 2026-2036
DLIF and XLIF Implants Market Size, Share, and Industry Trends Forecast 2026-2036
DLIF and XLIF Implants Market Outlook
Capital-intensity divergence between integrated manufacturers and assembly-focused competitors is bifurcating competitive dynamics in the DLIF and XLIF Implants Market. Stryker leverages its captive manufacturing of PEEK and titanium interbodies to sustain margin control across hospital and surgical center channels. Medtronic anchors its position through navigation-enabled XLIF workflows that differentiate procedural efficiency. NuVasive specializes in lateral access retractor systems that dominate the minimally invasive surgery segment.
DLIF and XLIF implants are lateral interbody fusion devices inserted through the psoas muscle corridor or pre-psoas oblique path, typically manufactured from titanium porous structures or radiolucent PEEK with bone graft windows to promote osteointegration. These implants restore disc height and sagittal alignment while minimizing posterior muscular disruption in degenerative disc disease and spondylolisthesis cases. Interbody implants constructed from titanium lead structural demand due to favorable modulus of elasticity and imaging compatibility, while PEEK variants occupy premium positioning for radiolucency-dependent navigation workflows. Minimally invasive surgery technology sustains the fastest expansion trajectory as robotics and imaging systems reduce neural retraction risk during lateral access.
FDA 510(k) premarket notification requirements govern implant biocompatibility and fatigue testing standards, while EU MDR technical documentation demands extend clinical evaluation obligations for lateral access systems in European markets. Japan's PMDA and METI coordinate on foreign manufacturer registration and quality management system audits that condition market entry for DLIF and XLIF device suppliers. Stakeholders must monitor evolving reimbursement coding for lateral interbody fusion procedures across Medicare, German DRG frameworks, and Japan's fee schedule revisions to anticipate volume shifts between hospital inpatient and outpatient surgical settings.
Market Dynamics
Navigation-integrated lateral access systems are compressing procedural learning curves while FDA 510(k) fatigue testing requirements extend development timelines for implant manufacturers seeking hospital contracts.
Growth Catalysts
- Minimally invasive surgery technology:Robotic guidance and intraoperative imaging reduce neural retraction risk during psoas corridor access, accelerating surgeon adoption in tertiary care centers.
- Medicare reimbursement coverage:Favorable DRG coding for lateral interbody fusion procedures sustains volume growth in US hospital inpatient and outpatient surgical settings.
- Aging demographics:Degenerative disc disease prevalence among patients over sixty-five concentrates demand in the United States, Germany, and Japan where surgical intervention rates remain elevated.
Market Restraints
- Titanium raw material volatility:Sponge and alloy price fluctuations compress margin predictability for manufacturers dependent on porous titanium interbody production.
- EU MDR technical documentation:Extended clinical evaluation obligations for lateral access systems delay European market entry and inflate regulatory compliance costs.
- Posterior lumbar interbody fusion:Established PLIF techniques with familiar reimbursement pathways constrain lateral approach penetration in cost-sensitive hospital systems.
Strategic Opportunities
- Ambulatory surgical centers:Outpatient migration of select fusion procedures creates channel expansion potential for implant suppliers with streamlined instrumentation sets.
- Pre-psoas oblique access:Anterior-to-psoas trajectory development reduces lumbar plexus injury risk, opening surgeon training opportunities beyond lateral access specialists.
- Japan's aging surgical population:Fee schedule revisions and PMDA foreign manufacturer registration pathways condition market entry for DLIF and XLIF device suppliers targeting metropolitan hospital clusters.
Industry Challenges
- Surgeon training bandwidth:Lateral access technique proficiency requires dedicated cadaveric lab investment and proctored case volume that academic medical centers struggle to allocate.
- EU MDR notified body capacity:Technical documentation review queues for lateral interbody fusion systems extend time-to-revenue for manufacturers targeting European hospital procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DLIF and XLIF Implants Market |
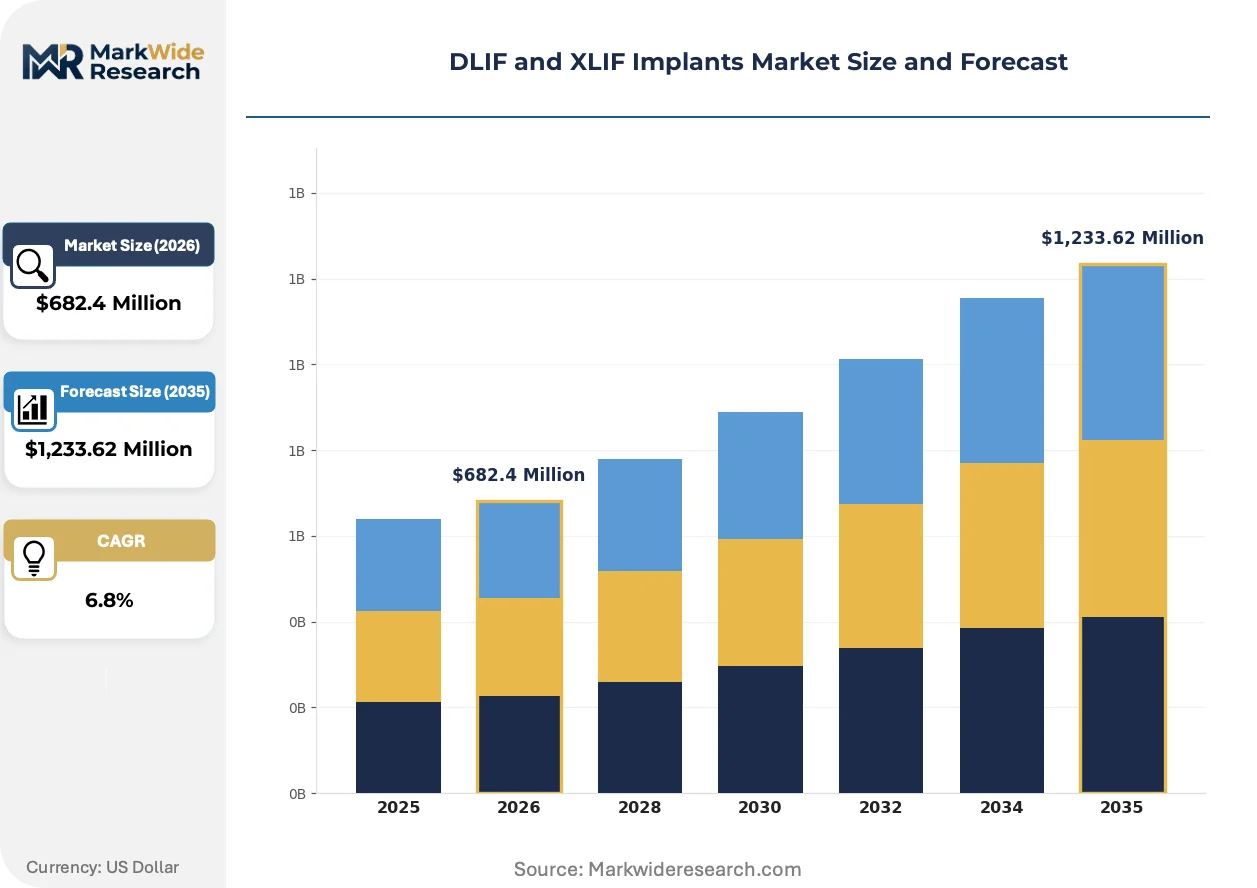
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,233.62 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interbody Implants, Biologics, Instrumentation, Access Systems End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Technology: Minimally Invasive Surgery, Robotics, Imaging Systems, Navigation Systems Material: Titanium, PEEK, Stainless Steel, Bone Grafts |
| Companies Covered | Stryker, Zimmer Biomet, Medtronic, Alphatec Spine, Orthofix Medical, NuVasive, DePuy Synthes, B. Braun, Globus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DLIF and XLIF Implants Market Strategic Shifts
Implant surface engineering and intraoperative navigation convergence are redefining procedural efficiency benchmarks while regulatory documentation demands reshape product development resource allocation.
3D-printed titanium porous structures with optimized pore geometries for osteointegration are displacing machined solid titanium interbodies in premium hospital segments. Academic medical centers and high-volume spine surgeons adopt these constructs for complex deformity and revision cases where bone graft incorporation speed determines outcomes. This displacement compresses commoditization pressure on conventional titanium manufacturing while elevating R&D investment thresholds for competitive participation.
EU MDR Article 10 technical documentation requirements mandate systematic clinical evaluation for lateral access retractor systems that previously operated under MDD equivalence pathways. European notified bodies now demand prospective data collection for psoas muscle corridor complications, extending certification timelines by twelve to eighteen months. Mid-cap manufacturers without legacy clinical databases face exclusion from German and French hospital tender processes where MDR compliance certificates constitute mandatory bid documentation.
Hospital value analysis committees now require bundled instrumentation and implant pricing for lateral interbody fusion procedures, collapsing separate line-item negotiations into comprehensive procedural contracts. This compression favors suppliers with full retractor, implant, and biologic portfolios while marginalizing component-only vendors. The shift is most visible in United States integrated delivery networks where orthopedic service line administrators consolidate spine implant spend across multiple hospital sites.
DLIF and XLIF Implants Market Segmentation
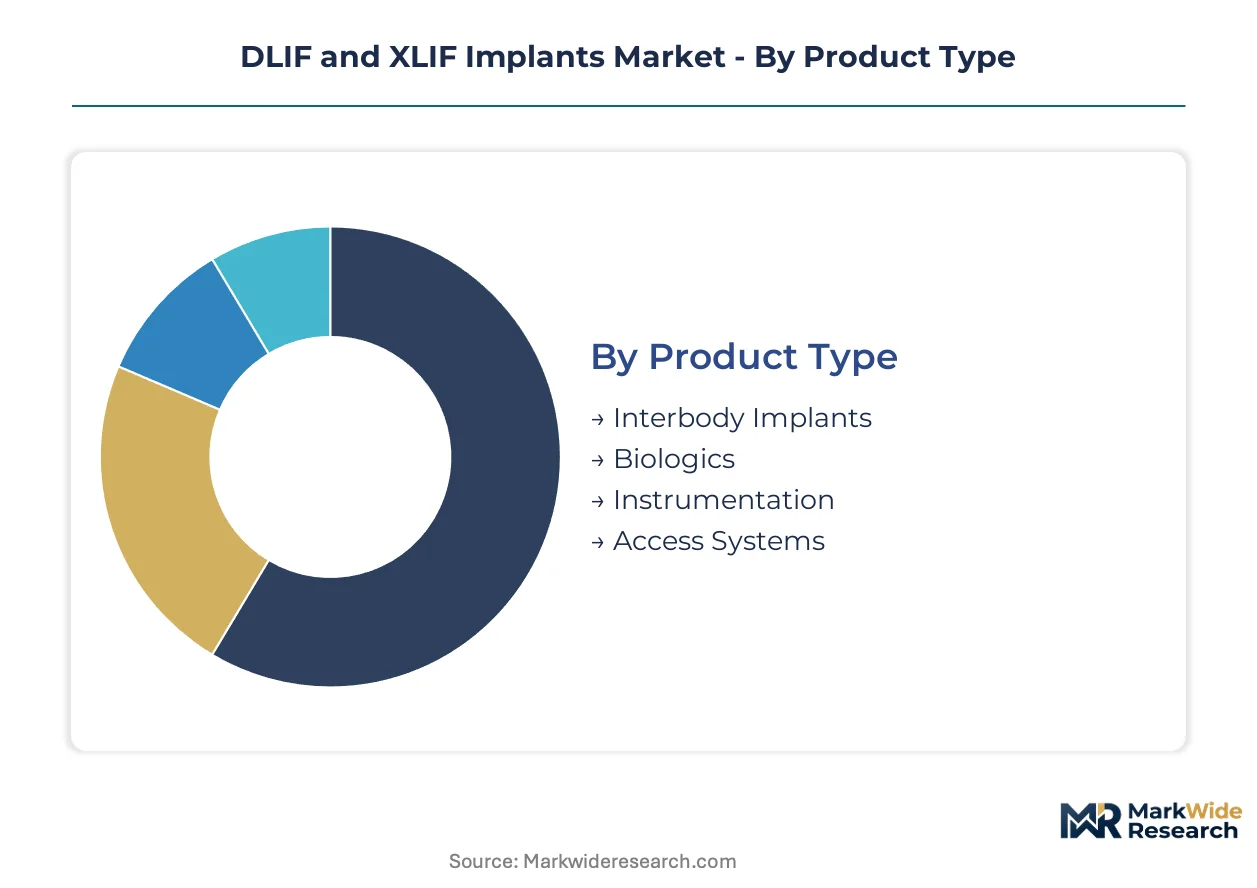
Segmentation in the DLIF and XLIF Implants Market reveals how regulatory pathways, reimbursement structures, and surgical workflow requirements reshape procurement priorities across hospital systems and ambulatory channels.
Product Type:
FDA 510(k) clearance complexity varies substantially by product category, with interbody implants facing distinct fatigue testing protocols compared to biologics or instrumentation sets.
- Interbody Implants:Titanium porous structures and PEEK constructs with bone graft windows restore disc height and sagittal alignment. Demand concentrates in tertiary care centers performing complex deformity corrections, where osteointegration speed determines revision risk and length-of-stay metrics.
- Biologics:Demineralized bone matrix and synthetic graft materials accelerate fusion consolidation in lateral interbody procedures. Adoption is climbing fastest in United States integrated delivery networks where bundled procedural payments incentivize bone healing optimization.
- Instrumentation:Retractor blades, disc preparation tools, and insertion instruments complete the surgical set.
- Access Systems:Lateral retractor frames and table-mounted positioning equipment enable psoas corridor visualization.
Established volume favors Interbody Implants; emerging adoption favors Biologics.
End User:
Reimbursement coding distinctions between inpatient DRG and outpatient APC frameworks are redirecting procedure volume across facility types.
- Hospitals:Academic medical centers and community hospital systems dominate complex lateral fusion cases requiring extended monitoring. United States Medicare DRG reimbursement sustains inpatient volume for multilevel procedures and patient populations with comorbidity burdens.
- Surgical Centers:Ambulatory facilities capture single-level fusions in healthy patients, with United States commercial payers expanding prior authorization pathways for outpatient lateral interbody fusion.
- Orthopedic Clinics:Preoperative planning and postoperative monitoring services support surgical volume.
- Rehabilitation Facilities:Post-fusion physical therapy protocols manage functional recovery timelines.
Procedure complexity anchors Hospitals; cost pressure and payer incentives are accelerating Surgical Centers.
Technology:
Capital equipment requirements and training infrastructure demands create divergent adoption curves across technology categories.
- Minimally Invasive Surgery:Lateral access retractor systems with integrated lighting and neuromonitoring capability reduce muscular disruption and blood loss. Germany's hospital procurement frameworks prioritize these systems for degenerative disc disease pathways where length-of-stay reduction targets are mandated.
- Robotics:Guidance platforms for pedicle screw placement and interbody positioning compress procedural variability. Japan's metropolitan hospital clusters are integrating these systems fastest amid surgeon workforce constraints and precision demands.
- Imaging Systems:Intraoperative CT and fluoroscopy configurations enable real-time implant positioning verification.
- Navigation Systems:Optical and electromagnetic tracking reduces neural retraction risk during psoas corridor access.
Clinical penetration peaks with Minimally Invasive Surgery; capital deployment is climbing steepest for Robotics.
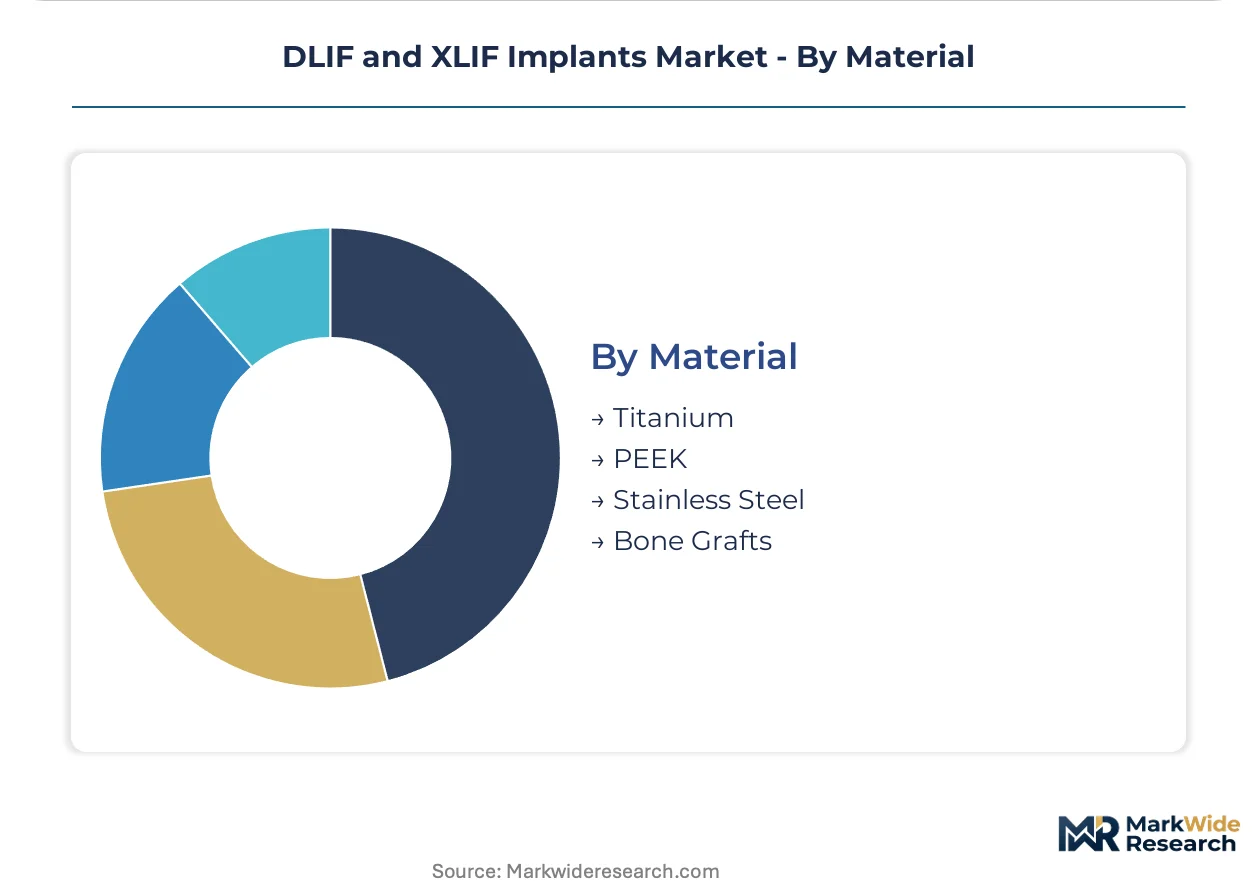
Material:
Raw material sourcing constraints and imaging compatibility requirements differentiate competitive positioning across material categories.
- Titanium:Porous structures manufactured via additive manufacturing or conventional machining offer favorable modulus of elasticity matching vertebral bone. United States hospital value analysis committees specify titanium for complex revision cases where radiographic artifact tolerance is acceptable.
- PEEK:Radiolucent polymer interbodies enable artifact-free navigation and postoperative imaging assessment. Premium positioning in German and Japanese markets reflects preference for intraoperative fluoroscopy clarity and fusion monitoring precision.
- Stainless Steel:Legacy instrumentation and temporary fixation components retain cost-sensitive applications.
- Bone Grafts:Autograft and allograft materials supplement interbody fusion biological environment.
Structural volume leadership sits with Titanium; PEEK commands premium positioning in navigation-dependent workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States hospital value analysis committees drive hard bundled pricing negotiations, while Japanese metropolitan clusters absorb premium navigation-enabled systems with limited procurement pushback.
United States
Medicare DRG reimbursement for lateral interbody fusion sustains procedure volume across academic medical centers and community hospital systems. FDA 510(k) clearance pathways govern implant biocompatibility standards, with fatigue testing protocols extending development timelines. Spine implant procurement concentrates in integrated delivery networks across Texas, California, and the Northeast Corridor where orthopedic service line administrators consolidate multihospital spend.
Germany
Hospital procurement frameworks mandate length-of-stay reduction targets that accelerate minimally invasive lateral access adoption. EU MDR technical documentation requirements extend clinical evaluation obligations for lateral retractor systems, delaying certification by twelve to eighteen months. Medical device manufacturing clusters in Baden-Württemberg and Bavaria host notified body review capacity that conditions European market entry timelines.
Japan
Aging surgical populations and degenerative disc disease prevalence drive demand in metropolitan hospital clusters. PMDA and METI coordinate on foreign manufacturer registration and quality management system audits that condition market entry for implant suppliers. Tokyo and Osaka medical centers integrate robotics and navigation systems fastest amid surgeon workforce constraints.
United Kingdom
NHS England procurement frameworks prioritize cost-per-procedure metrics that compress implant pricing for lateral fusion systems. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel compliance obligations for manufacturers. London and Southeast hospital trusts concentrate complex deformity case volume where titanium porous structures command preference.
Australia
Private health insurance reimbursement for spinal fusion procedures sustains demand in Sydney and Melbourne private hospital networks. TGA medical device registration requirements align with ISO 13485 quality management standards, streamlining entry for EU- and US-cleared manufacturers. Metropolitan surgical centers capture single-level lateral fusion volume as commercial payer outpatient authorization expands.
DLIF and XLIF Implants Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the DLIF and XLIF Implants Market. Stryker, Medtronic, and Zimmer Biomet leverage captive manufacturing and navigation-enabled workflows to defend margin control across hospital channels. Mid-cap specialists concentrate on lateral access retractor innovation and pre-psoas oblique trajectory development. Competitive moves center on bundled procedural contracting and M&A-driven portfolio completion.
Among integrated multinationals, Stryker and Medtronic exemplify the navigation-integrated tier, while NuVasive occupies a specialist position in minimally invasive lateral access systems. These three companies anchor competitive dynamics through divergent strategic postures: Stryker through backward integration into PEEK and titanium interbody production, Medtronic through procedural workflow efficiency, and NuVasive through retractor system specialization that dominates surgeon training channels.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Medtronic |
| Alphatec Spine |
| Orthofix Medical |
| NuVasive |
| DePuy Synthes |
| B. Braun |
| Globus Medical |
| Others |
Value Chain & Pricing Dynamics
Capacity-reservation contracts with titanium sponge suppliers lock in feedstock access and price visibility for implant manufacturers navigating volatile alloy markets. These arrangements insulate PEEK and titanium interbody producers from spot-market swings while committing hospital procurement teams to multi-year volume agreements.
Pricing Analysis
After-sales revenue from instrument tray refurbishment and retractor blade replacement drives lifetime value beyond initial implant sales. The market operates on a hybrid pricing model combining per-unit implant transactions with bundled procedural contracts that consolidate retractor, interbody, and biologic spend. Price differentiation hinges on FDA 510(k) clearance tier and navigation-system compatibility, with premium positioning reserved for titanium porous structures validated in deformity cases. Pricing pressure stems from hospital value analysis committees consolidating orthopedic service line spend across integrated delivery networks. Cost-sensitive community hospitals exhibit highest price sensitivity, while academic medical centers absorb premium navigation-enabled systems with limited procurement resistance.
Supply Chain Analysis
Just-in-time inventory strategies dominate implant manufacturing, though strategic stockpiling of titanium sponge and PEEK resin buffers against raw material volatility. Supply concentrates in United States, Germany, and Japan where precision machining clusters and additive manufacturing hubs feed finished interbody production. Raw material dependencies center on titanium sponge from specialized metallurgical suppliers, medical-grade PEEK resin, and demineralized bone matrix from tissue processing facilities. Single-source vulnerability for porous titanium additive manufacturing equipment creates chokepoint exposure. Distribution runs through orthopedic distributor networks and direct hospital contracts, with surgical center channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Navigation-integrated lateral access systems are disrupting procedural economics, with FDA 510(k) clearance timelines compressing competitive windows for implant manufacturers.
For Market Incumbents: Compound defensive positioning through backward integration into PEEK and titanium interbody production and captive manufacturing of navigation-enabled retractor systems. Threat exposure concentrates in mid-cap specialists developing pre-psoas oblique access trajectories that bypass established lateral corridor patents. Capacity addition in Baden-Württemberg precision machining clusters secures European market access amid EU MDR certification queues. For New Entrants and Emerging Players: Lead with ambulatory surgical center channels where streamlined instrumentation sets and outpatient reimbursement expansion create white-space penetration. Japan's metropolitan hospital clusters present the most penetrable geography, with PMDA foreign manufacturer registration pathways conditioning market entry for lateral access specialists. Go-to-market execution should anchor on surgeon training partnerships with academic medical centers seeking cadaveric lab investment alternatives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among implant manufacturers with captive biologics portfolios and instrument tray service contracts. Long-term viability over a five-to-ten year horizon favors targets with EU MDR technical documentation already filed and German hospital tender qualifications secured. The signal to watch is bundled procedural contracting penetration in United States integrated delivery networks, where orthopedic service line consolidation accelerates implant supplier selection.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker's direct contracting with Texas and California IDNs consolidates multihospital spine implant spend. |
| FDA 510(k) Submission | Medtronic's fatigue testing protocols for titanium porous interbodies extend hospital contract eligibility. |
| CE Marking Pathway | NuVasive's MDR technical documentation for lateral retractor systems conditions German procurement access. |
| Software Companion Development | Navigation-enabled XLIF workflows differentiate procedural efficiency in academic medical centers. |
| Reimbursement Strategy | DRG coding optimization for lateral interbody fusion sustains Medicare volume in inpatient settings. |
Study Parameters
The analysis maps interbody implant, biologics, instrumentation, and access system sub-sectors, each validated through orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up and top-down triangulation cross-checks segment-level volume assumptions against aggregate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation by product type, end user facility, surgical technology, and implant material composition. CAGRs derive from procedure volume trajectories, reimbursement pathway evolution, and technology adoption curves. Forecast inputs incorporate aging demographic projections, surgeon workforce constraints, and regulatory certification timelines.
Underlying assumptions cover Medicare DRG stability, EU MDR notified body capacity, and titanium raw material supply continuity, with deviation risk concentrated in reimbursement coding revisions and posterior fusion technique resurgence. Revision becomes warranted when lateral interbody fusion complication rates cross thresholds triggering payer prior authorization restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bandage Contact Lenses Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Depression Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Breast Localization System Market
Medical Devices
Silastic Implant Market
Medical Devices
Global Esophageal Catheters Market