
 Endoscopic Mucosal Resection Market | 2026-2036
Endoscopic Mucosal Resection Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Mucosal Resection Market Analysis
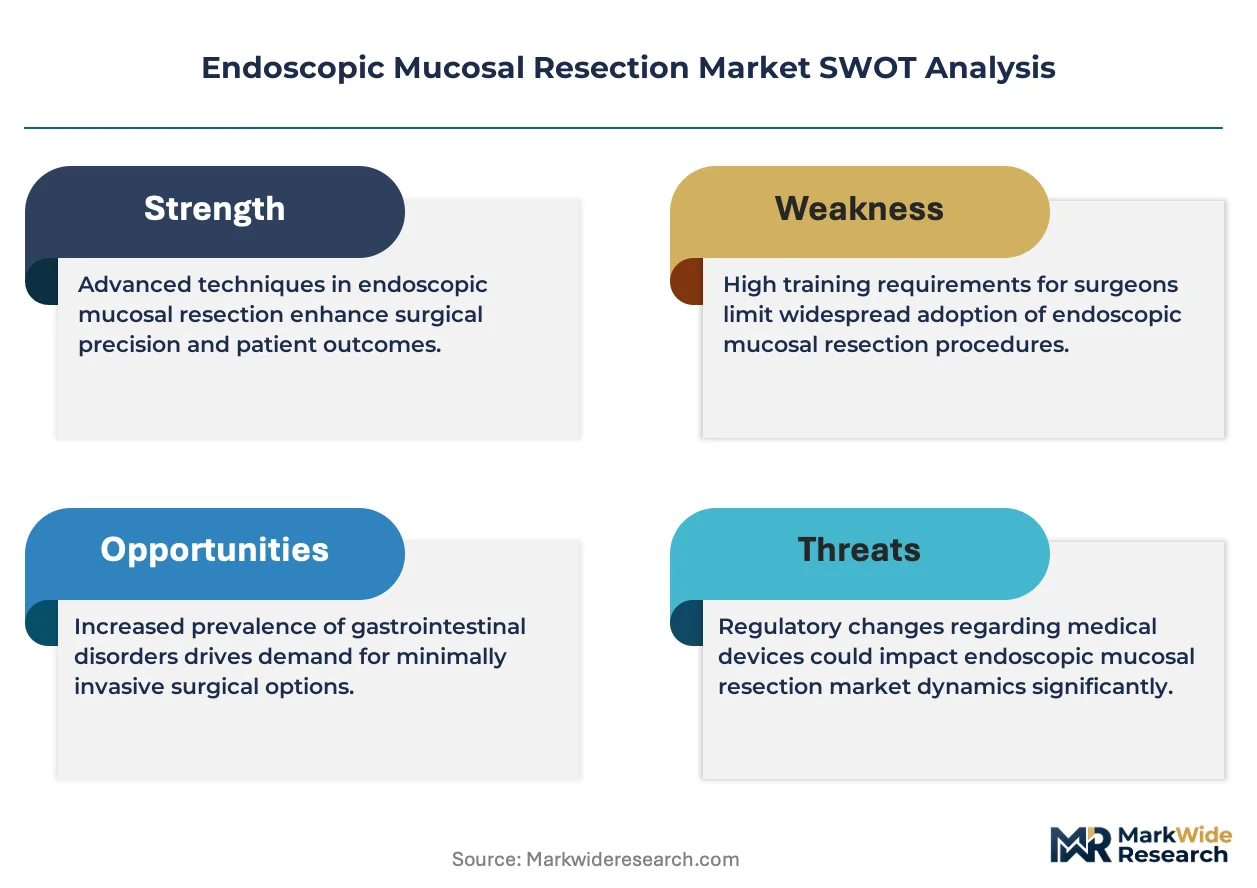
High-definition imaging specification tiers is collapsing the distinction between diagnostic endoscopy and therapeutic resection, enabling real-time tissue characterization that reduces unnecessary biopsies. Olympus leverages its vertically integrated optical chain to dominate premium visualization platforms. Boston Scientific anchors its position through electrosurgical accessory ecosystems that lock in recurring revenue. Medtronic competes via broad hospital contracting power that bundles EMR tools with capital equipment.
Endoscopic mucosal resection removes superficial gastrointestinal lesions through submucosal injection followed by snare resection, typically achieving en bloc removal for lesions under 20 millimeters. The technique preserves organ anatomy while providing histological specimens for definitive staging. Single-use devices command the largest revenue pool given infection control mandates and convenience premiums in high-throughput settings. Electrosurgical units represent the fastest-growing product category as hybrid knife technologies displace conventional snare-based workflows. Ambulatory surgical centers emerge as the most contested end-user segment as payor pressure shifts complex polypectomy away from inpatient settings.
FDA 510(k) premarket notification governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for electrosurgical instruments entering European markets. Japan's PMDA maintains rigorous biocompatibility standards for reusable instrument materials that extend approval timelines. Stakeholders must monitor how reimbursement coding for hybrid EMR procedures evolves against conventional polypectomy rates.
Market Dynamics
Hybrid knife electrosurgical platforms are collapsing the traditional separation between diagnostic endoscopy and therapeutic resection, forcing device manufacturers to integrate real-time tissue characterization into single-procedure workflows.
Growth Catalysts
- Same-day discharge mandates:Ambulatory surgical centers in the United States are accelerating EMR adoption to meet payor requirements for outpatient polypectomy protocols.
- FDA 510(k) streamlining:The premarket notification pathway for endoscopic resection devices reduces time-to-market for novel snare and electrosurgical designs.
- Optical chain integration:High-definition imaging specification tiers enable real-time histological assessment without biopsy delays.
Market Restraints
- Copper and precious metal volatility:Electrosurgical generator components face input cost pressure from commodity market fluctuations.
- EU MDR clinical evidence requirements:Stricter documentation for electrosurgical instruments entering European markets extends approval timelines and raises development costs.
- Conventional snare substitution:Established polypectomy devices in budget-constrained health systems resist displacement despite hybrid knife performance advantages.
Strategic Opportunities
- India outpatient expansion:Private hospital chains in Mumbai and Delhi are building dedicated endoscopy suites for early gastrointestinal cancer detection programs.
- AI-assisted lesion detection:Computer vision algorithms integrated with EMR platforms reduce missed adenoma rates during screening colonoscopy.
- Single-use device mandates:Infection control protocols in high-throughput Japanese endoscopy centers are accelerating conversion from reusable instruments.
Industry Challenges
- Submucosal injection proficiency:EMR technique requires specialized training in saline-lift methodology that general gastroenterologists lack without dedicated fellowship exposure.
- Capital equipment integration:Electrosurgical units must interface with legacy endoscope processor architectures from multiple manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Mucosal Resection Market |
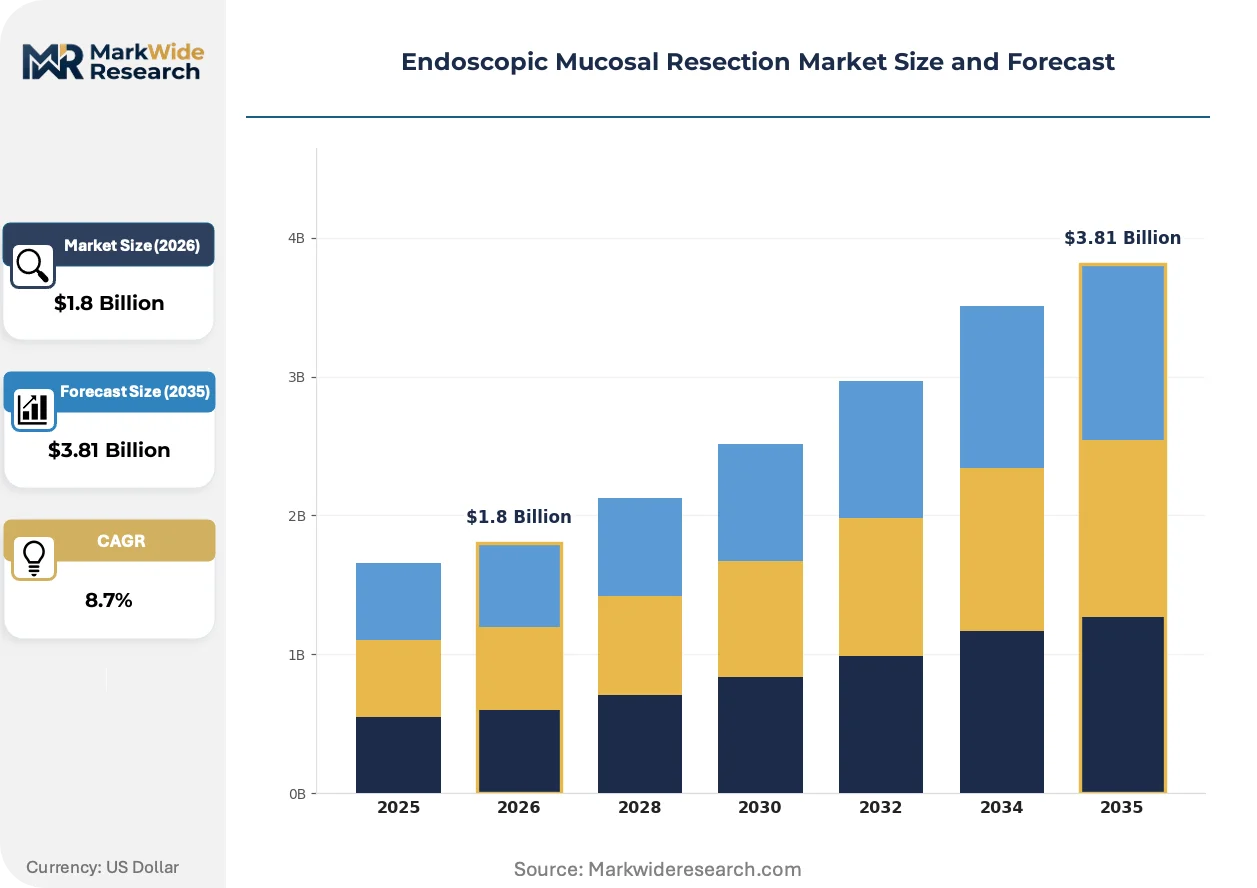
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Devices, Reusable Instruments, Electrosurgical Units, Accessories Delivery Mode: Minimally Invasive, Outpatient Procedure, In-Hospital, On-Site Care End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Gastroenterology, Oncology, General Surgery, Other Surgical Procedures |
| Companies Covered | Olympus, Boston Scientific, Medtronic, Cook Medical, Fujifilm Healthcare, ERBE Elektromedizin, CONMED, Steris, Interscope Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Mucosal Resection Market Emerging Trajectories
Real-time tissue characterization capabilities are merging diagnostic and therapeutic functions into unified procedure workflows, compressing the traditional multi-visit pathway for polyp management.
Hybrid knife electrosurgical technology combines submucosal injection and cutting in a single instrument, eliminating instrument exchanges during EMR. Ambulatory surgical centers in the United States are adopting these platforms fastest due to throughput pressure. The technology is decomposing the conventional separation between diagnostic biopsy and therapeutic resection into a single visit.
Japan's PMDA maintains rigorous biocompatibility standards for reusable instrument materials that manufacturers must satisfy before market authorization. These requirements extend approval timelines but elevate material quality benchmarks across the supply base. Electrosurgical accessory manufacturers targeting Japanese distribution must invest in extended biocompatibility testing protocols.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases for electrosurgical platforms. Third-party service providers are displacing manufacturer maintenance agreements in high-volume United States health systems. This shift concentrates in integrated delivery networks with centralized biomedical engineering capabilities.
Endoscopic Mucosal Resection Market Segmentation
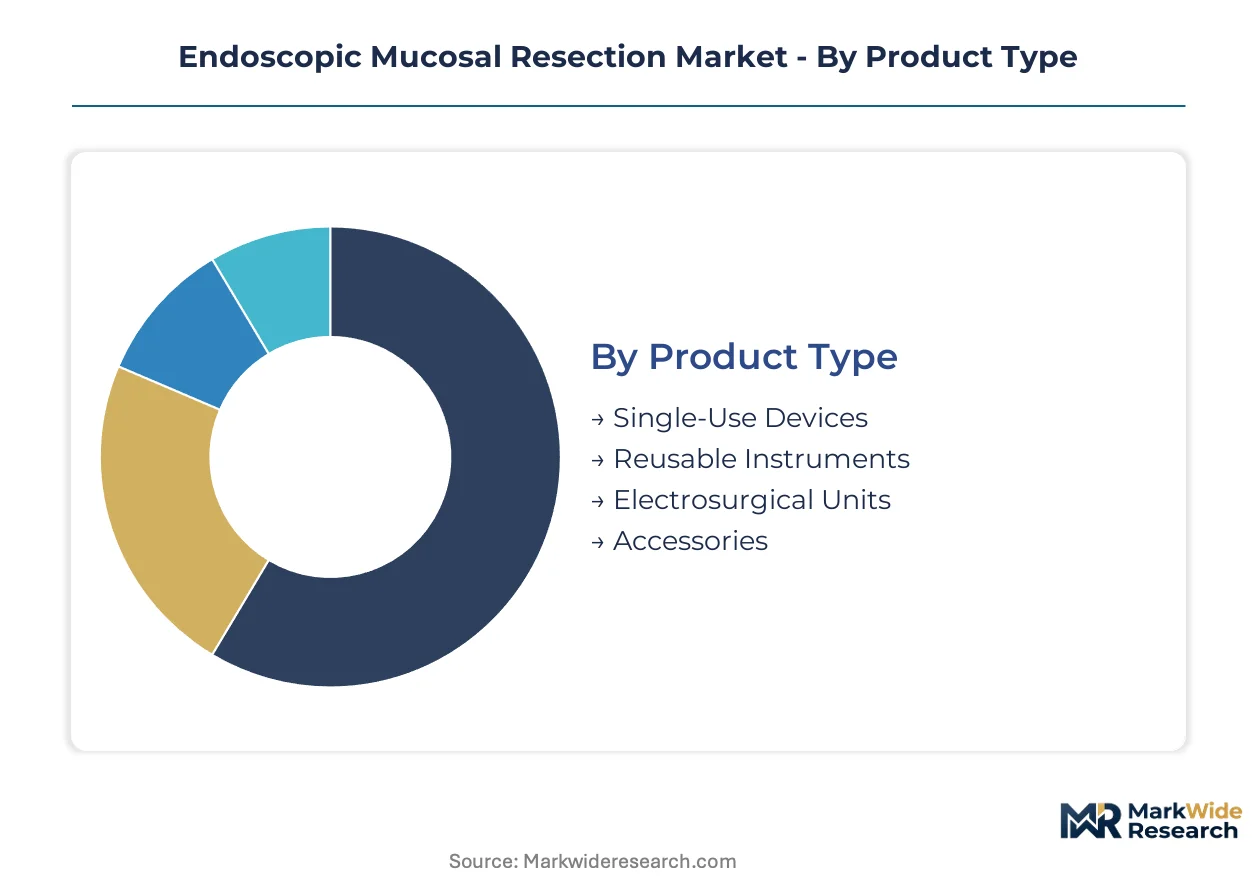
Device configuration and care setting selection directly determine reimbursement pathways and capital allocation priorities for EMR providers. Segmentation reveals where substitution pressure from hybrid platforms is collapsing traditional category boundaries.
Product Type:
Substitution pressure from hybrid electrosurgical platforms is fragmenting the conventional divide between single-use and reusable instrument portfolios.
- Single-Use Devices:Pre-sterilized snares, injection needles, and retrieval nets eliminate reprocessing overhead in high-throughput ambulatory settings. Demand concentrates in United States ASCs where infection control mandates and same-day discharge protocols drive disposable preference. Japanese endoscopy centers are accelerating conversion under PMDA-influenced biocompatibility standards.
- Electrosurgical Units:Hybrid knife platforms integrate submucosal injection and cutting functions, displacing conventional snare-based workflows. Adoption is climbing fastest in United States hospital systems bundling EMR tools with capital equipment procurement. Generator interface requirements with legacy Olympus and Fujifilm processor architectures create integration friction.
- Reusable Instruments:Metal snares and injection catheters face margin compression from copper and precious metal commodity volatility.
- Accessories:Electrosurgical pads, grounding plates, and irrigation tubing represent recurring revenue pools locked to primary device ecosystems.
Single-Use Devices retain volume leadership; Electrosurgical Units hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification across delivery settings mirrors reimbursement differential between inpatient and outpatient polypectomy codes.
- Minimally Invasive:Submucosal injection followed by snare resection preserves gastrointestinal organ anatomy while enabling histological staging. United States ASCs dominate procedural volume as payor pressure shifts complex polypectomy away from hospital-based settings.
- Outpatient Procedure:Same-day discharge mandates from commercial insurers and Medicare Advantage plans are concentrating EMR investment in dedicated endoscopy suites. Mumbai and Delhi private hospital chains are building comparable outpatient capacity for early cancer detection programs.
- In-Hospital:Large lesions requiring anesthesia support or complication management retain inpatient preference.
- On-Site Care:Mobile endoscopy units serve rural and underserved populations with portable electrosurgical platforms.
Outpatient Procedure captures the fastest volume migration; In-Hospital retains the highest acuity cases.
End User:
Customer type determines procurement leverage and service contract structure across the installed base.
- Ambulatory Surgical Centers:High-throughput polypectomy demand and payor outpatient mandates make ASCs the most contested end-user segment. United States facilities prioritize single-use device convenience and rapid room turnover over capital equipment ownership.
- Hospitals:Integrated delivery networks exploit centralized biomedical engineering to unbundle after-sales service contracts from electrosurgical platform purchases. Third-party maintenance providers are displacing manufacturer service agreements.
- Specialty Clinics:Gastroenterology-focused practices concentrate EMR proficiency but lack capital for hybrid platform acquisition.
- Research Institutions:Academic medical centers drive AI-assisted lesion detection algorithm development and training protocol innovation.
Hospitals retain installed base dominance; Ambulatory Surgical Centers gain share fastest on outpatient migration.
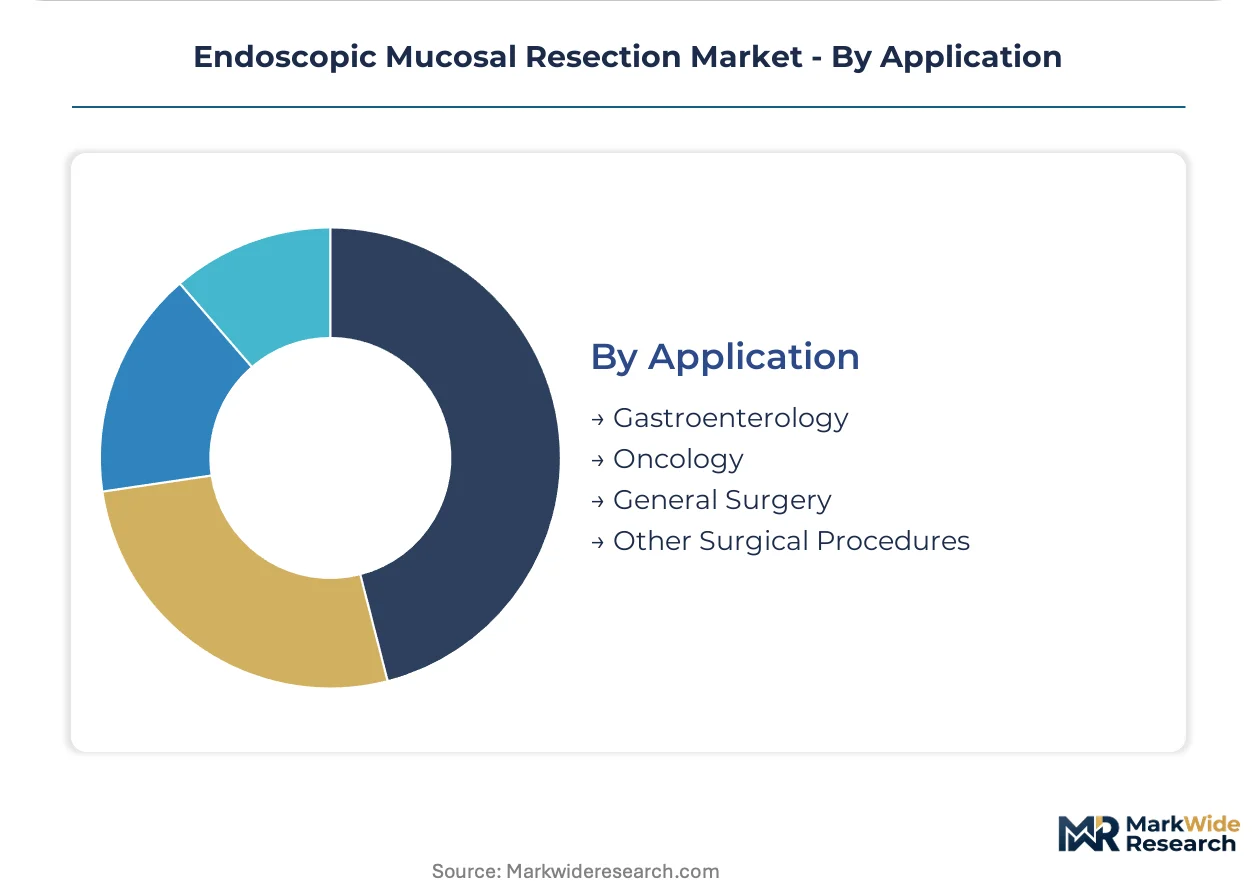
Application:
Volume concentration in screening-driven indications creates margin pressure in therapeutic oncology segments.
- Gastroenterology:Screening colonoscopy guidelines in the United States generate procedural volume for diminutive polyp removal. High-definition imaging specification tiers enable real-time tissue characterization that reduces unnecessary biopsies and compresses diagnostic-therapeutic timelines.
- Oncology:EMR for early gastrointestinal cancer staging demands specialized submucosal injection proficiency that general gastroenterologists lack without dedicated fellowship exposure. Japan's PMDA maintains rigorous standards for reusable instruments used in cancer resection protocols.
- General Surgery:EMR adjuncts to laparoscopic procedures remain underdeveloped relative to dedicated gastroenterology workflows.
- Other Surgical Procedures:Esophageal and duodenal applications represent niche expansion opportunities.
Gastroenterology retains volume leadership; Oncology holds the steepest expansion curve on early detection program investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing for endoscopic mucosal resection clusters in Japan, Germany, and the United States, where precision electrosurgical engineering and optical component fabrication have concentrated over decades. These three markets anchor supply chains for hybrid knife platforms and high-definition visualization systems. Regulatory pathways in each jurisdiction determine how quickly novel designs reach clinical settings.
United States
Screening colonoscopy guidelines from the U.S. Preventive Services Task Force drive procedural volume for diminutive polyp removal. FDA 510(k) premarket notification governs clearance timelines for novel snare and electrosurgical designs. Ambulatory surgical centers in Texas and Florida are building dedicated endoscopy suites to capture same-day discharge mandates from commercial insurers.
Japan
Early gastrointestinal cancer detection programs sustain demand for precision submucosal injection techniques. PMDA maintains rigorous biocompatibility standards for reusable instrument materials that extend approval timelines. Tokyo and Osaka medical device clusters concentrate manufacturing for optical chains and electrosurgical generators serving domestic and export markets.
Germany
Hybrid electrosurgical platform development benefits from precision engineering capabilities in the Baden-Württemberg and Bavaria industrial regions. EU Medical Device Regulation imposes stricter clinical evidence requirements for electrosurgical instruments entering European markets. ERBE Elektromedizin anchors a regional supply base for electrosurgical accessories.
India
Private hospital chains in Mumbai and Delhi are constructing dedicated endoscopy suites for early cancer detection programs targeting rising colorectal incidence. CDSCO regulates medical device imports and domestic manufacturing under evolving framework alignment with global standards. Outpatient procedural volume is climbing fastest in Maharashtra and Karnataka tertiary care centers.
China
Domestic endoscope manufacturing capacity is expanding in the Yangtze River Delta and Pearl River Delta regions. NMPA oversees medical device registration with accelerating review timelines for innovative electrosurgical instruments. Local procurement preferences in Shanghai and Beijing hospital systems are shifting toward domestically produced visualization platforms.
Endoscopic Mucosal Resection Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates that control optical component supply chains and electrosurgical generator manufacturing. Three strategic archetypes dominate: vertically integrated visualization platform vendors, electrosurgical accessory ecosystem builders, and broad hospital contracting powerhouses. Competitive moves center on unbundling after-sales service contracts from capital equipment purchases and bundling EMR tools with endoscope processor architectures.
Among Japanese and German precision manufacturers, Olympus and ERBE Elektromedizin exemplify the vertically integrated archetype, while Boston Scientific occupies a position within the electrosurgical accessory tier. These three anchors represent distinct competitive vectors—optical chain control, electrosurgical workflow integration, and procedural ecosystem lock-in—that define how procurement departments evaluate platform commitments.
| Leading Market Players |
|---|
| Olympus |
| Boston Scientific |
| Medtronic |
| Cook Medical |
| Fujifilm Healthcare |
| ERBE Elektromedizin |
| CONMED |
| Steris |
| Interscope Medical |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for hybrid electrosurgical generators concentrate pricing power with Japanese and German manufacturers who control precision optical component fabrication, while ASC procurement committees exploit third-party service unbundling to compress capital equipment margins.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium visualization platforms, standard electrosurgical accessories, and economy snare alternatives. Price differentiation stems from CE marking grade and after-sales service bundling, with hybrid knife platforms commanding premiums over conventional snares. Cost compression in the reusable instrument tier intensifies because copper and precious metal commodity volatility squeezes manufacturer margins. Ambulatory surgical centers exhibit highest price sensitivity due to throughput-driven procurement, while integrated delivery networks leverage volume scale for lowest net acquisition costs.
Supply Chain Analysis
Strategic stockpiling of electrosurgical generator components prevails over just-in-time approaches given copper and precious metal price volatility exposure. Manufacturing concentrates in Japan, Germany, and the United States, where precision engineering capabilities anchor hybrid platform production. The supply chain draws from optical glass substrates, electrosurgical-grade copper alloys, and biocompatible polymer coatings. Single-source vulnerability in high-definition imaging sensor fabrication creates concentrated disruption risk. Distribution runs through GPO contracts and direct hospital procurement channels, with third-party service providers displacing manufacturer maintenance agreements in high-volume health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face substitution defense imperatives as hybrid knife platforms collapse the diagnostic-therapeutic boundary and threaten conventional snare-based revenue pools.
For Market Incumbents: Secure optical chain control through backward integration into high-definition imaging sensor fabrication, insulating premium visualization platform margins from supply disruption. Lock in ASC channel access by bundling single-use device contracts with rapid-turnaround service guarantees, neutralizing third-party maintenance encroachment. Hybrid knife commoditization pressure demands certification investment in PMDA biocompatibility standards to sustain Japanese market premium positioning.
For New Entrants and Emerging Players: After-sales service unbundling in United States integrated delivery networks presents the most penetrable white-space opportunity, where biomedical engineering capabilities enable third-party electrosurgical platform maintenance. Target Maharashtra and Karnataka tertiary care centers in India for outpatient endoscopy suite partnerships, exploiting private hospital chain expansion for early cancer detection programs. Pursue software companion development for AI-assisted lesion detection as the primary go-to-market angle, differentiating on missed adenoma rate reduction rather than capital equipment head-to-head competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates with under-optimized electrosurgical accessory portfolios, where EMR tool bundling potential remains unrealized. Long-term viability over the projection horizon hinges on hybrid platform adoption curves displacing conventional workflows, favoring targets with optical component captive supply or electrosurgical generator manufacturing depth. Monitor reimbursement coding evolution for hybrid EMR procedures against conventional polypectomy rates as the critical inflection signal for capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines for electrosurgical instruments entering European markets. |
| Hospital System Partnership | ASC same-day discharge mandates concentrate procurement leverage with high-throughput United States facilities. |
| Software Companion Development | AI-assisted lesion detection algorithms reduce missed adenoma rates during screening colonoscopy workflows. |
| Reimbursement Strategy | Hybrid EMR procedure coding evolution against conventional polypectomy rates determines capital equipment ROI. |
| Backward Integration | Captive supply of high-definition imaging sensors protects premium visualization platform margin structure. |
Methodological Framework
Operator-level perspectives from gastroenterologists, ASC clinical directors, hospital purchasing committee members, and biomedical engineering managers anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation from FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement schedules, and hospital GPO contract repositories. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation established market sizing boundaries.
Sensitivity analysis across copper price volatility scenarios, EU MDR approval timeline distributions, and ASC outpatient migration rates tested forecast robustness. Segmentation dimensions modeled include product configuration, delivery setting, end-user type, and application indication, with regional regulatory cluster effects incorporated throughout the projection horizon. CAGRs derived from procedure volume elasticity to screening guideline adherence and capital equipment replacement cycles, with electrosurgical unit adoption curves and single-use device conversion rates as key industry-specific inputs.
Underlying assumptions cover reimbursement stability for outpatient polypectomy, hybrid knife clinical outcome parity, and copper commodity price band containment, with deviation risk concentrated in FDA clearance timeline delays and EU MDR clinical evidence requirement escalations. Revision becomes warranted when hybrid EMR reimbursement coding crosses threshold divergence from conventional polypectomy rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Endoscopy Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
AI in Endoscopy Market
Endoscopy
Non-Invasive Colon Cancer Screening Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Duodenoscope Market
Endoscopy
Gastroscopes Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
Global Veterinary Endoscopes Market