
 Disease-Modifying Antirheumatic Drug (DMARD) Market | 2026-2036
Disease-Modifying Antirheumatic Drug (DMARD) Market Size, Share, and Industry Trends Forecast 2026-2036
Disease-Modifying Antirheumatic Drug (DMARD) Market Outlook
The EU Green Deal's pharmaceutical sustainability criteria is realigning manufacturing priorities across the DMARD supply base. AbbVie Inc. leverages its integrated biologics platform to sustain manufacturing scale for adalimumab-class therapies. Pfizer Inc. anchors its position through biosimilar development capabilities, while Amgen Inc. differentiates via recombinant protein engineering leadership in TNF-inhibitor production.
Disease-modifying antirheumatic drugs comprise synthetic small molecules, biologic proteins, targeted synthetic agents, and biosimilar alternatives designed to suppress autoimmune-mediated joint destruction and systemic inflammation through immunomodulation, cytokine blockade, or Janus kinase pathway interruption. Biologics command the dominant value share due to manufacturing complexity and clinical efficacy in refractory rheumatoid arthritis, while JAK inhibitors represent the fastest-expanding category driven by oral administration convenience and payer preference for pharmacy-dispensed alternatives over infusion center dependency. Synthetic DMARDs retain substantial volume in early-line therapy across outpatient settings where methotrexate protocols remain standard of care.
FDA biosimilar interchangeability standards, EMA manufacturing inspections under the EU GMP framework, and Japan's PMDA quality consistency guidelines collectively determine market access timelines and production location decisions for biologic DMARD suppliers. The FDA's IRA Medicare price negotiation provisions are reshaping revenue models for originator biologics approaching patent expiry. Stakeholders must monitor regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorization requirements when prioritizing development portfolios and geographic launch sequencing.
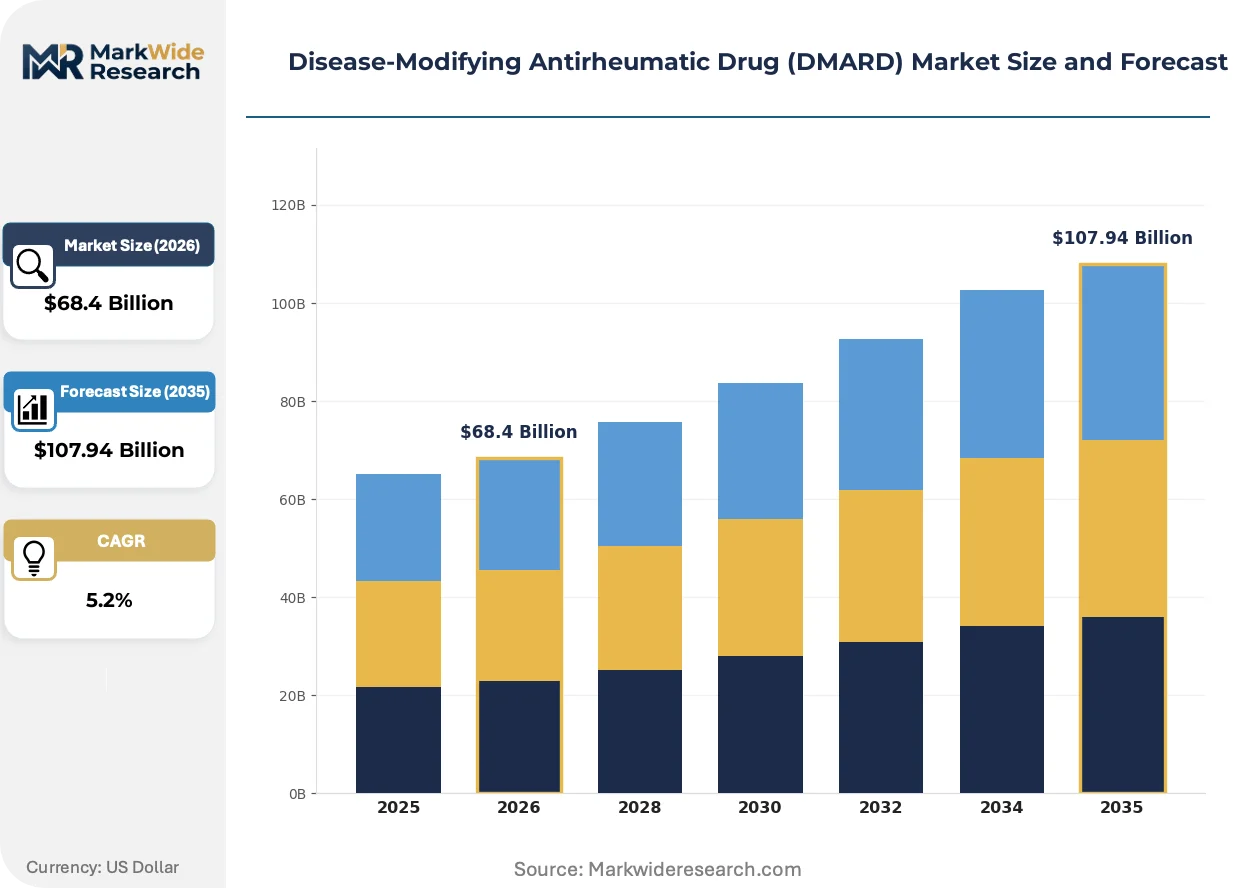
Market Dynamics
The FDA's biosimilar interchangeability pathway is compressing originator biologic revenue cycles while specialty clinics in the United States, Germany, and Japan accelerate adoption of infusion-sparing oral JAK inhibitors for rheumatoid arthritis management.
Growth Catalysts
- Medicare price negotiation under the IRA:The FDA's IRA provisions are forcing originator manufacturers to accelerate pipeline diversification before patent cliffs, expanding patient access to previously cost-prohibitable biologics.
- EU Green Deal pharmaceutical sustainability criteria:EMA manufacturing inspections under tightened environmental standards are rewarding early-adopter facilities with expedited batch release timelines across European distribution networks.
- Japan's PMDA quality consistency guidelines:METI-aligned production incentives are attracting biologics manufacturers to establish dedicated autoimmune therapy facilities in the Osaka-Kobe pharmaceutical cluster.
Market Restraints
- Plasmid DNA supply concentration:Contract manufacturing organizations in South Korea and Singapore control critical starting materials for recombinant protein production, creating single-source vulnerability for TNF-inhibitor supply chains.
- EMA cold-chain distribution requirements:Temperature excursion protocols for biologic DMARDs add 15-20% logistics cost premiums versus small-molecule alternatives, compressing pharmacy margin structures.
- Subcutaneous formulation substitution:Biosimilar adalimumab products are capturing rheumatology practice formulary slots previously reserved for intravenous infliximab, eroding infusion center revenue dependencies.
Strategic Opportunities
- Underpenetrated early-line synthetic DMARD protocols:Rheumatology practices in India's tier-2 cities lack methotrexate monitoring infrastructure, creating white space for pharmacy-managed therapeutic drug monitoring services.
- Convergence of wearable biosensors and JAK inhibitor therapy:Real-time inflammation monitoring via connected devices enables dynamic dosing algorithms that differentiate next-generation oral therapies from fixed-dose biologics.
- Germany's DigiGesund digital health fast-track:The BfArM approval pathway for app-integrated medication adherence programs offers regulatory tailwind for connected delivery devices in biologic self-administration.
Industry Challenges
- Cell line development talent scarcity:Mammalian expression system expertise concentrates among legacy biologics veterans approaching retirement, constraining biosimilar manufacturer hiring pipelines.
- Legacy EHR integration complexity:Rheumatology practices using decade-old practice management systems face multi-year upgrade cycles to support REMS-compliant biologic prescribing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disease-Modifying Antirheumatic Drug (DMARD) Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Synthetic DMARDs, JAK Inhibitors, Biosimilars Therapy Area: Rheumatoid Arthritis, Psoriatic Arthritis, Ankylosing Spondylitis, Juvenile Idiopathic Arthritis End User: Hospitals, Specialty Clinics, Outpatient Facilities, Homecare Settings Administration Route: Oral, Subcutaneous, Intravenous, Topical |
| Companies Covered | AbbVie Inc., Pfizer Inc., Amgen Inc., Johnson & Johnson, Roche Holding AG, Bristol-Myers Squibb Company, Novartis AG, Eli Lilly and Company, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disease-Modifying Antirheumatic Drug (DMARD) Market Strategic Shifts
Biologic manufacturing platforms are converging with continuous processing technologies while regulatory frameworks on three continents simultaneously tighten environmental accountability and accelerate approval pathways for differentiated delivery formats.
Biospecific antibody engineering is consolidating the competitive landscape around platforms capable of dual cytokine blockade with single-agent administration. Rheumatology practices in the United States are prioritizing these molecules for refractory patients who failed sequential monotherapy. The technology is consolidating manufacturing scale advantages among firms with integrated cell line development and single-use bioreactor capabilities, compressing mid-tier competitors into licensing partnerships.
The EU Green Deal's pharmaceutical sustainability criteria are mandating solvent recovery rates and renewable energy thresholds for EMA-inspected facilities. Manufacturers are relocating active pharmaceutical ingredient production to sites with verified carbon accounting to maintain European market access. Biologics with complex downstream processing requirements face the steepest compliance cost escalations, advantaging synthetic DMARD producers with simpler chemistry.
Payer preference for pharmacy-dispensed oral agents is disrupting infusion center economics across United States rheumatology networks. Pharmacy benefit managers are steering prior authorization toward JAK inhibitors with established cardiovascular safety profiles, displacing site-of-care revenue for hospital-affiliated infusion suites. This channel rotation is most visible in Medicare Advantage plans concentrated in Florida and Arizona retirement corridors.
Disease-Modifying Antirheumatic Drug (DMARD) Market Segmentation
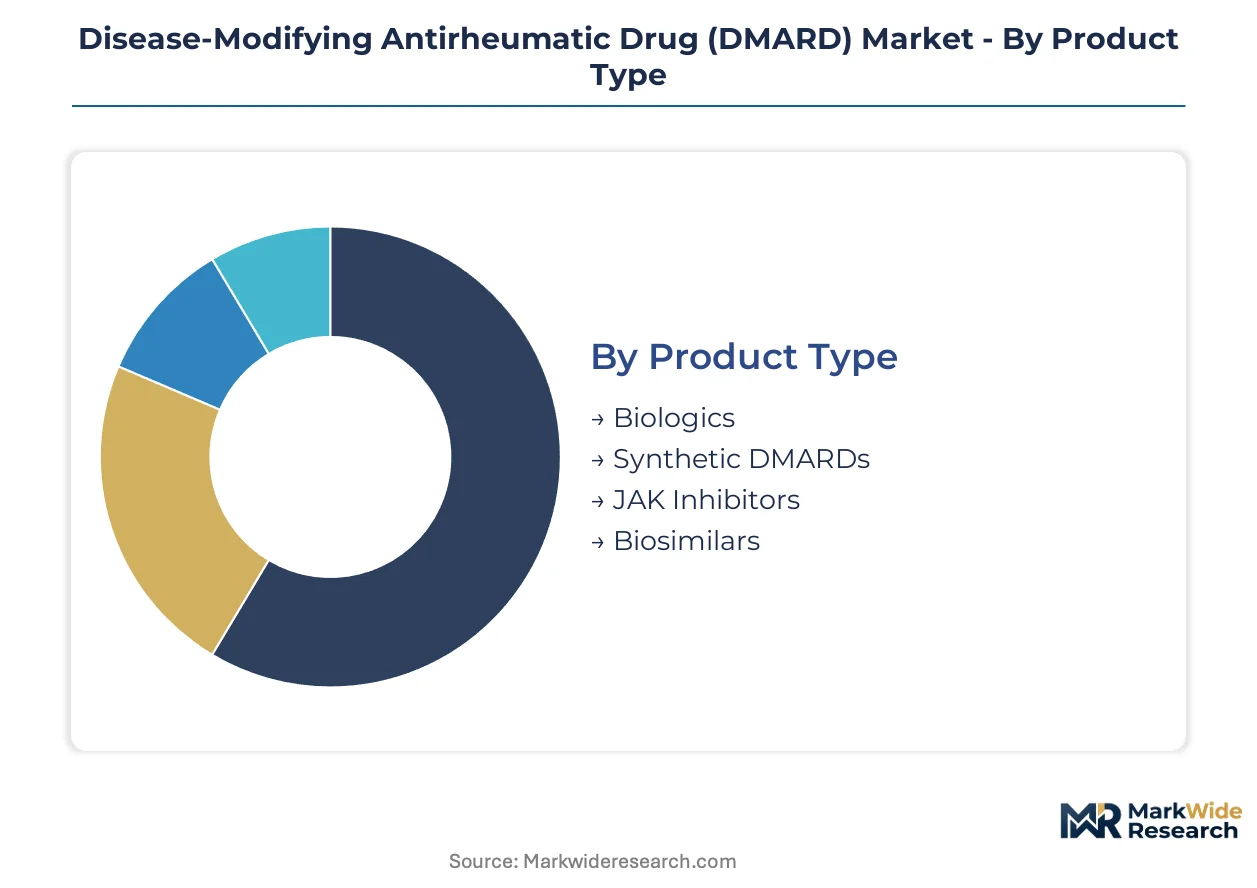
DMARD segmentation reveals divergent manufacturing economics and channel economics across therapy modalities. Biologics command premium pricing through recombinant production complexity, while synthetic agents scale through conventional chemistry. Route of administration increasingly determines site-of-care economics and payer reimbursement structures.
Product Type:
Technology platforms separate segments by manufacturing complexity and regulatory pathway intensity.
- Biologics:Recombinant proteins produced in mammalian cell culture systems deliver targeted cytokine blockade through monoclonal antibodies and fusion proteins. Demand concentrates in United States specialty clinics managing refractory rheumatoid arthritis, where infusion center economics and prior authorization requirements favor agents with established REMS programs.
- JAK Inhibitors:Small-molecule agents interrupt intracellular signaling through Janus kinase pathway inhibition, enabling oral administration and pharmacy dispensing. Germany's DigiGesund fast-track pathway is accelerating adoption of app-integrated adherence programs for these agents, displacing infusion-dependent biologics in Medicare Advantage networks.
- Synthetic DMARDs:Conventional immunomodulators including methotrexate, sulfasalazine, and hydroxychloroquine manufactured through chemical synthesis.
- Biosimilars:FDA-interchangeable and EMA-approved follow-on biologics referencing originator TNF-inhibitors and other monoclonal antibodies.
Mature deployment sits with Synthetic DMARDs. Newer deployment is concentrated in JAK Inhibitors.
Therapy Area:
Clinical indication drives dosing intensity, combination protocol requirements, and specialist referral patterns.
- Rheumatoid Arthritis:Systemic autoimmune joint destruction represents the foundational indication establishing DMARD efficacy benchmarks and reimbursement codes. United States rheumatology practices prioritize early biologic intervention for seropositive patients with erosive disease progression, while Japan's PMDA quality guidelines shape manufacturing standards for agents targeting this population.
- Psoriatic Arthritis:Spondyloarthropathy with overlapping dermatologic manifestations creates dual-specialty prescribing involving rheumatology and dermatology. Payer formularies in Germany require documented skin involvement for biologic authorization, channeling mild cases toward synthetic DMARDs and topical combinations.
- Ankylosing Spondylitis:Axial spondyloarthritis affecting spinal fusion and sacroiliac joints.
- Juvenile Idiopathic Arthritis:Pediatric autoimmune arthropathies requiring weight-based dosing and specialized pediatric rheumatology infrastructure.
Volume concentration rests with Rheumatoid Arthritis. Fastest label expansion is occurring in Psoriatic Arthritis.
End User:
Care setting determines reimbursement mechanism, nursing intensity, and patient monitoring infrastructure requirements.
- Specialty Clinics:Dedicated rheumatology practices concentrate biologic prescribing through infusion suites and self-injection training programs. United States Medicare billing codes for in-office drug administration sustain margin structures that hospital systems are replicating through acquired practice networks.
- Hospitals:Academic medical centers and community hospitals manage complex comorbidities requiring interdisciplinary coordination.
- Outpatient Facilities:Ambulatory surgery centers and infusion centers competing on convenience and parking access.
- Homecare Settings:Self-administered subcutaneous biologics and oral agents supported by specialty pharmacy nursing services.
Biologic revenue concentrates in Specialty Clinics. Oral agent volume is shifting toward Homecare Settings.
Administration Route:
Delivery mechanism determines cold-chain requirements, patient training burden, and pharmacokinetic profile optimization.
- Subcutaneous:Prefilled syringes and auto-injector devices enable self-administration of biologic agents outside clinical settings. Japan's Osaka-Kobe pharmaceutical cluster hosts manufacturing capacity for these delivery systems, with METI production incentives attracting dedicated autoimmune therapy facilities.
- Intravenous:Infusion center administration of biologic agents allows higher dosing and therapeutic drug monitoring.
- Oral:Small-molecule agents including JAK inhibitors and synthetic DMARDs distributed through retail and specialty pharmacy.
- Topical:Localized delivery for limited joint involvement in mild disease presentations.
Established volume sits with Intravenous. Steepest expansion trajectory belongs to Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic DMARD production clusters in mammalian cell culture facilities across the United States, Germany, and Japan, while consumption concentrates in aging populations with established rheumatology infrastructure. Regulatory divergence between FDA biosimilar pathways and EMA sustainability mandates is fragmenting manufacturing location decisions.
United States
Specialty clinics in Florida and Arizona retirement corridors drive infusion-to-oral conversion for JAK inhibitors. The FDA's IRA Medicare price negotiation provisions compress originator biologic revenue cycles before patent cliffs. Massachusetts and California host the dominant mammalian expression system facilities supplying TNF-inhibitor active pharmaceutical ingredients.
Germany
Rheumatology practices in Bavaria and North Rhine-Westphalia prioritize early biologic intervention for seropositive patients. The BfArM DigiGesund fast-track pathway accelerates app-integrated adherence programs for oral agents. The Rhine-Main pharmaceutical cluster concentrates EMA-inspected facilities adapting to EU Green Deal solvent recovery mandates.
Japan
Japan's aging demographic sustains demand for subcutaneous self-administration formats in Kanto and Kansai regions. METI-aligned production incentives attract dedicated autoimmune therapy facilities to the Osaka-Kobe pharmaceutical cluster. The PMDA quality consistency guidelines shape manufacturing standards for agents targeting refractory rheumatoid arthritis populations.
United Kingdom
NHS England prior authorization protocols channel mild psoriatic arthritis cases toward synthetic DMARDs and topical combinations. The MHRA post-Brexit regulatory divergence creates parallel submission requirements for biologic manufacturers. The Golden Triangle research corridor maintains early-phase clinical trial density for next-generation JAK inhibitors.
India
Rheumatology practices in Maharashtra and Karnataka lack methotrexate monitoring infrastructure, creating white space for pharmacy-managed therapeutic drug monitoring services. The CDSCO accelerated approval pathway for biosimilars references EMA and FDA precedents. Hyderabad and Ahmedabad manufacturing clusters supply plasmid DNA starting materials for regional recombinant protein production.
Disease-Modifying Antirheumatic Drug (DMARD) Market Competitive Environment
The competitive structure tilts toward integrated biologics platforms with captive cell line development capabilities. Originators with established REMS programs and biosimilar developers with single-use bioreactor scale anchor the two dominant tiers. Strategic archetypes include mammalian expression system specialists, JAK inhibitor chemistry-scale players, and biosimilar interchangeability pathway navigators. Capacity expansion and portfolio diversification toward oral agents represent the dominant competitive moves.
Among integrated biologics originators, AbbVie Inc. and Amgen Inc. exemplify platform-scale archetypes with mammalian cell culture infrastructure, while Pfizer Inc. occupies a position spanning originator and biosimilar development capabilities. These entities anchor the competitive landscape through manufacturing scale advantages and regulatory pathway expertise rather than discrete product-level positioning.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Johnson & Johnson |
| Roche Holding AG |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Eli Lilly and Company |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Mammalian cell culture media costs cascade through biologic DMARD tiers from upstream recombinant protein production to downstream infusion center billing rates, with cold-chain logistics premiums amplifying price spreads between intravenous and subcutaneous formulations.
Pricing Analysis
Outcome-based contracting tied to radiographic progression-free survival anchors biologic DMARD reimbursement negotiations in United States Medicare Advantage networks. Three-tier pricing structure across originator biologics, biosimilars, and synthetic DMARDs reflects manufacturing complexity differentials and REMS program overhead. Cost compression in biosimilar tiers is intensifying because FDA interchangeability standards accelerate formulary substitution. Hospital-affiliated infusion centers exhibit lowest price sensitivity due to captive patient flows, while independent specialty clinics face acute margin pressure from oral JAK inhibitor channel shifts.
Supply Chain Analysis
Cold-chain freight expenditures for biologic DMARDs impose 15-20% cost premiums versus small-molecule distribution, with temperature excursion liability concentrated in United States specialty pharmacy networks. Active pharmaceutical ingredient production draws from mammalian expression facilities in Massachusetts, California, and the Rhine-Main cluster, with plasmid DNA starting materials sourced from contract manufacturing organizations in South Korea and Singapore. Single-source vulnerability in TNF-inhibitor cell line development creates supply chain risk for biosimilar manufacturers lacking captive expression platforms. Distribution runs through specialty pharmacy channels for self-administered subcutaneous agents and hospital-affiliated infusion suites for intravenous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic DMARD manufacturing scale requirements and regulatory pathway complexity are consolidating competitive positions around integrated platforms, forcing mid-tier players toward licensing partnerships or exit.
For Market Incumbents: Deploy cell line development capabilities as the defensive anchor against biosimilar erosion. AbbVie-class integrated biologics platforms should accelerate pipeline diversification toward oral JAK inhibitor combinations before patent cliffs compress originator revenue. Manufacturing scale advantages in mammalian expression systems must extend to single-use bioreactor deployments that match biosimilar cost structures. For New Entrants and Emerging Players: Direct-to-clinic digital adherence platforms offer the lowest-friction entry vector for JAK inhibitor market penetration. India's tier-2 rheumatology practices lack methotrexate monitoring infrastructure, creating white space for pharmacy-managed therapeutic drug monitoring services. Germany's DigiGesund fast-track pathway enables app-integrated medication adherence programs as the go-to-market angle. For Investors and Strategic Acquirers: FDA biosimilar interchangeability designations are the leading indicator that manufacturing scale advantages have crystallized around specific platform players. Five-to-ten-year viability favors acquisition targets with captive mammalian expression systems and established REMS programs. Watch for PMDA quality consistency guideline compliance as the signal that Japanese market access timelines have firmed for specific manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor deployment in Massachusetts and Rhine-Main clusters matches biosimilar unit economics. |
| Pipeline Diversification | JAK inhibitor combinations offset patent cliff exposure for adalimumab-class originator portfolios. |
| Regulatory Approval Pathway | FDA interchangeability designation accelerates formulary substitution and compresses originator pricing power. |
| Strategic Partnership | Osaka-Kobe pharmaceutical cluster partnerships leverage METI production incentives for subcutaneous device manufacturing. |
| Reimbursement Strategy | Medicare Advantage prior authorization protocols in Florida and Arizona retirement corridors favor oral agent channel shifts. |
Study Parameters
Document review covered FDA biosimilar filings, EMA manufacturing inspection records, and ClinicalTrials.gov protocols, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from SEC 10-K disclosures, CMS Medicare reimbursement databases, and Japan's PMDA quality consistency guideline publications. Bottom-up patient flow modeling and top-down pharmaceutical spending aggregates were triangulated to establish market sizing.
Historical prescription volume trajectories were cross-referenced against panel input from rheumatology practice administrators to calibrate adoption curve assumptions across the projection horizon. Segmentation dimensions modeled include therapy modality, administration route, patient population severity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline prevalence estimates and treatment penetration rates, with biosimilar substitution velocity and IRA Medicare price negotiation impacts incorporated as scenario variables.
The model holds under stable regulatory equivalence between FDA and EMA biosimilar standards; deviation in interchangeability designation timelines or EU Green Deal solvent recovery mandates would shift manufacturing location decisions and access timelines. Forecasts reflect documented assumptions regarding patient population growth, pricing compression trajectories, and channel migration patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market