
 China Hospital Supplies Market | 2026-2036
China Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
China Hospital Supplies Market Outlook
China's dual carbon goals under MEE oversight is repositioning hospital supply procurement toward lower-carbon manufacturing credentials and recyclable material standards. Mindray Medical International Limited leverages in-house imaging component production to sustain cost advantages across public hospital tenders. Weigao Group anchors its position through dominant domestic manufacturing scale in disposable surgical consumables. Yuwell competes aggressively in home-care adjacent devices that feed back into hospital supply chains through specialty center partnerships.
Hospital supplies encompass the full spectrum of instruments, equipment, consumables, and digital infrastructure required for patient diagnosis, intervention, and continuous care within institutional settings, with sterilization validation and biocompatibility testing serving as non-negotiable technical gateways for market access. The report segments this market across product type, technology, end user, and distribution channel dimensions. Surgical instruments and consumables together occupy the largest value share due to recurring replacement cycles and volume intensity in public hospital operating theaters. Telemedicine and imaging solutions represent the fastest-expanding technology segments as tier-two and tier-three hospitals accelerate digital infrastructure deployment under regional health bureau mandates.
NMPA device registration requirements and GB standards compliance create layered barriers for imported products while privileging domestic manufacturers with established testing relationships. SAMR pricing oversight and provincial centralized procurement platforms are compressing margins on high-volume consumables and standard surgical kits. Stakeholders must monitor the pace of NMPA innovation pathway expansions and provincial volume-based purchasing coalition expansions to calibrate R&D allocation and channel strategy.
Market Dynamics
Provincial centralized procurement platforms under SAMR oversight are compressing margins across high-volume consumables while simultaneously accelerating vendor consolidation in China's hospital supply ecosystem.
Growth Catalysts
- NMPA Innovation Pathway:Accelerated device registration for domestically manufactured advanced surgical instruments reduces time-to-market for local producers serving tertiary care centers in Beijing and Shanghai.
- Yangtze River Delta Hospital Cluster:Concentrated demand from tier-three hospitals in Jiangsu and Zhejiang provinces drives procurement volume for imaging equipment and digital infrastructure.
- Dual Carbon Goals:MEE-mandated emissions standards are redirecting hospital purchasing criteria toward suppliers with verified energy-efficient manufacturing and recyclable packaging credentials.
Market Restraints
- GB Standards Compliance Costs:Biocompatibility testing and sterilization validation requirements for imported surgical consumables create layered technical barriers that privilege established domestic testing relationships.
- Provincial Procurement Coalitions:Volume-based purchasing platforms in multiple provinces are standardizing pricing across surgical kits and standard consumables, eroding differentiated positioning.
- Petrochemical Input Volatility:Disposable plastic-based medical supplies face margin pressure from fluctuating polymer feedstock costs and MEE environmental compliance add-ons.
Strategic Opportunities
- Home-Care Hospital Integration:Specialty centers in Guangdong and Sichuan are forming partnership channels with home-care device suppliers, creating reverse-flow supply chain entry points.
- Telemedicine Infrastructure Mandates:Regional health bureau directives for tier-two hospital digitalization are opening procurement windows for remote diagnostic equipment and cloud-connected monitoring systems.
- Energy-Efficient Manufacturing Certification:Early accreditation under evolving MEE carbon accounting frameworks positions suppliers for preferential tender scoring in municipal hospital systems.
Industry Challenges
- Legacy System Integration:Digital infrastructure vendors face complex interoperability requirements when connecting new imaging and telemedicine platforms to existing hospital information systems in older tier-two facilities.
- Specialized Regulatory Affairs Talent:Shortage of professionals with dual expertise in NMPA device registration pathways and provincial tender documentation is slowing market entry timelines for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Hospital Supplies Market |
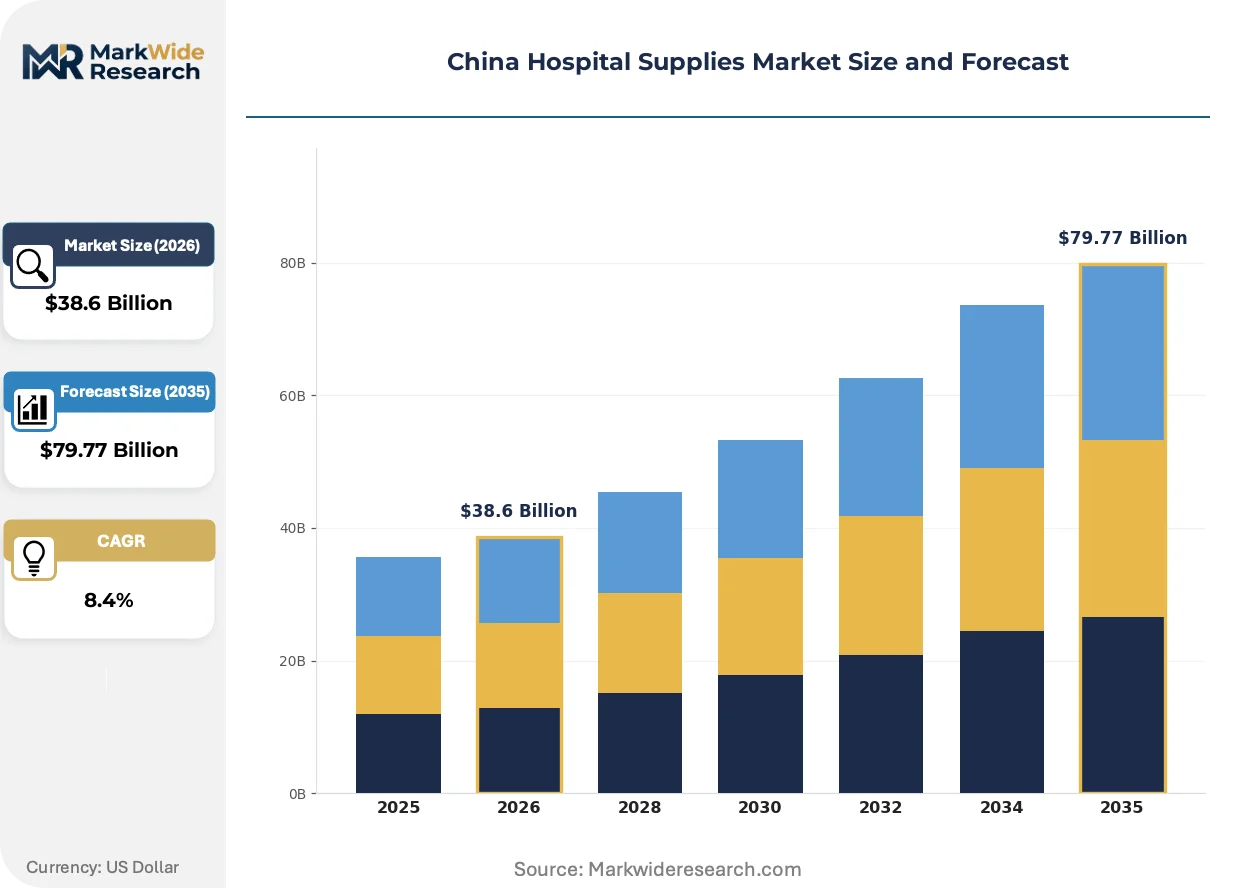
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostics Equipment, Therapeutic Devices, Consumables Technology: Telemedicine, Electronic Health Records, Wearable Devices, Imaging Solutions End User: Public Hospitals, Private Clinics, Specialty Centers, Emergency Services Distribution Channel: Direct Sales, Wholesalers, E-commerce, Retail Pharmacies |
| Companies Covered | Mindray Medical International Limited, Weigao Group, Yuwell, Medtronic, Johnson & Johnson, Cardinal Health, 3M, B. Braun, MicroPort Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Hospital Supplies Market Strategic Shifts
Hospital supply procurement in China is pivoting from transactional purchasing toward integrated vendor partnerships, with digital infrastructure and sustainability credentials emerging as primary selection criteria alongside traditional price-performance metrics.
Single-use surgical instrument kits are modularizing procurement workflows for operating theaters. Tertiary hospitals in Beijing are adopting configurable tray systems that reduce sterilization overhead and inventory carrying costs. This standardization is modularizing supplier relationships into platform-level contracts rather than discrete product orders.
SAMR pricing oversight combined with provincial volume-based purchasing mandates is restructuring competitive dynamics. Manufacturers must now optimize production scale to meet coalition tender minimums while maintaining GB standards compliance. High-volume consumables segments face the most acute margin compression as procurement platforms aggregate demand across multiple provinces.
Hospital administrators are bundling after-sales service and maintenance into multi-year equipment contracts. Tier-three hospitals in the Yangtze River Delta are negotiating integrated service agreements for imaging systems that include software updates and technician training. This bundling is visible most prominently in Shanghai municipal hospital tenders, where total cost of ownership now dominates capital allocation decisions.
China Hospital Supplies Market Segmentation
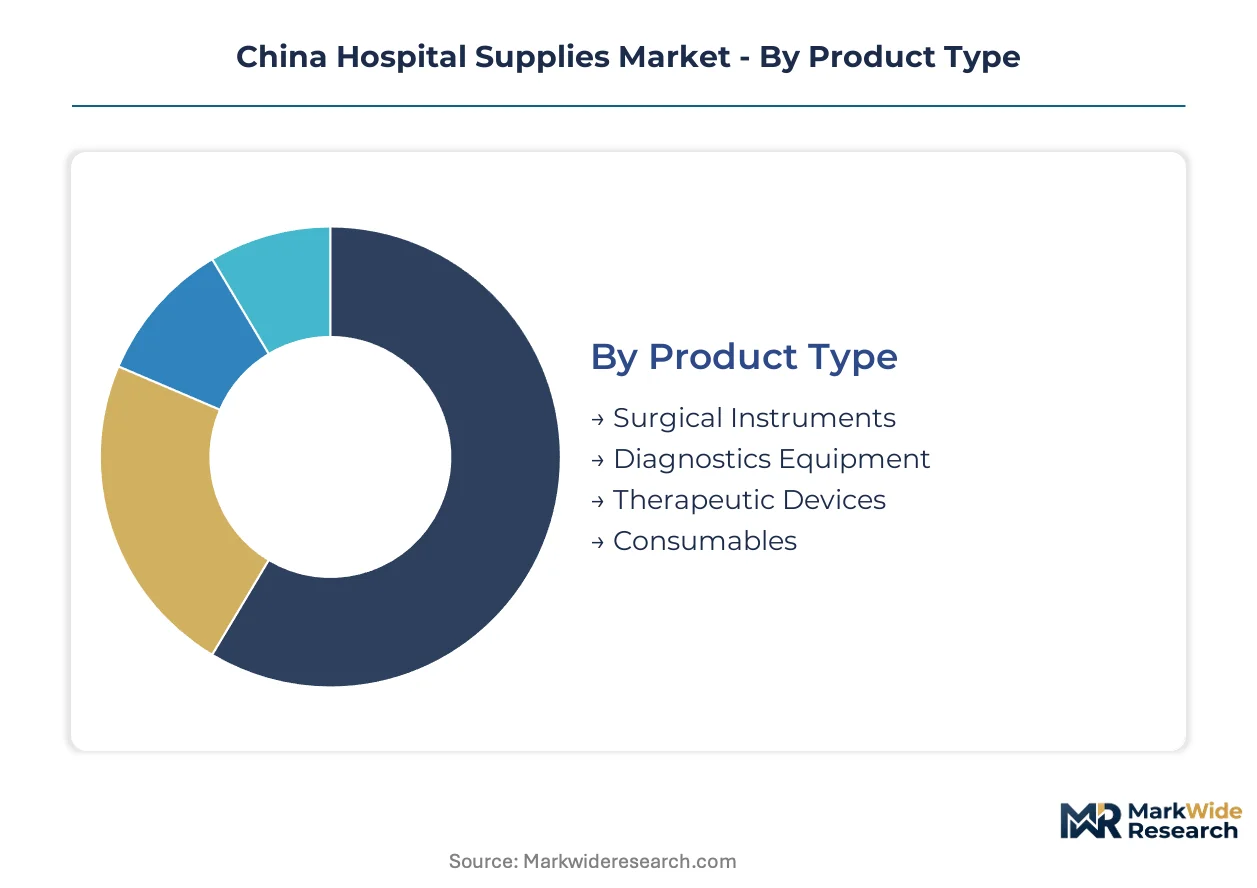
Hospital supply procurement in China stratifies sharply across facility tiers and technology readiness. Segment boundaries determine which vendors qualify for provincial tenders versus municipal contracts.
Product Type:
Procurement volume differentiates by replacement cycle length and sterilization overhead burden.
- Surgical Instruments:Configurable tray systems dominate tertiary hospital procurement in Beijing and Shanghai, reducing sterilization validation costs through modular standardization. NMPA registration pathways favor domestic manufacturers with established GB standards testing relationships for reusable instrument kits.
- Consumables:Disposable surgical kits face acute margin compression under SAMR volume-based purchasing mandates across multiple provinces. Polymer feedstock volatility and MEE environmental compliance add-ons compound cost pressure for single-use plastic-based supplies.
- Diagnostics Equipment:Imaging systems anchor capital expenditure budgets in Yangtze River Delta tier-three hospitals.
- Therapeutic Devices:Infusion and respiratory equipment concentrate in specialty center partnerships.
Volume sits with Consumables; growth tilts toward Surgical Instruments.
Technology:
Adoption readiness splits between digitally mature tertiary centers and legacy-dependent tier-two facilities.
- Telemedicine:Regional health bureau mandates for tier-two hospital digitalization are opening procurement windows for remote diagnostic platforms. Cloud-connected monitoring systems face interoperability barriers when integrating with older hospital information systems in Jiangsu and Zhejiang provinces.
- Imaging Solutions:Municipal hospital tenders in Shanghai now weight total cost of ownership over acquisition price, bundling software updates and technician training into multi-year contracts. Domestic component production confers cost advantages in public hospital tenders.
- Electronic Health Records:System integration complexity slows deployment in older tier-two facilities.
- Wearable Devices:Home-care hospital integration creates reverse-flow channels through Guangdong and Sichuan specialty centers.
Deployment concentrates in Imaging Solutions; expansion accelerates fastest in Telemedicine.
End User:
Facility classification determines tender access and pricing authority under SAMR oversight.
- Public Hospitals:Centralized procurement platforms aggregate demand across provinces, standardizing pricing for high-volume consumables. Tertiary centers in Beijing and Shanghai retain discretion for advanced surgical instrument selection.
- Specialty Centers:Cardiovascular and oncology-focused facilities in Guangdong and Sichuan are forming partnership channels with home-care device suppliers. These arrangements create alternative entry points for therapeutic device vendors outside standard hospital procurement.
- Private Clinics:Fragmented purchasing limits scale leverage in consumables.
- Emergency Services:Pre-hospital care equipment follows distinct municipal procurement tracks.
Procurement scale favors Public Hospitals; partnership flexibility advantages Specialty Centers.
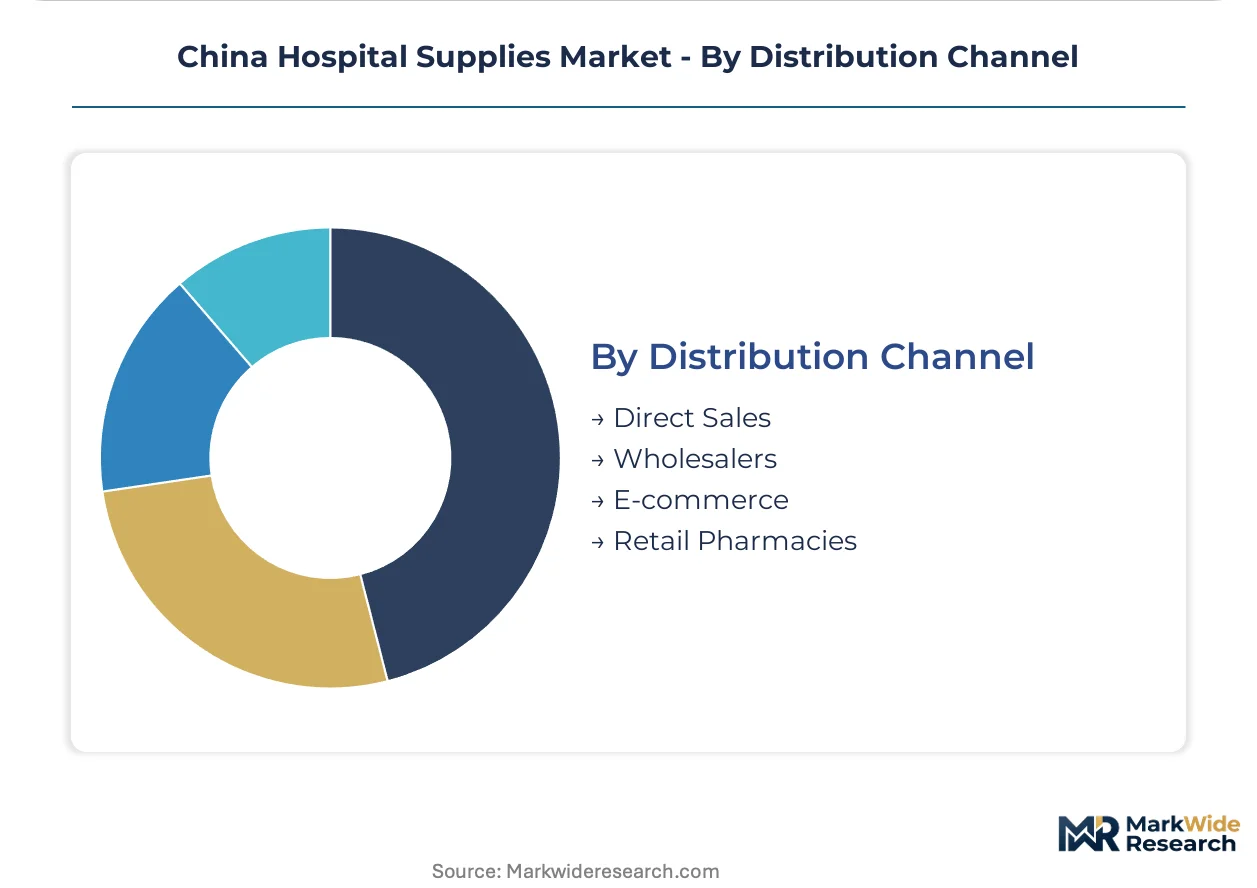
Distribution Channel:
Channel selection tracks product complexity and service bundling requirements.
- Direct Sales:Imaging equipment and digital infrastructure vendors negotiate integrated service agreements directly with tier-three hospitals. Shanghai municipal tenders explicitly require manufacturer-certified technician training and software maintenance commitments.
- E-commerce:Standard consumables and home-care adjacent devices migrate toward platform procurement as provincial coalitions expand volume-based purchasing. SAMR pricing oversight accelerates price transparency for commodity supplies.
- Wholesalers:Regional distributors retain role in tier-two hospital supply.
- Retail Pharmacies:Limited to patient-directed home-care products.
Transaction volume flows through Direct Sales; channel shift runs fastest toward E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta hospital cluster anchors procurement volume for China's hospital supplies market, with Shanghai municipal tenders setting pricing benchmarks that cascade across Jiangsu and Zhejiang provinces.
Beijing-Tianjin-Hebei
Tertiary care hospitals in Beijing drive demand for advanced surgical instruments and configurable tray systems. NMPA accelerated registration pathways privilege domestic manufacturers with established GB standards testing relationships. The Beijing municipal hospital system is consolidating vendor contracts for imaging equipment around total cost of ownership metrics.
Yangtze River Delta
Tier-three hospitals in Jiangsu and Zhejiang provinces concentrate procurement for digital infrastructure and telemedicine platforms. SAMR volume-based purchasing coalitions aggregate demand across Shanghai, standardizing pricing for high-volume consumables. The Suzhou-Nantong medical device manufacturing corridor supplies components to hospitals throughout the delta region.
Pearl River Delta
Specialty cardiovascular and oncology centers in Guangdong province form partnership channels with home-care device suppliers. MEE dual carbon goals redirect purchasing criteria toward energy-efficient manufacturing credentials. The Shenzhen-Guangzhou hospital corridor is piloting integrated telemedicine infrastructure under regional health bureau mandates.
Sichuan-Chongqing
Western China hospital expansion drives demand for diagnostic equipment and therapeutic devices in specialty centers. Provincial centralized procurement platforms under SAMR oversight compress margins on standard surgical kits. The Chengdu-Chongqing medical cluster is developing reverse-flow supply chains linking home-care device vendors to hospital specialty partnerships.
Shandong Peninsula
Manufacturing scale in disposable surgical consumables concentrates procurement relationships for public hospitals across northern provinces. GB standards compliance for sterilization validation creates technical barriers favoring established domestic testing relationships. The Qingdao-Jinan hospital network is expanding digital infrastructure deployment under municipal health bureau directives.
China Hospital Supplies Market Competitive Environment
Premium-margin players sit above commodity-margin players across the certification and service-bundling dimension, with tier-three hospital tenders rewarding integrated maintenance contracts over discrete product sales. The vendor base stratifies between domestic manufacturers with NMPA pathway advantages and multinational suppliers with established tertiary hospital relationships. Three archetypes dominate: scale-driven disposable producers, vertically integrated imaging specialists, and partnership-based home-care integrators. Competitive moves concentrate on multi-year service contract bundling and provincial coalition tender qualification.
Within the domestic scale-driven tier, Mindray Medical International Limited and Weigao Group exemplify manufacturers leveraging in-house production and established GB standards relationships to anchor public hospital procurement positions. Yuwell occupies a position bridging home-care and hospital supply chains through specialty center partnerships in Guangdong and Sichuan. These three represent distinct strategic archetypes—imaging component integration, disposable manufacturing scale, and reverse-flow channel development—that shape competitive dynamics under SAMR pricing oversight and NMPA registration requirements.
| Leading Market Players |
|---|
| Mindray Medical International Limited |
| Weigao Group |
| Yuwell |
| Medtronic |
| Johnson & Johnson |
| Cardinal Health |
| 3M |
| B. Braun |
| MicroPort Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed domestic manufacturers and family-owned mid-cap disposable producers anchor China's hospital supply base, compressing procurement costs through captive polymer processing while NMPA registration barriers protect pricing power for compliant incumbents.
Pricing Analysis
Total cost of ownership anchors municipal tender evaluation in Shanghai, bundling software maintenance and technician training into multi-year imaging contracts. Price differentiation separates premium-tier domestic producers with NMPA innovation pathway access from standard-tier commodity suppliers serving provincial coalitions. Cost compression in high-volume consumables intensifies as SAMR volume-based purchasing aggregates demand across Jiangsu and Zhejiang. Public hospital procurement committees exhibit acute price sensitivity for surgical kits, while tertiary centers in Beijing retain discretion for advanced instrument selection.
Supply Chain Analysis
Polymer feedstock supply rests on petrochemical producers in Shandong and Liaoning provinces, with specialty resin grades imported from South Korea and Japan for biocompatible applications. Raw material dependencies center on polypropylene, polyethylene, and medical-grade silicone elastomers. Single-source vulnerability concentrates in imported imaging sensor components subject to export control screening. Distribution runs through provincial centralized procurement platforms for consumables, while capital equipment flows via direct manufacturer-hospital negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
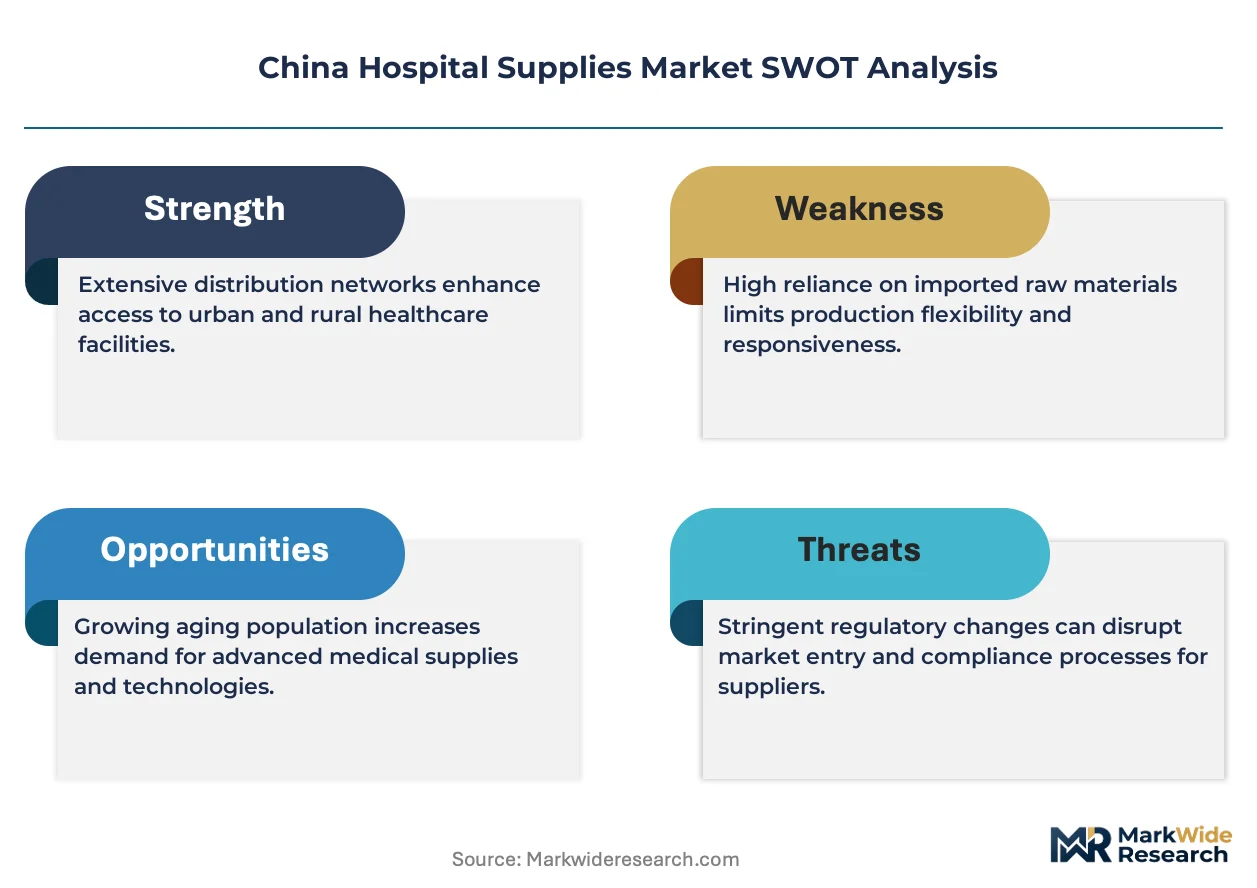
China's hospital supply market reads as a cost-of-compliance story where NMPA device registration requirements and GB standards testing relationships erect formidable barriers-to-entry moats for established domestic players.
For Market Incumbents: Deploy multi-year service contract bundling to lock in tier-three hospital relationships before provincial coalition expansion accelerates. Deepen backward integration into polymer compounding to offset MEE environmental compliance add-ons and petrochemical input volatility. Consolidate testing laboratory partnerships to accelerate NMPA pathway navigation for next-generation surgical instruments.
For New Entrants and Emerging Players: Capture home-care hospital integration channels in Guangdong and Sichuan specialty centers where partnership flexibility exceeds public procurement rigidity. Target telemedicine infrastructure deployment in digitally immature tier-two facilities facing regional health bureau mandates. Lead with cloud-connected monitoring systems that bypass legacy hospital information system interoperability barriers through modular API architectures.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale domestic manufacturers with dormant NMPA registration portfolios and underutilized GB standards testing relationships in the Yangtze River Delta. Long-term viability hinges on positioning for post-consolidation procurement platform qualification. Watch provincial coalition expansion pace as the inflection signal for margin compression severity.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation Pathway Registration | Accelerated approval timelines privilege domestic producers serving Beijing and Shanghai tertiary centers. |
| Provincial Coalition Tender Qualification | Scale thresholds under SAMR oversight determine access to high-volume consumables procurement. |
| MEE Carbon Accounting Certification | Early accreditation positions suppliers for preferential scoring in municipal hospital systems. |
| Home-Care Specialty Center Partnership | Reverse-flow channels in Guangdong and Sichuan bypass standard hospital procurement barriers. |
| Integrated Service Contract Bundling | Multi-year maintenance agreements lock in tier-three hospital relationships against competitor displacement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across hospital procurement managers, biomedical engineers, GPO contracts managers, and NMPA regulatory affairs specialists. Secondary sources encompassed hospital procurement databases, SAMR centralized purchasing platform disclosures, MEE emissions compliance filings, and medical device import customs records. Bottom-up segment sizing and top-down macro validation were triangulated to produce integrated market estimates.
Data-stream reconciliation across product type, technology readiness, end-user facility tier, and distribution channel dimensions shaped the analytical framework. CAGRs were derived from trend extrapolation moderated by regulatory inflection points and procurement policy shifts. Forecast inputs incorporated NMPA registration pipeline velocity, provincial coalition expansion schedules, and MEE dual carbon compliance trajectory.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA pathway rule changes, SAMR pricing oversight intensity, and polymer feedstock cost trajectories. Assumptions reflect documented procurement policy trajectories and regulatory filing patterns. A small set of triggers—provincial coalition geographic expansion, MEE carbon accounting framework finalization, and NMPA innovation pathway eligibility criteria—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Sterile Container Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Safety Needles Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Europe Insulin Syringe Market