
 Digital Media Market | 2026-2036
Digital Media Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Media Market Analysis
Enterprise marketing departments are realigning budgets from traditional broadcast toward programmatic digital channels. DAZN leverages sports streaming rights to anchor subscriber retention across European and Asian markets. Grammarly sustains product-led growth through AI-assisted writing tools embedded in professional workflows. Dow Jones competes in premium financial news distribution, controlling institutional subscription revenue streams.
Digital media encompasses video, audio, text, and image content distributed through social media, streaming platforms, websites, and mobile applications, encoded via adaptive bitrate streaming protocols and delivered through content delivery networks to optimize latency below two seconds for live broadcasts. Video content dominates bandwidth consumption and advertising revenue pools, while mobile apps represent the fastest-growing delivery channel as 5G networks reduce buffering friction. Native advertising formats command premium pricing due to higher engagement metrics versus standard display inventory.
The FCC governs broadcast-to-digital transition standards in the United States, while GDPR and the EU AI Act impose consent and algorithmic transparency obligations across European operations. India's TRAI issues net neutrality directives that shape streaming cost structures and platform competition. Stakeholders must monitor emerging platform liability frameworks and first-party data strategies as third-party cookies deprecate across major browsers.
Market Dynamics
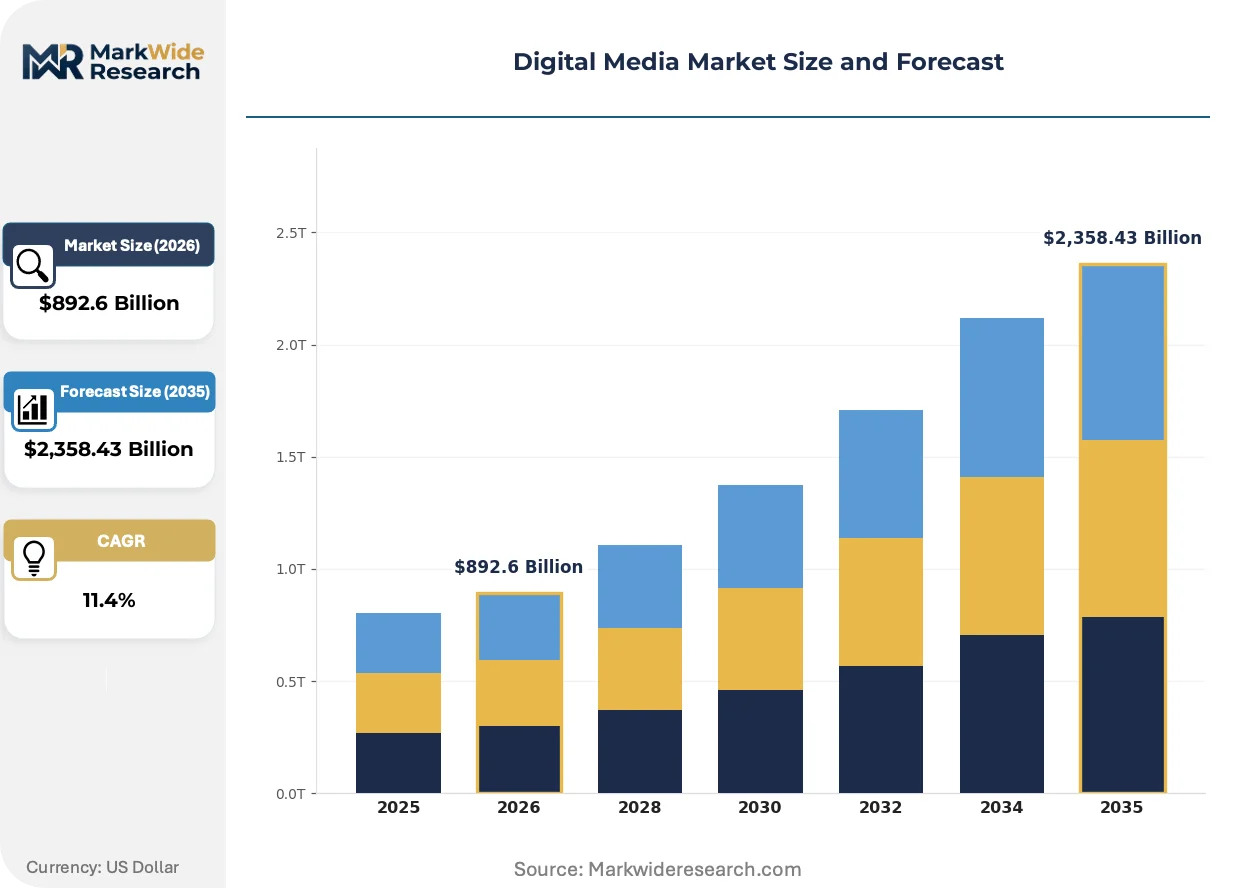
Programmatic advertising infrastructure and first-party data architectures are restructuring competitive advantage in digital media, as third-party cookie deprecation forces enterprises to rebuild audience targeting capabilities around authenticated user relationships and contextual intelligence.
Growth Catalysts
- 5G network densification:Mobile carriers in India and China are expanding millimeter-wave coverage, reducing live-streaming latency to sub-two-second thresholds and enabling interactive broadcast formats previously constrained by bandwidth.
- GDPR consent frameworks:European publishers have operationalized transparent data collection as a subscriber trust mechanism, converting compliance investment into direct-to-consumer subscription revenue streams.
- Programmatic CTV adoption:Connected television inventory in the United States is migrating from upfront commitments to real-time bidding, compressing sales cycles and expanding addressable audience pools for performance marketers.
Market Restraints
- Content licensing cost inflation:Exclusive sports and entertainment rights in European markets have escalated 40-60% across major streaming platforms, compressing subscriber lifetime value economics.
- Algorithmic transparency mandates:The EU AI Act imposes explainability requirements on recommendation engines, increasing engineering overhead for personalization systems.
- Ad-supported substitution:Free ad-supported streaming television (FAST) channels are capturing price-sensitive viewers who previously subscribed to premium tiers.
Strategic Opportunities
- India's rural broadband expansion:BharatNet infrastructure deployment is connecting 250,000+ village-level access points, creating first-time streaming audiences in regional language markets.
- Interactive commerce integration:Shoppable video formats are converging live-streaming with embedded checkout, opening direct-response revenue models for product categories from cosmetics to automotive.
- Carbon disclosure alignment:The EU CSRD mandates streaming platforms to report Scope 3 emissions from content delivery networks, creating competitive differentiation for providers with renewable-powered edge infrastructure.
Industry Challenges
- First-party data engineering scarcity:Publishers face acute shortages of identity resolution specialists capable of building unified customer data platforms that replace deprecated cookie-based targeting.
- Cross-platform measurement fragmentation:Inconsistent attention metrics across mobile apps, connected TVs, and desktop browsers complicate media planning and attribution modeling for enterprise advertisers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Media Market |
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $2,358.43 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video, Audio, Text, Image Delivery Channel: Social Media, Streaming Platforms, Websites, Mobile Apps Ad Format: Display Ads, Native Ads, Video Ads, Sponsored Content Audience Segment: Millennials, Generation Z, Seniors, Professionals |
| Companies Covered | Plex, VideoAmp, Minute Media, GumGum, Rokt, DAZN, Grammarly, Dow Jones, Grammerly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Media Market Emerging Trajectories
Generative artificial intelligence is compressing content production timelines and enabling real-time personalization at scale, while regulatory pressure on algorithmic systems forces architectural redesign of distribution platforms.
Adaptive bitrate streaming protocols combined with edge computing nodes are rewriting how live content reaches audiences. Broadcasters and sports leagues are deploying these technologies to deliver 4K video with sub-second latency to mobile devices. The structural consequence is collapsing the distinction between broadcast television and interactive digital experiences, as viewers gain pause, replay, and multi-angle control previously reserved for on-demand libraries.
The EU AI Act's risk classification system for recommendation algorithms is mandating human oversight and audit trails for high-impact systems. Publishers operating in European markets must document how automated curation influences user behavior and electoral discourse. News and political content platforms are most affected, with several organizations establishing dedicated algorithmic accountability officers and external audit relationships.
Enterprise marketing departments are consolidating media buying around outcome-based performance guarantees rather than impression-based commitments. This procurement evolution displaces traditional upfront guarantees with dynamic budget allocation tied to verified conversions. The shift is most visible in the United States, where direct-to-consumer brands now dominate programmatic CTV spending and demand supply-path optimization to reduce intermediary fees.
Digital Media Market Segmentation
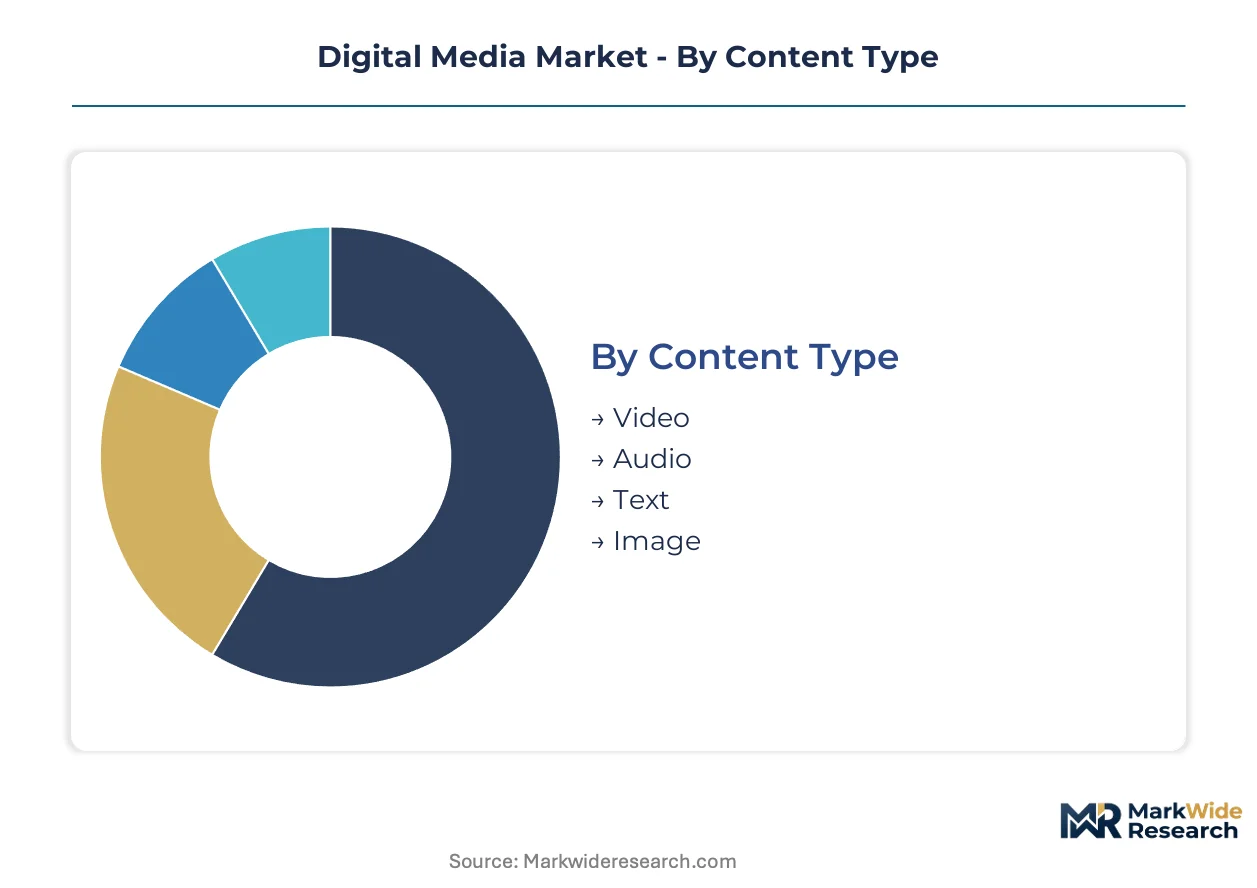
Segmentation in digital media reveals how content economics, distribution infrastructure, and audience monetization models diverge across technical and demographic dimensions. Buyers allocate budgets differently based on latency requirements, ad format performance, and generational consumption patterns.
Content Type:
Production cost intensity and bandwidth requirements drive procurement priorities for enterprise buyers licensing content libraries.
- Video:Adaptive bitrate streaming protocols encode 4K and live broadcasts, consuming the majority of CDN bandwidth. Demand concentrates among sports leagues and entertainment studios in the United States and India as 5G densification reduces buffering friction for mobile-first audiences.
- Audio:Podcasts and music streaming operate at lower bitrates, enabling offline caching and subscription bundling. European publishers leverage GDPR-compliant consent frameworks to convert listeners into direct subscribers, particularly in Germany and France.
- Text:News articles and newsletters distribute through email and aggregator platforms with minimal infrastructure overhead.
- Image:Stock photography and user-generated content support programmatic advertising at scale.
Video leads on scale; Audio leads on momentum.
Delivery Channel:
Latency thresholds and audience addressability determine platform selection for performance marketers.
- Streaming Platforms:Subscription video-on-demand and live services deploy edge computing nodes to achieve sub-two-second latency. India's rural broadband expansion through BharatNet infrastructure is creating first-time streaming audiences in regional language markets previously unreachable.
- Mobile Apps:Native applications capture the deepest engagement metrics through push notifications and offline functionality. China's MIIT regulations shape data localization requirements for apps operating in that market.
- Social Media:Algorithmic feeds optimize for attention duration through recommendation engines now subject to EU AI Act transparency mandates.
- Websites:Open-web inventory faces measurement fragmentation as third-party cookies deprecate across major browsers.
Streaming Platforms command the largest addressable audiences; Mobile Apps are gaining share fastest.
Ad Format:
Engagement depth and viewability standards differentiate pricing power across inventory types.
- Native Ads:Editorial-style placements within content feeds command premium CPMs through higher click-through rates. United States-based direct-to-consumer brands now dominate programmatic native spending, demanding supply-path optimization to reduce intermediary fees.
- Video Ads:Pre-roll and mid-roll formats in streaming environments benefit from completion rate advantages over skippable social inventory.
- Display Ads:Banner and rich media units face pricing pressure from ad-supported substitution trends in connected television.
- Sponsored Content:Publisher-produced branded articles and videos require disclosure compliance under FTC guidelines in the United States.
Native Ads lead on margin; Video Ads lead on volume expansion.
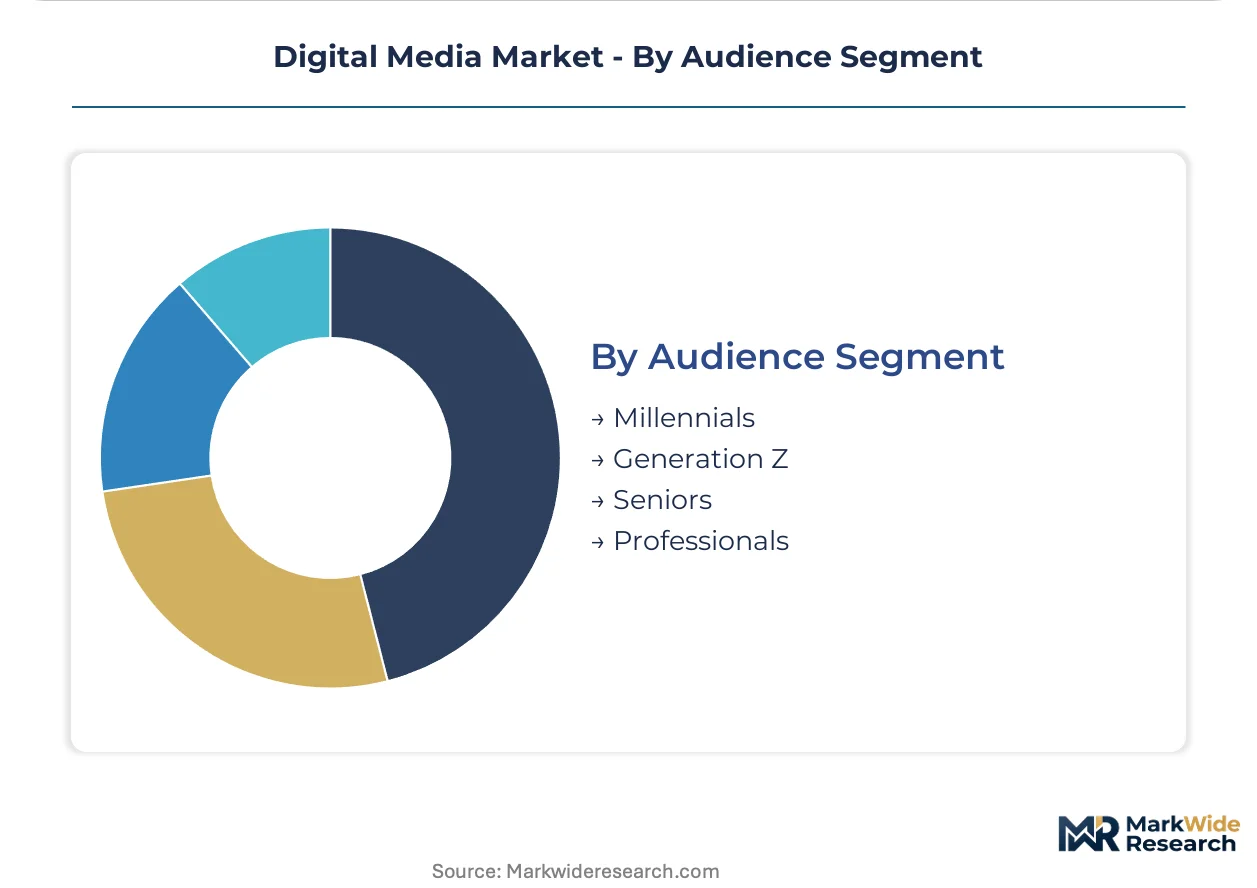
Audience Segment:
Platform preferences and payment willingness stratify content investment and subscription pricing.
- Generation Z:Short-form vertical video consumption on mobile-first platforms defines engagement patterns. India's youth demographic drives regional language content production as BharatNet infrastructure expands rural connectivity.
- Professionals:Business news and productivity tool subscriptions sustain recurring revenue through enterprise procurement. Grammarly and Dow Jones compete for institutional licensing budgets in the United States and United Kingdom.
- Millennials:Family-oriented streaming bundles and podcast consumption balance entertainment with educational content.
- Seniors:Linear television migration to connected TV platforms creates addressable inventory for healthcare and financial services advertisers.
Professionals lead on lifetime value; Generation Z leads on engagement intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors the digital media industry's infrastructure investment and platform development, though competitive dynamics now concentrate across five distinct national markets with divergent regulatory and demand profiles.
United States
Enterprise marketing departments drive programmatic advertising procurement, particularly for connected television inventory migrating to real-time bidding. The FCC governs broadcast-to-digital transition standards while the FTC enforces disclosure compliance for sponsored content formats. New York and Los Angeles host the dominant content production clusters, where streaming platforms and advertising technology firms co-locate to capture talent density and brand proximity.
China
MIIT regulations shape data localization requirements for mobile applications serving domestic audiences, compelling infrastructure investment at national scale. The country's dual carbon goals pressure streaming platforms to report emissions from content delivery networks. Beijing and Shanghai concentrate platform headquarters and cloud infrastructure deployment, with Hangzhou emerging as a hub for live-commerce technology integration.
India
BharatNet infrastructure deployment connects 250,000+ village-level access points, creating first-time streaming audiences in regional language markets. TRAI issues net neutrality directives that shape streaming cost structures and platform competition. Mumbai and Bangalore anchor content production and technology development respectively, with Hyderabad building specialized capacity for regional language media.
Germany
GDPR consent frameworks have operationalized transparent data collection as a subscriber trust mechanism, converting compliance investment into direct-to-consumer revenue. The EU AI Act imposes explainability requirements on recommendation engines deployed to German audiences. Berlin hosts a cluster of audio streaming and podcast production studios, while Munich concentrates advertising technology engineering.
United Kingdom
Professional productivity tool subscriptions sustain recurring revenue through enterprise procurement, particularly for AI-assisted writing and financial news distribution. The Information Commissioner's Office enforces GDPR-aligned standards for algorithmic transparency in content curation. London anchors premium financial news distribution and advertising technology development, with Manchester building capacity for regional content production.
Digital Media Market Vendor Landscape
Strategic partnerships dominate the current landscape as platforms seek exclusive content rights and advertising technology integration. The vendor base organizes around three tiers: global streaming platforms with original content libraries, specialized advertising technology providers with measurement capabilities, and productivity tool developers embedding AI into professional workflows. Consolidation pressures concentrate among mid-scale streaming services facing content licensing cost inflation. Geographic expansion and technology licensing represent the primary competitive vectors as enterprises rebuild audience targeting around first-party data architectures.
Within the streaming platform tier, DAZN exemplifies sports-rights-driven subscriber retention across European and Asian markets. Grammarly occupies a position among productivity tool developers leveraging AI-assisted functionality for professional workflow integration. Dow Jones anchors the premium financial news distribution segment, controlling institutional subscription revenue streams in the United States and United Kingdom.
| Leading Market Players |
|---|
| Plex |
| VideoAmp |
| Minute Media |
| GumGum |
| Rokt |
| DAZN |
| Grammarly |
| Dow Jones |
| Grammerly |
| Others |
Supply Flow & Price Mechanics
The EU CSRD mandates streaming platforms to report Scope 3 emissions from content delivery networks, gating qualified supply relationships and premium-tier pricing access for providers with renewable-powered edge infrastructure. This sustainability disclosure framework separates compliant publishers from legacy operators while reshaping procurement criteria for enterprise advertisers seeking carbon-aligned inventory.
Pricing Analysis
Direct-to-consumer subscription margins compress intermediary layers between content platforms and end users. Three-tier pricing structure across premium, standard, and economy levels stratifies access based on ad load tolerance and resolution quality. Price differentiation rests on exclusive sports rights and original programming investment. Cost compression in ad-supported tiers is intensifying because FAST channels capture price-sensitive viewers who previously subscribed to premium tiers. Small-market streaming services exhibit highest price sensitivity; institutional enterprise licensing shows lowest.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel streaming platforms to qualify multiple CDN providers across United States, India, and Germany markets. Content delivery architecture draws from edge computing nodes, renewable energy contracts, and transatlantic fiber capacity. Single-source vulnerability concentrates in exclusive licensing agreements with major sports leagues and entertainment studios. Distribution runs through programmatic exchanges, direct publisher integrations, and platform-owned sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital media hinges on first-party data monetization and premium subscription tier migration as enterprises rebuild audience targeting capabilities around authenticated user relationships.
For Market Incumbents: To counter ad-supported substitution threatening premium subscriber retention, streaming platforms should deepen exclusive content licensing and deploy AI-assisted personalization engines. Vertical integration into owned-and-operated advertising technology stacks preserves margin capture from programmatic transactions. First-party data platform investment replaces deprecated cookie-based targeting with unified customer identity resolution.
For New Entrants and Emerging Players: Capture India's rural broadband expansion through BharatNet infrastructure as the most penetrable geography for regional language streaming services. Regional content production partnerships and offline-first mobile app architectures address connectivity constraints. Go-to-market positioning emphasizes hyperlocal sports rights and vernacular entertainment catalogs unavailable from global platforms.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale advertising technology specialists because first-party data engineering scarcity creates valuation premiums for identity resolution capabilities. Long-term viability centers on platforms with authenticated user bases and direct subscription revenue exposure. Signal to watch: regulatory enforcement patterns under the EU AI Act recommendation engine mandates as inflection indicator for compliance cost allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Platform Buildout | Unified customer data platforms replace deprecated third-party cookie targeting for enterprise advertisers. |
| Exclusive Content Licensing | Sports and entertainment rights anchor subscriber retention against ad-supported substitution trends. |
| Programmatic CTV Integration | Real-time bidding infrastructure captures connected television inventory migrating from upfront commitments. |
| Regional Language Expansion | BharatNet infrastructure deployment creates first-time streaming audiences in previously unreachable Indian markets. |
| Algorithmic Accountability Investment | EU AI Act compliance documentation and audit trail capabilities satisfy European transparency mandates. |
Methodological Framework
Direct dialogue with streaming platform executives, advertising technology engineers, content licensing directors, and enterprise marketing procurement officers grounds qualitative assessment in operational reality. Secondary validation incorporates SEC filings from publicly traded media companies, TRAI regulatory directives, GDPR enforcement patterns, and hyperscaler infrastructure capex disclosures. Bottom-up and top-down triangulation cross-checks subscriber volume estimates against advertising revenue pools and content production expenditure data.
Bottom-up modeling aggregates platform-reported subscriber metrics and advertising revenue per user across deployment models, organization size, vertical specialization, and regional adoption patterns. Top-down analysis benchmarks total addressable market against broadband penetration curves and mobile data consumption trends. CAGRs derive from segment-level growth rate reconciliation against macroeconomic indicators and technology diffusion curves. Industry-specific forecast inputs include 5G network densification timelines and content licensing contract renewal schedules.
Underlying measurement precision varies by segment; subscription video-on-demand carries tighter precision than emerging interactive commerce formats. Forecasts reflect assumptions around regulatory enforcement intensity and technology adoption velocity. Deviation in third-party cookie deprecation timelines or EU AI Act implementation scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Video Production Market
Digital Media
Europe Anime Merchandising Market
Digital Media
United States Sports Betting Market
Digital Media
Mobile Entertainment Market
Digital Media
Europe Inflight Entertainment and Connectivity Market
Digital Media
Sports Broadcasting Technology Market
Digital Media
Europe Professional Audio Video (Proav) Market
Digital Media
Stock Music Software Market
Digital Media
Cognitive Media Market
Digital Media
3D Animation Market
Digital Media
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Digital Media
Digital Media Switchers Market
Digital Media
Digital Content Market
Digital Media
Online Art Market
Digital Media
Digital Content Creator Market
Digital Media
Online Gambling Market