
 Enterprise Firewall Market | 2026-2036
Enterprise Firewall Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Firewall Market Intelligence
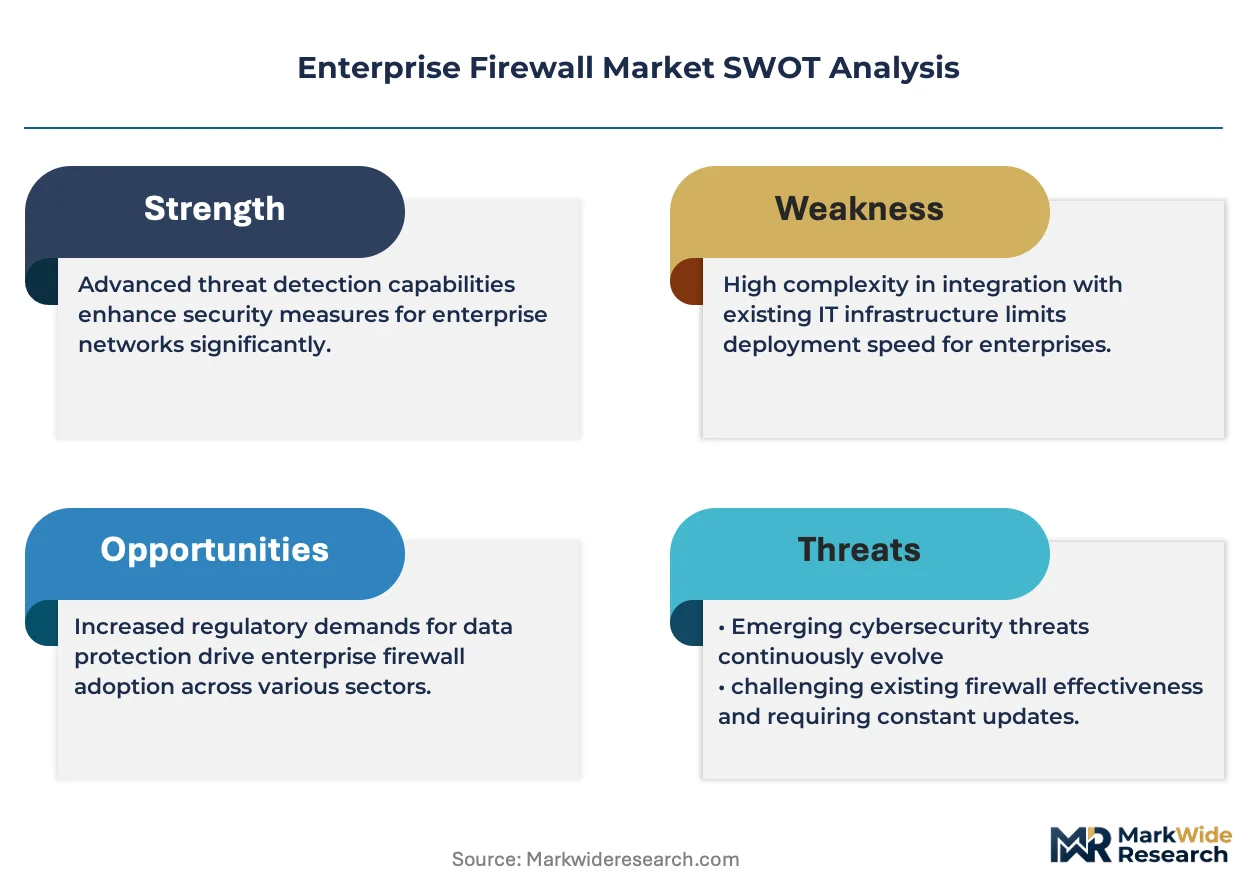
The capability gap between developing proprietary threat intelligence and relying on third-party data feeds is collapsing the market's middle tier. Palo Alto Networks leverages its extensive in-house research to differentiate its platforms. Fortinet sustains a competitive advantage through its custom-developed ASIC processors that accelerate security functions. Cisco Systems competes by integrating security features deeply within its vast networking hardware ecosystem.
An enterprise firewall is a network security system that establishes a barrier between a trusted internal network and untrusted external networks. These systems perform deep packet inspection to identify and block malicious traffic, including encrypted threats. Next-Generation Firewall solutions represent the dominant segment, displacing older stateful inspection firewalls. The market is also seeing a structural shift toward cloud-based and hybrid deployment models to secure distributed workforces and cloud assets.
Regulatory frameworks like the GDPR in Europe and HIPAA in the United States set strict requirements for data protection and network security. These mandates compel organizations to deploy firewalls with robust logging, auditing, and threat prevention capabilities. In China, the Cybersecurity Law imposes similar data localization and security obligations. Future investment decisions will balance security efficacy against the total cost of ownership and operational complexity.
Market Dynamics
The structural shift toward securing distributed workforces and multi-cloud environments is the primary force shaping the market. This decentralization of corporate assets renders traditional, on-premises perimeter defense models increasingly inadequate, compelling a move toward more flexible, cloud-native deployment models to protect data and applications everywhere.
Growth Catalysts
- Regulatory Mandates:Europe's GDPR and the US HIPAA framework compel investment in firewalls with advanced logging to avoid severe data breach penalties.
- BFSI Sector Demand:Financial institutions require sophisticated threat intelligence to protect high-value transactions, driving adoption of advanced firewall platforms.
- Encrypted Threat Inspection:The need to inspect SSL/TLS traffic for malware drives the market for Next-Generation Firewalls with deep packet inspection.
Market Restraints
- Total Cost of Ownership:High acquisition costs and mandatory subscriptions for threat intelligence feeds present a significant financial barrier for mid-sized enterprises.
- Operational Complexity:Configuring granular security policies for NGFWs in hybrid cloud environments requires specialized cybersecurity talent, which is often scarce and costly.
- Performance Bottlenecks:Activating features like SSL/TLS inspection can degrade network throughput, forcing a trade-off between security efficacy and network speed.
Strategic Opportunities
- Emerging Economies:Rapid digitalization in Southeast Asia and Latin America creates greenfield opportunities as businesses establish their initial security perimeters.
- OT and ICS Security:The IT/OT convergence in manufacturing and utilities presents an opportunity for specialized firewalls to protect industrial control systems.
- SASE Platform Integration:Integrating firewall-as-a-service (FWaaS) into Secure Access Service Edge (SASE) frameworks offers a unified security model for distributed workforces.
Industry Challenges
- Cybersecurity Skills Gap:A persistent shortage of trained security analysts capable of managing complex NGFW policies and responding to threats hinders effective firewall operation.
- Legacy System Integration:Integrating modern firewalls with an organization's existing, disparate security tools and network infrastructure creates operational friction and potential security gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Firewall Market |
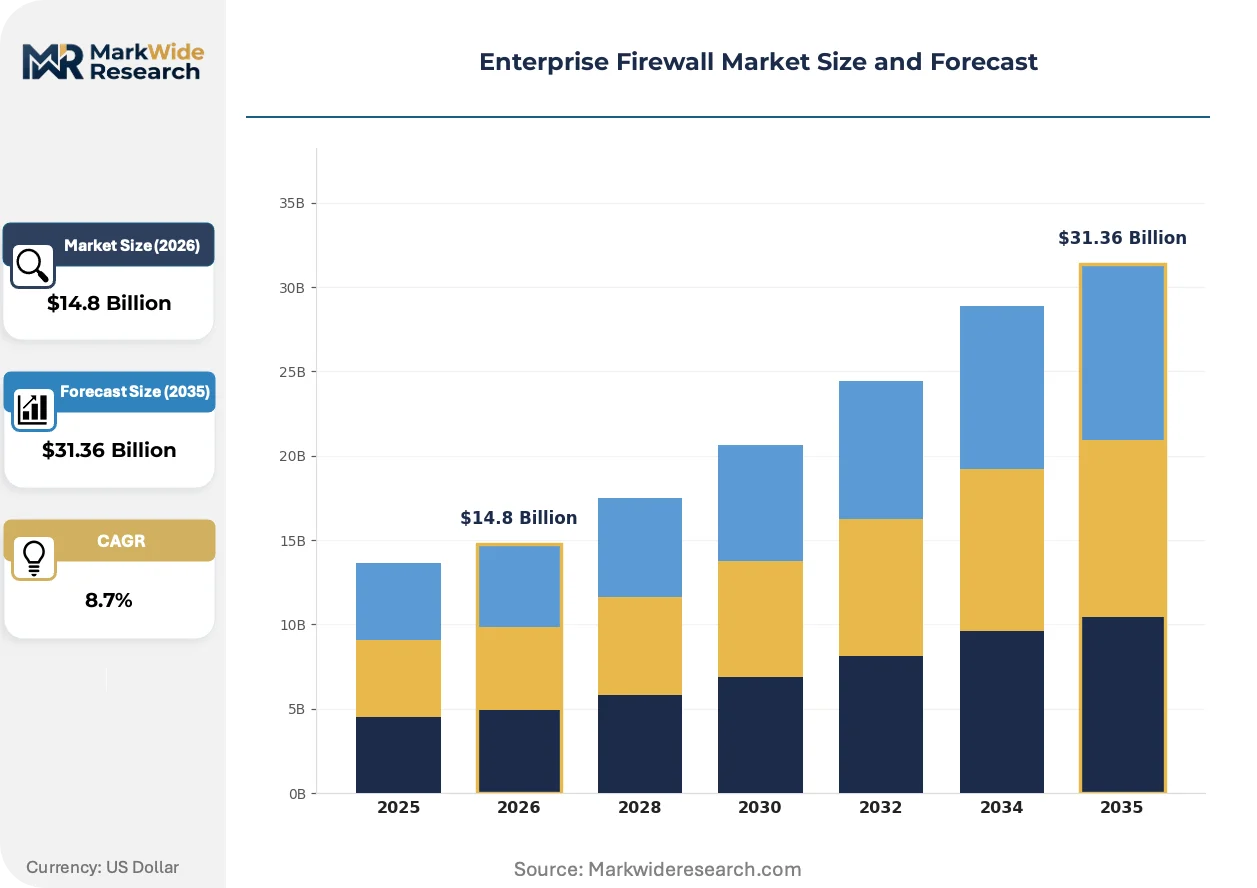
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized Solution Type: Unified Threat Management, Next-Generation Firewall, Stateful Inspection Firewall, Proxy Firewall Application: Data Center Security, Network Perimeter Defense, Secure Remote Access, Intrusion Prevention End User: BFSI, Telecommunications, Manufacturing, Energy & Utilities |
| Companies Covered | Palo Alto Networks, Fortinet, Check Point Software Technologies, Cisco Systems, Juniper Networks, Sophos, Barracuda Networks, WatchGuard Technologies, SonicWall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Firewall Market Strategic Shifts & Innovations
The market's evolution is defined by the shift from hardware-centric perimeter defense to intelligent, software-defined security models. This transition is driven by the need to secure dynamic, borderless networks against increasingly automated and sophisticated cyber threats that bypass traditional defenses.
Artificial intelligence and machine learning are being integrated into firewall platforms to automate threat detection and response. Large enterprises adopt these capabilities to analyze vast amounts of log data and identify anomalous patterns indicative of zero-day attacks. This automation is displacing the reliance on manual threat hunting and static, signature-based security policies.
China's Cybersecurity Law imposes strict data localization and security review requirements on companies operating within the country. This mandate forces multinational corporations to deploy separate firewall instances and security policies specifically for their Chinese operations, often using government-approved vendors. The financial services and technology sectors are most impacted by these compliance obligations.
A significant behavioral shift is the move from perpetual hardware licensing toward flexible, subscription-based consumption models. This trend affects the Firewall-as-a-Service (FWaaS) segment, where customers pay for security functions based on usage, rather than upfront capital expenditure. This model is most prominent in cloud-first organizations and mid-market enterprises seeking predictable operational spending.
Enterprise Firewall Market Segmentation
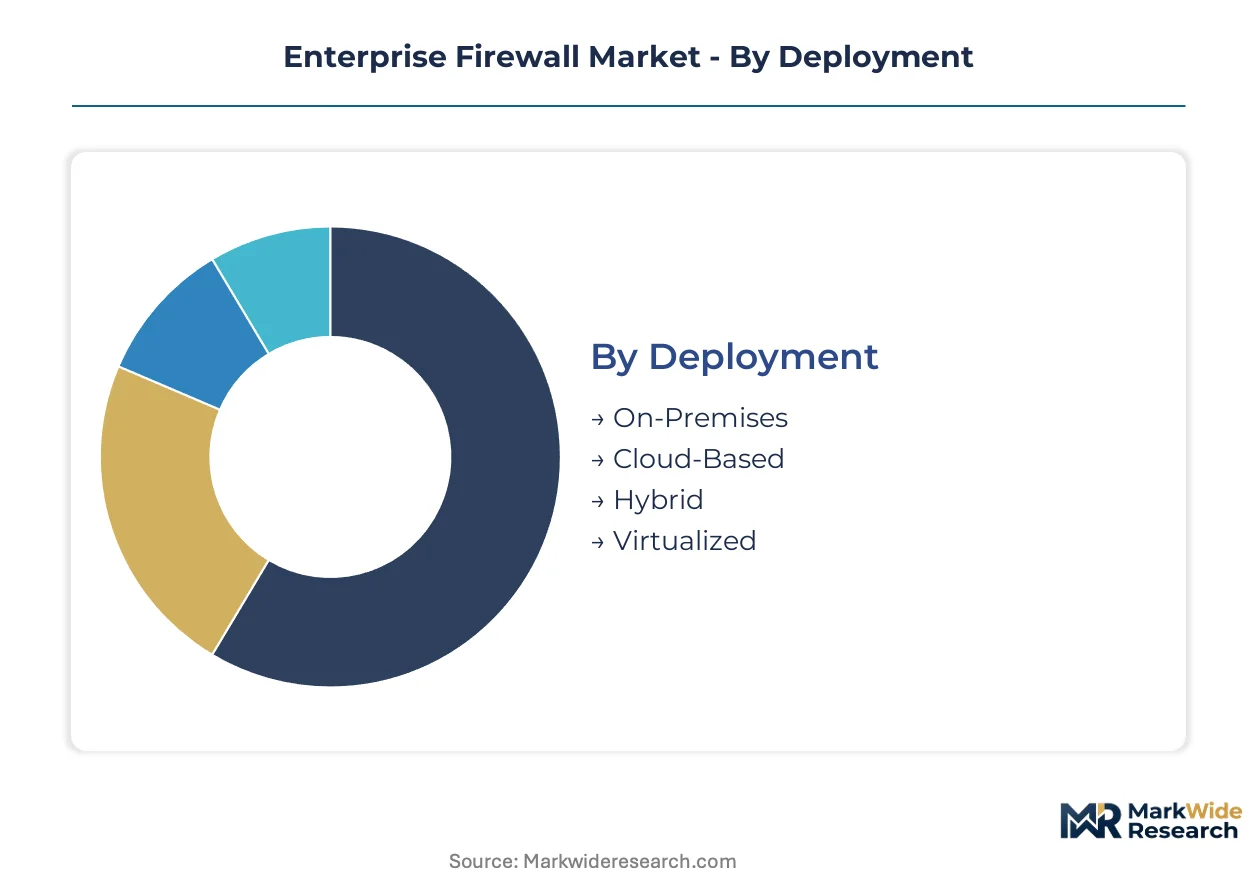
Understanding the Enterprise Firewall market through segmentation reveals distinct demand patterns and technological preferences across various deployment models, solution types, applications, and end-user industries. This granular view highlights where innovation and investment are concentrating, providing clarity on the market's structural evolution.
Deployment:
Margin pools for deployment models vary significantly based on infrastructure control and service delivery complexity. Cloud-Based and Hybrid models offer higher service-related margins due to ongoing management and subscription fees.
- On-Premises:These are traditional hardware or software firewalls installed directly within an organization's physical data center or network perimeter. Enterprises with strict data residency requirements or extensive legacy infrastructure often prefer on-premises deployments.
- Cloud-Based:Firewall-as-a-Service (FWaaS) solutions deliver security functions directly from the cloud, offering scalability and reduced infrastructure overhead. Demand concentrates in digital-native enterprises and distributed workforces seeking operational flexibility and simplified management.
- Hybrid:This model combines on-premises firewall appliances with cloud-delivered security services, creating a unified security posture across diverse IT estates. Large corporations managing both legacy systems and multi-cloud workloads widely adopt hybrid deployments, driven by data residency and performance needs.
- Virtualized:Software-defined firewalls run as virtual machines on standard server hardware, providing agility and automation for software-defined data centers and private cloud environments.
On-Premises deployment holds installed capacity. Cloud-Based is rotating up the share rankings.
Solution Type:
Cost tiers for solution types reflect their feature sets and threat intelligence capabilities, with Next-Generation Firewalls commanding premium pricing due to advanced functionalities.
- Unified Threat Management:UTM solutions consolidate multiple security functions, such as firewall, VPN, and anti-malware, into a single appliance or platform. Small and medium-sized enterprises widely adopt UTM for simplified security management and cost efficiency.
- Next-Generation Firewall:NGFWs integrate advanced features like deep packet inspection, intrusion prevention, and application control, going beyond traditional port and protocol inspection. Demand concentrates in financial institutions and government agencies needing robust threat protection against sophisticated attacks and encrypted threats.
- Stateful Inspection Firewall:This foundational firewall technology monitors the state of active network connections, allowing or blocking packets based on context established during a session.
- Proxy Firewall:Acting as an intermediary, a proxy firewall inspects traffic at the application layer, enforcing security policies and often masking internal network details.
Next-Generation Firewall solutions dominate new deployments. Unified Threat Management maintains its presence in the SMB segment.
Application:
The application landscape for enterprise firewalls is defined by distinct security objectives across various network segments, each addressing specific vulnerabilities.
- Data Center Security:This application focuses on protecting critical servers, applications, and sensitive data residing within centralized computing environments. Cloud service providers and large enterprises use specialized firewalls to secure virtualized workloads and east-west traffic.
- Network Perimeter Defense:This traditional application establishes a secure boundary between an organization's internal network and external untrusted networks, preventing unauthorized access. Enterprises globally prioritize this application to prevent data exfiltration and external attacks.
- Secure Remote Access:Firewalls facilitate secure connections for remote employees and partners to access corporate resources, often through VPNs and multi-factor authentication.
- Intrusion Prevention:Integrated firewall capabilities actively detect and block malicious activities, such as denial-of-service attacks or malware propagation, in real-time.
Network Perimeter Defense remains a foundational requirement. Data Center Security is expanding most quickly due to cloud adoption.
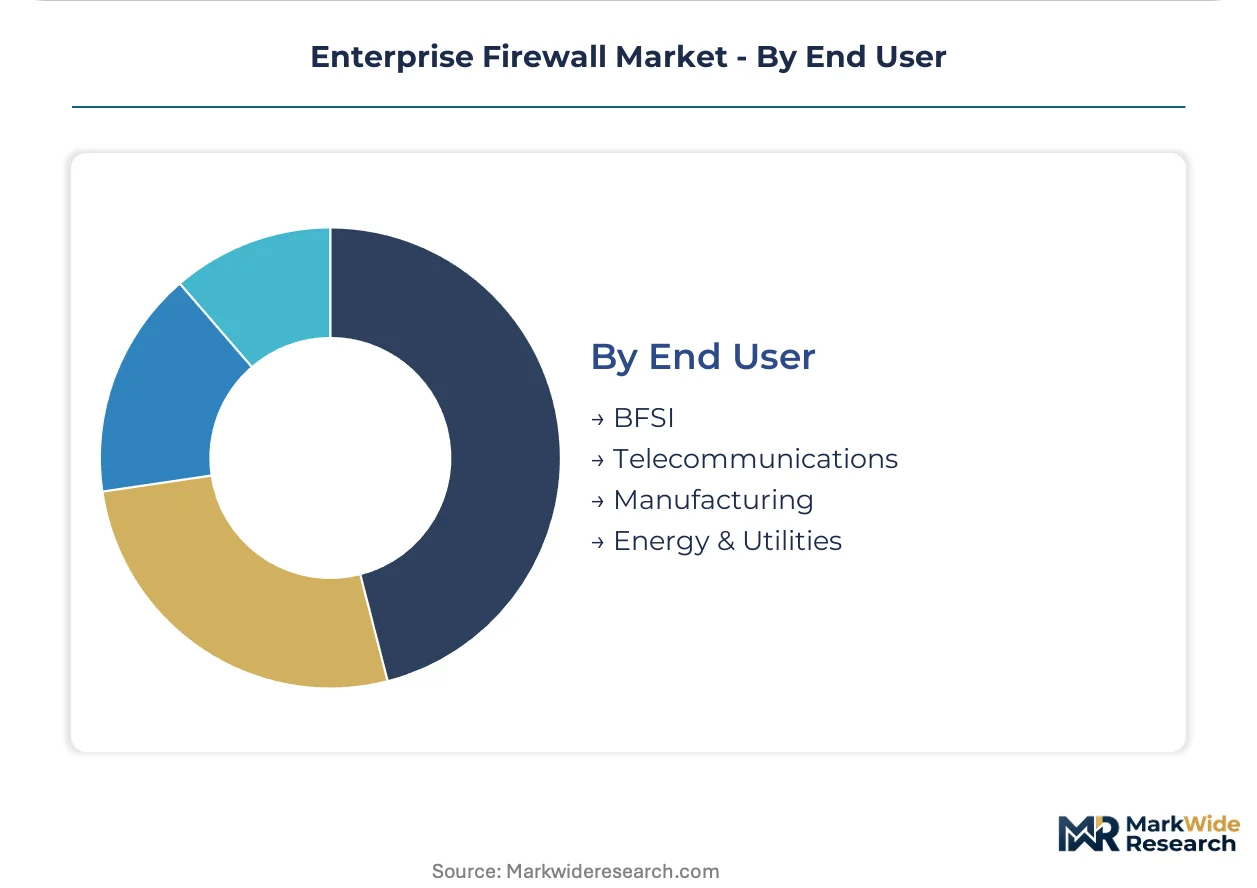
End User:
Customer type significantly influences firewall feature requirements and compliance considerations, driving specialized demand across various sectors.
- BFSI:Financial institutions require highly sophisticated firewall platforms with advanced threat intelligence and stringent compliance features to protect high-value transactions and sensitive customer data. Regulations like Europe's GDPR and the US HIPAA framework compel robust firewall deployments in this sector.
- Telecommunications:Network operators deploy high-performance firewalls to secure vast infrastructure, protect subscriber data, and ensure service continuity across their distributed networks. Managing large traffic volumes and complex network architectures presents unique security challenges for these providers.
- Manufacturing:This sector utilizes firewalls to protect industrial control systems (ICS) and intellectual property from cyber threats, particularly with the increasing IT/OT convergence.
- Energy & Utilities:Firewalls secure critical national infrastructure, protecting operational technology (OT) systems against cyber-physical attacks and ensuring operational resilience.
The BFSI sector drives demand for advanced capabilities. Telecommunications continues to be a significant consumer of high-throughput solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for advanced enterprise firewall solutions often concentrates in mature economies, while emerging markets prioritize cost-effectiveness for foundational security. This asymmetry influences deployment models and feature adoption across different regions. Demand for robust perimeter defenses remains universally high, driven by evolving cyber threats.
United States
Demand for advanced threat protection in the BFSI sector drives significant firewall investments across the United States. HIPAA regulations compel organizations to deploy firewalls with comprehensive logging and auditing capabilities to protect sensitive data. Silicon Valley and other tech hubs continue to innovate in cloud-native security architectures and SASE integration.
Germany
Strict GDPR compliance mandates necessitate robust firewall solutions for data protection across German enterprises, especially in data-intensive industries. The manufacturing sector's increasing IT/OT convergence requires specialized firewalls to secure industrial control systems. Major financial centers like Frankfurt drive demand for next-generation firewall platforms with deep packet inspection.
China
China's Cybersecurity Law imposes strict data localization and security review requirements, significantly influencing firewall deployment strategies for multinational corporations. Companies operating in China must often use government-approved vendors for their security infrastructure. Technology hubs in Shenzhen and Beijing lead in developing localized security solutions that comply with national regulations.
India
Rapid digitalization across Indian enterprises fuels demand for initial security perimeters and cloud-based firewall services, particularly among mid-market firms. The Reserve Bank of India (RBI) mandates stringent cybersecurity standards for the financial sector, driving advanced firewall adoption. Major IT centers like Bangalore and Hyderabad are increasingly adopting hybrid security models to protect distributed assets.
Singapore
Singapore's role as a regional financial and technology hub drives demand for advanced firewall platforms and SASE integration for digital-native businesses. The Cyber Security Agency of Singapore (CSA) promotes robust cybersecurity practices across critical national infrastructure. Fintech companies in Marina Bay require sophisticated threat intelligence for high-value transactions and regulatory compliance.
Enterprise Firewall Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the enterprise firewall market. The market structure is tiered, with established vendors offering comprehensive, feature-rich solutions alongside agile specialists focusing on niche security challenges. Three strategic archetypes emerge: integrated network security providers, pure-play firewall specialists, and cloud-native security innovators. Dominant competitive moves include strategic partnerships to expand ecosystem integration and continuous portfolio diversification into adjacent security domains, seeking to capture new revenue streams.
Within the integrated network security provider archetype, Cisco Systems, Inc. exemplifies a strategy of embedding security deeply within its vast networking hardware ecosystem, appealing to organizations seeking unified infrastructure management. Palo Alto Networks, Inc. represents a pure-play firewall specialist, leveraging extensive in-house research to differentiate its advanced threat prevention platforms that address sophisticated cyber threats. Fortinet, Inc. occupies a position as a provider known for custom-developed ASIC processors that accelerate security functions, catering to performance-sensitive environments requiring high-throughput security enforcement.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Fortinet |
| Check Point Software Technologies |
| Cisco Systems |
| Juniper Networks |
| Sophos |
| Barracuda Networks |
| WatchGuard Technologies |
| SonicWall |
| Others |
Cost & Logistics Intelligence
Europe's GDPR compliance mandates rigorous security standards, gating vendor qualification and influencing premium pricing for certified firewall solutions. This regulatory influence impacts both the availability of compliant offerings and the cost structures across the market.
Pricing Analysis
Configured-to-order pricing commands a premium over standard firewall solutions, reflecting the complexity of integrating advanced features for specific enterprise environments. The dominant pricing structure is subscription-based, particularly for Firewall-as-a-Service (FWaaS) and Next-Generation Firewalls. Price differentiation stems from the level of integrated threat intelligence and the extent of customization required for hybrid cloud deployments. Pricing softness affects the mid-market segment due to the high total cost of ownership for advanced platforms. BFSI and government agencies exhibit the least price sensitivity, prioritizing robust security over cost.
Supply Chain Analysis
Just-in-time inventory strategies characterize the software-defined firewall segment, while hardware appliances often require strategic stockpiles of critical components. Hardware manufacturing for enterprise firewalls concentrates in East Asia, particularly China, for base components and assembly. Key raw material dependencies include specialized ASIC chips and network processing units. Geopolitical tensions impacting semiconductor supply lines represent a structural risk to hardware availability. Distribution of firewall solutions primarily runs through a network of value-added resellers and direct sales to large enterprise clients, alongside cloud marketplaces for FWaaS offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enterprise firewall market is entering a cyclical recovery, driven by renewed enterprise IT spending on digital transformation initiatives.
For Market Incumbents: Fortify core market positions by accelerating the integration of AI and machine learning into threat detection engines. Acquire specialized cloud-native security startups to counter the threat from agile, cloud-first competitors. Invest heavily in R&D for advanced SSL/TLS inspection capabilities to maintain a technological edge. Consolidate product portfolios to offer unified security platforms, simplifying management for complex hybrid environments.
For New Entrants and Emerging Players: Differentiate on specialized security for emerging vectors like operational technology (OT) and industrial control systems (ICS). Target mid-market enterprises and cloud-native businesses seeking flexible, subscription-based Firewall-as-a-Service solutions. Focus on delivering simplified deployment and management through intuitive user interfaces. Partner with managed security service providers (MSSPs) to leverage existing sales channels and reduce customer acquisition costs.
For Investors and Strategic Acquirers: China's Cybersecurity Law reshapes the acquisition landscape for localized security solutions within that market. The long-term viability of the enterprise firewall market remains strong over the next 5-10 years due to escalating cyber threats and evolving regulatory mandates. Identify acquisition targets specializing in AI-driven threat intelligence, SASE platform integration, or cloud-native network security. A significant signal to watch is the increasing consolidation of point security solutions into comprehensive SASE frameworks by major vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies diverse security functions for simplified management across IT estates. |
| AI/ML Development | Automates threat detection and response capabilities against sophisticated attacks. |
| SASE Integration | Delivers unified security for distributed workforces and multi-cloud environments. |
| Cloud-Native Offering | Addresses demand for flexible, scalable security solutions with operational agility. |
| Channel Partnership | Expands market reach to mid-sized enterprises and specialized vertical segments. |
Research Approach
A standing panel of CISOs, network architects, security operations managers, and cloud security engineers provided ongoing calibration to the market model. This primary research was combined with extensive secondary validation from regulatory compliance documents, cybersecurity threat reports, and enterprise IT spending surveys. Both bottom-up and top-down triangulation methods were employed to ensure data consistency and accuracy.
Outputs were cross-validated against external benchmarks and industry-reported metrics to ensure their consistency and reliability. The analytical framework incorporated quantitative modeling across the analysis window, segmenting the market by deployment model, solution type, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected growth drivers over the projection horizon, considering enterprise IT security budgets and adoption rates of cloud services.
Forecasts assume regulatory continuity in Europe's GDPR and the US HIPAA framework; material policy shifts would require re-modeling and re-evaluation of market trajectories. These projections reflect assumptions regarding technological advancements and macroeconomic stability. Revision becomes warranted when significant shifts in global cybersecurity spending or regulatory enforcement cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Digital Immune System Market
Cybersecurity
Education Data Security Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
Server Security Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
Information Security Products and Services Market
Cybersecurity
Global SSH Terminal Market
Cybersecurity
Global Quantum Cryptography Solutions Market
Cybersecurity
Global Breach and Attack Simulation Market
Cybersecurity
E-Mail Security Market
Cybersecurity
Cybersecure Vehicle Control Unit Gateway Systems Market
Cybersecurity
North America Cyber Security Market
Cybersecurity
Global Deep Packet Inspection (DPI) Market
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Network Sandboxing Market