
 Global Digital Assurance Market | 2026-2036
Global Digital Assurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Assurance Market Foresight
Enterprise buyer concentration is rebalancing as mid-market banks and regional insurers fragment procurement across specialized vendors rather than consolidating with single providers. Tata Consultancy Services anchors large-scale quality engineering programs for North American financial clients. Accenture differentiates through AI-infused testing platforms that reduce defect detection cycles. Wipro competes aggressively on price for cloud-native assurance contracts in the telecommunications vertical.
Digital assurance encompasses systematic verification, validation, and monitoring of software ecosystems to guarantee functional integrity, security posture, and regulatory conformance across distributed architectures. The discipline employs automated test orchestration, synthetic transaction monitoring, and continuous compliance scanning to prevent production failures in mission-critical systems. Testing Automation and Security Validation command the deepest margin pools as enterprises prioritize zero-trust architecture validation and shift-left security integration. Cloud-Based deployment models are expanding fastest as organizations retire legacy on-premises test labs, though Hybrid configurations persist in regulated sectors requiring data sovereignty controls.
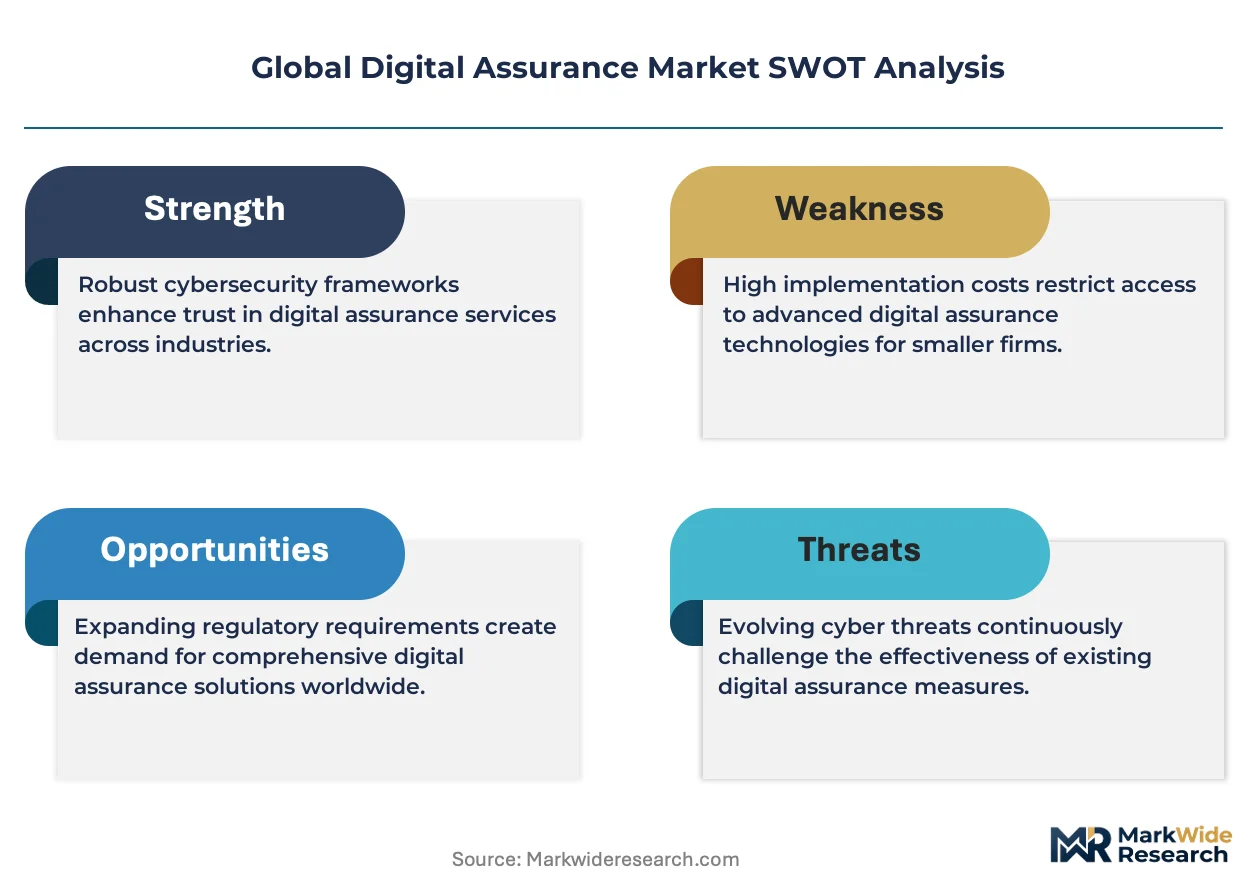
ISO 27001 certification requirements, EU GDPR audit mandates enforced by national data protection authorities, and SEC cybersecurity disclosure rules are elevating demand for documented assurance trails and independent validation reporting. India's BIS standards for IT service quality and the US FAA's software integrity guidelines for aviation systems further fragment compliance requirements across verticals. Stakeholders must evaluate whether their assurance portfolios can absorb emerging algorithmic accountability obligations without eroding delivery economics.
Market Dynamics
Cloud migration mandates from the EU and US SEC are forcing financial institutions to revalidate entire software estates, compressing testing cycles while expanding scope to include continuous compliance monitoring across distributed architectures.
Growth Catalysts
- EU GDPR audit mandates:National data protection authorities in France, Germany, and Italy enforce documented assurance trails, expanding demand for independent validation reporting across banking and insurance software ecosystems.
- Shift-left security integration:DevOps pipelines now embed automated vulnerability scanning from design phase, pulling testing automation spend earlier in development cycles for cloud-native applications.
- India:IT services clusters in Bangalore and Hyderabad supply cost-competitive testing capacity, anchoring global delivery models for North American and European financial services clients.
Market Restraints
- Specialized talent scarcity:Shortage of engineers certified in ISO 27001 and cloud security architecture inflates labor costs for zero-trust validation programs.
- Supply concentration in South India:Testing capacity clusters in Bangalore and Hyderabad create geographic risk exposure during regional infrastructure disruptions or policy shifts.
- Legacy system technical debt:Mainframe-dependent banks face integration friction when connecting modern API-based assurance tools to COBOL-era core systems.
Strategic Opportunities
- Brazil:ANVISA digital health software regulations and open banking mandates create unmet demand for localized assurance services in Latin America's largest financial market.
- AI Act compliance services:EU algorithmic accountability obligations for high-risk systems open new service lines for bias testing and explainability validation.
- Synthetic transaction monitoring:Convergence of robotic process automation with behavioral analytics enables continuous production validation without customer data exposure.
Industry Challenges
- Multi-framework certification complexity:Simultaneous ISO 27001, SOC 2, and sector-specific audits for aviation (FAA) and healthcare (HIPAA) strain documentation and timeline coordination.
- Cloud repatriation friction:Data sovereignty requirements in Germany, France, and Saudi Arabia force reconfiguration of test environments originally architected for centralized cloud regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Assurance Market |
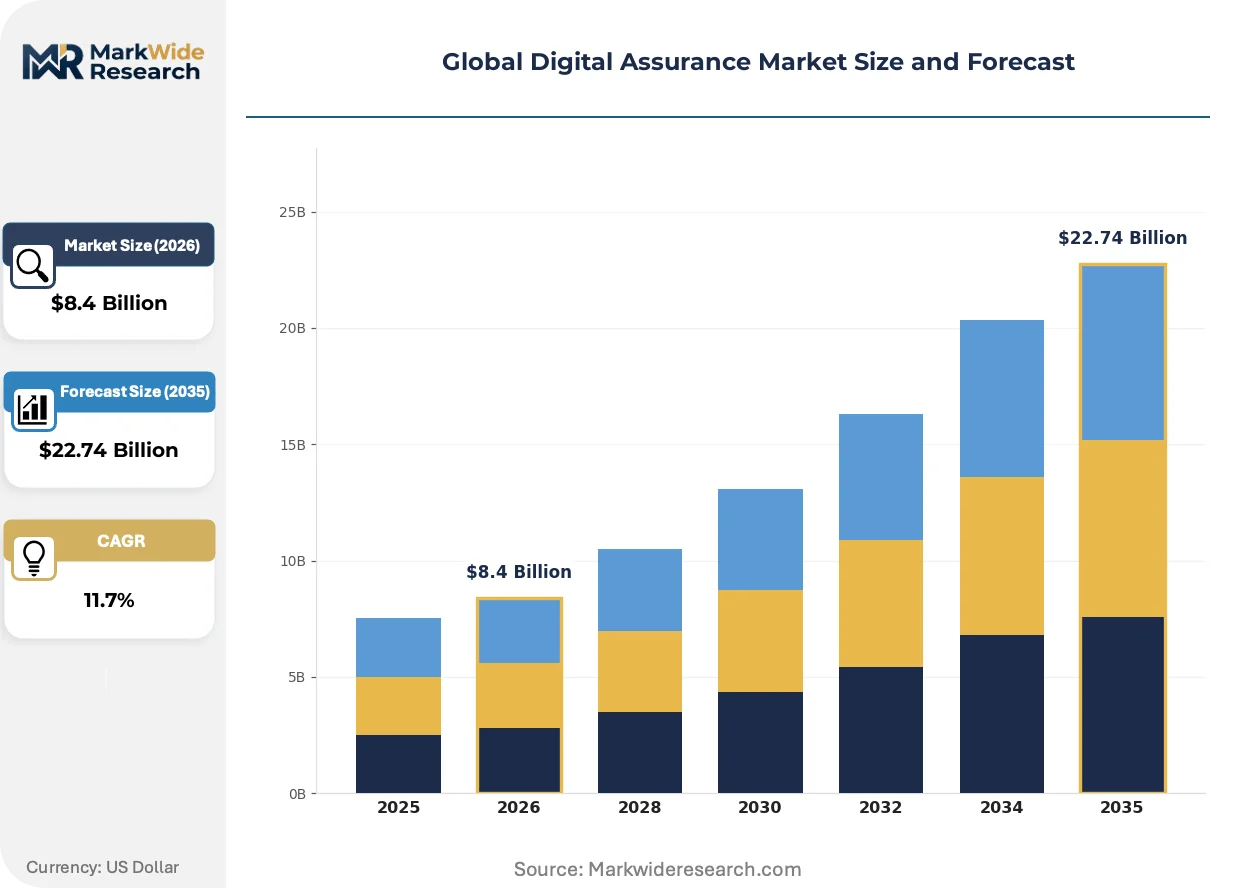
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing Automation, Performance Testing, Security Validation, Compliance Monitoring, Usability Assessment Technology: AI & Machine Learning, Cloud Computing, Blockchain Verification, Robotic Process Automation, Big Data Analytics End User: Financial Institutions, Telecommunications Providers, Software Developers, E-Commerce Platforms, Government Agencies Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services, SaaS Platforms |
| Companies Covered | Accenture, Tata Consultancy Services, Capgemini, Cognizant, Wipro, Infosys, IBM, HCL Technologies, NTT DATA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Assurance Market Shifts & Advancements
Intelligent test orchestration is displacing script-based automation, with machine learning now prioritizing test cases based on production failure probability rather than static coverage matrices.
Agentic AI systems are automating defect triage and root-cause analysis in testing pipelines. Mid-market insurers in the US and Germany deploy these tools to compress mean-time-to-resolution from days to hours. The technology is automating away tier-one quality engineering roles while elevating demand for AI governance specialists.
The EU AI Act's conformity assessment requirements for high-risk software systems mandate third-party validation before market deployment. Medical device manufacturers and credit-scoring platforms face the steepest compliance ramps. French and German notified bodies are expanding certification capacity to absorb application backlogs.
Enterprise buyers now unbundle assurance contracts from systems integrators, contracting directly with specialized testing boutiques for security validation while retaining legacy vendors for functional testing. This bifurcation is most advanced in UK and Dutch banking sectors, where procurement teams maintain separate vendor panels for cloud-native versus mainframe assurance.
Global Digital Assurance Market Segmentation
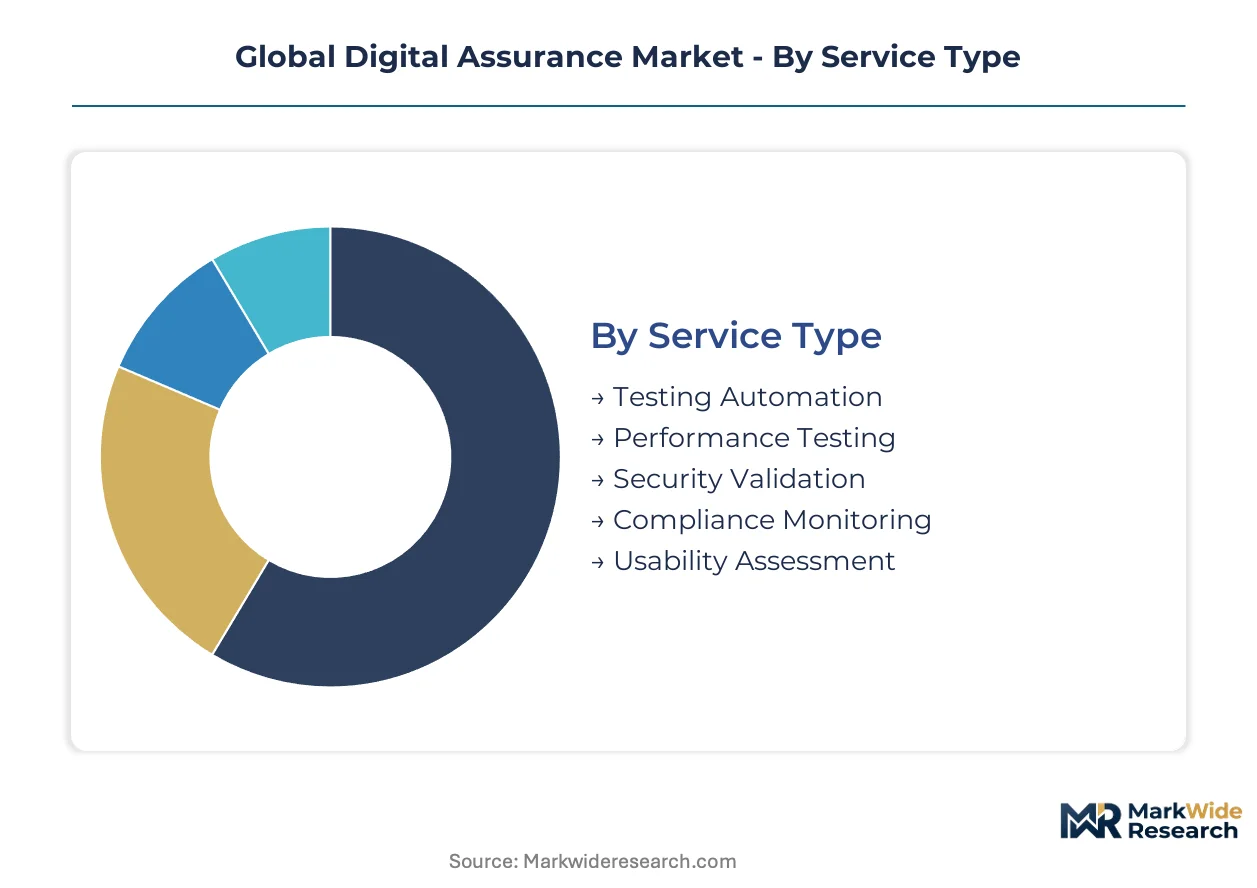
Digital assurance procurement fragments across four distinct axes that reshape vendor selection criteria and pricing architecture. Service type determines margin structure, while deployment model governs data sovereignty compliance. Technology and end-user dimensions increasingly intersect as AI-infused testing platforms target sector-specific validation requirements.
Service Type:
Technical sophistication and regulatory exposure differentiate service tiers, with automation depth and security criticality driving procurement priorities.
- Testing Automation:Script orchestration and CI/CD pipeline integration enable continuous validation for cloud-native development cycles. Financial institutions in the US and Germany deploy these tools to compress release cycles while maintaining SOX and GDPR documentation trails. Shift-left adoption pulls spending earlier in development workflows.
- Security Validation:Penetration testing, vulnerability assessment, and zero-trust architecture verification command premium pricing due to certified talent scarcity. Demand concentrates among US healthcare entities facing HIPAA breach notification mandates and EU banks under DORA operational resilience requirements.
- Performance Testing:Load simulation and latency benchmarking for high-throughput transaction systems.
- Compliance Monitoring:Continuous audit trails for ISO 27001, SOC 2, and sector-specific frameworks including FAA software integrity guidelines.
- Usability Assessment:Accessibility validation and user experience benchmarking for customer-facing applications.
Testing Automation leads on scale; Security Validation leads on momentum.
Technology:
Underlying infrastructure capabilities determine automation ceiling and integration complexity for assurance delivery models.
- AI & Machine Learning:Intelligent test case prioritization and predictive defect analytics reduce manual coverage planning. US mid-market insurers deploy ML-driven triage to compress mean-time-to-resolution from days to hours.
- Cloud Computing:Elastic test environment provisioning eliminates capital-intensive on-premises lab maintenance. EU GDPR and US SEC cloud migration mandates force revalidation of entire software estates, expanding scope to distributed architectures.
- Blockchain Verification:Distributed ledger integrity testing for smart contract deployments in financial settlement systems.
- Robotic Process Automation:Synthetic transaction generation for continuous production validation without customer data exposure.
- Big Data Analytics:Log aggregation and pattern recognition across multi-terabyte test result repositories.
Cloud Computing anchors current procurement volumes; AI & Machine Learning exhibits the steepest expansion trajectory.
End User:
Regulatory intensity and system criticality create divergent assurance requirements across vertical demand pools.
- Financial Institutions:Payment infrastructure protection and open banking API validation dominate procurement. EU DORA and US SEC cybersecurity disclosure rules mandate documented assurance trails with independent validation reporting.
- Telecommunications Providers:5G network slicing validation and subscriber data protection across distributed edge infrastructure.
- Software Developers:Embedded quality engineering for DevOps-native product companies.
- E-Commerce Platforms:Peak-load resilience testing and payment gateway security for transaction volume spikes.
- Government Agencies:FedRAMP and national security accreditation for federal system deployments.
Financial Institutions command the deepest spending; Government Agencies are gaining share fastest on cybersecurity prioritization.
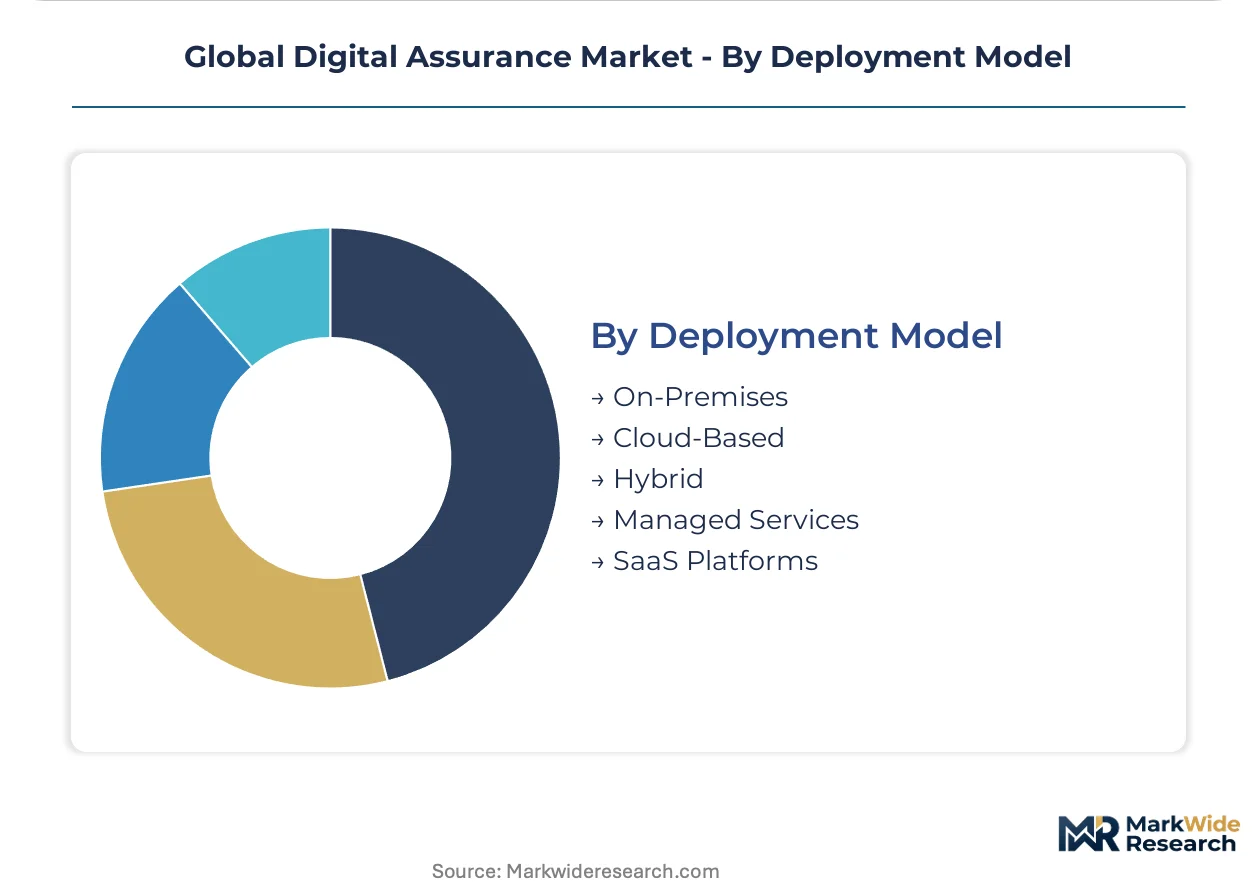
Deployment Model:
Infrastructure location and operational responsibility allocation determine compliance posture and cost structure.
- Cloud-Based:Centralized test environment management with pay-per-use consumption economics. Organizations retire legacy on-premises labs despite hybrid persistence in regulated sectors requiring data sovereignty controls in Germany, France, and Saudi Arabia.
- Hybrid:Split architecture preserving sensitive data on-premises while leveraging cloud scalability for non-critical workloads. Aviation and healthcare verticals favor this model for FAA and HIPAA boundary compliance.
- On-Premises:Captive test infrastructure for classified or air-gapped system validation.
- Managed Services:Outsourced assurance operations with SLA-backed outcome commitments.
- SaaS Platforms:Browser-accessible testing tools with minimal implementation overhead for mid-market adopters.
Cloud-Based deployment expands most quickly; Hybrid configurations retain strategic importance for regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India supplies the densest testing capacity globally, while the United States generates the highest contract values for security-critical assurance programs. Germany, the United Kingdom, and Brazil round out the five-country demand matrix with distinct regulatory drivers and industrial specializations.
United States
Financial institutions dominate procurement for payment infrastructure protection and open banking API validation. SEC cybersecurity disclosure rules and HIPAA breach notification mandates from the Department of Health and Human Services require documented assurance trails with independent validation reporting. The New York financial district and Silicon Valley tech corridors anchor delivery partnerships with Indian IT services hubs.
Germany
Automotive OEMs and industrial machinery manufacturers drive demand for embedded software validation in autonomous systems and IoT-enabled production lines. The EU AI Act's conformity assessment requirements and national data protection authority enforcement under GDPR elevate third-party certification spending. Engineering clusters in Stuttgart and Munich concentrate specialized testing boutiques alongside major systems integrators.
India
IT services hubs in Bangalore and Hyderabad supply cost-competitive testing capacity for North American and European financial services clients. BIS standards for IT service quality and RBI operational resilience guidelines shape domestic capability development. The Telangana and Karnataka state governments actively promote software testing parks to capture expanding global demand.
United Kingdom
Procurement teams in London and Edinburgh maintain separate vendor panels for cloud-native versus mainframe assurance, fragmenting contract structures. The Financial Conduct Authority's operational resilience framework and Bank of England stress-testing requirements compress delivery timelines. Fintech clusters in London's Shoreditch and Manchester's digital districts drive specialized security validation demand.
Brazil
ANVISA digital health software regulations and Central Bank open banking mandates create unmet demand for localized assurance services in Latin America's largest financial market. Domestic IT services firms compete with Indian and US providers for compliance monitoring contracts. São Paulo's financial district and Rio de Janeiro's technology parks anchor emerging delivery capabilities.
Global Digital Assurance Market Competitive Landscape
Indian IT services conglomerates anchor one tier; European consulting specialists hold differentiated positions in regulated verticals. Market structure exhibits moderate consolidation with tiered service segmentation: scale-driven quality engineering programs, AI-infused testing platforms, and price-competitive cloud-native contracts. Three strategic archetypes dominate: global systems integrators with captive delivery networks, specialized security boutiques with certified talent pools, and mid-market regional players with sector-specific compliance expertise. Competitive moves center on unbundling assurance contracts from systems integration and direct procurement of security validation by enterprise buyers.
Within the global systems integrator tier, Accenture, Tata Consultancy Services, and Wipro occupy positions representing distinct competitive vectors. Accenture exemplifies the AI-infused platform archetype with machine learning-driven test orchestration capabilities. Tata Consultancy Services anchors large-scale quality engineering programs for North American financial clients through its Bangalore and Hyderabad delivery footprint. Wipro sits within the aggressive price-competition segment for cloud-native assurance contracts, particularly in telecommunications verticals. These three entities collectively illustrate how geographic delivery concentration, technology differentiation, and pricing strategy segment competitive positioning without requiring specific claims about individual market shares or financial performance.
| Leading Market Players |
|---|
| Accenture |
| Tata Consultancy Services |
| Capgemini |
| Cognizant |
| Wipro |
| Infosys |
| IBM |
| HCL Technologies |
| NTT DATA |
| Others |
Supply & Pricing Matrix
Cloud infrastructure spot pricing indices from AWS, Azure, and GCP serve as the primary cost anchor for digital assurance delivery, cascading through vendor margin structures into three-tier pricing stratification across premium certified, standard automated, and economy manual testing tiers.
Pricing Analysis
Capacity additions in India's Bangalore and Hyderabad corridors are reshaping price floors for automated testing services, compressing margins for legacy on-premises providers while elevating AI-infused platform premiums. Pricing stratifies across ISO 27001-certified security validation, SOC 2-compliant automation suites, and uncertified functional testing tiers, with certification level and automation depth as primary differentiation drivers. Cost compression in manual testing tiers is intensifying due to robotic process automation substitution, while financial institutions exhibit lowest price sensitivity given regulatory penalty exposure.
Supply Chain Analysis
ISO 27001 and SOC 2 certification requirements gate supplier participation, filtering delivery capacity toward credentialed engineering pools in India, Poland, and Romania. Talent pipelines draw from computer science graduates, certified security architects, and DevOps practitioners, with specialized zero-trust validation skills commanding scarcity premiums. Single-source vulnerability concentrates in Bangalore-Hyderabad corridor exposure to regional infrastructure disruption. Distribution runs through direct enterprise procurement, systems integrator subcontracts, and SaaS platform self-service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Digital Assurance Market functions as a regulatory compounder where EU AI Act conformity assessments and SEC cybersecurity disclosure mandates perpetually expand mandatory validation scope.
For Market Incumbents: To counter unbundling of assurance contracts by enterprise procurement teams, anchor multi-year quality engineering partnerships with embedded AI governance specialists and backward integration into synthetic data generation capabilities for privacy-compliant testing environments. For New Entrants and Emerging Players: Cloud-native SaaS delivery routes offer the most penetrable wedge for mid-market insurers and regional banks in Brazil and Southeast Asia, targeting localized compliance monitoring for open banking and digital health regulations with freemium-tier security scanning tools. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized security boutiques holding certified zero-trust architecture talent pools and aviation or medical device sector expertise. Long-term viability hinges on algorithmic accountability service line expansion. A model refresh is warranted upon material change in EU AI Act enforcement intensity or FDA software validation pathway revisions.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Infused Platform Launch | Machine learning-driven test orchestration reduces defect detection cycles for US financial clients. |
| Specialist Firm Acquisition | Certified zero-trust boutiques extend DORA and HIPAA compliance capabilities into EU and US healthcare. |
| Geographic Expansion | Localized delivery centers in São Paulo and Mexico City capture ANVISA and Central Bank mandate demand. |
| Strategic Partnership | Hyperscaler alliances embed assurance tools into AWS and Azure marketplaces for self-service procurement. |
| Regulatory Certification Investment | EU notified body accreditation opens high-risk system validation under AI Act conformity assessments. |
Research Methodology
Bottom-up financial services and healthcare IT procurement modeling reconciled against top-down vendor capacity tracking forms the analytical core of this study. Primary interviews with CTOs, quality engineering directors, regulatory compliance officers, and procurement leads at North American and European enterprises combined with secondary validation from SEC cybersecurity disclosure filings, EU AI Act implementation guidance, RBI operational resilience circulars, and hyperscaler capex disclosures. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of testing automation spend, security validation contract values, and compliance monitoring penetration established baseline growth patterns across the projection horizon. The forecast framework models service type, deployment model, end-user vertical, and regional regulatory cluster dimensions. CAGRs derive from regression-adjusted extrapolation of vendor revenue trajectories and enterprise IT budget allocation surveys, with cloud migration mandate intensity and AI Act implementation timeline as industry-specific sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for agentic AI test automation would alter the outlook for labor-intensive quality engineering roles. Forecasts reflect assumptions about regulatory enforcement consistency and certification body capacity expansion. A model refresh is warranted upon material change in EU AI Act high-risk system classification scope or SEC cybersecurity disclosure rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
Digital Pen Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Global Hybrid Integration Platform Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Global Smart Lecture Capture System Market