
 Global Diabetic Nephropathy Market | 2026-2036
Global Diabetic Nephropathy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Nephropathy Market Analysis
Multi-source procurement of active pharmaceutical ingredients is expanding across the diabetic nephropathy supply chain. Novartis AG leverages its integrated generics division to secure cost-stable supplies of renin-angiotensin system inhibitors. Eli Lilly and Company anchors its position through sustained investment in GLP-1 receptor agonist pipelines with nephroprotective indications. Bayer AG differentiates via its radiology contrast and diagnostic imaging portfolio serving kidney function assessment protocols.
Diabetic nephropathy constitutes progressive glomerular damage resulting from prolonged hyperglycemia, characterized by albuminuria exceeding 30 mg per 24 hours and declining estimated glomerular filtration rate below 60 mL per minute per 1.73 square meters. Medications targeting the renin-angiotensin-aldosterone system dominate current prescribing patterns, though biomarker-guided early intervention represents the fastest-expanding segment as precision diagnostics enable stage-specific therapeutic selection. Dialysis equipment maintains mature revenue stability while renal replacement therapy absorbs disproportionate margin pools in advanced and end-stage treatment categories.
The FDA, EMA, and Japan's PMDA enforce divergent evidentiary standards for nephroprotective claims, compelling developers to design parallel clinical programs across jurisdictions. REACH compliance in Europe and the EU MDR's strengthened clinical investigation requirements are elevating documentation burdens for device-drug combination products in renal care. Stakeholders must monitor evolving reimbursement benchmarks for sodium-glucose cotransporter-2 inhibitors and finerenone analogs as health technology assessments increasingly condition market access on cardiovascular outcome data.
Market Dynamics
Integrated care protocols in hospital-based nephrology departments are compressing treatment timelines and forcing coordination between diagnostic imaging, pharmaceutical intervention, and renal replacement therapy planning. This structural shift elevates vendors with full-stack capabilities while marginalizing point-solution specialists.
Growth Catalysts
- Biomarker-Guided Early Intervention:Precision diagnostics enabling stage-specific therapeutic selection are expanding addressable patient populations before irreversible glomerular damage occurs. Hospital laboratories in Germany and Japan are prioritizing automated albuminuria screening platforms.
- FDA Accelerated Approval Pathways:Chronic kidney disease therapies now reach prescribers faster, compressing development-to-commercialization cycles for nephroprotective agents. Developers are filing parallel submissions with cardiovascular outcome data bundled.
- Dialysis Infrastructure Investment:Reimbursement frameworks in the United States and Japan are absorbing capital equipment costs, stabilizing demand for renal replacement devices and consumables.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient procurement for renin-angiotensin system inhibitors concentrates in a limited supplier base, exposing formulators to price volatility and qualification delays.
- Divergent Evidentiary Standards:FDA, EMA, and PMDA require non-overlapping clinical endpoints for nephroprotective claims, forcing redundant trial designs that inflate development expenditures.
- End-Stage Treatment Lock-In:Once patients initiate dialysis, switching costs and clinical inertia prevent uptake of novel disease-modifying therapies that might slow progression.
Strategic Opportunities
- Underpenetrated Early-Stage Populations:India and Brazil present substantial untreated albuminuria cohorts where diagnostic penetration remains below 15 percent. Point-of-care testing platforms can bypass centralized lab bottlenecks.
- SGLT-2 Inhibitor Reimbursement Tailwinds:Health technology assessments in Germany and the United Kingdom are expanding coverage for sodium-glucose cotransporter-2 inhibitors based on renal outcome data, opening primary care prescribing channels.
- AI-Enabled Risk Stratification:Machine learning models trained on electronic health records are converging with wearable glucose monitors to predict nephropathy progression before clinical symptoms emerge.
Industry Challenges
- Nephrologist Workforce Scarcity:Fellowship training programs in the United States and Japan are producing insufficient specialists to staff expanding dialysis center networks, forcing task delegation to nurse practitioners.
- EU MDR Documentation Burden:Device-drug combination products for renal care face elevated clinical investigation requirements under the Medical Device Regulation, delaying market entry by 18-24 months.
- Legacy EMR Integration Friction:Hospital information systems lack standardized data fields for glomerular filtration rate trending, complicating population health management initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Nephropathy Market |
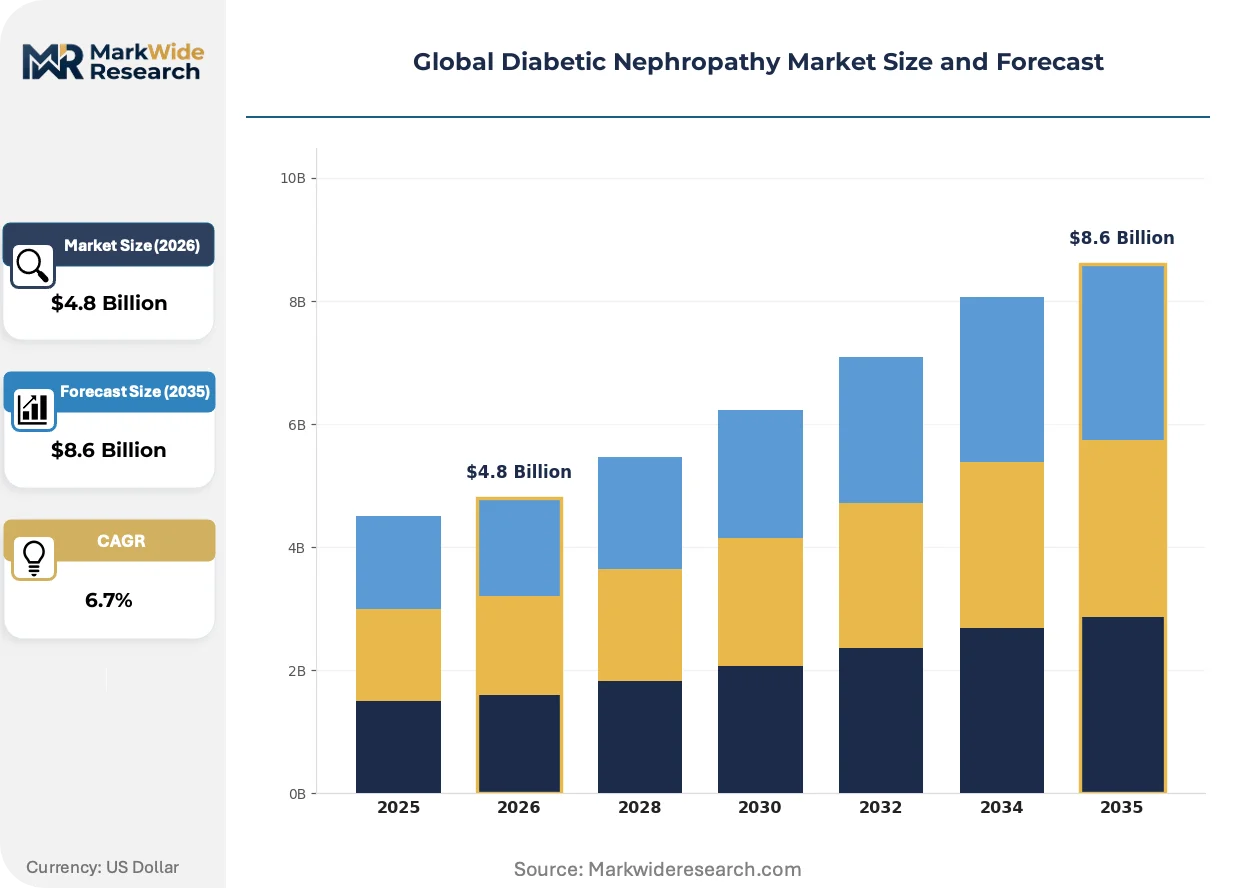
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialysis Equipment, Renal Replacement Therapy, Medications, Biomarkers Delivery Mode: Intravenous, Oral, Subcutaneous, Intrapertioneal End User: Hospitals, Home Care Settings, Ambulatory Surgical Centers, Dialysis Clinics Treatment Stage: Early Stage, Moderate Stage, Advanced Stage, End Stage |
| Companies Covered | Bayer AG, Johnson & Johnson, AstraZeneca, Boehringer Ingelheim International GmbH, Merck & Co. Inc., Novartis AG, Eli Lilly and Company, Pfizer Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Nephropathy Market Emerging Trajectories
Modular diagnostic platforms are fragmenting the traditional centralized laboratory model, enabling point-of-care albuminuria testing that compresses time-to-treatment decisions. This shift is redistributing value capture from hospital systems to ambulatory care networks.
Continuous glucose monitoring systems paired with predictive analytics engines are modularizing diabetes management into discrete, reimbursable intervention bundles. Endocrinology practices in the United States are adopting these platforms fastest, integrating nephrology referral triggers directly into workflow software. The technology is modularizing chronic disease management from episodic specialist visits into algorithm-driven care pathways.
REACH compliance and the EU MDR's strengthened post-market surveillance requirements are elevating documentation standards for contrast agents used in kidney function assessment. Manufacturers serving European markets must now maintain extended clinical follow-up databases. Device-drug combinations face the steepest compliance cost increases, favoring larger portfolios with dedicated regulatory affairs infrastructure.
Hospital procurement committees are unbundling diagnostic imaging from therapeutic decision support, creating separate vendor relationships for radiology contrast, interpretation software, and nephrology consultation. This pattern is most visible in German integrated care networks, where purchasing autonomy has devolved to regional sickness funds. The shift is compressing vendor margins while expanding opportunities for specialized software providers.
Global Diabetic Nephropathy Market Segmentation
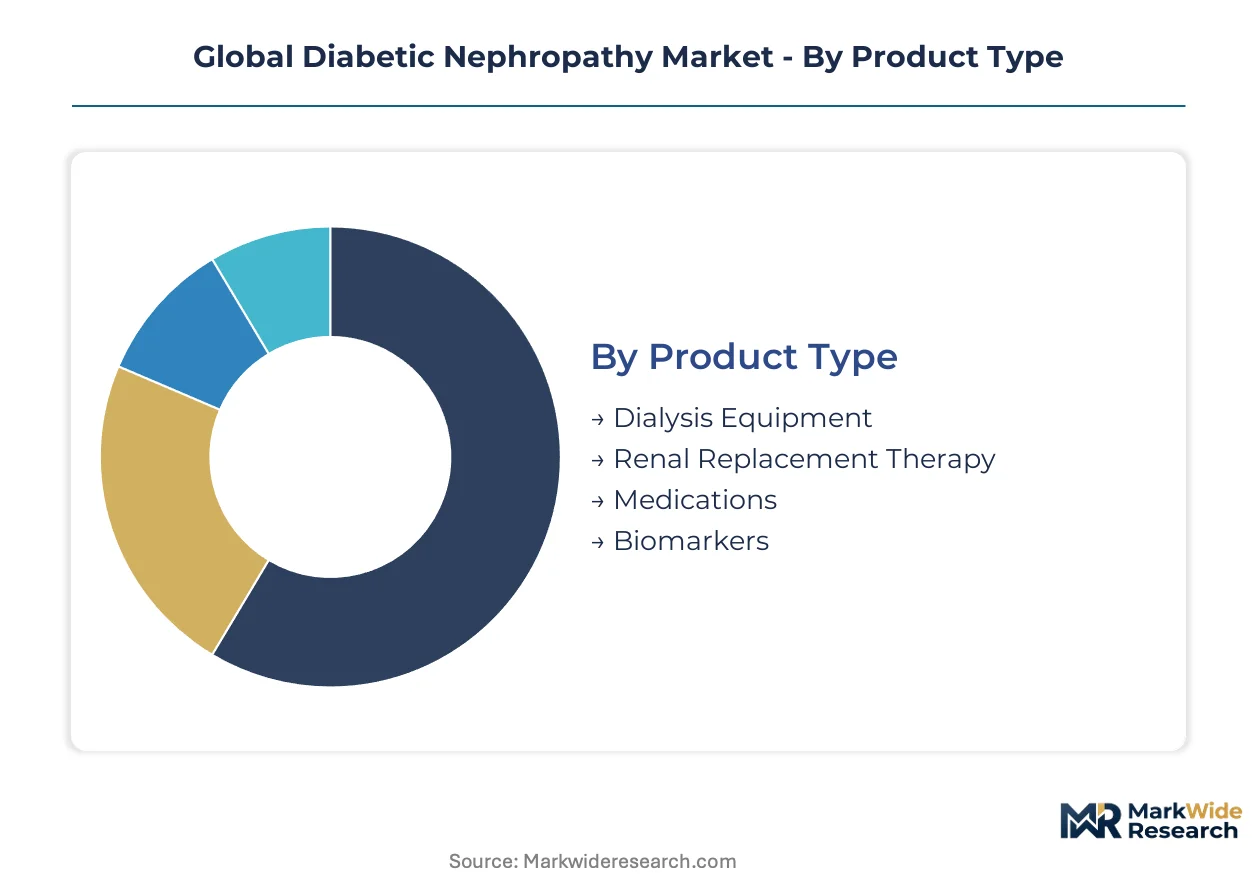
Segmentation in diabetic nephropathy reveals distinct capital intensity profiles across intervention modalities. Equipment replacement cycles diverge sharply from pharmaceutical consumption patterns, creating heterogeneous vendor strategies. Understanding these structural differences illuminates where margin pools concentrate and where volume expansion offers sustainable returns.
Product Type:
Replacement cycles for capital equipment compress as integrated care protocols demand interoperable platforms, while consumable-driven segments benefit from recurring revenue streams.
- Dialysis Equipment:Hemodialysis and peritoneal dialysis machines incorporate real-time monitoring modules that hospitals refresh every 5-7 years. German integrated care networks are bundling equipment procurement with long-term service contracts to lock in operational expenditure predictability.
- Medications:Renin-angiotensin system inhibitors and emerging SGLT-2 formulations constitute chronic consumption with monthly refill patterns. United States pharmacy benefit managers are tightening prior authorization requirements for nephroprotective agents, forcing manufacturers to demonstrate cardiovascular outcome equivalence.
- Renal Replacement Therapy:Dialysis consumables and filtration membranes generate recurring demand tied to patient session frequency.
- Biomarkers:Albuminuria and eGFR testing platforms enable stage-specific therapeutic selection.
Medications sits at the top of the volume ranking, with Biomarkers climbing the fastest.
Delivery Mode:
Cost tier differentiation separates acute inpatient administration from ambulatory self-management, with reimbursement benchmarks determining viable delivery economics.
- Oral:Small-molecule formulations including ACE inhibitors and finerenone analogs dominate first-line prescribing for early-stage patients. Japan's PMDA has streamlined bioequivalence requirements for oral generics, accelerating price competition in maintenance therapy categories.
- Subcutaneous:GLP-1 receptor agonist formulations with nephroprotective indications require patient training for self-administration. United States endocrinology practices are embedding injection training into bundled diabetes management protocols.
- Intravenous:Iron replacement and erythropoiesis-stimulating agents for dialysis patients.
- Intraperitoneal:Dialysis solutions delivered directly to the peritoneal cavity.
Oral delivery captures the largest patient population, while Subcutaneous administration is expanding most quickly through primary care channel development.
End User:
Customer type fragmentation reflects divergent procurement authority, with hospital systems consolidating vendor relationships while ambulatory settings prioritize point-of-care flexibility.
- Hospitals:Nephrology departments command capital budgets for imaging equipment and dialysis infrastructure, with procurement committees unbundling diagnostic from therapeutic vendor relationships. German sickness funds are devolving purchasing autonomy to regional integrated care networks.
- Dialysis Clinics:Specialized operators concentrate patient volume for renal replacement therapy, achieving economies in consumable procurement. United States freestanding dialysis centers are consolidating under national chains to negotiate favorable reimbursement rates.
- Home Care Settings:Peritoneal dialysis and self-monitoring devices for stable patients.
- Ambulatory Surgical Centers:Biopsy and vascular access procedures.
Hospitals retain the deepest capital commitment, though Dialysis Clinics are gaining share fastest through vertical integration of patient management.
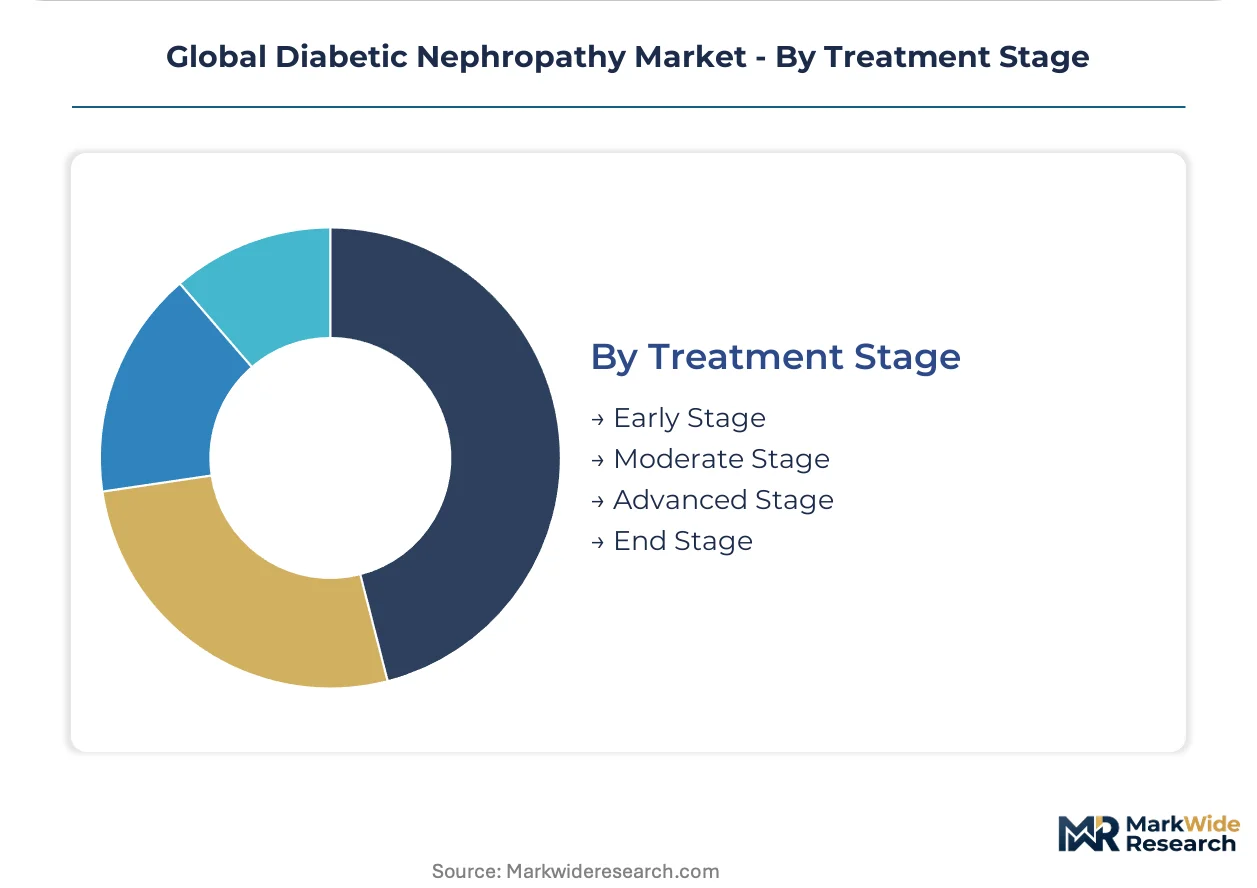
Treatment Stage:
Application urgency escalates from asymptomatic monitoring to life-sustaining intervention, with margin structure inverting as clinical stakes rise.
- Early Stage:Albuminuria screening and RAAS inhibitor initiation target glomerular preservation before irreversible damage. Automated screening platforms in Japanese hospital laboratories are compressing time-to-diagnosis intervals.
- End Stage:Dialysis dependency and transplant evaluation absorb disproportionate expenditure per patient, with renal replacement therapy consuming the majority of lifetime nephropathy costs. United States Medicare reimbursement frameworks stabilize demand for dialysis services regardless of modality innovation.
- Moderate Stage:Intensified monitoring and combination pharmacotherapy.
- Advanced Stage:Preparation for renal replacement with vascular access placement.
End Stage commands the highest per-patient expenditure, with Early Stage intervention showing the steepest expansion trajectory as precision diagnostics enable population-scale screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where nephroprotective drug development concentrates, as divergent FDA, EMA, and PMDA evidentiary standards create compliance cost gaps that favor multi-jurisdictional trial designs in specific territories. Developers now site clinical operations where accelerated approval pathways and stable reimbursement frameworks overlap.
United States
Medicare reimbursement frameworks stabilize demand for dialysis services and renal replacement therapies regardless of modality innovation. The FDA's accelerated approval pathways for chronic kidney disease therapies compress development-to-commercialization cycles. Hospital procurement committees in the Northeast Corridor are unbundling diagnostic imaging from therapeutic decision support, creating separate vendor relationships.
Germany
Regional sickness funds are devolving purchasing autonomy to integrated care networks, compressing vendor margins while expanding opportunities for specialized software providers. REACH compliance and the EU MDR's strengthened clinical investigation requirements elevate documentation burdens for device-drug combination products. Bavarian hospital laboratories are prioritizing automated albuminuria screening platforms for early-stage intervention.
Japan
PMDA has streamlined bioequivalence requirements for oral generics, accelerating price competition in maintenance therapy categories. METI frameworks support dialysis infrastructure investment that absorbs capital equipment costs. Hospital-based nephrology departments in the Kanto region are scaling adoption of integrated care protocols that coordinate diagnostic imaging with pharmaceutical intervention.
India
Untreated albuminuria cohorts present substantial underpenetrated populations where diagnostic penetration remains below 15 percent. CDSCO regulatory pathways for nephroprotective agents are converging with WHO prequalification standards. Point-of-care testing platforms in Maharashtra and Gujarat are bypassing centralized laboratory bottlenecks to compress time-to-treatment decisions.
Brazil
ANVISA enforcement of nephroprotective labeling standards is elevating documentation requirements for imported renal care products. Public health system procurement for dialysis consumables concentrates in São Paulo and Minas Gerais industrial corridors. Freestanding dialysis centers in Rio de Janeiro are consolidating under regional chains to negotiate favorable reimbursement rates.
Global Diabetic Nephropathy Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biomarker-guided diagnostics and AI-enabled risk stratification. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with full-stack capabilities, specialized diagnostics firms with precision platforms, and regional equipment suppliers serving dialysis infrastructure. Consolidation pressures favor players with dedicated regulatory affairs infrastructure capable of navigating divergent FDA, EMA, and PMDA standards. Dominant competitive moves include portfolio diversification into device-drug combinations and geographic expansion through regional integrated care network partnerships.
Among Swiss and German pharmaceutical conglomerates, Novartis AG and Bayer AG exemplify the integrated archetype with generics divisions and diagnostic imaging portfolios respectively. Eli Lilly and Company represents the sustained-investment archetype in GLP-1 receptor agonist pipelines with nephroprotective indications. These three occupy positions where multi-source API procurement and parallel clinical program design across jurisdictions anchor competitive durability.
| Leading Market Players |
|---|
| Bayer AG |
| Johnson & Johnson |
| AstraZeneca |
| Boehringer Ingelheim International GmbH |
| Merck & Co. Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Pfizer Inc. |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FDA-approved nephroprotective agents and commodity renin-angiotensin system generics manifests in both pricing power and sourcing complexity. Premium-tier formulations command reimbursement advantages through cardiovascular outcome data while commodity API procurement concentrates in cost-optimized manufacturing corridors.
Pricing Analysis
Distributor margin layers for SGLT-2 inhibitors and finerenone analogs compress as pharmacy benefit managers tighten prior authorization requirements. Three-tier pricing structure across premium, standard, and economy levels reflects cardiovascular outcome certification status, volume scale commitments, and bundled service offerings. Pricing pressure stems from Japanese PMDA bioequivalence streamlining accelerating generic entry in maintenance therapy categories. Dialysis clinics demonstrate highest price sensitivity due to Medicare reimbursement caps, while hospital nephrology departments absorb premium diagnostics through capital budgets.
Supply Chain Analysis
Dual-sourcing requirements for active pharmaceutical ingredients now extend to renin-angiotensin system inhibitor precursors as formulators mitigate qualification delays. API manufacturing concentrates in India, China, and Switzerland, with filtration membrane production anchored in Germany and Japan. Raw material dependencies include angiotensin-converting enzyme inhibitor intermediates, GLP-1 receptor agonist peptides, and diagnostic contrast agent precursors. Single-source vulnerability persists for specialized biomarker reagents used in automated albuminuria screening platforms. Distribution runs through regional integrated care networks in Germany and national dialysis chains in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetic nephropathy market represents a late-cycle quality story as demand shifts decisively toward biomarker-guided early intervention requiring precision diagnostic certification.
For Market Incumbents: Anchor competitive durability through backward integration into API manufacturing and parallel clinical program design across FDA, EMA, and PMDA jurisdictions. Novartis AG's generics division model demonstrates cost-stable supply security against emerging entrant price pressure. Capacity addition in Indian API corridors and investment in AI-enabled risk stratification platforms provide defensive moats against diagnostic modularization trends. For New Entrants and Emerging Players: Begin with point-of-care albuminuria testing platforms targeting Maharashtra and Gujarat in India where diagnostic penetration remains below fifteen percent. Underpenetrated early-stage populations in Brazil present comparable whitespace for automated screening deployment. Licensing partnerships with established dialysis equipment manufacturers offer fastest channel access without capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR documentation burdens exceed eighteen-month compliance timelines for device-drug combination products. Long-term viability centers on acquisition targets with dedicated regulatory affairs infrastructure spanning REACH compliance and FDA accelerated approval pathways. The signal to watch is health technology assessment expansion for SGLT-2 inhibitors in Germany and the United Kingdom conditioning primary care reimbursement on renal outcome data.| Strategic Initiative | Industry Significance |
|---|---|
| Parallel Regulatory Submission Design | FDA, EMA, and PMDA alignment compresses development-to-commercialization cycles for nephroprotective agents. |
| Point-of-Care Diagnostic Platform Launch | Automated albuminuria screening bypasses centralized laboratory bottlenecks in underpenetrated Indian and Brazilian markets. |
| API Manufacturing Scale-Up | Multi-source procurement of renin-angiotensin system inhibitor precursors insulates formulators from price volatility. |
| Integrated Care Network Partnership | German sickness fund devolution creates vendor relationships unbundling diagnostic imaging from therapeutic decision support. |
| AI-Enabled Risk Stratification Development | Machine learning models trained on electronic health records converge with wearable glucose monitors for predictive nephropathy detection. |
Methodological Framework
Direct dialogue with nephrology department heads, formulary directors at United States pharmacy benefit managers, regulatory affairs leads at pharmaceutical conglomerates, and procurement managers at German integrated care networks grounded qualitative findings. Secondary validation drew from FDA accelerated approval filings, EMA nephroprotective indication submissions, ClinicalTrials.gov endpoint designs, and CMS Medicare dialysis reimbursement benchmarks. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Bottom-up volume projections tracked treatment stage progression from early albuminuria screening through end-stage dialysis dependency, cross-referenced with administration route preferences across oral, subcutaneous, and intravenous delivery modes. Top-down pharmaceutical spending analysis incorporated health technology assessment decisions in Germany and the United Kingdom. CAGRs were derived from fitted growth curves across the analysis window, with inputs including PMDA generic streamlining timelines, METI dialysis infrastructure investment frameworks, and CDSCO regulatory convergence with WHO prequalification standards.
Caveats apply where FDA evidentiary standard shifts or EMA REACH compliance cost escalations could materially shift the outlook. Forecasts assume stable Medicare reimbursement frameworks for renal replacement therapy and continued PMDA bioequivalence streamlining for oral generics. Deviation in health technology assessment conditioning of SGLT-2 inhibitor coverage on cardiovascular outcome data would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Renal Artery Embolization Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
US Continuous Renal Replacement Therapy Market