
 CRISPR Gene Detection and Diagnostic Market | 2026-2036
CRISPR Gene Detection and Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
CRISPR Gene Detection and Diagnostic Market Insights
Next-generation CRISPR-Cas12 detection chemistry is reconfiguring how point-of-care diagnostic assays achieve single-molecule sensitivity without thermocycling infrastructure. Thermo Fisher Scientific leverages its global distribution network to sustain instrument placement across academic and clinical labs. Mammoth Biosciences differentiates through miniaturized Cas proteins optimized for field-deployable diagnostics. Sherlock Biosciences anchors its platform on SHERLOCK and DETECTR nucleic acid detection technologies for pathogen identification.
CRISPR gene detection and diagnostic systems employ RNA-guided nucleases to recognize specific DNA or RNA sequences, generating detectable signals through collateral cleavage of reporter molecules with attomolar sensitivity; these platforms serve clinical, agricultural, and research applications requiring rapid nucleic acid identification. Kits and reagents capture the recurring revenue stream as consumable-intensive workflows dominate laboratory operations. CRISPR-Cas12 systems represent the fastest-growing technology segment due to trans-cleavage activity enabling multiplexed detection formats. Diagnostic laboratories constitute the primary end-user channel where throughput requirements and regulatory compliance standards concentrate purchasing decisions.
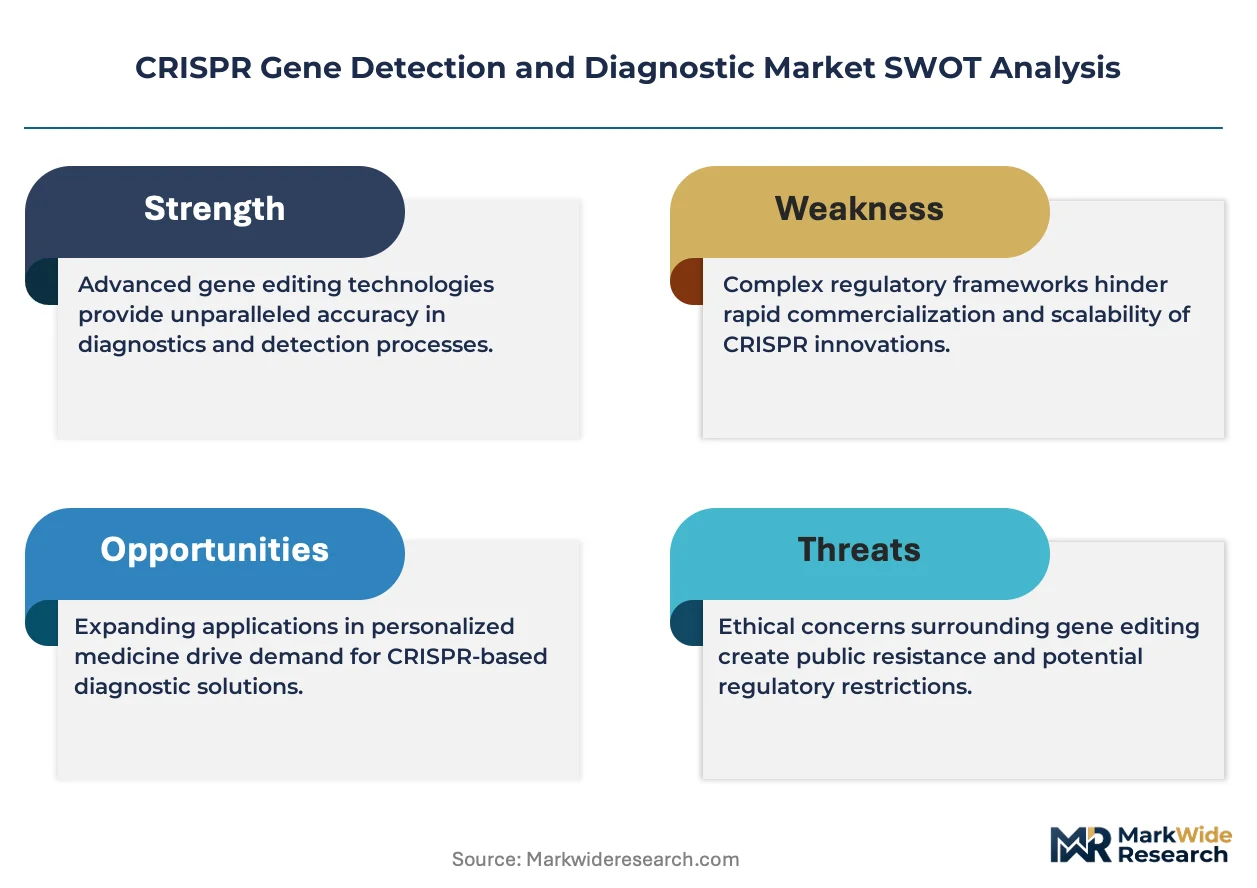
FDA oversees premarket review of CRISPR-based in vitro diagnostics under its Center for Devices and Radiological Health, while EMA's In Vitro Diagnostic Regulation establishes performance benchmarks for European market entry. ISO 13485 quality management standards govern manufacturing processes for diagnostic kit producers seeking multi-jurisdictional commercialization. Stakeholders must monitor evolving predicate device pathways and companion diagnostic co-development frameworks as regulatory science adapts to programmable nuclease detection modalities.
Market Dynamics
CRISPR diagnostic platforms face a structural inflection where thermocycling elimination collides with FDA's predicate device pathway evolution, forcing developers to recalibrate validation strategies against both technical performance benchmarks and shifting regulatory science expectations.
Growth Catalysts
- Cas12 trans-cleavage chemistry:Collateral cleavage activity enables multiplexed detection formats that collapse assay complexity. Clinical diagnostic laboratories in the United States are expanding infectious disease screening programs around this capability.
- EMA In Vitro Diagnostic Regulation:Performance benchmarking frameworks establish transparent commercialization criteria across European markets. Manufacturers gain predictable pathways for CE marking and market entry.
- Point-of-care infrastructure gaps:Field-deployable diagnostics address thermocycler scarcity in resource-limited settings. Miniaturized Cas protein architectures unlock decentralized nucleic acid identification.
Market Restraints
- Guide RNA synthesis cost volatility:Oligonucleotide manufacturing concentrates among specialized suppliers. Input price swings compress kit margin structures for mid-tier producers.
- ISO 13485 certification timelines:Quality management system implementation extends product launch schedules. Multi-jurisdictional commercialization requires sequential audit cycles.
- Fluorescence reader hardware dependency:Signal detection requires capital-intensive instrumentation. Point-of-care deployment faces equipment cost barriers against lateral flow substitutes.
Strategic Opportunities
- Agricultural pathogen surveillance:Crop and livestock screening programs represent underpenetrated demand. Food safety regulators in Brazil and Australia are piloting CRISPR-based field diagnostics.
- Companion diagnostic co-development:Pharmaceutical pipelines create paired assay demand. FDA's evolving guidance on gene editing diagnostics shapes product development timelines for oncology applications.
- Cloud-connected assay interpretation:Machine learning integration with smartphone-based readouts collapses expertise requirements. Community health workers in India access centralized algorithmic support.
Industry Challenges
- Bioinformatics talent scarcity:Guide RNA design and off-target prediction require specialized computational biology expertise. Academic medical centers compete with commercial developers for trained personnel.
- Legacy LIMS integration friction:CRISPR workflow data formats conflict with established laboratory information management systems. Hospital networks face middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CRISPR Gene Detection and Diagnostic Market |
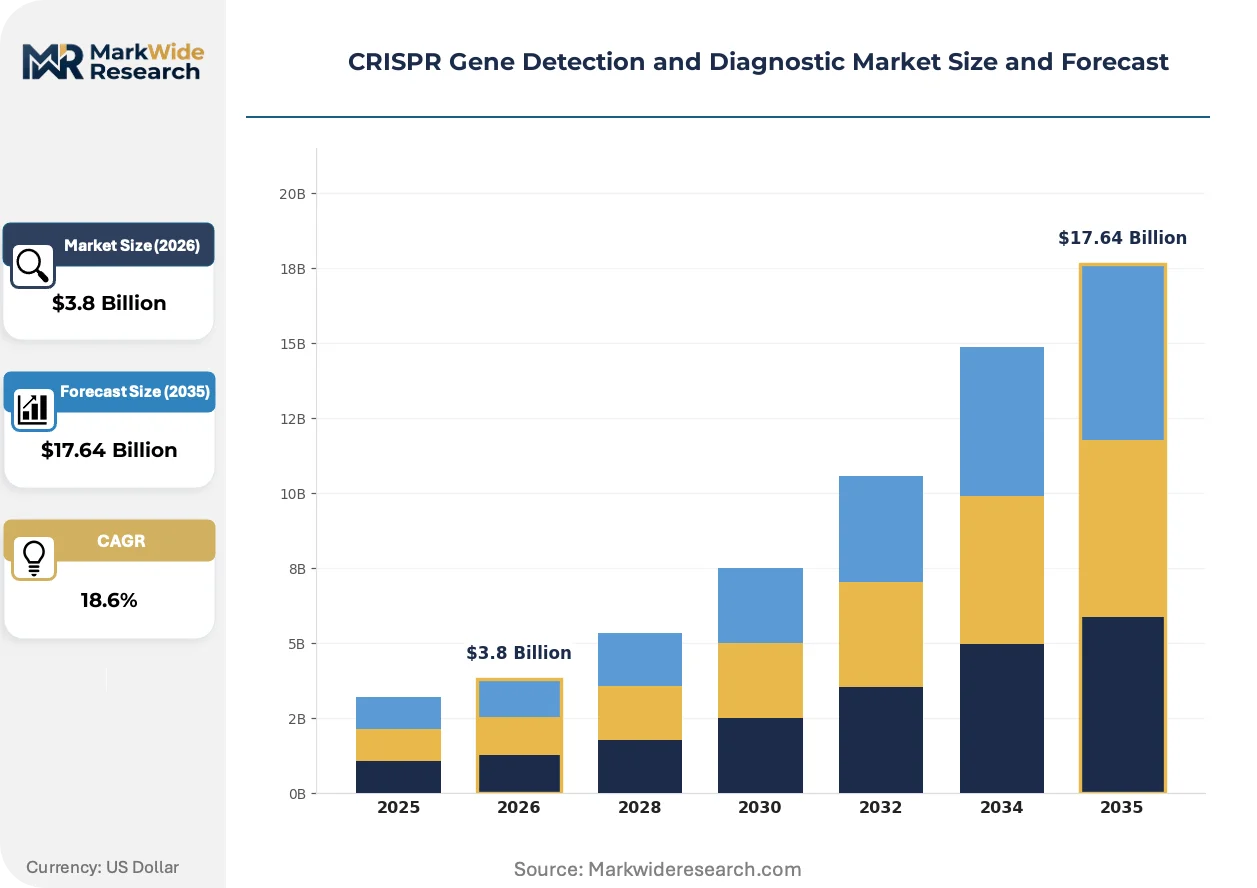
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CRISPR-Cas9, CRISPR-Cas12, CRISPR-based Sensors, PCR-based Systems Application: Genetic Testing, Pathogen Detection, Cancer Diagnostics, Agricultural Biotechnology End User: Research Institutions, Diagnostic Laboratories, Pharmaceutical Companies, Contract Research Organizations Product Type: Kits, Reagents, Instruments, Software |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Agilent Technologies, Inc., Horizon Discovery Group, Integrated DNA Technologies, Inc., Synthego Corporation, Mammoth Biosciences, Inc., Sherlock Biosciences, Inc., Caribou Biosciences, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CRISPR Gene Detection and Diagnostic Market Trends and Innovations
Programmable nuclease detection modalities are compressing the traditional central lab-to-clinic assay migration timeline, with collateral cleavage architectures and smartphone readout systems collapsing infrastructure requirements faster than regulatory frameworks can adapt.
Next-generation CRISPR-Cas12 detection chemistry is digitizing how point-of-care diagnostic assays achieve single-molecule sensitivity without thermocycling infrastructure. Clinical diagnostic laboratories in academic medical centers are adopting these platforms for infectious disease screening within compressed validation windows. The technology is digitizing signal generation pathways, replacing fluorescence polarization with smartphone camera-based quantification that collapses capital requirements.
FDA's evolving guidance on gene editing diagnostics is reshaping predicate device pathway expectations for CRISPR-based in vitro diagnostics. Developers face expanded analytical validation requirements as the Center for Devices and Radiological Health adapts review standards to programmable nuclease modalities. Early-stage companies are responding by front-loading clinical performance studies to preempt regulatory queries.
Diagnostic procurement patterns among hospital networks are fragmenting as point-of-care units gain independent purchasing authority. Central laboratory contracts no longer capture all molecular testing demand; emergency departments and outpatient clinics acquire CRISPR-based platforms through separate capital budgets. This decentralization is most visible in United States academic medical centers, where biotech cluster proximity accelerates pilot program adoption.
CRISPR Gene Detection and Diagnostic Market Segmentation
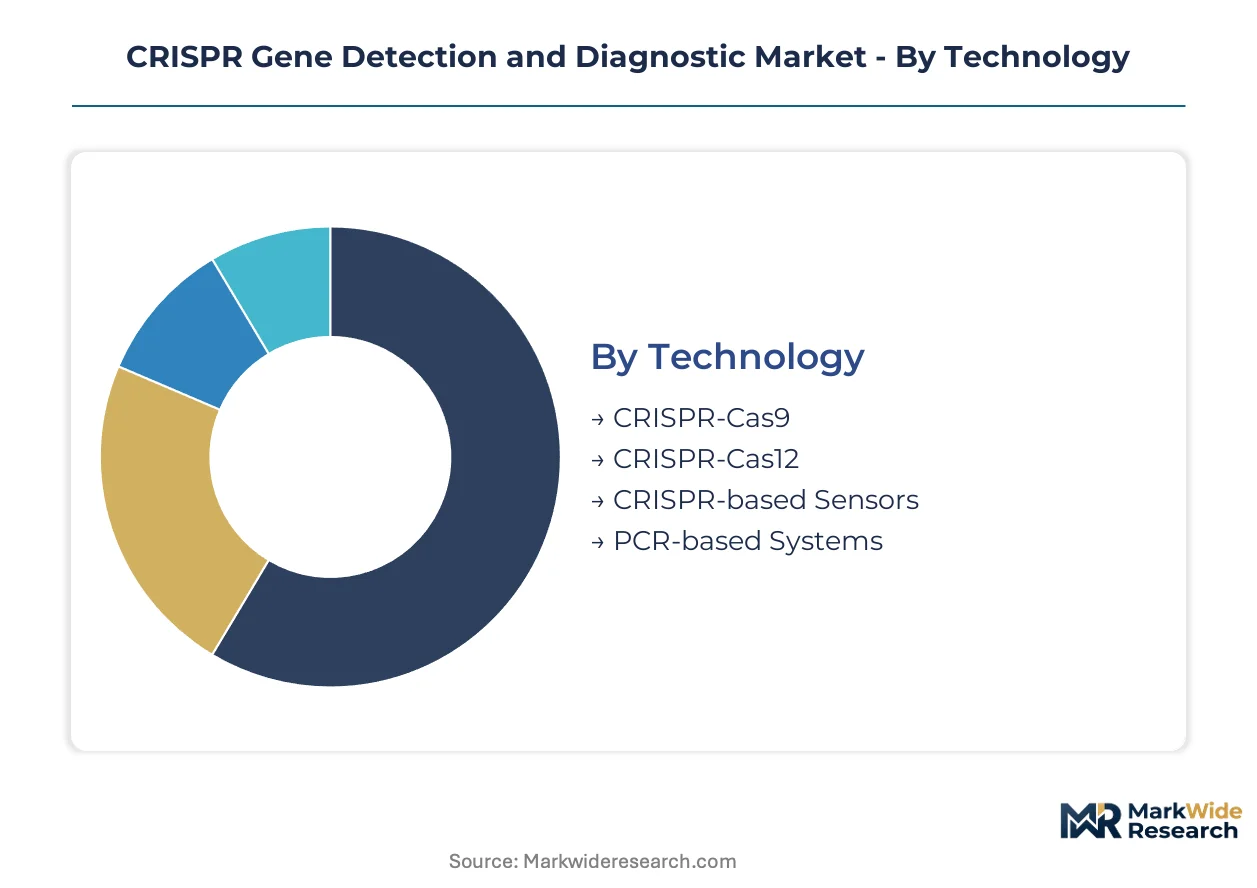
CRISPR diagnostic platforms fragment across four intersecting dimensions that determine procurement patterns and margin structures. Technology choices dictate sensitivity thresholds and infrastructure requirements, while end-user concentration shapes regulatory compliance burdens and volume economics.
Technology:
Mature thermocycling-dependent methods coexist with emerging isothermal chemistries that eliminate capital-intensive instrumentation.
- CRISPR-Cas12:Trans-cleavage activity generates collateral signal amplification without thermocycling, enabling multiplexed detection formats. Academic medical centers in the United States prioritize this chemistry for infectious disease screening programs where infrastructure constraints limit PCR deployment.
- CRISPR-Cas9:Established editing platform repurposed for diagnostic applications through guide RNA-directed binding assays. Research institutions leverage existing Cas9 expertise and reagent supply chains for proof-of-concept studies in genetic testing workflows.
- CRISPR-based Sensors:Electrochemical and optical transduction interfaces convert nucleic acid recognition into quantifiable signals.
- PCR-based Systems:Gold-standard amplification integrated with CRISPR readout for enhanced specificity in clinical validation studies.
CRISPR-Cas12 handles the majority of new platform throughput; CRISPR-based Sensors are climbing the fastest on share as point-of-care applications expand.
Application:
Clinical validation requirements create cost tier stratification between regulated diagnostic use and research-stage screening.
- Pathogen Detection:Infectious disease screening commands the largest installed base, with FDA premarket review pathways well-established for respiratory and sexually transmitted infection panels. Diagnostic laboratories in academic medical centers drive recurring reagent demand through high-throughput screening programs.
- Genetic Testing:Carrier screening and pharmacogenomic applications require analytical validation against reference standards. Pharmaceutical companies sponsor companion diagnostic co-development to support precision medicine pipelines.
- Cancer Diagnostics:Liquid biopsy applications for circulating tumor DNA detection face extended validation timelines.
- Agricultural Biotechnology:Crop and livestock pathogen surveillance operates under lighter regulatory burden with faster field deployment cycles.
Pathogen Detection captures the dominant share of validated assay volume; Agricultural Biotechnology is expanding most quickly as food safety regulators pilot decentralized testing.
End User:
Customer type determines purchasing authority structure and budget cycle alignment.
- Diagnostic Laboratories:Centralized molecular testing facilities with ISO 13485-compliant quality systems and predicate device familiarity. Hospital networks in the United States concentrate purchasing decisions through group purchasing organizations.
- Research Institutions:Academic medical centers and university labs with flexible capital budgets and proximity to biotech clusters. Early technology adoption occurs here before clinical translation.
- Pharmaceutical Companies:Companion diagnostic development partnerships and internal biomarker discovery programs.
- Contract Research Organizations:Outsourced validation services for regulatory submission support.
Diagnostic Laboratories manage the bulk of commercial assay throughput; Research Institutions are gaining share fastest as technology transfer accelerates.
Product Type:
Supply concentration varies between consumable-intensive recurring revenue and capital equipment placement cycles.
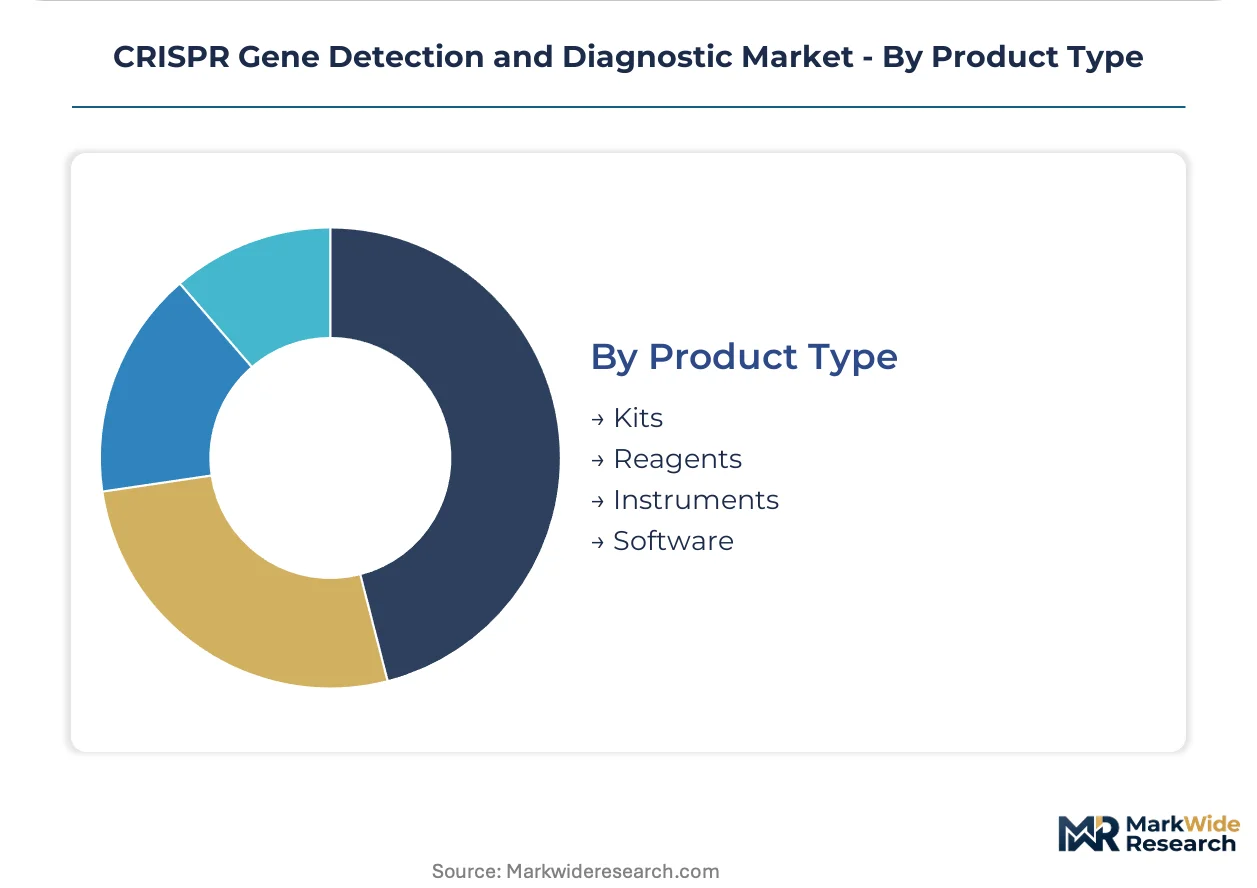
- Kits:Pre-formulated reagent sets with guide RNA and reporter chemistry optimized for specific target panels. Recurring revenue stream dominates laboratory consumable budgets with highest margin profile.
- Reagents:Bulk oligonucleotides, Cas proteins, and detection substrates purchased by high-volume users. Guide RNA synthesis cost volatility compresses margin structures for specialized suppliers.
- Instruments:Fluorescence readers and microfluidic cartridges requiring capital expenditure approval.
- Software:Bioinformatics platforms for guide RNA design and assay interpretation.
Kits generate the majority of recurring revenue; Software is climbing the fastest on share as cloud-connected assay interpretation reduces expertise barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic procurement concentrates in academic medical centers with proximity to biotech clusters, while regulatory pathway clarity determines commercialization velocity. FDA premarket review timelines shape United States platform adoption, and EMA performance benchmarking accelerates European market entry.
United States
FDA's Center for Devices and Radiological Health oversees predicate device pathway evolution for CRISPR-based in vitro diagnostics. The agency's expanding analytical validation requirements force developers to front-load clinical performance studies. Greater Boston and San Francisco Bay Area biotech clusters anchor early pilot program adoption among academic medical centers.
Germany
ISO 13485 quality management certification timelines extend product launch schedules for kit manufacturers seeking multi-jurisdictional commercialization. EMA In Vitro Diagnostic Regulation establishes transparent CE marking criteria across European markets. Munich and Heidelberg research institutions drive recurring reagent demand through high-throughput screening programs.
China
NMPA medical device registration pathways adapt review standards to programmable nuclease detection modalities. The country's national pharmaceutical regulator accelerates approval timelines for infectious disease screening platforms. Yangtze River Delta diagnostic laboratories in Shanghai and Suzhou concentrate point-of-care infrastructure deployment.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated assessment of novel CRISPR-Cas12 detection chemistries. The national medicines regulator maintains alignment with ISO standards for quality system implementation. London and Cambridge academic medical centers prioritize miniaturized Cas protein architectures for decentralized testing.
India
CDSCO medical device rules govern import and manufacture of molecular diagnostic kits with escalating quality system requirements. The national pharmaceutical regulator pilots streamlined pathways for point-of-care platforms. Bangalore and Hyderabad biotech clusters attract cloud-connected assay interpretation development for community health worker deployment.
CRISPR Gene Detection and Diagnostic Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument placement and consumable-intensive workflows. Thermo Fisher Scientific leverages global distribution networks to sustain academic and clinical lab penetration, while miniaturized Cas protein developers target field-deployable diagnostics. Three archetypes dominate: diversified life science conglomerates with platform breadth, CRISPR-native specialists with biochemical innovation, and research-tool incumbents with reagent supply chains. Competitive moves center on strategic partnerships for regulatory co-development and technology licensing for predicate device pathway acceleration.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions defined by global distribution scale and ISO 13485-compliant manufacturing breadth. Within the CRISPR-native specialist tier, Mammoth Biosciences, Inc. and Sherlock Biosciences, Inc. exemplify platform-specific innovation anchored on collateral cleavage detection architectures. Research-tool incumbents including Agilent Technologies, Inc. and Integrated DNA Technologies, Inc. represent reagent supply chain control and oligonucleotide manufacturing concentration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Agilent Technologies, Inc. |
| Horizon Discovery Group |
| Integrated DNA Technologies, Inc. |
| Synthego Corporation |
| Mammoth Biosciences, Inc. |
| Sherlock Biosciences, Inc. |
| Caribou Biosciences, Inc. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in guide RNA synthesis infrastructure across specialized oligonucleotide suppliers drives both input cost volatility and kit margin compression for mid-tier diagnostic producers, forcing procurement teams toward long-term offtake contracts or backward integration into captive manufacturing.
Pricing Analysis
Cost-plus contracts with phosphoramidite indexation dominate bulk reagent purchasing between kit manufacturers and oligonucleotide suppliers. Three-tier pricing structure across premium-certified, standard-research-grade, and economy-bulk tiers separates FDA-validated assay panels from exploratory screening applications. Pricing pressure stems from fluorescence reader hardware dependency that elevates capital barriers against lateral flow substitutes. Academic medical centers exhibit highest price sensitivity due to grant-funded budget cycles, while pharmaceutical companion diagnostic partnerships absorb premium tiering with minimal negotiation.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for Cas protein and guide RNA manufacturers. Manufacturing concentrates in United States, Germany, and China, with specialized oligonucleotide synthesis anchoring in San Diego and Heidelberg clusters. Raw material dependencies span phosphoramidite chemistries, recombinant Cas12 proteins, and fluorescence reporter substrates. Single-source vulnerability in guide RNA design software creates chokepoint exposure. Distribution runs through ISO 13485-certified kit assemblers to diagnostic laboratories and research institutions via group purchasing organizations and direct institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent and software attach rates are expanding faster than instrument hardware placements as laboratories prioritize consumable-intensive workflows and cloud-connected assay interpretation over capital equipment acquisition.
For Market Incumbents: Entrench predicate device pathway expertise through expanded FDA premarket submission consulting services, locking in diagnostic laboratory loyalty. Deepen backward integration into guide RNA manufacturing to neutralize oligonucleotide supplier concentration and stabilize input costs. Defend against CRISPR-native specialists by accelerating miniaturized Cas protein R&D timelines.
For New Entrants and Emerging Players: Pursue agricultural pathogen surveillance in Brazil and Australia where regulatory burden remains lighter and field deployment cycles compress. Target food safety regulator pilot programs as the most penetrable entry channel. Lead with smartphone-based readout systems that collapse fluorescence reader capital requirements for resource-limited settings.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-connected assay interpretation platforms as software margins displace hardware-dependent returns. Five-to-ten year viability favors CRISPR-native specialists with collateral cleavage IP estates over diversified life science conglomerates with legacy PCR entrenchment. Signal to monitor: FDA guidance publication velocity on programmable nuclease predicate devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Pharmaceutical pipelines create paired assay demand under FDA evolving guidance frameworks. |
| CE Marking Pathway Acceleration | EMA In Vitro Diagnostic Regulation establishes transparent performance benchmarking for European entry. |
| Cloud-Connected Assay Interpretation | Machine learning integration with smartphone readouts collapses expertise requirements for decentralized deployment. |
| Backward Integration into Guide RNA | In-house phosphoramidite chemistry neutralizes supplier concentration and stabilizes kit margin structures. |
| Hospital System Partnership | Academic medical center pilot programs anchor early adoption before clinical translation scaling. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA CE marking databases, and ISO 13485 audit records. Primary interviews engaged diagnostic laboratory directors, CRISPR platform R&D leads, regulatory affairs specialists at IVD manufacturers, and hospital procurement committee members. Secondary validation drew from ClinicalTrials.gov companion diagnostic entries, CMS Medicare reimbursement schedules, and GPO contract disclosure databases. Bottom-up kit volume estimates triangulated against top-down market sizing across technology and application segments.
Forecast inputs span CRISPR-Cas12 trans-cleavage chemistry adoption curves, point-of-care infrastructure deployment rates, and predicate device pathway timeline assumptions across the analysis window. Segmentation modeling incorporates technology choice, application validation tier, end-user purchasing authority structure, and product type margin profile. CAGRs derive from logistic diffusion curves fitted to early-adopter penetration patterns in academic medical centers. Industry-specific inputs include FDA guidance publication schedules and EMA In Vitro Diagnostic Regulation implementation phase transitions.
Sensitivities concentrate around FDA predicate device pathway evolution, guide RNA synthesis cost trajectories, and fluorescence reader hardware substitution by lateral flow formats. Forecasts embed assumptions regarding regulatory science adaptation rates and thermocycling elimination timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
Microbial Gene Editing Services Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
UK Gene Editing Market