
 China Specialty Enzymes Market | 2026-2036
China Specialty Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
China Specialty Enzymes Market Insights
Pharmaceutical bioprocessing is decoupling from traditional chemical catalysts as domestic drugmakers scale therapeutic enzyme adoption. Novozymes leverages its Danish fermentation expertise to supply high-purity proteases for injectable biologics manufacturing in China. BASF anchors its position through backward integration into genetically modified strain development, while Advanced Enzyme Technologies competes on cost-optimized amylase variants for regional generics producers.
China specialty enzymes comprise biocatalysts—typically proteins with molecular weights between 10,000 and 150,000 Daltons—engineered through submerged fermentation or solid-state culture to accelerate specific biochemical reactions under defined temperature and pH conditions. These enzymes serve as process enablers across pharmaceutical synthesis, food modification, and biomass conversion where chemical alternatives fail on stereoselectivity or environmental compliance. Proteases command the largest revenue share due to their indispensability in cheese manufacturing and protein hydrolysate production, while lipases represent the fastest-expanding category as biodiesel refiners adopt enzymatic transesterification to meet stricter emissions standards. Powder formulations retain dominance in bulk industrial applications, though liquid concentrates gain traction in automated pharmaceutical dispensing systems where dosing precision reduces batch failure rates.
SAMR enforces GB standards on enzyme activity labeling and contaminant thresholds, while MEE regulations on fermentation wastewater discharge shape plant location decisions and capital intensity for new entrants. The dual carbon goals further redirect R&D subsidies toward enzymatic processes that reduce energy consumption in chemical synthesis. Stakeholders must weigh domestic strain development against import dependency as Beijing tightens biosecurity reviews on genetically modified organism imports.
Market Dynamics
China's specialty enzymes sector is bifurcating between high-purity pharmaceutical-grade supply chains and cost-optimized industrial formulations, with dual carbon compliance forcing fermentation plant relocations from coastal zones to western provinces with renewable energy access.
Growth Catalysts
- Dual carbon goals:Beijing's 2030 carbon peak mandate redirects state subsidies toward enzymatic processes that cut energy intensity in chemical synthesis by 40-60% versus thermal catalysis.
- Biologics manufacturing expansion:Antibody-drug conjugate producers in Shanghai Zhangjiang Hi-Tech Park are tripling therapeutic protease procurement for cell culture media optimization.
- GB standards tightening:SAMR's updated purity thresholds for food-grade enzymes are accelerating domestic substitution of imported preparations in Shandong dairy processing corridors.
Market Restraints
- Strain import dependency:Genetically modified production organisms face extended biosecurity review timelines at customs, stretching R&D cycles for novel enzyme variants by 8-14 months.
- Fermentation feedstock volatility:Corn steep liquor and soybean meal prices swing 15-25% seasonally, compressing margins for bulk amylase and cellulase manufacturers without long-term agricultural contracts.
- Wastewater discharge limits:MEE regulations on COD and ammonia nitrogen in fermentation effluent require tertiary treatment installations that add 12-18% to greenfield capital intensity.
Strategic Opportunities
- Western province greenfield sites:Sichuan and Gansu offer stranded renewable power at 0.25-0.32 RMB/kWh, enabling carbon-neutral enzyme production for export to EU markets under CBAM alignment.
- Continuous flow biocatalysis:Immobilized enzyme packed-bed reactors are penetrating fine chemical synthesis, replacing batch stirred-tank operations in Jiangsu agrochemical intermediates plants.
- Clean-label food acceleration:FSSAI-equivalent standards in ASEAN import markets create demand for Chinese-origin transglutaminase and lipase preparations certified for additive-free meat and bakery applications.
Industry Challenges
- Fermentation scale-up expertise gap:Industrial microbiologists capable of optimizing 100,000L+ submerged culture titers command 2.5x median manufacturing wages, constraining mid-tier producer expansion.
- Cross-contamination validation:Multi-product enzyme plants must demonstrate cleaning validation protocols to NMPA inspectors, adding 6-9 months to facility qualification timelines for pharmaceutical-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Specialty Enzymes Market |
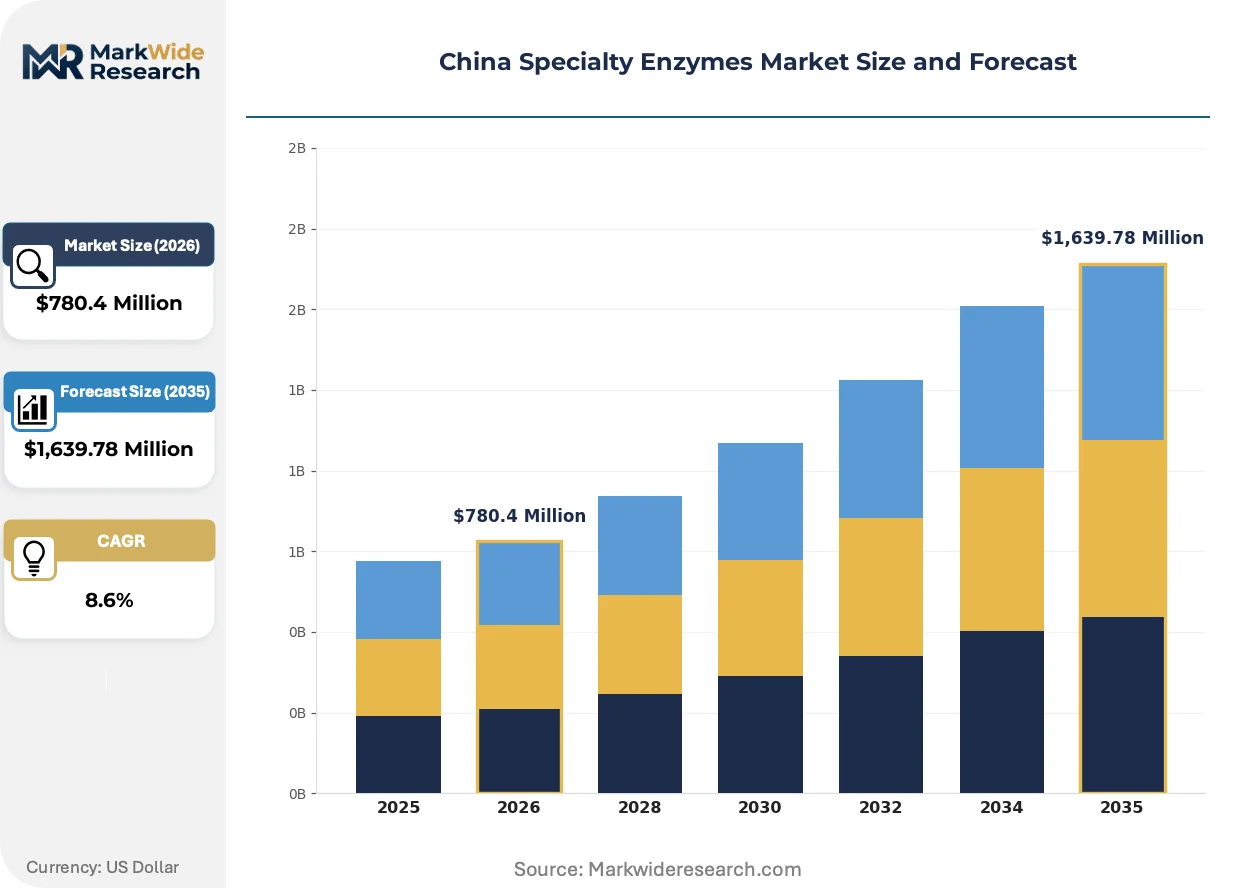
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,639.78 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Cellulases, Lipases Application: Food & Beverages, Pharmaceuticals, Biofuels, Animal Feed Form: Liquid, Powder, Granulated, Tablet End User: BFSI, Healthcare, Agriculture, Industrial |
| Companies Covered | Novozymes, Amano Enzyme Inc., Koninklijke DSM N.V., Chr. Hansen Holding A/S, Advanced Enzyme Technologies, BASF, Codexis Inc., Kerry Group, China National Bluestar Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Specialty Enzymes Market Trends and Innovations
Enzyme engineering platforms are compressing development timelines from strain isolation to commercial production, while regulatory pressure on process sustainability forces simultaneous adoption of synthetic biology and circular manufacturing systems.
Directed evolution combined with machine learning-guided protein design is electrifying the discovery of thermostable lipase variants for biodiesel transesterification. Shandong and Guangdong refiners are piloting these biocatalysts at 50,000-ton annual capacity, enabling continuous operation at 45°C versus conventional 35°C batch limits and cutting steam consumption by one-third.
MEE's 2024 fermentation wastewater discharge standards now mandate zero liquid discharge for new enzyme plants above 5,000-ton annual output. This is forcing membrane bioreactor and anaerobic digestion technology adoption in Jiangsu and Zhejiang facilities, with compliance costs absorbed through product mix shifts toward higher-margin pharmaceutical grades.
Clean-label procurement is consolidating buyer power among Shandong food conglomerates that now require enzyme suppliers to disclose full strain lineage and processing aids. This is compressing vendor lists from 12-15 qualified suppliers per category to 3-4 strategic partners, with contract terms extending from annual to 3-year frameworks with volume guarantees and joint formulation development clauses.
China Specialty Enzymes Market Segmentation
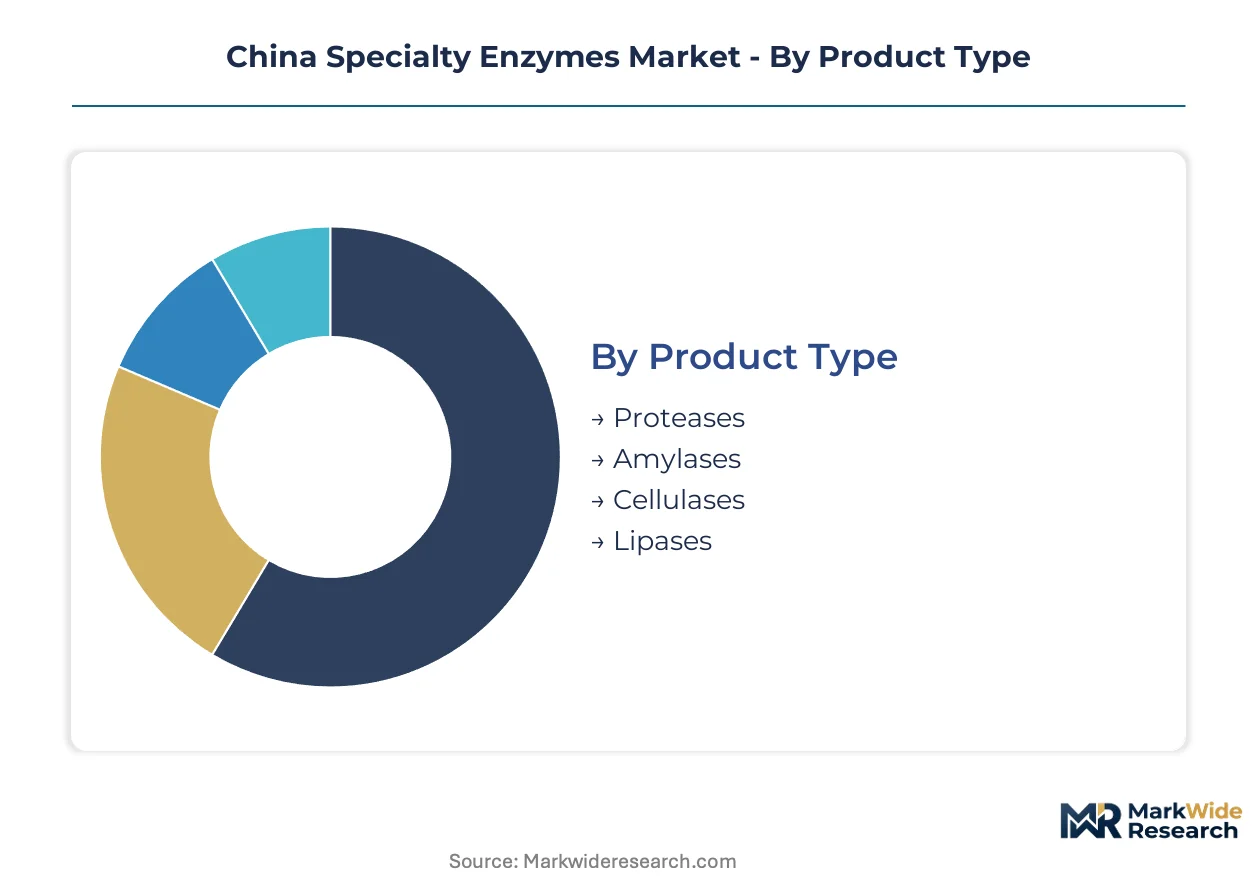
Enzyme manufacturers in China configure production lines around molecular function and application purity requirements rather than commodity scale. Segmentation decisions determine whether strains serve standalone industrial processes or embed within complex multi-step bioprocessing chains.
Product Type:
Proteases and amylases operate as standalone bulk commodities with established downstream integration, while lipases and cellulases increasingly embed within specialized bioconversion systems requiring strain customization.
- Proteases:Hydrolytic enzymes cleaving peptide bonds with molecular weights typically between 20,000 and 100,000 Daltons, produced via submerged fermentation of Bacillus subtilis or Aspergillus oryzae. Demand concentrates in Shandong dairy processing corridors where cheese manufacturing and protein hydrolysate production drive procurement from domestic suppliers meeting tightened GB standards. SAMR purity thresholds are accelerating substitution of imported preparations.
- Amylases:Starch-degrading enzymes catalyzing α-1,4-glycosidic bond hydrolysis, available as thermostable variants for high-temperature liquefaction. Jiangsu generic drug manufacturers procure cost-optimized variants for pharmaceutical excipient production, squeezing margins through volume contracting without long-term agricultural feedstock agreements.
- Cellulases:Complex enzyme systems depolymerizing cellulose into fermentable sugars, critical for biomass conversion applications. Sichuan bioethanol pilot plants evaluate cellulase cocktails for agricultural residue processing under dual carbon compliance mandates.
- Lipases:Ester hydrolases enabling transesterification and interesterification reactions with high stereoselectivity. Guangdong biodiesel refiners pilot thermostable variants at 50,000-ton annual capacity, cutting steam consumption through continuous 45°C operation versus conventional batch limits.
Proteases lead volumes today; lipases are gaining share fastest.
Application:
Cost tiers separate pharmaceutical-grade supply chains with NMPA validation requirements from industrial formulations competing on unit economics and feedstock flexibility.
- Food & Beverages:Enzyme formulations for dairy, baking, brewing, and juice clarification requiring FSSAI-equivalent certification for ASEAN export markets. Shandong conglomerates now mandate full strain lineage disclosure, compressing qualified supplier lists from 12-15 to 3-4 strategic partners with 3-year framework contracts.
- Pharmaceuticals:High-purity biocatalysts for therapeutic protein synthesis and cell culture media optimization. Shanghai Zhangjiang Hi-Tech Park antibody-drug conjugate producers tripled therapeutic protease procurement, with cross-contamination validation protocols adding 6-9 months to facility qualification timelines.
- Biofuels:Enzymatic transesterification systems for biodiesel production and cellulosic ethanol conversion. Western province greenfield sites leverage stranded renewable power at 0.25-0.32 RMB/kWh for carbon-neutral production aligned with EU CBAM requirements.
- Animal Feed:Phytase and non-starch polysaccharide enzymes improving nutrient digestibility in swine and poultry operations. Corn steep liquor price volatility of 15-25% seasonally compresses margins for bulk manufacturers lacking agricultural contracts.
Food & Beverages dominates current procurement; Pharmaceuticals shows the steepest expansion trajectory.
Form:
Volume concentration favors powder for bulk industrial handling, while margin concentration shifts toward liquid concentrates in automated pharmaceutical dispensing.
- Liquid:Standardized enzyme concentrates with defined activity units per milliliter, optimized for automated dosing systems. Jiangsu biologics manufacturers adopt liquid formulations to reduce batch failure rates through precision dispensing in cell culture applications.
- Powder:Spray-dried or freeze-dried preparations with extended shelf stability for bulk material handling. Retains dominance in Shandong and Guangdong food processing corridors where manual dosing and extended storage predominate.
- Granulated:Dust-free formulations with controlled particle size distribution for safe handling in feed mills. Sichuan and Gansu facilities package granulated cellulases for agricultural residue processing operations.
- Tablet:Unit-dose solid preparations for laboratory and small-scale pharmaceutical synthesis. Limited penetration constrained by dissolution rate variability in high-purity applications.
Powder leads volumes today; liquid concentrates are climbing the fastest.
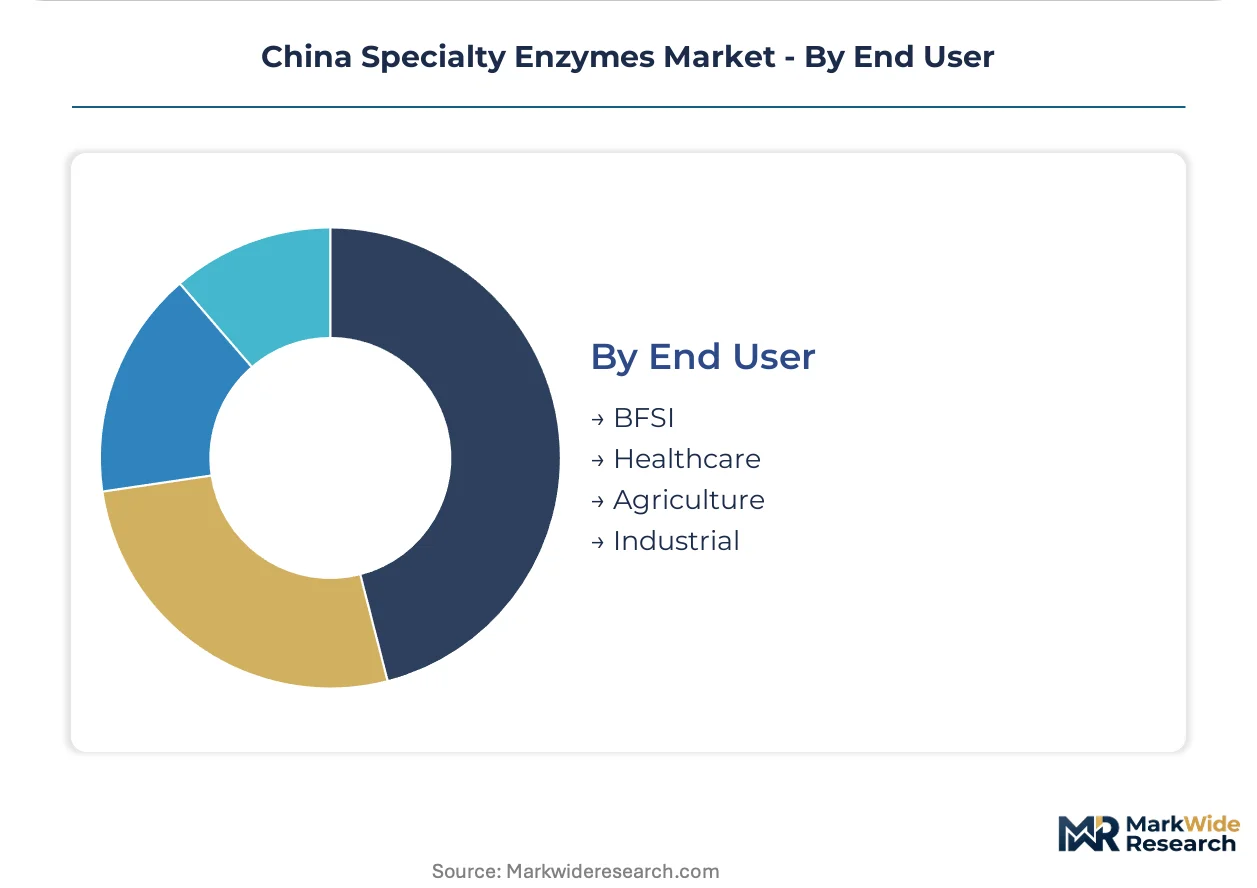
End User:
Customer sophistication determines specification stringency, with industrial and healthcare segments diverging on purity validation and documentation requirements.
- BFSI:Banking, financial services, and insurance sector procurement for document preservation and archival applications. Niche demand concentrated in state-owned institution digitization projects.
- Healthcare:Hospitals, diagnostic laboratories, and research institutions requiring GMP-compliant enzyme preparations. NMPA inspection protocols for multi-product plants enforce cleaning validation documentation.
- Agriculture:Crop processing, silage fermentation, and soil amendment applications. Corn and soybean meal feedstock dependency creates margin pressure for cellulase and phytase suppliers without grain elevator partnerships.
- Industrial:Textile desizing, leather bating, detergent manufacturing, and wastewater treatment operations. MEE zero liquid discharge mandates for plants above 5,000-ton annual output force membrane bioreactor adoption in Jiangsu and Zhejiang.
Industrial users anchor current demand; Healthcare procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme production migrates toward western provinces where stranded renewable power and relaxed MEE discharge standards compress compliance costs versus coastal manufacturing zones. This regulatory-arbitrage dynamic reshapes plant location decisions across the value chain.
Yangtze River Delta
Shanghai Zhangjiang Hi-Tech Park anchors therapeutic protease demand as antibody-drug conjugate manufacturers triple procurement for cell culture media optimization. SAMR enforces GB standards on enzyme activity labeling that accelerate domestic substitution. Cross-contamination validation protocols add 6-9 months to facility qualification timelines for pharmaceutical-grade output.
Pearl River Delta
Guangdong biodiesel refiners pilot thermostable lipase variants at 50,000-ton annual capacity, cutting steam consumption through continuous 45°C operation. MEE regulations on COD and ammonia nitrogen in fermentation effluent force membrane bioreactor adoption. Clean-label food procurement consolidates buyer power among conglomerates requiring full strain lineage disclosure.
Shandong Peninsula
Dairy processing corridors drive protease procurement for cheese manufacturing and protein hydrolysate production. GB standards tightening on food-grade enzyme purity accelerates substitution of imported preparations. Vendor lists compress from 12-15 qualified suppliers per category to 3-4 strategic partners with 3-year framework contracts.
Sichuan-Chongqing
Stranded renewable power at 0.25-0.32 RMB/kWh enables carbon-neutral enzyme production for EU CBAM-aligned export. Bioethanol pilot plants evaluate cellulase cocktails for agricultural residue processing under dual carbon compliance mandates. Zero liquid discharge mandates for plants above 5,000-ton annual output shape greenfield capital intensity.
Western China
Gansu facilities package granulated cellulases for agricultural residue processing operations with access to low-cost wind and solar generation. Fermentation feedstock volatility of 15-25% seasonally compresses margins for bulk manufacturers without long-term agricultural contracts. MEE's 2024 wastewater standards redirect R&D subsidies toward enzymatic processes.
China Specialty Enzymes Market Competitive Landscape
Capacity expansion dominates the current landscape as producers relocate fermentation assets to western provinces with renewable energy access and relaxed discharge standards. The vendor base stratifies between multinational strain developers with Danish and German fermentation heritage and domestic cost-optimized suppliers. Three archetypes emerge: premium pharmaceutical-grade specialists, bulk industrial commodity producers, and hybrid regional generics suppliers. Geographic expansion and backward integration into genetically modified strain development constitute the dominant competitive moves.
Among Danish-heritage specialists, Novozymes occupies a position exemplifying premium-tier pharmaceutical supply through submerged fermentation expertise. BASF anchors the integrated multinational archetype with captive strain development capabilities. Advanced Enzyme Technologies sits within the cost-optimized domestic tier competing on amylase variants for regional generics producers. These three represent the competitive spectrum without exhausting the participant set.
| Leading Market Players |
|---|
| Novozymes |
| Amano Enzyme Inc. |
| Koninklijke DSM N.V. |
| Chr. Hansen Holding A/S |
| Advanced Enzyme Technologies |
| BASF |
| Codexis Inc. |
| Kerry Group |
| China National Bluestar Group |
| Others |
Pricing and Supply Chain Analysis
Immobilized enzyme packed-bed reactor adoption simultaneously compresses unit production costs and concentrates supply relationships among Jiangsu pharmaceutical manufacturers capable of validating continuous flow biocatalysis systems. This technology transition rewards producers with NMPA-qualified facilities while squeezing batch-oriented competitors on both margin and procurement access.
Pricing Analysis
Distributor margins for pharmaceutical-grade enzymes absorb 18-25% of ex-factory value, with direct-to-OEM contracting bypassing this layer for Shanghai Zhangjiang biologics manufacturers. Three-tier pricing structure across GMP-certified, food-grade, and industrial-grade tiers reflects NMPA validation burden and strain lineage documentation requirements. Pricing pressure stems from corn steep liquor and soybean meal volatility compressing bulk amylase margins. Generic drug manufacturers in Jiangsu exhibit highest price sensitivity; antibody-drug conjugate producers accept premium positioning for cross-contamination validated supply.
Supply Chain Analysis
Freight costs from western province greenfield sites to coastal demand centers add 8-12% to delivered enzyme costs, favoring Sichuan and Gansu producers with rail-accessible facilities. Supply concentrates in China, Denmark, and Germany for high-purity pharmaceutical strains; industrial bulk enzymes draw from domestic submerged fermentation capacity. Raw material dependencies include corn steep liquor, soybean meal, and specialized nitrogen sources. Single-source vulnerability runs through genetically modified strain imports facing extended SAMR biosecurity review. Distribution runs through regional chemical distributors for industrial grades and direct technical sales for pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China specialty enzymes constitute a late-cycle quality story as SAMR purity mandates and dual carbon compliance filter marginal producers from pharmaceutical and clean-label food supply chains. Therapeutic protease specifications from Shanghai antibody-drug conjugate manufacturers now require documentation depth that only validated domestic facilities can sustain.
For Market Incumbents: Acquire stranded renewable power assets in Sichuan and Gansu to lock in 0.25-0.32 RMB/kWh electricity costs before western province site competition intensifies. Secure long-term agricultural feedstock contracts with Shandong grain elevators to insulate bulk amylase margins from 15-25% seasonal corn steep liquor volatility. Cross-contamination validation protocols represent the priority defensive moat against mid-tier producers seeking pharmaceutical-grade qualification. For New Entrants and Emerging Players: Launch via continuous flow biocatalysis technology licensing to Jiangsu agrochemical intermediates plants seeking batch replacement. Target thermostable lipase supply to Guangdong biodiesel refiners piloting 50,000-ton enzymatic transesterification capacity. Clean-label meat and bakery enzyme formulations for ASEAN export markets offer the most penetrable white space given FSSAI-equivalent certification gaps among established suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional generics-focused enzyme suppliers because SAMR facility qualification timelines stretch 6-9 months and vendor lists compress from 12-15 to 3-4 qualified suppliers per category. Long-term viability centers on backward integration into genetically modified strain development to escape import dependency. The signal to watch is MEE zero liquid discharge enforcement velocity for plants above 5,000-ton annual output.| Strategic Initiative | Industry Significance |
|---|---|
| Western Province Greenfield Development | Sichuan and Gansu stranded renewable power enables CBAM-aligned export production. |
| Continuous Flow Biocatalysis Adoption | Immobilized enzyme packed-bed systems displace batch stirred-tank operations in Jiangsu. |
| Strain Lineage Documentation Investment | Full disclosure protocols satisfy Shandong conglomerate clean-label procurement mandates. |
| Long-term Agricultural Feedstock Contracting | Corn steep liquor price hedging protects bulk amylase margin structures. |
| NMPA Cross-contamination Validation | Cleaning protocol documentation qualifies facilities for therapeutic protease supply. |
Research Methodology
Multiple input streams — fermentation plant operating data, SAMR regulatory filings, and customs enzyme import records — were reconciled against primary interviews with industrial microbiologists, pharmaceutical procurement managers, and MEE compliance officers. Secondary validation drew from GB standards documentation, NMPA facility inspection disclosures, and provincial renewable energy pricing bulletins. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing across the analysis window.
Segment-level projections incorporated product type, application purity tier, and form factor dimensions alongside regional production hub access to renewable energy. CAGRs were derived from slope analysis of historical procurement patterns and forward capacity expansion announcements. Forecast inputs included dual carbon subsidy allocation trajectories and MEE wastewater discharge standard implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended GMO import review timelines or abrupt corn steep liquor price spikes. Model outputs reflect assumptions on strain development cycle durations and western province infrastructure buildout velocity. A model refresh is warranted upon material change in SAMR biosecurity review protocols or MEE zero liquid discharge enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Biocatalyst Market