
 South Korea Oral Anti-Diabetic Drug Market | 2026-2036
South Korea Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Oral Anti-Diabetic Drug Market Insights
Endocrinology specialist shortages across provincial health centers is unwinding access bottlenecks that previously limited patient enrollment in structured diabetes programs. Novo Nordisk leverages its insulin portfolio depth to anchor hospital formulary positioning nationwide. Handok competes through localized manufacturing and distribution partnerships with regional pharmacy chains. Eli Lilly and Company differentiates via sustained investment in GLP-1 receptor agonist combinations with oral agents.
South Korea oral anti-diabetic drugs comprise chemically synthesized or biologically derived pharmaceutical agents formulated for gastrointestinal absorption, with molecular weights typically below 500 Daltons for small-molecule agents like metformin and DPP-4 inhibitors, designed to modulate glucose metabolism through pancreatic, hepatic, or renal mechanisms. These agents serve as first-line or adjunctive interventions to achieve glycemic control in type 2 diabetes mellitus patients before or alongside insulin initiation. SGLT2 inhibitors command expanding prescription share among cardiologists and nephrologists due to demonstrated heart and kidney protection beyond glucose lowering. Homecare distribution channels are gaining traction as telemedicine reimbursement policies mature, though hospital and clinic dispensing still dominates volume. Metformin maintains its foundational status in initial therapy protocols despite emerging combination preferences.
MFSD review timelines and KDCA pharmacovigilance reporting requirements shape product launch sequencing and post-market surveillance obligations for all entrants. The national health insurance service reimbursement list, managed by HIRA, determines patient out-of-pocket exposure and thus physician prescribing patterns across public and private institutions. Stakeholders must monitor evolving MFDS guidance on fixed-dose combination approvals and HIRA's periodic cost-effectiveness reassessments to anticipate portfolio repositioning requirements.
Market Dynamics
MFDS biosimilar pathway reforms are compressing competitive entry timelines and forcing incumbent portfolio repositioning across Seoul's tertiary hospital network and provincial clinics.
Growth Catalysts
- Hospital-based diabetes management programs:Structured protocols in Seoul National University Hospital and Asan Medical Center are expanding combination therapy enrollment. These programs bundle oral agents with patient monitoring systems.
- HIRA reimbursement expansion:The national health insurance service's periodic cost-effectiveness reassessments are broadening SGLT2 inhibitor coverage for cardiorenal indications beyond glycemic control.
- Telemedicine maturation:Reimbursement policy evolution for remote consultations is unlocking homecare distribution channels in Gyeonggi-do and Busan metropolitan zones.
Market Restraints
- API import dependency:Active pharmaceutical ingredient sourcing concentrates on Chinese and Indian manufacturers, exposing formulators to supply volatility and quality audit failures.
- KDCA pharmacovigilance burden:Post-market surveillance reporting requirements impose sustained compliance costs that disproportionately strain mid-scale domestic entrants.
- Endocrinologist concentration:Specialist availability clusters in Seoul and five major cities, creating access bottlenecks that limit structured program enrollment in Gangwon-do and Jeolla provinces.
Strategic Opportunities
- Daegu-Gyeongbuk medical cluster:Underpenetrated tertiary capacity in this southeastern region offers first-mover positioning for combination therapy protocols before saturation.
- Fixed-dose combination approvals:MFDS guidance evolution on single-pill formulations creates regulatory tailwind for GLP-1 oral agent pairings seeking streamlined review pathways.
- Community pharmacy integration:Regional pharmacy chains in Daejeon and Gwangju are piloting adherence monitoring programs that could reshape dispensing economics.
Industry Challenges
- Clinical trial site activation:Principal investigator recruitment delays at provincial institutions compress development timelines for novel mechanism candidates.
- Legacy system integration:Hospital electronic medical record fragmentation between Seoul's major centers requires bespoke connectivity solutions for real-world evidence collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Oral Anti-Diabetic Drug Market |
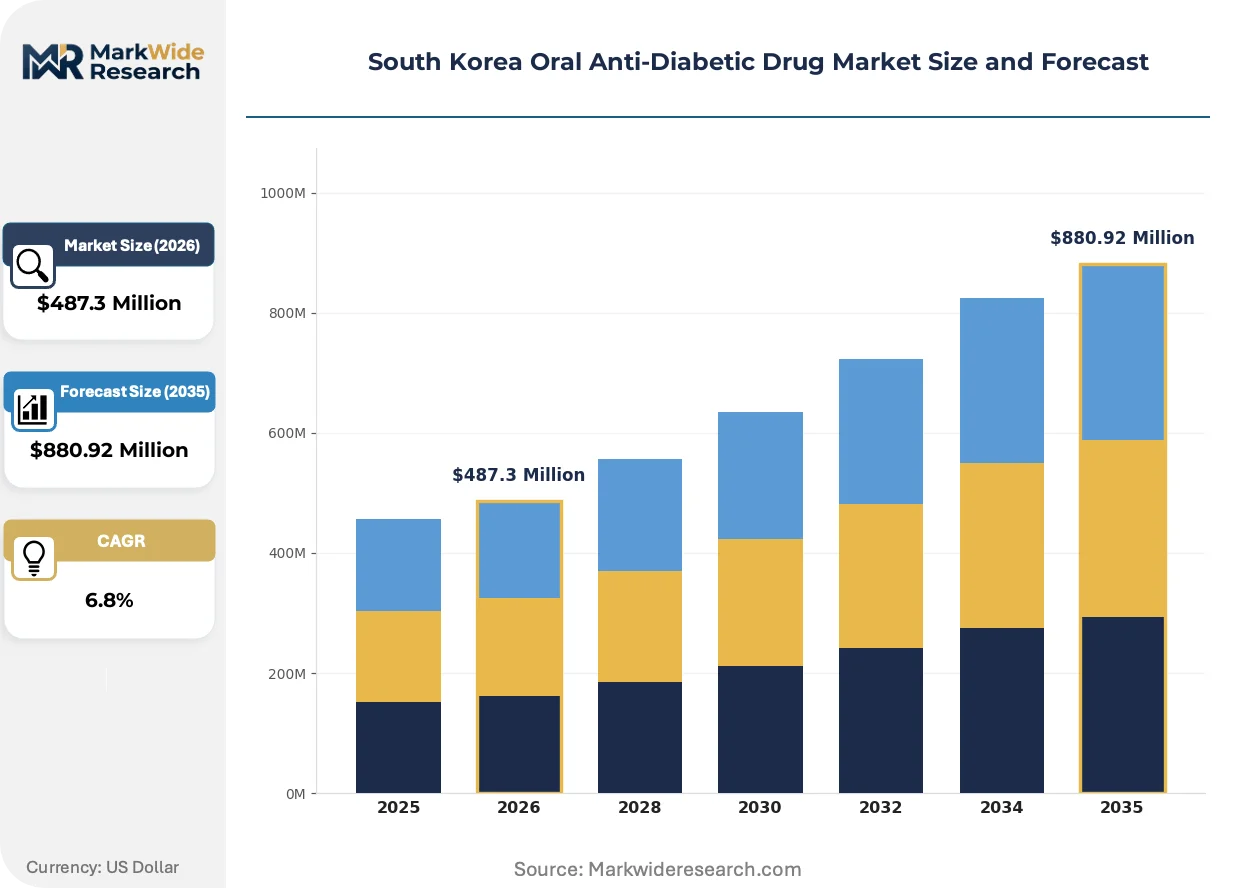
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors End User: Hospitals, Clinics, Pharmacies, Homecare Treatment Stage: Initial, Maintenance, Combination Therapy, Advanced Administration Route: Oral, Injectable, Transdermal, Others |
| Companies Covered | Janssen Pharmaceuticals, Takeda, Eli Lilly and Company, Pfizer, Novo Nordisk, Astellas, AstraZeneca, Handok, Sanofi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Oral Anti-Diabetic Drug Market Trends and Innovations
Digital therapeutics and combination formulation science are converging to reshape how oral anti-diabetic agents demonstrate value beyond glucose lowering endpoints.
Continuous glucose monitoring patch technology is miniaturizing sensor form factors for integration with oral therapy regimens. Endocrinology departments at Severance Hospital and Samsung Medical Center are piloting combined prescription bundles. This convergence is miniaturizing the boundary between pharmaceutical and device reimbursement categories.
MFDS fixed-dose combination guidance revisions are streamlining review pathways for multi-mechanism pills. Domestic manufacturers gain accelerated access to priority review queues when cardiorenal outcome data accompanies submissions. SGLT2 inhibitor-metformin combinations receive disproportionate benefit from this regulatory tailwind.
Patient-driven channel selection is fragmenting traditional hospital-centric dispensing patterns. Younger demographics in Seongnam and Suwon are migrating toward certified online pharmacies with cold-chain capabilities. This behavioral pivot pressures wholesalers to reconfigure last-mile logistics for temperature-sensitive biologic oral agents.
South Korea Oral Anti-Diabetic Drug Market Segmentation
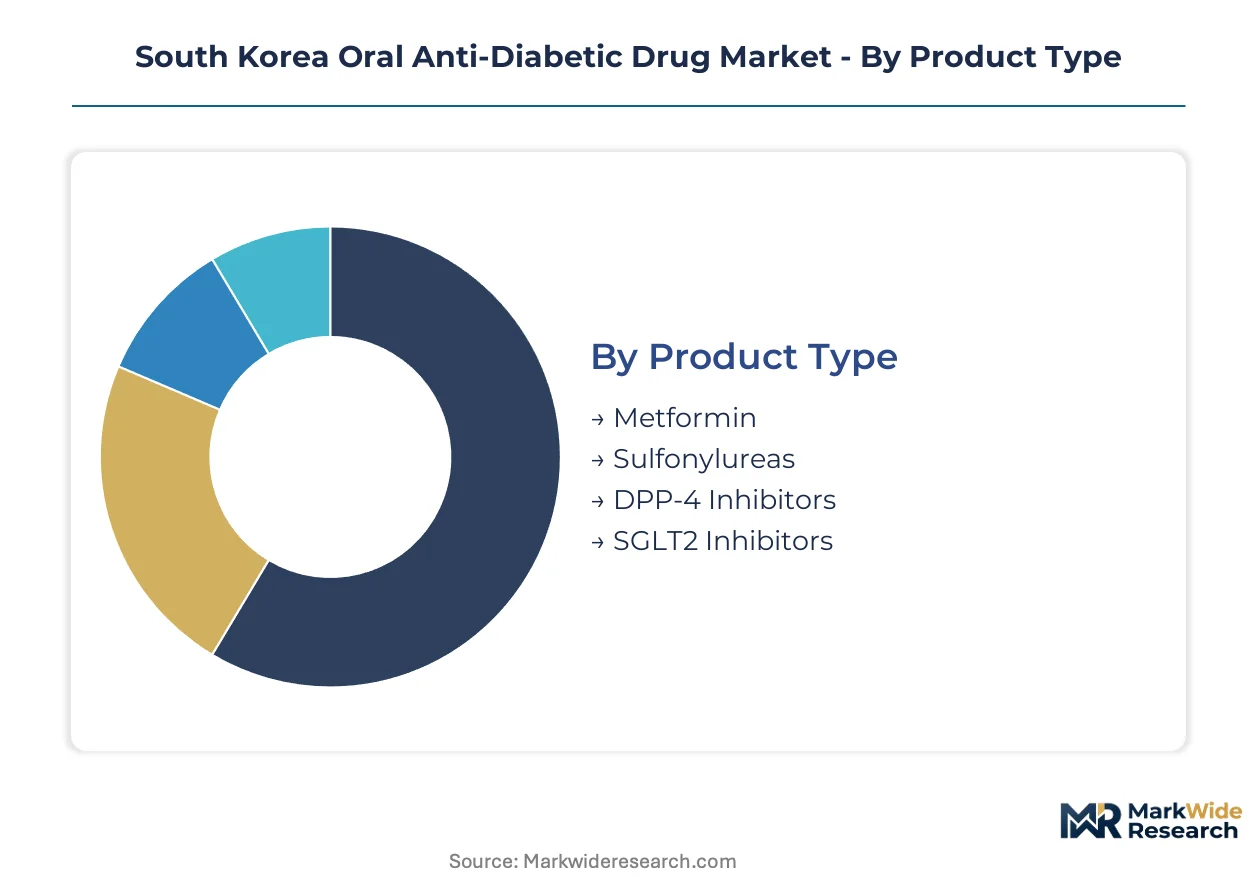
Oral anti-diabetic drug segmentation in South Korea reflects reimbursement stratification by HIRA and prescribing authority concentration across Seoul's tertiary network. Product type and end user dimensions intersect with MFDS approval pathways to determine commercial access and margin structure.
Product Type:
MFDS review timelines and KDCA post-market surveillance obligations vary substantially across mechanistic classes, shaping launch sequencing and portfolio investment.
- Metformin:Biguanide compound with molecular weight 129.16 Daltons suppressing hepatic gluconeogenesis and enhancing peripheral insulin sensitivity. Demand concentrates in Seoul National University Hospital and Asan Medical Center initial therapy protocols driven by HIRA first-line reimbursement status and decades of safety data.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers with demonstrated cardiorenal outcome benefits beyond glycemic control. Prescription volume clusters among cardiologists and nephrologists at Severance Hospital and Samsung Medical Center propelled by expanded HIRA coverage for heart failure and chronic kidney disease indications.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 enzyme inhibitors with weight-neutral glucose lowering profile used in maintenance protocols across Gyeonggi-do metropolitan clinics.
- Sulfonylureas:Pancreatic beta-cell secretagogues with established hypoglycemia risk profiles remaining in provincial health center formularies due to cost advantages.
Metformin handles the majority of throughput; SGLT2 inhibitors are gaining share fastest on cardiorenal indication expansion.
End User:
Channel economics diverge sharply between institutional dispensing with bundled monitoring services and retail pharmacy transactions shaped by patient cost-sharing.
- Hospitals:Tertiary centers in Seoul, Busan, and Daegu dominate combination therapy enrollment through structured diabetes management programs integrating oral agents with continuous glucose monitoring and specialist consultation.
- Clinics:Metropolitan and provincial primary care settings handle maintenance therapy transitions and prescription renewals with lighter monitoring infrastructure.
- Pharmacies:Regional chains in Daejeon and Gwangju are piloting adherence monitoring programs that reshape dispensing economics through value-added services.
- Homecare:Certified online pharmacies with cold-chain capabilities in Seongnam and Suwon serve younger demographics seeking convenience, though volume remains constrained by reimbursement policy maturation.
Hospitals capture the highest value per patient encounter; homecare channels show the steepest expansion trajectory as telemedicine reimbursement evolves.
Treatment Stage:
Protocol positioning determines formulary tier placement and physician prescribing autonomy across South Korea's dual public-private system.
- Initial:First-line monotherapy or dual therapy initiation at diagnosis, concentrated in endocrinology departments with structured patient education requirements.
- Maintenance:Stable glycemic control periods with periodic HbA1c monitoring, representing the largest patient volume across provincial health centers.
- Combination Therapy:Multi-mechanism oral regimens or oral-insulin pairings, fastest-expanding segment driven by hospital-based program enrollment and MFDS fixed-dose combination pathway streamlining.
- Advanced:Complex regimens preceding or accompanying insulin intensification, managed primarily at tertiary referral centers with multidisciplinary teams.
Maintenance therapy handles the majority of patient-years; combination therapy is climbing the fastest on protocol adoption.
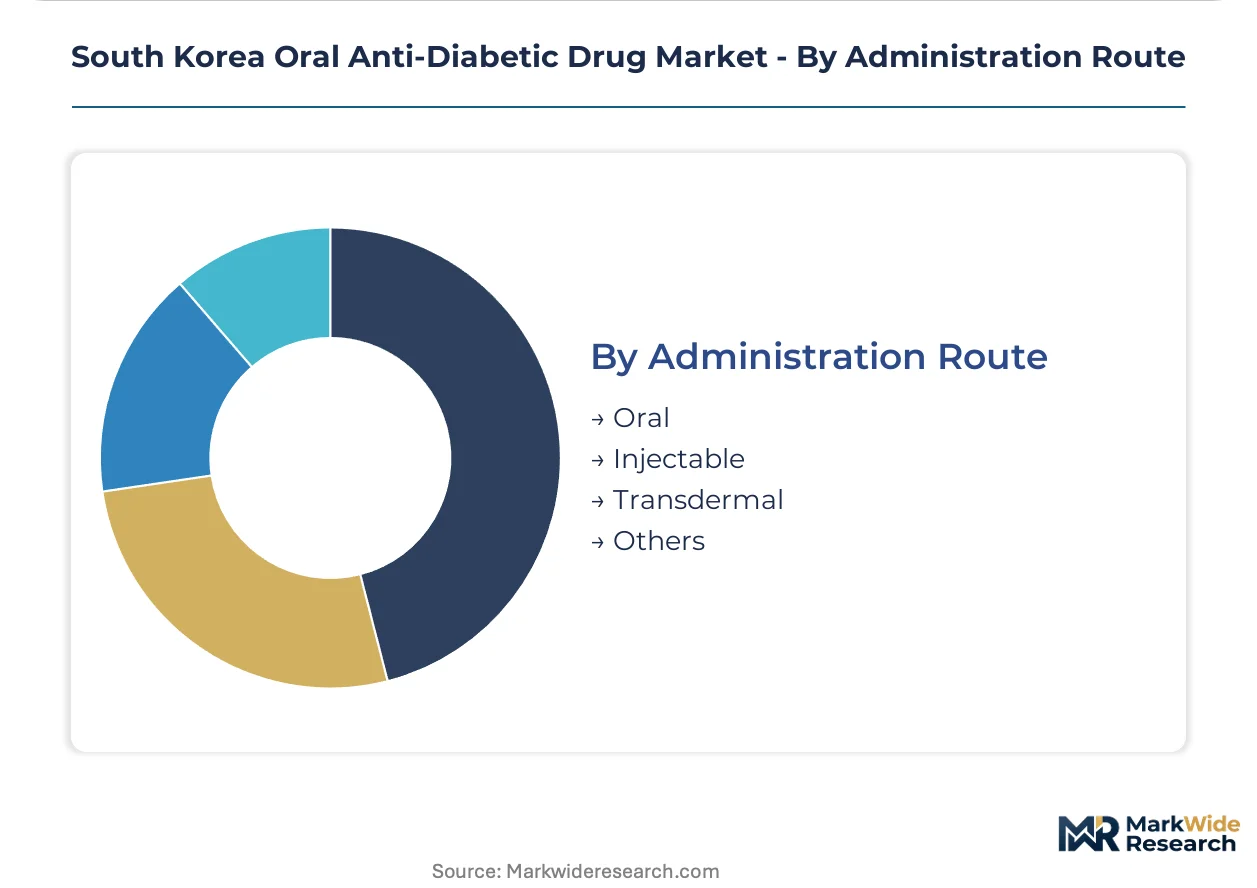
Administration Route:
Reimbursement category boundaries between pharmaceutical and device channels shape patient out-of-pocket exposure and access pathways.
- Oral:Gastrointestinal absorption of small-molecule and biologic agents with molecular weights typically below 500 Daltons, encompassing the full scope of this market analysis.
- Injectable:Subcutaneous insulin and GLP-1 receptor agonist delivery, relevant as combination therapy context and competitive reference point for oral agent positioning.
- Transdermal:Patch-based delivery systems in early development for continuous glucose monitoring integration with oral regimens.
- Others:Nasal and buccal formulations under investigation at domestic research institutes with limited commercial presence.
Oral administration handles essentially all volume in this market; transdermal formats are expanding most quickly on device convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Seoul consumes combination therapies at triple the rate of provincial zones, while Jeolla and Gangwon provinces remain anchored to sulfonylurea maintenance protocols due to specialist scarcity.
Seoul Capital Area
Severance Hospital and Samsung Medical Center drive SGLT2 inhibitor-metformin dual therapy enrollment through structured cardiorenal programs. MFDS priority review queues accelerate fixed-dose combination approvals for submissions bundled with heart failure outcome data. The Gangnam-Seongnam corridor hosts the densest concentration of certified online pharmacies with cold-chain capabilities.
Busan-Ulsan
Port-city industrial demographics elevate demand for weight-neutral DPP-4 inhibitors among employed patient populations. HIRA regional reimbursement offices process appeals for expanded SGLT2 coverage in chronic kidney disease cases. Pusan National University Hospital anchors combination therapy protocols for the southeastern coastal zone.
Daegu-Gyeongbuk
Underpenetrated tertiary capacity creates first-mover positioning for hospital-based diabetes management programs before network saturation. Kyungpook National University Hospital activates clinical trial sites for novel mechanism candidates facing principal investigator recruitment delays elsewhere. The medical cluster attracts pharmaceutical distribution investments from regional pharmacy chains.
Daejeon-Sejong
Government complex proximity shapes public health insurance policy pilot programs for telemedicine reimbursement. KDCA pharmacovigilance reporting infrastructure concentrates here, imposing compliance cost burdens on mid-scale domestic entrants. Community pharmacy adherence monitoring programs reshape dispensing economics across the Chungcheong corridor.
Gwangju-Honam
Agricultural employment patterns sustain sulfonylurea dominance in initial therapy protocols due to cost sensitivity and hypoglycemia risk tolerance. Endocrinologist availability bottlenecks limit structured program enrollment relative to national averages. Regional pharmacy chains pilot value-added adherence services to differentiate from hospital-centric dispensing.
South Korea Oral Anti-Diabetic Drug Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South Korea's oral anti-diabetic drug market. Multinational pharmaceutical conglomerates anchor hospital formulary positioning through insulin portfolio depth and GLP-1 receptor agonist combinations. Domestic manufacturers compete via localized production and regional distribution partnerships. The dominant competitive moves are strategic partnerships with tertiary hospital networks and portfolio diversification into fixed-dose combination formulations.
Among multinational developers, Novo Nordisk and Eli Lilly and Company exemplify the integrated leader archetype through sustained investment in combination therapies. Handok represents the domestic specialist tier, competing through manufacturing localization and pharmacy chain alliances. These three anchors illustrate how regulatory navigation of MFDS biosimilar pathways and HIRA reimbursement positioning separate market tiers.
| Leading Market Players |
|---|
| Janssen Pharmaceuticals |
| Takeda |
| Eli Lilly and Company |
| Pfizer |
| Novo Nordisk |
| Astellas |
| AstraZeneca |
| Handok |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Seoul's tertiary hospital networks and domestic distributors lock in both API supply access and price visibility for metformin and DPP-4 inhibitor portfolios. These contracts insulate formulators from spot-market volatility in Chinese active pharmaceutical ingredient sourcing while anchoring HIRA reimbursement tier positioning.
Pricing Analysis
Project-based contracting dominates institutional procurement, with Seoul National University Hospital and Asan Medical Center negotiating bundled pricing for combination therapy protocols that include patient monitoring services. Price differentiation hinges on cardiorenal outcome certification tiers and vertical integration depth into local manufacturing. Cost compression in the sulfonylurea segment is intensifying because of HIRA periodic cost-effectiveness reassessments. Provincial health centers exhibit the highest price sensitivity due to budget constraints, while tertiary centers prioritize clinical outcome data over unit cost.
Supply Chain Analysis
Strategic stockpiling preferences among Korean formulators reflect API import dependency vulnerabilities, with manufacturers maintaining 3-6 month safety inventories of critical inputs. Active pharmaceutical ingredient sourcing draws from China, India, and Switzerland, with metformin precursors and SGLT2 inhibitor intermediates concentrated among specialized chemical manufacturers. Single-source vulnerability in high-purity DPP-4 inhibitor synthesis creates exposure to quality audit failures. Distribution runs through regional pharmacy chains with cold-chain capabilities serving the Seongnam-Suwon corridor, supplemented by hospital-based dispensing for combination therapy enrollment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of endocrinology specialists trained in cardiorenal protocol management constrains expansion of structured diabetes programs beyond Seoul's tertiary network, creating asymmetric access to high-margin combination therapies.
For Market Incumbents: Consolidate hospital formulary positioning through exclusive supply agreements with Severance Hospital and Samsung Medical Center before MFDS biosimilar pathway reforms accelerate competitive entry. Deepen backward integration into API synthesis for SGLT2 inhibitor-metformin combinations to defend margin structure against Indian and Chinese generic pressure. Prioritize KDCA pharmacovigilance infrastructure investment to sustain post-market surveillance compliance as regulatory burdens intensify. For New Entrants and Emerging Players: Lead with fixed-dose combination submissions targeting Daegu-Gyeongbuk's underpenetrated tertiary capacity, where first-mover positioning remains available before network saturation. The most penetrable segment is community pharmacy adherence monitoring programs in Daejeon and Gwangju, where regional chains seek value-added partnerships. Deploy telemedicine-integrated homecare distribution as the primary go-to-market angle, leveraging evolving HIRA reimbursement for remote consultations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated domestic manufacturers with localized production and established MFDS regulatory navigation capabilities. Long-term viability hinges on portfolio diversification into cardiorenal indication expansion and digital therapeutic convergence over the next decade. Target acquisition archetypes include mid-scale formulators with priority review queue access and hospital network relationships. The signal to watch is MFDS guidance evolution on GLP-1 oral agent pairings, which would indicate inflection toward next-generation combination platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Approval Pathway | MFDS priority review queues accelerate market entry for cardiorenal outcome-bundled submissions. |
| Hospital System Partnership | Exclusive supply agreements with Seoul National University Hospital anchor formulary tier positioning. |
| Backward Integration into API Synthesis | In-house production of SGLT2 inhibitor intermediates reduces exposure to Chinese import volatility. |
| Telemedicine Reimbursement Strategy | HIRA policy evolution in Daejeon-Sejong unlocks homecare channel expansion for younger demographics. |
| Digital Therapeutic Platform Integration | Continuous glucose monitoring convergence at Severance Hospital blurs pharmaceutical-device reimbursement boundaries. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads at MFDS, hospital formulary directors, and payer access specialists at HIRA, then refined through secondary validation. Sources included MFDS approval filings, KDCA pharmacovigilance reports, HIRA reimbursement database updates, and clinical trial registrations. Bottom-up prescription volume modeling and top-down market sizing triangulation anchored value estimates.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by treatment stage, administration route, and regional regulatory cluster. Segmentation dimensions encompass product type mechanistic classes, end-user channel economics, and patient population protocol positioning. CAGRs derive from regression analysis of historical enrollment trends in structured diabetes management programs, adjusted for MFDS biosimilar pathway timeline compression.
The analysis sits within stated boundaries; outcomes outside sustained HIRA reimbursement expansion for cardiorenal indications would require recalibration. Forecasts reflect assumptions regarding endocrinologist workforce growth and telemedicine policy maturation. Revision becomes warranted when API import dependency triggers supply disruption thresholds or MFDS fixed-dose combination guidance accelerates beyond modeled timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
North America Insulin Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetic Shoes Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Asia Pacific Diabetes Drug Market