
 Supplier Quality Management Applications Market | 2026-2036
Supplier Quality Management Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Supplier Quality Management Applications Market Analytics
Talent scarcity in statistical process control engineering is collapsing implementation timelines across enterprise deployments. SAP leverages its ERP install base to anchor quality modules into existing procurement workflows. Siemens dominates industrial IoT integration, connecting shop-floor sensors directly to supplier scorecards. ETQ specializes in configurable compliance frameworks that navigate multi-jurisdictional audit standards.
Supplier Quality Management Applications encompass software platforms that automate vendor qualification, performance monitoring, and non-conformance tracking through configurable workflows and real-time dashboards. These systems integrate CAPA methodologies, ISO 9001 documentation hierarchies, and risk-based sampling protocols to prevent defective inputs from entering production lines. Cloud-based deployment is outpacing on-premises installations as pharmaceutical end users prioritize remote audit capabilities and elastic compute for batch record analysis. Quality Control functionality leads application-type revenue, though Risk Assessment modules are expanding fastest among electronics manufacturers managing multi-tier Asian supply networks.
FDA 21 CFR Part 11 requirements shape validation protocols for pharmaceutical adopters, while EMA's GDP guidelines enforce traceability standards across European distribution chains. ISO 9001:2015 and IATF 16949 automotive mandates create baseline compliance thresholds that filter vendor eligibility in contract negotiations. Stakeholders must decide whether to build proprietary supplier data lakes or subscribe to networked platforms that aggregate cross-industry vendor risk intelligence.
Market Dynamics
Cloud-native audit architectures are compressing deployment cycles for pharmaceutical and aerospace buyers while fragmenting vendor competitive moats around integration depth rather than feature breadth.
Growth Catalysts
- EU MDR documentation mandates:European pharmaceutical manufacturers must maintain auditable supplier qualification records across device classes, forcing quality system upgrades that embed automated CAPA tracking and electronic batch record integration.
- Industrial IoT sensor proliferation:Automotive and electronics manufacturers in Germany's supplier corridor are deploying shop-floor data streams that feed real-time supplier scorecards, collapsing the latency between defect detection and vendor notification.
- Remote audit capabilities:Cloud-based platforms with video-verified inspection workflows are eliminating travel-dependent qualification processes, enabling Asian contract manufacturers to maintain European pharmaceutical supply chain eligibility without on-site presence.
Market Restraints
- Statistical process control talent scarcity:Enterprise deployments face collapsed implementation timelines as qualified engineers command premium compensation, stretching vendor professional services capacity and delaying customer go-live dates.
- Validation protocol rigidity:FDA 21 CFR Part 11 requirements impose documentation hierarchies that resist agile iteration, forcing pharmaceutical adopters into waterfall deployment patterns that lag industrial manufacturing upgrade cycles by 18-24 months.
- Legacy ERP integration friction:On-premises quality modules from incumbent procurement suites retain data gravity, creating switching costs that slow cloud-native platform displacement despite superior analytics capabilities.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical manufacturing:CDSCO's tightening GMP enforcement creates compliance urgency among domestic API producers lacking structured vendor qualification systems, opening greenfield deployment opportunities for configurable audit frameworks.
- AI-augmented risk scoring:Machine learning models trained on multi-industry non-conformance databases can predict supplier failure probability before physical inspection, enabling predictive intervention that reduces incoming quality control sampling costs.
- Networked vendor intelligence platforms:Cross-industry data cooperatives aggregating anonymized supplier performance metrics offer subscription-based risk intelligence that displaces proprietary due diligence costs for mid-market manufacturers.
Industry Challenges
- Multi-jurisdictional audit standard navigation:Quality teams must simultaneously satisfy ISO 9001:2015, IATF 16949 automotive mandates, and sector-specific pharmaceutical requirements, creating configuration complexity that strains platform flexibility.
- Shop-floor sensor integration complexity:Connecting heterogeneous industrial IoT devices to centralized quality databases requires protocol translation layers that introduce latency and data fidelity risks during real-time defect escalation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplier Quality Management Applications Market |
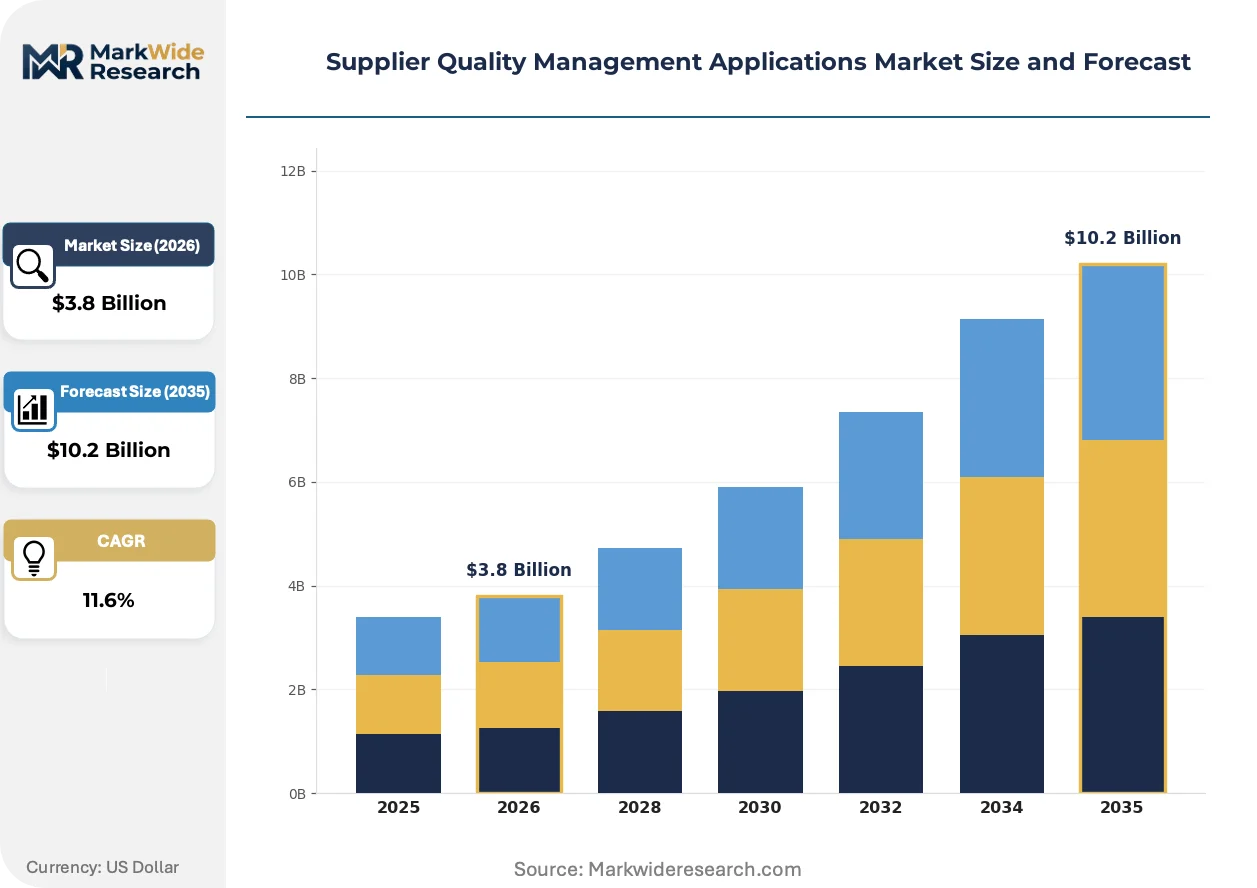
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Quality Control, Compliance Management, Supplier Audits, Risk Assessment Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Aerospace, Automotive, Electronics, Pharmaceuticals Feature: Document Management, Reporting & Analytics, Supplier Collaboration, Workflow Automation |
| Companies Covered | SAP, Oracle, IBM, Siemens, Dassault Systèmes, ETQ, Sparta Systems, MasterControl, Veeva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplier Quality Management Applications Market Evolving Landscape
Quality management platforms are converging with adjacent enterprise systems while regulatory digitization mandates accelerate architectural modernization across compliance-intensive verticals.
Microservices-based quality architectures are decomposing monolithic audit platforms into interoperable components that pharmaceutical manufacturers can deploy incrementally. Tier-1 suppliers in Germany's automotive corridor are adopting containerized CAPA modules that integrate with existing MES investments without full system replacement. This decomposition is compressing vendor lock-in durations and shifting procurement evaluation criteria toward API extensibility rather than feature checklists.
REACH substance traceability requirements are forcing electronics manufacturers to map multi-tier Asian supply networks for conflict mineral and restricted substance documentation. The regulation's downstream communication obligations cascade supplier qualification demands to tier-3 component vendors previously outside quality system scope. European OEMs are responding by mandating blockchain-anchored material declarations from high-risk supply chain nodes.
Buyer consolidation among pharmaceutical contract manufacturers is concentrating purchasing power and extending quality system requirements deeper into supplier bases. Large CDMOs are unbundling after-sales quality support from equipment procurement, creating standalone service contracts for ongoing compliance maintenance. This pattern is most visible in Ireland's pharmaceutical manufacturing cluster, where facility consolidation has reduced the number of independent quality system owners while expanding per-site vendor management complexity.
Supplier Quality Management Applications Market Segmentation
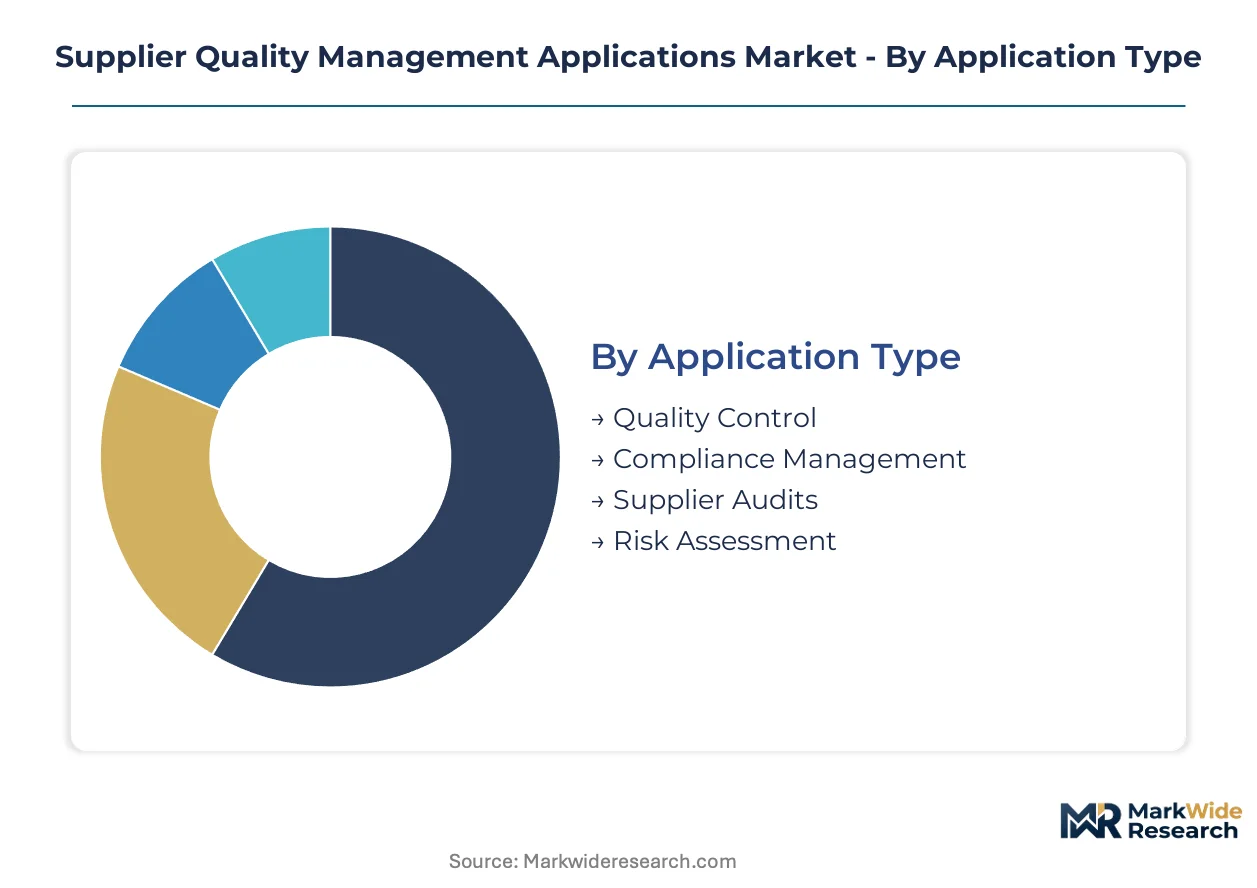
Regulatory fragmentation across FDA, EMA, and ISO jurisdictions forces buyers to select segments matching their validation burden and audit frequency. Deployment choices directly determine implementation timelines and recurring compliance costs.
Application Type:
FDA 21 CFR Part 11 and EU MDR documentation mandates create divergent functional requirements across pharmaceutical versus industrial manufacturing adopters.
- Quality Control:Modules automate incoming inspection protocols, AQL sampling, and non-conformance disposition through electronic batch record integration. Pharmaceutical manufacturers in Germany's supplier corridor deploy these systems to satisfy EMA GDP traceability requirements for high-risk APIs.
- Risk Assessment:Predictive algorithms score supplier failure probability using multi-tier network visibility and historical non-conformance data. Electronics manufacturers managing Asian supply chains favor this segment to navigate REACH substance traceability obligations across tier-3 component vendors.
- Compliance Management:Configurable frameworks map ISO 9001:2015, IATF 16949, and sector-specific requirements into unified audit trails.
- Supplier Audits:Cloud-native platforms with video-verified workflows eliminate travel-dependent qualification processes.
Established volume favors Quality Control; emerging adoption favors Risk Assessment.
Deployment Model:
Cost tier separation reflects customer IT maturity and validation protocol rigidity rather than feature differentiation.
- Cloud-Based:Elastic compute architectures support remote audit capabilities and batch record analysis without capital infrastructure. Aerospace manufacturers accelerating adoption prioritize these platforms for supplier scorecard analytics across distributed manufacturing networks.
- SaaS:Subscription pricing with pre-validated configurations compresses pharmaceutical go-live timelines despite FDA documentation requirements. Mid-market contract manufacturers in Ireland's pharmaceutical cluster favor this model to avoid waterfall deployment patterns.
- On-Premises:Legacy procurement suites retain data gravity in regulated environments with strict data residency requirements.
- Hybrid:Containerized CAPA modules integrate with existing MES investments without full system replacement.
Pharmaceutical validation constraints sustain On-Premises; remote audit demands expand Cloud-Based fastest.
End User:
Customer type determines integration complexity and regulatory exposure across the supplier qualification lifecycle.
- Pharmaceuticals:CDSCO's tightening GMP enforcement among Indian API producers creates greenfield demand for configurable audit frameworks. EU MDR documentation mandates force quality system upgrades embedding automated CAPA tracking.
- Automotive:Industrial IoT sensor proliferation in Germany's supplier corridor feeds real-time supplier scorecards from shop-floor data streams. IATF 16949 mandates create baseline compliance thresholds filtering vendor eligibility.
- Aerospace:Cloud-based audit platforms accelerate adoption as manufacturers prioritize remote qualification capabilities.
- Electronics:REACH downstream communication obligations cascade qualification demands to tier-3 Asian component vendors.
Regulatory intensity concentrates spend in Pharmaceuticals; sensor integration velocity favors Automotive.
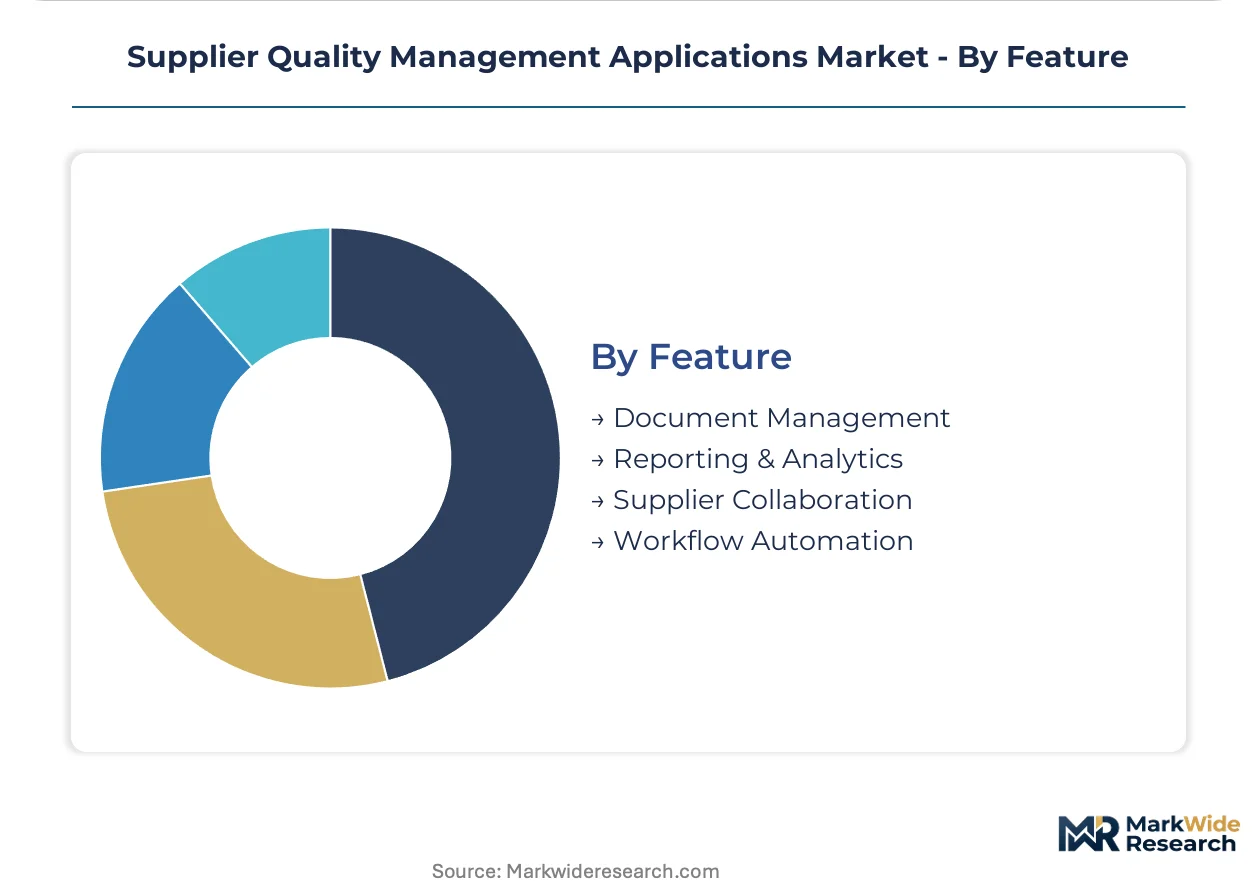
Feature:
Maturity gradients separate foundational documentation capabilities from advanced analytics and collaboration tools.
- Document Management:ISO 9001 documentation hierarchies and electronic signature workflows anchor compliance foundations. All regulated verticals require this capability as table stakes for vendor qualification.
- Workflow Automation:Configurable CAPA routing and escalation protocols reduce manual intervention in non-conformance processing. Pharmaceutical manufacturers prioritize this feature to compress deviation closure timelines under FDA scrutiny.
- Reporting & Analytics:Real-time dashboards consolidate supplier performance metrics across multiple audit standards.
- Supplier Collaboration:Portals enable tier-1 vendors to cascade quality requirements to sub-tier suppliers.
Universal need stabilizes Document Management; efficiency pressure elevates Workflow Automation most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Germany deploy supplier quality systems for EMA GDP traceability, while aerospace buyers in the United States prioritize cloud-native audit platforms for distributed supplier networks. Electronics producers across Asian manufacturing hubs emphasize REACH substance traceability for multi-tier component tracking.
United States
FDA 21 CFR Part 11 validation requirements shape pharmaceutical deployment patterns, forcing waterfall implementation timelines that lag industrial manufacturing by 18-24 months. Aerospace manufacturers accelerate cloud-based platform adoption to enable remote supplier qualification across distributed production networks. The Boston-Cambridge pharmaceutical cluster drives demand for electronic batch record integration and automated CAPA tracking systems.
Germany
Industrial IoT sensor proliferation feeds real-time supplier scorecards from shop-floor data streams in automotive production facilities. IATF 16949 automotive mandates create baseline compliance thresholds that filter vendor eligibility in contract negotiations. The Baden-Württemberg supplier corridor concentrates deployment of connected quality systems linking tier-1 automotive vendors to sub-tier component manufacturers.
India
CDSCO's tightening GMP enforcement creates compliance urgency among domestic API producers lacking structured vendor qualification systems. The country's national pharmaceutical regulator mandates auditable supplier documentation that accelerates quality system upgrades. Maharashtra's pharmaceutical manufacturing belt generates greenfield demand for configurable audit frameworks among contract manufacturers.
China
NMPA regulatory harmonization pressures domestic pharmaceutical manufacturers to adopt international-standard quality documentation hierarchies. The national medical products administration enforces traceability requirements that cascade through multi-tier Asian supply networks. The Yangtze River Delta electronics manufacturing hub deploys REACH substance tracking systems for conflict mineral documentation across tier-3 component vendors.
Japan
PMDA quality system regulations require pharmaceutical manufacturers to maintain validated supplier qualification records across device and drug production. The national pharmaceutical regulator's inspection protocols drive adoption of electronic signature workflows and automated deviation tracking. The Kansai industrial corridor integrates quality management platforms with existing MES investments through containerized CAPA modules.
Supplier Quality Management Applications Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the supplier quality management applications market. ERP-anchored vendors leverage procurement workflow integration to defend incumbent positions, while cloud-native specialists compete on deployment velocity and remote audit capabilities. Two strategic archetypes dominate: platform consolidators bundling quality modules into enterprise suites, and vertical specialists offering pre-validated configurations for regulated industries. M&A activity concentrates on sensor-to-scorecard integration capabilities, while strategic partnerships target multi-jurisdictional compliance framework coverage.
Among ERP-anchored platform providers, SAP and Oracle exemplify the integrated-suite archetype, leveraging existing install bases to embed quality modules into procurement workflows. Siemens occupies a position representing industrial IoT-native competitors, connecting shop-floor sensors directly to supplier performance analytics. ETQ anchors the specialist tier, exemplifying configurable compliance frameworks that navigate multi-jurisdictional audit standards without full enterprise system replacement.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| IBM |
| Siemens |
| Dassault Systèmes |
| ETQ |
| Sparta Systems |
| MasterControl |
| Veeva |
| Others |
Value Network & Pricing Analysis
Capacity utilization at cloud infrastructure providers draws from hyperscaler expansion in Germany's automotive corridor and India's pharmaceutical belt, compressing compute costs for SaaS deployments while anchoring price floors in on-premises legacy migrations. This scale dynamic concentrates supplier power among three platform archetypes and fragments margin capture across implementation services.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with annual SaaS tiers separating validated pharmaceutical configurations from standard industrial modules. Price differentiation rests on FDA 21 CFR Part 11 certification grade and geographic data residency requirements. Cost compression in mid-market segments intensifies because SAP and Oracle leverage existing ERP install bases to bundle quality modules at marginal incremental pricing. Contract manufacturers in Ireland's pharmaceutical cluster exhibit highest price sensitivity; aerospace OEMs managing distributed supplier networks show least.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore strains containerized delivery of on-premises server hardware to regulated pharmaceutical facilities in Germany and Japan. Software development concentrates in the United States, India, and Germany; cloud infrastructure draws from hyperscaler regions in Ireland, Frankfurt, and Mumbai. The supply chain hinges on single-source vulnerability in specialized statistical process control engineering talent. Distribution runs through direct enterprise sales with professional services bundling, supplemented by systems integrator channels in Asia-Pacific manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical compression in pharmaceutical capital expenditure, with EU MDR documentation mandates now forcing quality system refresh cycles that lagged during prior budget freezes.
For Market Incumbents: Consolidate sensor-to-scorecard integration capabilities through targeted capability acquisitions, defending against cloud-native entrants eroding integration moats. Deepen vertical integration into professional services capacity to offset statistical process control talent scarcity stretching implementation timelines. Prioritize certification investment in CDSCO-aligned audit frameworks for Indian pharmaceutical manufacturing expansion.
For New Entrants and Emerging Players: FDA 21 CFR Part 11 pre-validation fast-tracks open pharmaceutical white-space among mid-market contract manufacturers avoiding waterfall deployment patterns. Target underpenetrated Indian API producers facing CDSCO enforcement urgency with configurable compliance frameworks. Pursue channel partnerships with systems integrators serving Germany's automotive supplier corridor as primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical specialists offering pre-validated pharmaceutical configurations with 90%+ renewal rates. Long-term viability favors platforms with API extensibility enabling microservices decomposition rather than monolithic suite replacement. Watch for inflection in AI-augmented risk scoring adoption rates among electronics manufacturers as signal of platform differentiation value.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Scorecard Integration Acquisition | Connects Siemens shop-floor IoT directly to supplier performance analytics for automotive OEMs. |
| Pre-Validated SaaS Configuration Launch | Compresses pharmaceutical go-live timelines by embedding FDA 21 CFR Part 11 documentation hierarchies. |
| CDSCO-Aligned Audit Framework Partnership | Opens greenfield deployment among Indian API producers facing tightening GMP enforcement. |
| AI-Augmented Risk Scoring Module Development | Predicts supplier failure probability using REACH substance traceability data across tier-3 Asian networks. |
| Containerized CAPA Module Integration | Enables incremental deployment with existing MES investments in Japan's Kansai industrial corridor. |
Research Methodology
A standing panel of quality system directors, regulatory affairs leads at pharmaceutical manufacturers, automotive procurement officers, and cloud platform engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA inspection observation databases, IATF 16949 certification registries, and hyperscaler capex disclosures. Bottom-up deployment counts triangulated against top-down enterprise software spending estimates.
Consistency checks validated volume and value outputs against external benchmarks including ERP vendor quality module revenue disclosures and industrial IoT platform adoption surveys. The analytical framework modeled deployment model, end-user vertical, application type, and geographic regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic capacity utilization indicators and named regulatory enforcement calendars.
Decision-makers should treat outputs as directional under base assumptions of sustained EU MDR implementation timelines and stable cloud infrastructure pricing; material deviation in pharmaceutical capital expenditure cycles or trade lane disruption would warrant model refresh. Recalibration cycles align with material shifts in CDSCO enforcement intensity and REACH substance traceability expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Help Desk Software Market
Software & Services
Global Webinar Software Market
Software & Services
Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Scanning and Migration Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
Estate Management Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Construction Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Global Decision Support Software Market