
 Enterprise Data Observability Software Market | 2026-2036
Enterprise Data Observability Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Data Observability Software Market Insights
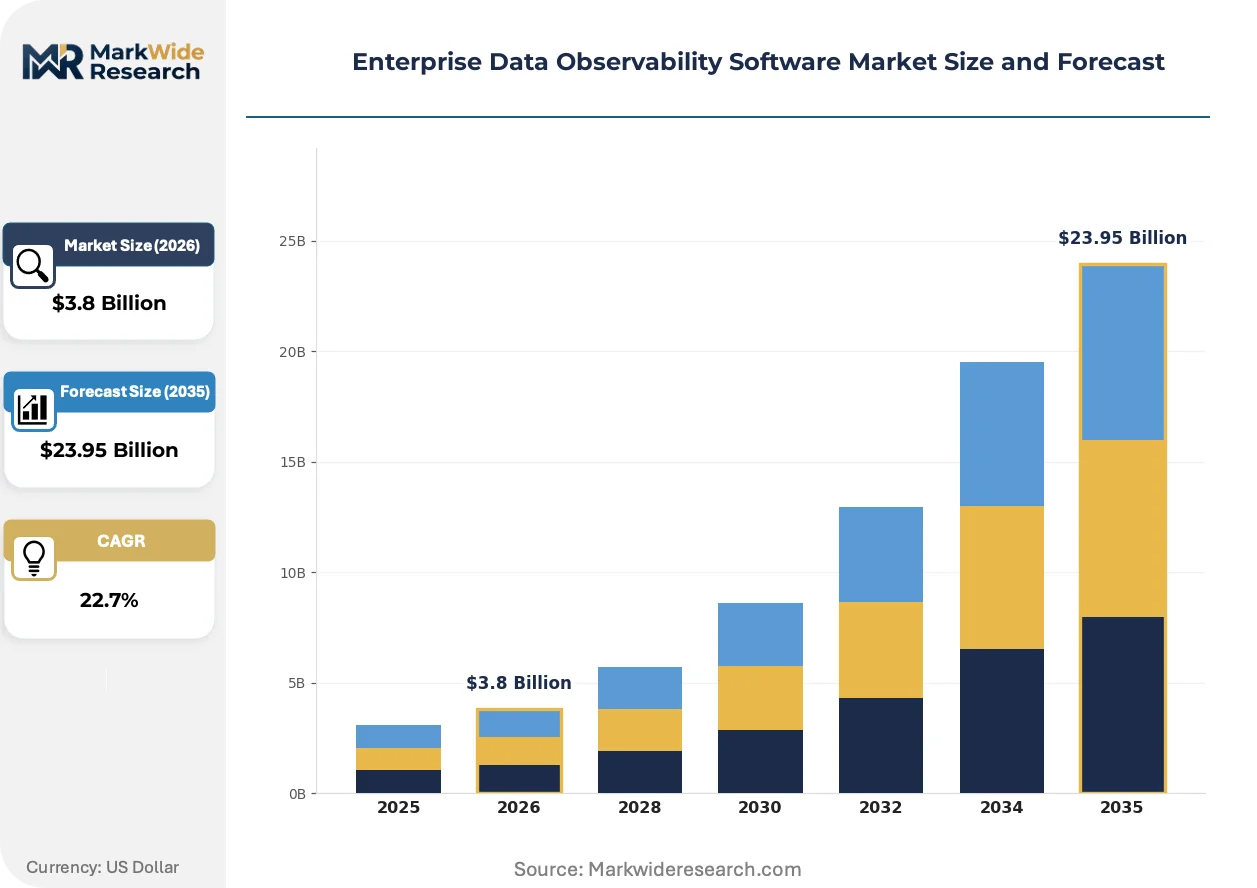
Platform licensing is narrowing as the dominant margin pool, shifting value from perpetual deployment fees toward recurring consumption-based arrangements. Datadog leverages deep integration across cloud-native environments to sustain pricing power in enterprise accounts. Splunk anchors its position through backward integration into security information and event management workflows. Monte Carlo differentiates via specialized data reliability engineering tooling that occupies a defensible niche in anomaly detection for modern data stacks.
Enterprise data observability software comprises integrated tooling that monitors data pipeline health, schema drift, and freshness thresholds across distributed architectures, typically operating through metadata extraction and automated lineage tracing to ensure analytical and operational systems consume trustworthy inputs. Cloud-native deployment leads current adoption curves as organizations abandon rigid on-premises configurations, while anomaly detection and root cause analysis represent the fastest-expanding solution types where margin pools concentrate due to technical complexity and scarcity of specialized engineering talent. Financial institutions and e-commerce platforms drive application-layer demand, particularly for fraud detection and customer insights use cases where data downtime carries direct revenue consequences.
FCC guidelines on telecommunications data integrity, EU GDPR requirements for data processing accountability, and SEC disclosure rules on material operational risks collectively shape vendor compliance tracking features and market access conditions across North America and Europe. ISO standards for information security management further constrain product architecture decisions, particularly for hybrid cloud configurations spanning regulated and unregulated jurisdictions. Stakeholders must weigh whether to build unified observability stacks or maintain fragmented point solutions as data mesh architectures proliferate across enterprise buyers.
Market Dynamics
Cloud-native deployment architectures are compressing sales cycles for data observability vendors while fragmenting procurement authority across data engineering and security teams. The shift from centralized IT gatekeepers to federated data mesh ownership models is rewriting contract structures and pricing benchmarks.
Growth Catalysts
- EU AI Act compliance mandates:Article 10 requirements for training data quality and bias monitoring are compelling financial institutions and healthcare systems to deploy automated lineage tracking and freshness validation across ML pipelines.
- Apache Iceberg and Delta Lake adoption:Open table formats enabling time-travel queries and schema evolution are expanding the addressable surface for metadata-driven observability tooling in modern data lakes.
- Fraud detection workload expansion:Real-time transaction monitoring systems at payment processors and neobanks require sub-minute anomaly detection on streaming pipelines, driving premium-tier consumption of root-cause analysis modules.
Market Restraints
- Specialized engineering talent scarcity:Data reliability engineering expertise concentrates in San Francisco, New York, and London metro areas, inflating implementation costs and elongating deployment timelines for mid-market buyers.
- Hybrid cloud configuration complexity:Jurisdictional data residency requirements force multi-region deployments that fragment observability telemetry and degrade correlation accuracy across sovereignty boundaries.
- Open-source alternative maturation:Projects like OpenLineage and Soda Core are capturing experimentation budgets and compressing willingness-to-pay for baseline schema monitoring and freshness alerting functionality.
Strategic Opportunities
- India's data localization mandates:RBI directives requiring domestic storage of payment system data are creating greenfield demand for compliant observability infrastructure among fintechs and scheduled commercial banks.
- AI/ML pipeline observability convergence:Unified platforms spanning feature store monitoring, model drift detection, and data quality validation are capturing expanded budgets from MLOps teams previously served by point solutions.
- Consumption-based pricing penetration:Metered billing tied to monitored table volume or pipeline execution count is lowering entry barriers for growth-stage SaaS companies and expanding addressable market depth.
Industry Challenges
- Legacy warehouse integration friction:On-premises Teradata and Oracle Exadata environments lack native metadata APIs, forcing expensive custom connector development and degrading time-to-value metrics in hybrid deployments.
- Alert fatigue and threshold calibration:Engineering teams struggle to tune sensitivity parameters across thousands of tables, leading to notification desensitization and delayed response to genuine incidents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Data Observability Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Native, Hybrid Cloud, Multi-Cloud Solution Type: Data Quality Monitoring, Anomaly Detection, Root Cause Analysis, Performance Management, Alerting, Compliance Tracking Application: Customer Insights, Fraud Detection, Supply Chain Analytics, Operational Efficiency, Risk Management End User: Financial Institutions, E-Commerce Platforms, Telecommunications Providers, Manufacturing Firms |
| Companies Covered | Datadog, Splunk, Dynatrace, New Relic, Monte Carlo, Acceldata, Bigeye, Soda, Informatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Data Observability Software Market Trends and Innovations
Automated root-cause analysis capabilities are migrating from premium add-ons to baseline expectations as data downtime costs become quantifiable at the revenue-line level. Vendors are racing to embed generative interfaces that compress incident investigation cycles.
Generative AI-powered natural language interfaces for incident investigation are rendering obsolete manual SQL querying and dashboard drilling as primary diagnostic workflows. Data platform teams at Fortune 500 retailers and insurers are piloting these tools for executive-facing downtime explanations. The compression of mean-time-to-resolution is shifting vendor differentiation from detection speed toward remediation automation.
The EU AI Act's risk-based classification system for automated decision-making is mandating auditable data provenance trails across high-risk applications including credit scoring and insurance pricing. Vendors are embedding compliance-ready lineage exports and bias detection modules to capture certification-driven procurement. German automotive manufacturers and French banking consortia represent the most advanced implementation cohorts.
Platform engineering teams are consolidating observability spend under unified FinOps frameworks that treat data pipeline reliability as a cost-center metric alongside compute and storage. Centralized procurement functions at US-based technology and healthcare enterprises are bundling data observability into broader cloud cost management mandates. This behavioral shift favors vendors with granular usage attribution and chargeback-ready reporting over those with opaque per-seat pricing.
Enterprise Data Observability Software Market Segmentation
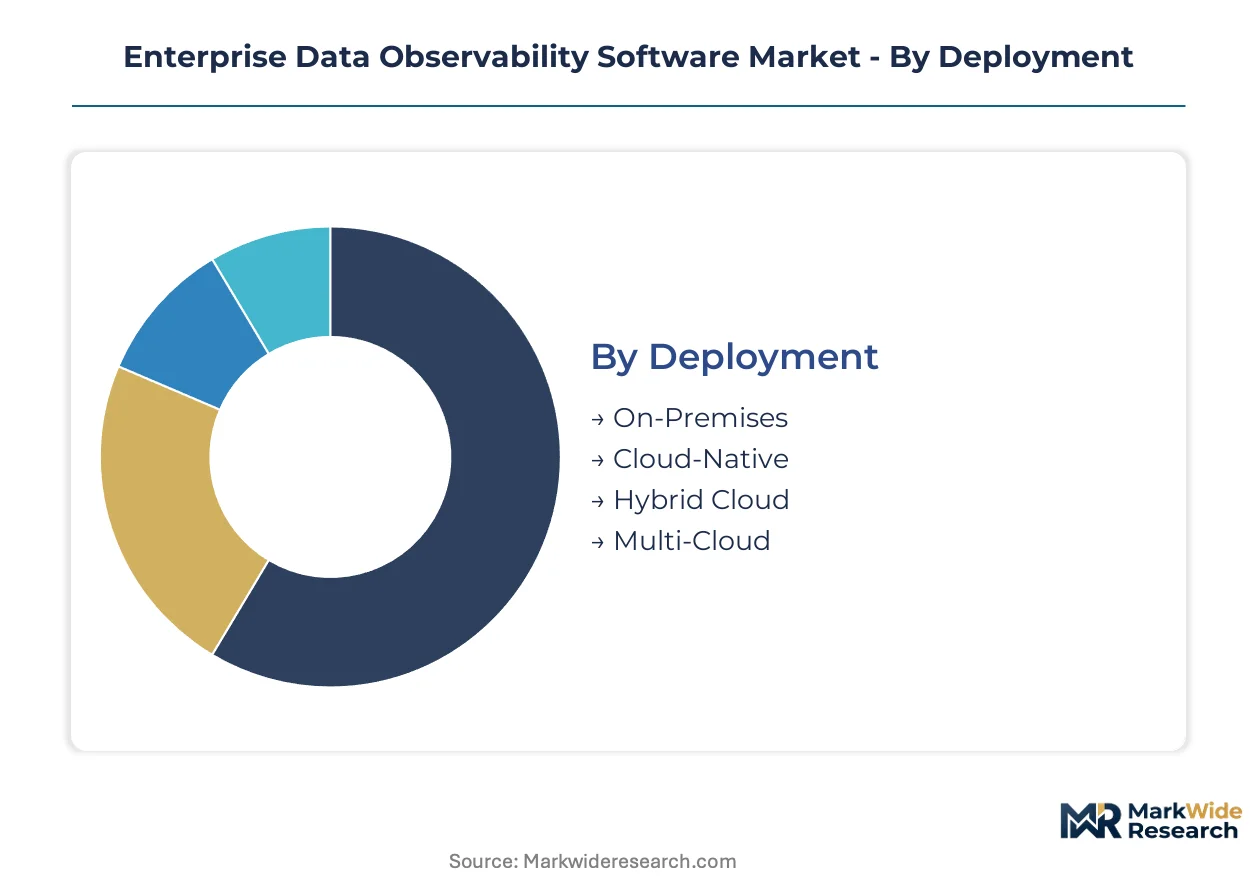
Enterprise data observability software segments reflect divergent procurement rhythms and technical maturity curves. Cloud-native deployments compress implementation cycles to weeks while legacy on-premises engagements extend across quarters. Solution providers must calibrate resource allocation across these heterogeneous velocity profiles.
Deployment:
Cloud-native configurations turn over fastest with monthly release cadences, while on-premises deployments cycle slowest through annual capital budgeting windows. Hybrid and multi-cloud arrangements occupy intermediate positions with quarterly review cycles.
- On-Premises:Dedicated infrastructure installations within enterprise data centers requiring hardware provisioning and network segmentation. Financial institutions in Germany and Switzerland maintain these configurations for sovereign data control under national banking supervisory requirements.
- Cloud-Native:Fully managed SaaS architectures leveraging container orchestration and serverless compute primitives. E-commerce platforms in the United States and United Kingdom prioritize these deployments for elastic scaling during promotional events.
- Hybrid Cloud:Split architectures preserving sensitive data on-premises while pushing analytics workloads to public cloud. Manufacturing firms across Japan and South Korea favor this model for operational technology isolation.
- Multi-Cloud:Distributed deployments across AWS, Azure, and GCP to mitigate vendor lock-in and optimize regional latency. Telecommunications providers in Australia and Canada adopt these strategies for resilience against single-provider outages.
On-Premises anchors the volume base while Cloud-Native gains share at the steepest rate.
Solution Type:
Cost tier stratification separates commodity alerting from premium root-cause analysis modules. Baseline functionality commands standard pricing while AI-augmented diagnostics extract premium multiples.
- Data Quality Monitoring:Automated validation of schema consistency, referential integrity, and business rule conformance across pipeline stages. Financial institutions in Singapore and Hong Kong deploy these tools for MAS and HKMA regulatory reporting accuracy.
- Anomaly Detection:Statistical and machine learning models identifying deviation patterns in time-series metrics and categorical distributions. Payment processors in Brazil and Mexico prioritize these capabilities for real-time fraud interception.
- Root Cause Analysis:Automated lineage traversal and impact propagation mapping to isolate failure origins. This segment extracts premium pricing due to specialized graph algorithms and scarce reliability engineering expertise.
- Performance Management:Latency tracking and throughput optimization for query execution and data movement operations. Retail analytics teams in France and Italy leverage these tools for customer dashboard responsiveness.
- Alerting:Threshold-based notification systems with multi-channel routing and escalation workflows. Mid-market SaaS companies in Spain and Netherlands standardize on these for operational baseline coverage.
- Compliance Tracking:Automated evidence collection and audit trail generation for regulatory examinations. Healthcare systems in Sweden and Denmark implement these for patient data governance under national privacy frameworks.
Alerting commands the widest installed base while Root Cause Analysis expands most quickly.
Application:
Customer-facing use cases generate revenue-line accountability that accelerates procurement decisions. Internal operational applications proceed through slower IT governance channels with extended security review cycles.
- Customer Insights:Real-time segmentation and behavioral prediction pipelines feeding personalization engines. Luxury retailers in Italy and United Kingdom invest heavily here for competitive differentiation in omnichannel experiences.
- Fraud Detection:Transaction scoring and identity verification workflows requiring sub-second latency with absolute accuracy. Neobanks across Nigeria and Kenya deploy these for mobile money protection against synthetic identity attacks.
- Supply Chain Analytics:Inventory optimization and demand forecasting across multi-tier supplier networks. Automotive manufacturers in Germany and Czech Republic depend on these for just-in-time production coordination.
- Operational Efficiency:Internal process automation and resource utilization monitoring with cost-center metrics. Logistics operators in Poland and Hungary adopt these for fleet and warehouse optimization.
- Risk Management:Credit exposure quantification and market stress testing for regulatory capital calculations. Insurance groups in Switzerland and Bermuda leverage these for solvency compliance and catastrophe modeling.
Fraud Detection concentrates the highest per-deployment spend while Customer Insights shows the steepest expansion trajectory.
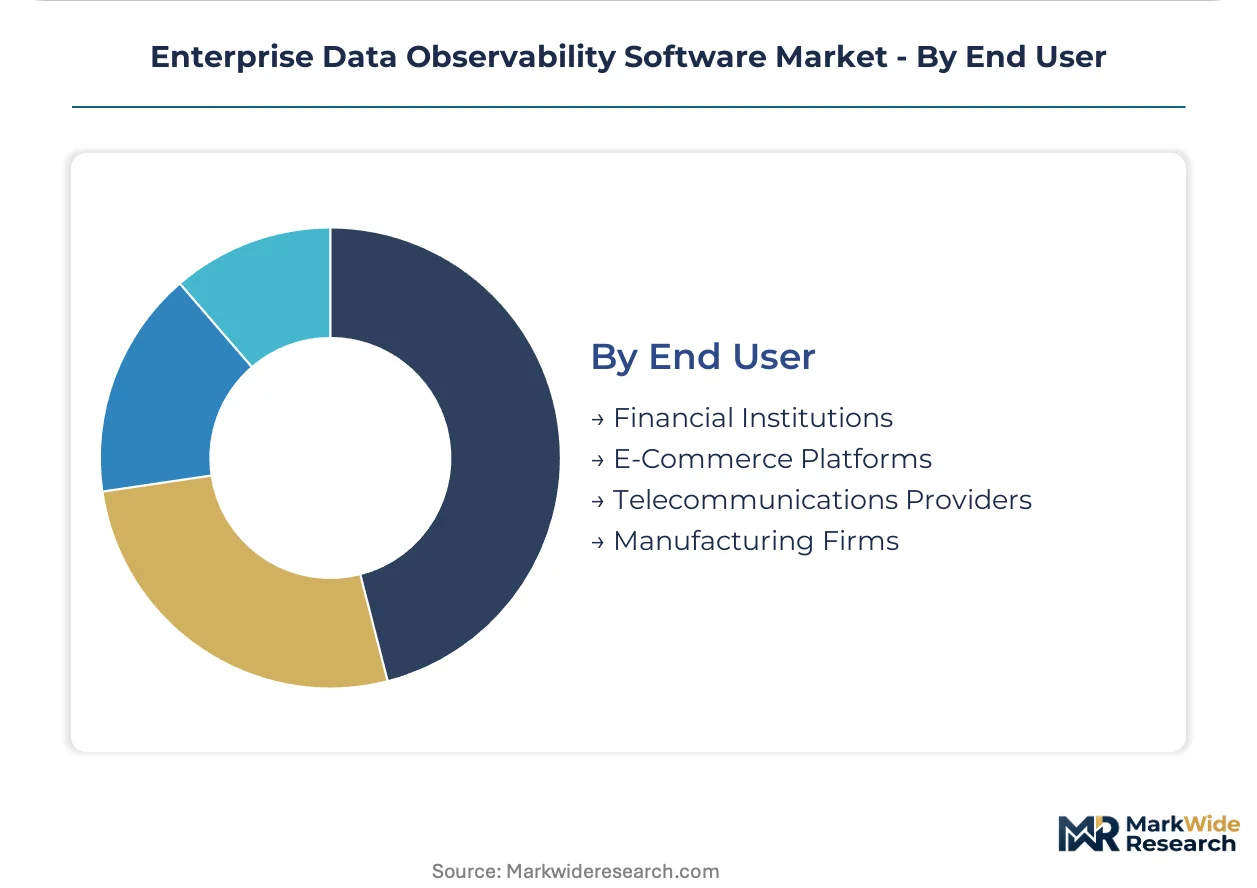
End User:
Financial institutions maintain the most mature procurement functions with dedicated data reliability engineering teams. Manufacturing firms represent the newest entrants with nascent observability practices and extended implementation timelines.
- Financial Institutions:Banks, insurers, and asset managers with stringent regulatory requirements and complex data lineage demands. Institutions across the United States, United Kingdom, and Singapore drive standard-setting for audit-ready observability architectures.
- E-Commerce Platforms:Digital retailers and marketplace operators with peak-load volatility and real-time personalization requirements. Companies in China, South Korea, and India prioritize these investments for festival-season reliability.
- Telecommunications Providers:Network operators managing subscriber data and service quality metrics across distributed infrastructure. Operators in Germany, Japan, and Australia lead adoption for 5G network slicing observability.
- Manufacturing Firms:Industrial producers integrating operational technology data with enterprise systems for predictive maintenance. German and Japanese automotive and electronics manufacturers represent the vanguard of this segment.
Financial Institutions anchor current revenue concentration while Manufacturing Firms present the largest untapped expansion surface.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States buyers prioritize cloud-native deployment velocity, while German and Japanese purchasers emphasize sovereign data control and hybrid architectures. This split shapes vendor product roadmaps and go-to-market investments.
United States
Financial institutions and e-commerce platforms in New York and San Francisco drive premium-tier demand for real-time anomaly detection on streaming pipelines. SEC disclosure rules on material operational risks compel audit-ready observability architectures. The San Francisco Bay Area concentrates data reliability engineering talent and venture-backed observability startups.
Germany
Automotive manufacturers and banking consortia in Bavaria and Baden-Württemberg deploy lineage tracking for EU AI Act compliance on automated decision-making systems. The national banking supervisory authority enforces strict data residency requirements for credit scoring workflows. Stuttgart-based automotive groups lead implementation of MLOps observability for predictive maintenance.
United Kingdom
Luxury retailers and insurers in London prioritize customer insights pipelines with sub-second freshness validation. GDPR accountability requirements shape procurement specifications for audit trail generation. The City of London financial district anchors demand for fraud detection observability among payment processors and neobanks.
India
Fintechs and scheduled commercial banks in Mumbai and Bangalore respond to RBI data localization mandates with greenfield observability infrastructure. The central bank's domestic storage requirements for payment system data create compliance-driven procurement windows. Bangalore's technology corridor hosts rapid deployment of cloud-native monitoring for UPI transaction pipelines.
Japan
Manufacturing firms in the Chubu region and telecommunications operators in Tokyo favor hybrid cloud configurations for operational technology isolation. METI industrial data governance guidelines encourage metadata-driven quality monitoring across supplier networks. Nagoya-based automotive electronics producers integrate observability into predictive maintenance systems.
Enterprise Data Observability Software Market Competitive Landscape
Capability concentration sits with specialized data reliability engineering vendors; scale advantage sits with broad observability incumbents with established enterprise distribution. The market structures around three tiers: cloud-native specialists, backward-integrated security platforms, and legacy data management incumbents. Dominant competitive moves include strategic partnerships with cloud hyperscalers and portfolio diversification into MLOps observability.
Within the specialized tier, Monte Carlo and Acceldata occupy positions defined by deep tooling for anomaly detection and data reliability engineering. Datadog and Splunk anchor the scale-driven segment, with the former exemplifying cloud-native integration density and the latter representing backward integration into security workflows. These groupings reflect divergent bets on whether data observability converges with general infrastructure monitoring or remains a distinct purchasing category.
| Leading Market Players |
|---|
| Datadog |
| Splunk |
| Dynatrace |
| New Relic |
| Monte Carlo |
| Acceldata |
| Bigeye |
| Soda |
| Informatica |
| Others |
Pricing and Supply Chain Analysis
EU AI Act Article 10 compliance deadlines for training data quality monitoring determine both the premium tier spreads for automated lineage tracking and the geographic shape of vendor supply chains as engineering talent concentrates in compliance-ready jurisdictions. Financial institutions facing these mandates absorb pricing premiums while mid-market buyers retreat to open-source alternatives.
Pricing Analysis
Long-term enterprise subscription contracts dominate the pricing architecture for Fortune 500 deployments, though consumption-based metered billing gains traction among growth-stage SaaS companies. Price differentiation separates audit-ready compliance tiers from baseline schema monitoring, with certification against ISO 27001 and SOC 2 Type II anchoring premium positioning. Pricing pressure stems from open-source alternatives like OpenLineage capturing experimentation budgets and compressing willingness-to-pay for standard alerting functionality. Mid-market SaaS companies exhibit the highest price sensitivity, while financial institutions under SEC disclosure rules on material operational risks demonstrate the lowest.
Supply Chain Analysis
Tariff exposure between the United States and China on cloud infrastructure hardware fragments observability telemetry routing and inflates multi-region deployment costs for hybrid configurations. Engineering talent supply concentrates in the United States, the United Kingdom, and India, with San Francisco, London, and Bangalore anchoring implementation service delivery. The vendor ecosystem draws from specialized reliability engineering expertise, open-source community contributions, and hyperscaler partnership programs. Single-source vulnerability sits with concentrated cloud compute dependencies for SaaS delivery. Distribution runs through direct enterprise sales teams, cloud marketplace listings, and systems integrator channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enterprise data observability market represents an early-cycle expansion story as EU AI Act compliance mandates force regulated industries to deploy automated lineage tracking for the first time, creating greenfield procurement windows among previously underserved mid-market buyers.
For Market Incumbents: Pre-empt open-source substitution by embedding generative AI-powered natural language interfaces into baseline product tiers before point solutions capture the diagnostic workflow automation layer. Fortify backward integration into security information and event management workflows to defend against cloud-native specialists encroaching on enterprise accounts. Prioritize certification investment against EU AI Act technical standards to maintain pricing power in European financial services procurement cycles. For New Entrants and Emerging Players: Establish a beachhead in India's fintech sector where RBI data localization mandates create compliance-driven demand for greenfield observability infrastructure among neobanks and payment processors. Target manufacturing firms in Japan and Germany as the most penetrable vertical given nascent observability practices and extended implementation timelines that favor agile vendors. Pursue a cloud-native deployment-first go-to-market angle to compress sales cycles and bypass legacy warehouse integration friction that slows incumbent delivery. For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape by elevating vendors with pre-built compliance modules and audit-ready lineage exports above generalist infrastructure monitoring platforms. Long-term viability centers on convergence with MLOps observability as feature store monitoring and model drift detection budgets consolidate under unified platforms. Target acquisition profiles favor specialized data reliability engineering vendors with defensible anomaly detection IP and European banking reference accounts. Monitor Apache Iceberg and Delta Lake adoption curves as the critical signal for metadata-driven tooling demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Hyperscalers | Deep AWS, Azure, and GCP native embedding accelerates procurement velocity among cloud-first enterprises. |
| Acquisition of Specialist Firm | Targeted data reliability engineering boutiques add graph-based root-cause analysis capabilities to broader portfolios. |
| Product Launch: MLOps Convergence | Unified feature store monitoring captures expanded budgets from data science teams previously served by point solutions. |
| Geographic Expansion: India Compliance | RBI-mandated domestic storage requirements for payment data create localized infrastructure deployment opportunities. |
| Strategic Partnership: Systems Integrator | Channel alliances with Accenture and Deloitte accelerate enterprise sales cycles and implementation service revenue. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CTOs, platform engineers, IT procurement officers, and data reliability engineering leads. Primary fieldwork captured deployment timelines, pricing benchmarks, and vendor selection criteria across financial services, e-commerce, and manufacturing verticals. Secondary validation drew from App Annie/Sensor Tower usage data, cloud marketplace transaction records, and open-source project contribution analytics. Bottom-up sizing of monitored pipeline volumes and top-down triangulation against enterprise software spend categories anchored market estimates.
Forecast assumptions held cloud-native deployment velocity and EU AI Act enforcement timelines fixed while varying open-source adoption rates and hybrid cloud configuration complexity across the projection horizon. Segmentation modeling spanned deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derived from pipeline execution volume growth rates and consumption-based pricing penetration curves. Industry-specific inputs included Apache Iceberg table format adoption trajectories and RBI data localization compliance deadlines.
Sensitivities concentrate around open-source project maturation timelines, hyperscaler partnership exclusivity shifts, and EU AI Act delegated act publication schedules. Forecasts reflect documented assumptions on talent scarcity persistence and cloud infrastructure cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global OKR Software Market
Software & Services
Sales Enablement Software Market
Software & Services
Global Mobile Middleware Market
Software & Services
Balance Sheet Management Software Market
Software & Services
Recruitment Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Global Spa and Salon Software Market
Software & Services
Preschool Education Software Market
Software & Services
Global Call Center Software Market
Software & Services
Construction Suites Software Market
Software & Services
Output Management Software Market
Software & Services
Global Driving School Software Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Middle-East Virtual Data Room Market