
 Global Funeral Home Software Market | 2026-2036
Global Funeral Home Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Funeral Home Software Market Foresight
Chain service providers is hardening as the dominant end-user vertical, displacing independent mortuaries as the primary demand source for integrated platforms. Parting Pro leverages cloud-native architecture to serve distributed operator networks. Halcyon Death Care Management Solutions anchors its position through compliance-tracking specialization across US state jurisdictions. Passare competes on service-arrangement workflow depth, particularly for cremation-heavy operations.
Funeral home software denotes digital platforms that manage death-care operations including case management, scheduling, billing, regulatory documentation, and memorial coordination through centralized databases with role-based access controls. These systems automate vital-statistics reporting to state and federal authorities while integrating with cemetery plot databases and cremation equipment logs. Cloud-based deployment leads solution uptake due to lower capital requirements and remote accessibility for mobile funeral directors. Scheduling and planner modules capture disproportionate margin pools as operators prioritize resource optimization across limited viewing rooms and staff rosters. Compliance tracking represents the fastest-growing use case as jurisdictions tighten audit requirements for pre-need trust accounting and environmental permits.
FDA oversight of medical examiner data interoperability, HIPAA privacy rules for decedent health records, and state-level cemetery and funeral service boards collectively shape product development priorities and vendor certification requirements. The EU GDPR and emerging state privacy laws in California and Virginia add cross-border data governance complexity for platforms serving multinational chains. Stakeholders must monitor regulatory divergence between federal health-data standards and fragmented state licensing rules when evaluating platform scalability.
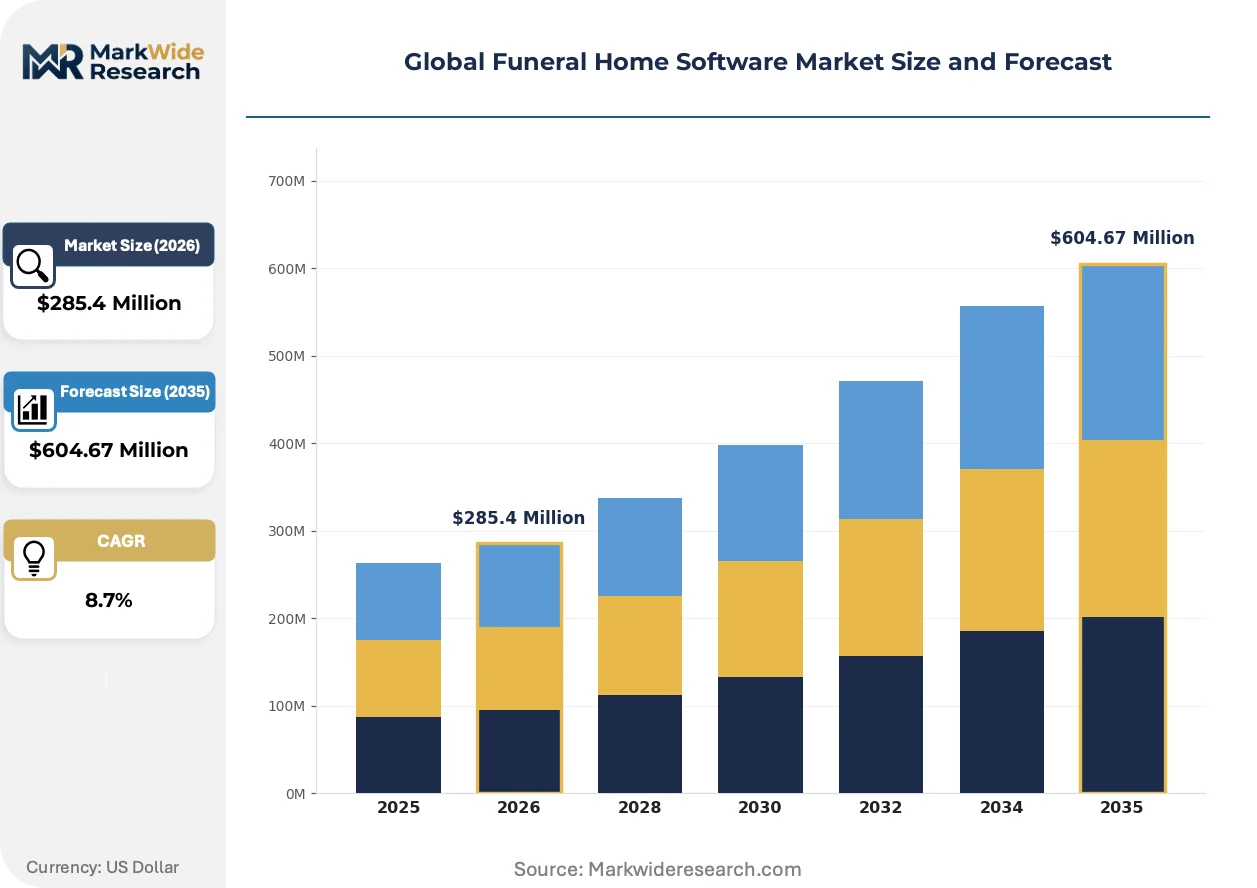
Market Dynamics
Cloud migration is compressing replacement cycles across funeral home operations as HIPAA-aligned data governance mandates force legacy system retirements. Multi-location chains now demand unified platforms that centralize compliance tracking across disparate state jurisdictions.
Growth Catalysts
- HIPAA Privacy Rules:US federal mandates for decedent health record protection are accelerating platform upgrades at independent mortuaries previously running on-premises systems.
- Pre-need Trust Accounting:State-level audit tightening for funeral service financial reserves is driving demand for automated compliance modules with real-time reporting.
- Cremation Equipment Integration:Hardware-software convergence with crematory logs and environmental permit tracking is expanding platform utility beyond traditional case management.
Market Restraints
- Data Migration Costs:Decades of paper-based vital statistics records and fragmented cemetery plot databases impose heavy conversion burdens on smaller operators.
- State Licensing Fragmentation:Disparate funeral service board requirements across US jurisdictions force vendors to maintain multiple certification tracks, elevating development overhead.
- Substitute Solutions:Generic practice management platforms adapted from veterinary or dental verticals compete on price for basic scheduling and billing functions.
Strategic Opportunities
- Australia Procurement Activity:Rising platform adoption among independent funeral directors in Sydney and Melbourne creates entry points for cloud-native vendors with cremation-heavy workflow specialization.
- GDPR-Aligned Export:EU data governance standards applicable to UK and Irish operations enable product line extensions into European markets with harmonized compliance architectures.
- Mobile Director Access:Smartphone-native interfaces for remote case intake and family communication represent underserved functionality at mid-market chains.
Industry Challenges
- Funeral Director Technology Fluency:Workforce demographics skew toward long-tenured staff with limited exposure to cloud-based operational tools, slowing rollout adoption.
- Legacy System Integration:Proprietary cemetery management databases and state vital statistics reporting portals require custom API development, extending implementation timelines.
- Environmental Permit Tracking:Evolving EPA and state-level cremation emission standards demand continuous platform updates to maintain audit-ready documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Funeral Home Software Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution Offering: Scheduling & Planner, Accounting & Billing, Customer Relationship Management, Reporting & Analytics, Inventory Management Use Case: Cremation Management, Obituary Publishing, Document Management, Service Arrangement, Compliance Tracking End User: Independent Mortuaries, Chain Service Providers, Memorial Parks, Cemetery Operators |
| Companies Covered | Parting Pro, Cemify, Plotbox, The Professional Programs, TerraPro, Osiris, Passare, Obit, Halcyon Death Care Management Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Funeral Home Software Market Shifts & Advancements
Digital infrastructure is rewiring how death-care operators coordinate across distributed locations, with mobile accessibility and automated compliance emerging as primary competitive differentiators.
Cloud-native architecture is rewriting deployment economics for multi-location funeral chains. These platforms eliminate on-premises server maintenance while enabling real-time data synchronization between branch offices and centralized compliance dashboards. Large operators in Texas and Florida are consolidating previously siloed location systems onto single instances, compressing IT staffing requirements by half.
GDPR and emerging state privacy laws in California and Virginia are reshaping cross-border data governance for multinational chains. Platforms must now maintain dual compliance tracks for EU decedent record handling and US state-level variations, elevating vendor certification complexity. Australian operators with UK parent companies face the steepest architecture demands as they navigate overlapping regulatory frameworks.
Subscription pricing models are displacing perpetual license structures across mid-market procurement. Independent mortuaries in the UK and Australia increasingly favor monthly SaaS arrangements that bundle software, support, and automatic regulatory updates, shifting capital expenditure to operational budgets. This preference is most pronounced among cremation-focused operators with thinner margins than traditional full-service funeral homes.
Global Funeral Home Software Market Segmentation
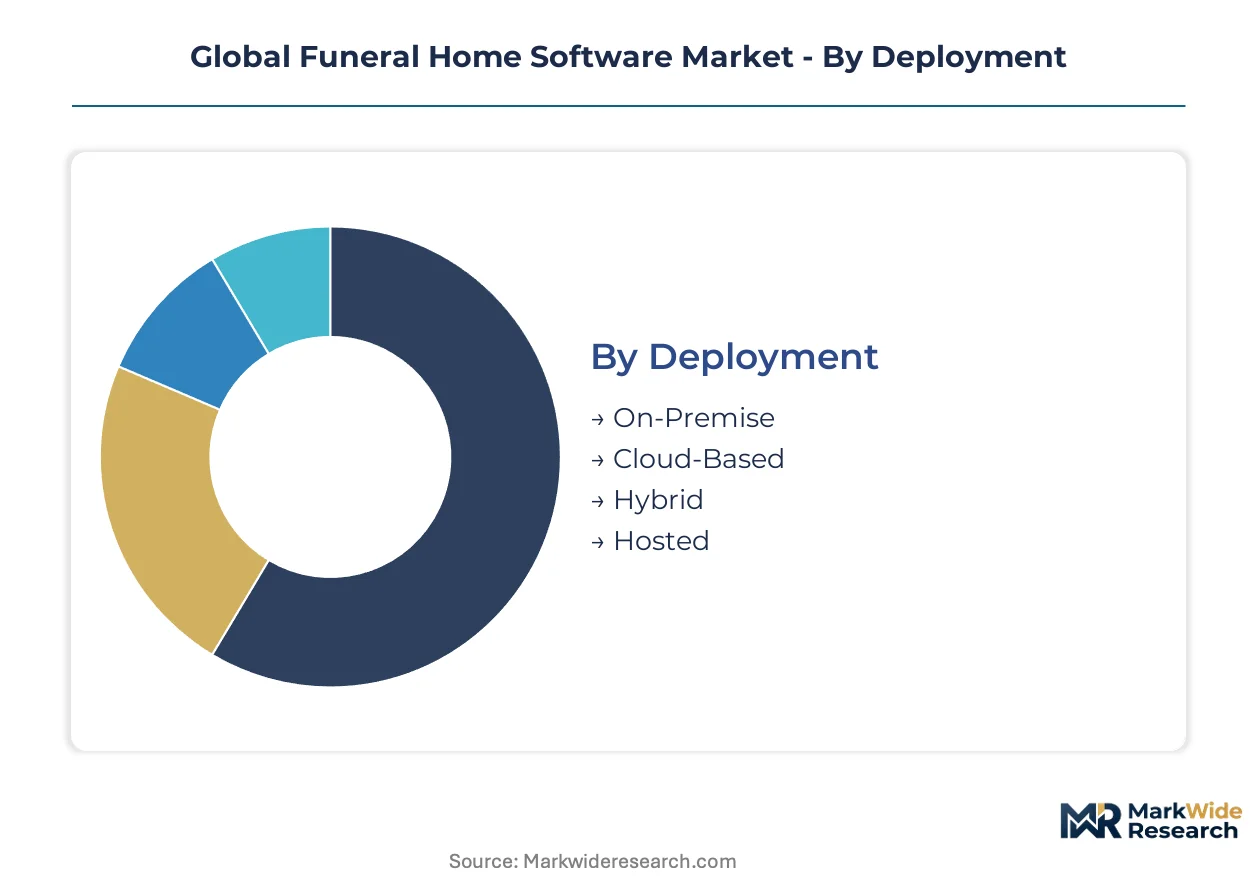
Funeral home software vendors architect product lines around distinct operational pain points, from HIPAA compliance mandates to cremation workflow automation. Deployment models and solution depth determine pricing tiers and customer acquisition costs across independent mortuaries and consolidated chains.
Deployment:
Supply concentration favors cloud-native architectures as multi-location chains demand centralized data governance without on-premises infrastructure burdens.
- On-Premise:Legacy server installations persist at independent mortuaries with limited IT staffing and strict local data custody preferences. Operators in rural US jurisdictions and parts of Germany favor these systems for direct control over decedent health records under HIPAA and GDPR interpretations.
- Cloud-Based:Browser-accessible platforms with automatic regulatory updates dominate procurement at funeral chains with five or more locations. Australian operators in Sydney and Melbourne are migrating rapidly to these systems for mobile director access and real-time synchronization between branch offices.
- Hybrid:Split architectures keep sensitive pre-need trust data on local servers while pushing scheduling and obituary functions to cloud instances. Mid-market chains in Texas and Florida deploy this model to balance compliance audit readiness with operational flexibility.
- Hosted:Third-party managed infrastructure offloads server maintenance while preserving dedicated tenant isolation. Cemetery operators with limited technical staff favor this deployment for predictable monthly costs without cloud multi-tenancy exposure.
Cloud-based deployments absorb the bulk of installed capacity; hybrid configurations are expanding most quickly among compliance-sensitive mid-market operators.
Solution Offering:
Margin pools concentrate in modules that automate regulatory documentation and resource optimization across constrained funeral home assets.
- Scheduling & Planner:Room and staff allocation systems with conflict detection and family preference tracking. Chains in the US Sun Belt prioritize these tools for maximizing viewing room utilization during peak demand periods.
- Accounting & Billing:Pre-need trust accounting with automated state audit reporting and installment payment processing. US state funeral board mandates for financial reserve transparency drive replacement demand at independent mortuaries.
- Customer Relationship Management:Decedent family communication portals with digital arrangement collaboration and grief resource libraries. UK operators leverage these systems for at-need and pre-need conversion tracking.
- Reporting & Analytics:Operational dashboards consolidating case volume, revenue per service, and compliance status across branch networks. Large chains deploy these for regional performance benchmarking and acquisition target evaluation.
- Inventory Management:Casket, urn, and memorial product tracking with supplier integration and automated reorder triggers. Cremation-heavy operators in Australia favor tight inventory control for urn and scattering tube assortments.
Scheduling and planner modules capture the deepest margin penetration; compliance-integrated accounting functions are climbing the fastest as state audit requirements tighten.
Use Case:
Workflow automation priorities diverge between cremation-focused operators and traditional full-service funeral homes with burial-centric service models.
- Cremation Management:Crematory equipment integration with environmental permit logging and chain-of-custody documentation. Operators in California and Washington state prioritize EPA-aligned emission tracking modules.
- Obituary Publishing:Multi-platform syndication to newspaper websites, social media, and memorial tribute portals with guestbook management. Independent mortuaries value streamlined obituary workflows for competitive differentiation against national brands.
- Document Management:Centralized storage for death certificates, burial permits, and veteran benefit applications with role-based access controls. HIPAA compliance mandates elevate this use case at US operators handling hospital-originated decedent cases.
- Service Arrangement:Digital selection of caskets, flowers, music, and catering with real-time pricing and contract generation. Chains standardize these workflows across locations to ensure consistent family experience and margin protection.
- Compliance Tracking:Automated monitoring of pre-need trust balances, state licensing renewals, and environmental audit deadlines. This function is expanding fastest as jurisdictions multiply reporting requirements for funeral service financial reserves.
Service arrangement tools absorb the bulk of user interaction time; compliance tracking is gaining share fastest amid regulatory complexity.
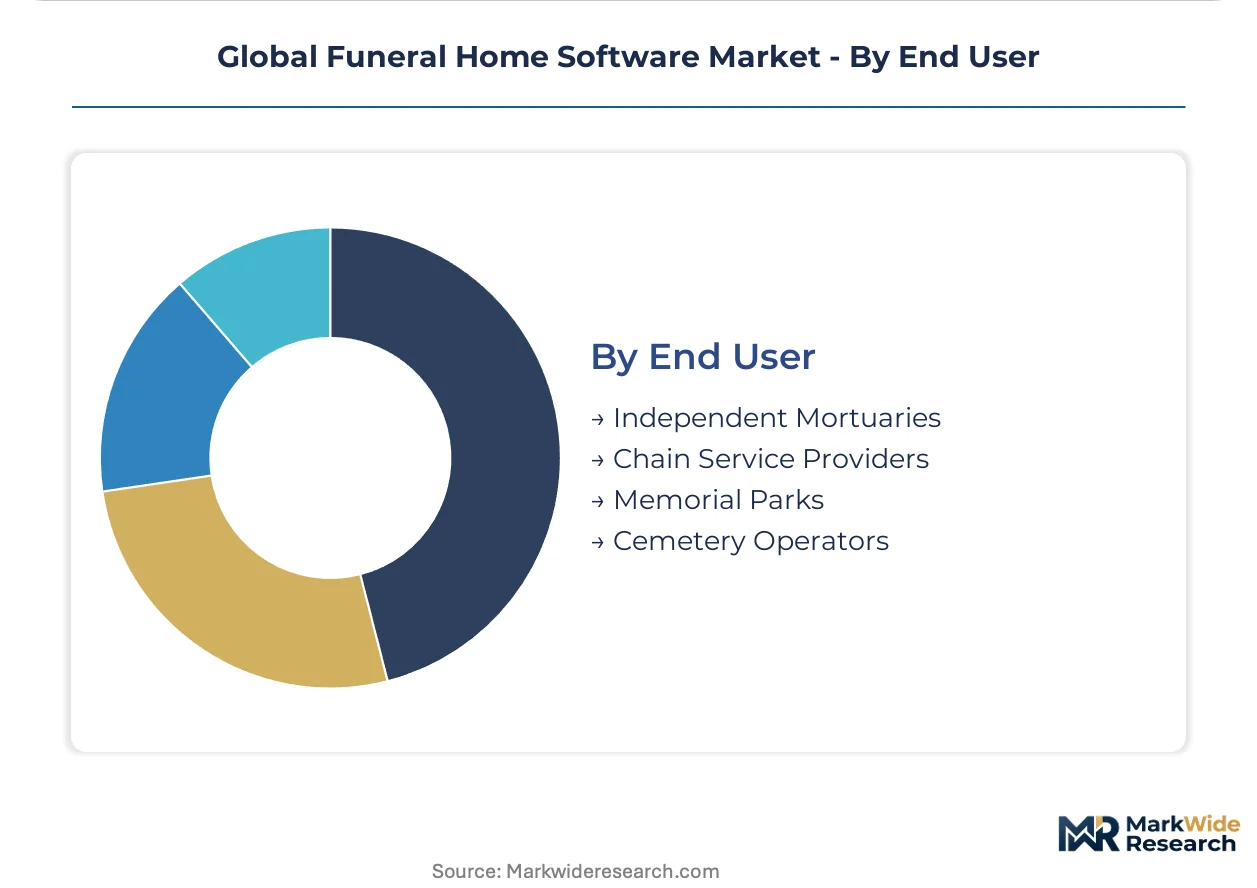
End User:
Customer scale determines platform complexity requirements, from single-location independents to multinational chains with unified multi-jurisdiction compliance needs.
- Independent Mortuaries:Single-location family-owned operations with 5-15 annual staff and limited IT budgets. These operators in the UK and Australia are shifting from paper-based systems to SaaS platforms as founders retire and successor generations demand digital workflows.
- Chain Service Providers:Regional and national consolidators operating 10-200+ locations with centralized procurement and compliance oversight. US-based chains in Texas, Florida, and California drive demand for unified platforms with real-time cross-location data synchronization.
- Memorial Parks:Cemetery-grounds operators with integrated funeral home facilities requiring plot inventory management and perpetual care trust accounting. These end users in Japan and South Korea prioritize geomancy-aligned plot selection tools and digital grave location mapping.
- Cemetery Operators:Standalone burial ground managers without on-site funeral services, focused on deed tracking, maintenance scheduling, and pre-need sales. Municipal and religious cemetery authorities in Germany and Italy favor specialized platforms over funeral-home-anchored suites.
Chain service providers command the largest platform deployments by location count; independent mortuaries represent the steepest expansion trajectory as cloud accessibility lowers adoption barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in Texas and Florida concentrate chain funeral home headquarters, accelerating cloud procurement across multi-location operators. Tax incentives for technology adoption in these zones compress implementation timelines for compliance-heavy platforms.
United States
HIPAA-aligned data governance mandates force legacy system retirements at independent mortuaries across Texas and Florida. The FDA oversees medical examiner data interoperability standards that shape vendor certification requirements. Dallas-Fort Worth anchors the largest concentration of chain service providers deploying unified platforms across state lines.
United Kingdom
GDP R-aligned data architectures enable product extensions from UK operators into Irish markets with harmonized compliance tracks. The CNIL-influenced UK data protection framework governs decedent record handling for multinational chains. London and Manchester drive procurement activity among independent funeral directors shifting from paper-based systems.
Australia
TGA-aligned privacy standards and rising cremation rates create demand for environmental permit tracking modules. State-level funeral service board mandates in New South Wales and Victoria tighten audit requirements for pre-need trust accounting. Sydney and Melbourne operators favor SaaS arrangements with mobile director access for distributed branch networks.
Germany
GDPR strict interpretations and local data custody preferences sustain on-premise installations at independent mortuaries in rural jurisdictions. The country's national data protection regulator enforces decedent health record handling standards that exceed EU baselines. Bavaria and North Rhine-Westphalia host specialized cemetery management platforms serving municipal burial authorities.
Japan
METI technology adoption incentives and aging demographics expand digital platform demand at memorial parks with integrated funeral facilities. JIS standards govern data interoperability between cemetery plot databases and municipal vital statistics portals. Tokyo and Osaka metropolitan areas concentrate procurement of geomancy-aligned plot selection tools and digital grave location mapping systems.
Global Funeral Home Software Market Competitive Landscape
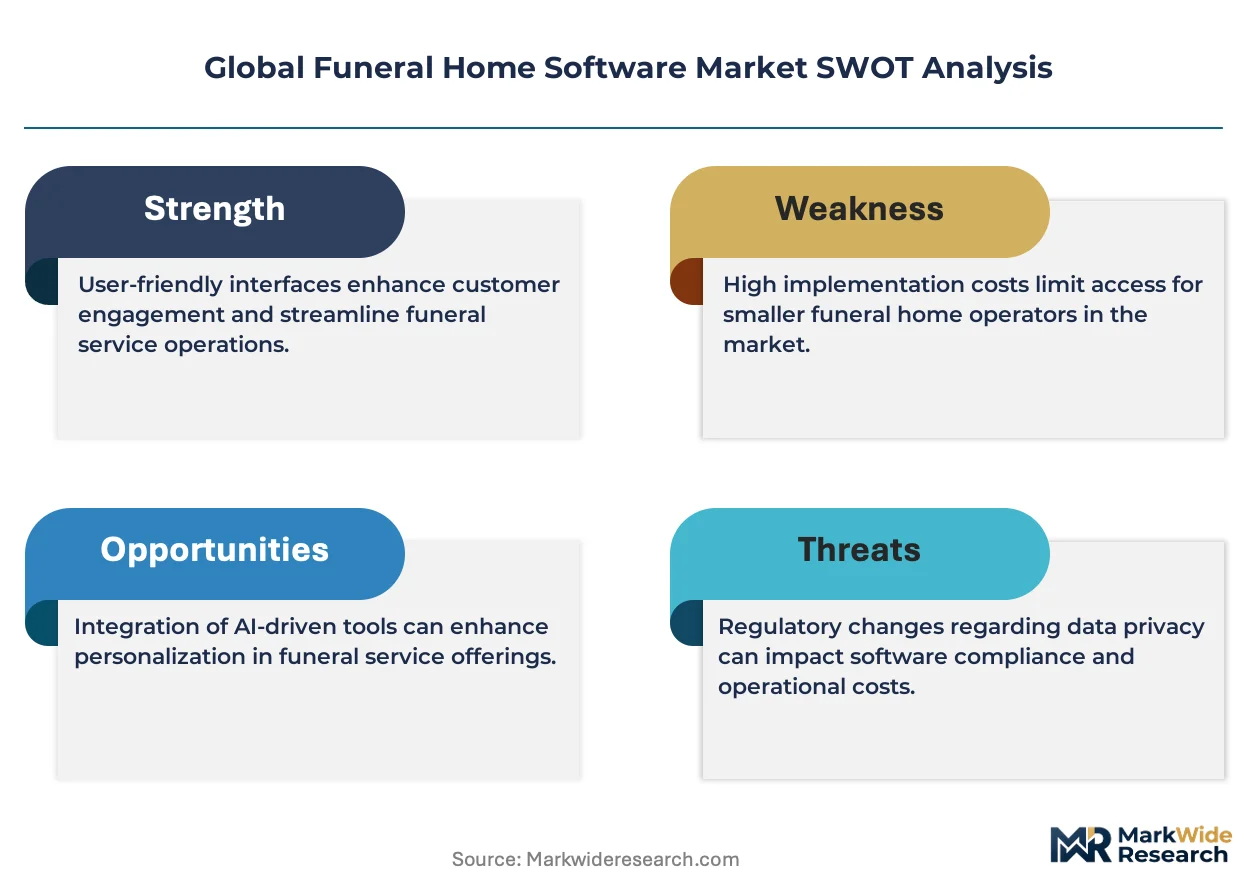
Top-tier vendors anchor the cloud-native segment, while legacy system integrators and regional specialists occupy lower tiers. The vendor base organizes around three strategic archetypes: HIPAA compliance specialists, cremation workflow optimizers, and multi-location chain consolidators. M&A activity concentrates among platforms acquiring state-level certification tracks, while strategic partnerships focus on crematory equipment hardware integration.
Within the cloud-native tier, Parting Pro and Passare exemplify distributed operator network specialization, with Parting Pro representing mobile-first architecture and Passare occupying a position in service-arrangement workflow depth. Halcyon Death Care Management Solutions anchors the compliance-tracking specialization archetype across US state jurisdictions. Cemify and Plotbox sit within the cemetery-integrated platform segment, serving operators requiring plot inventory management and perpetual care trust accounting.
| Leading Market Players |
|---|
| Parting Pro |
| Cemify |
| Plotbox |
| The Professional Programs |
| TerraPro |
| Osiris |
| Passare |
| Obit |
| Halcyon Death Care Management Solutions |
| Others |
Supply & Pricing Matrix
Certification-tier divergence between HIPAA-aligned compliance suites and basic scheduling modules manifests in both subscription pricing and vendor supply chain configurations. Premium tiers command recurring revenue multiples through automated state audit reporting, while commodity functionality competes on implementation speed and mobile accessibility.
Pricing Analysis
Short lead-time premiums attach to cloud-native deployments with pre-configured state certification tracks, whereas spot-access discounts emerge for generic practice management platforms adapted from adjacent verticals. Three-tier pricing structure across premium, standard, and economy levels separates enterprise chains with multi-location synchronization from independent mortuaries with single-site SaaS arrangements. Pricing pressure stems from substitute solutions competing on basic scheduling and billing functions. Independent mortuaries exhibit highest price sensitivity due to limited IT budgets, while consolidated chains prioritize compliance integration over cost minimization.
Supply Chain Analysis
Warehouse-distribution layer concentration in cloud infrastructure spans Amazon Web Services, Microsoft Azure, and Google Cloud Platform as primary hosting nodes. Raw material dependencies center on API development talent, cybersecurity certification labor, and regulatory compliance expertise. Single-source vulnerability concentrates in specialized state vital statistics reporting portal integrations. Distribution runs through direct vendor sales teams for enterprise chains and value-added resellers for independent mortuary segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in certified compliance engineering talent prop pricing power for vendors maintaining multi-jurisdiction audit automation. Capacity bottlenecks in HIPAA-aligned platform development sustain margin premiums.
For Market Incumbents: Hedge against generic practice management substitution by embedding crematory equipment integration and environmental permit tracking as differentiated modules. Defensive consolidation moves should prioritize acquisition of state-level certification tracks and captive API development capacity for legacy cemetery database interoperability. For New Entrants and Emerging Players: Launch via mobile-first SaaS distribution targeting cremation-heavy independent operators in Sydney and Melbourne with thin-margin workflow optimization. White-space concentration sits in smartphone-native interfaces for remote case intake, with GDPR-aligned architectures enabling European market extension from Australian beachheads. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-tracking specialists given state audit tightening for pre-need trust accounting. Long-term viability across the analysis window favors platforms with embedded regulatory update automation. Acquisition target archetype: mid-market vendors with hybrid deployment capabilities bridging on-premise data custody and cloud accessibility. Signal to watch: EPA emission standard revisions triggering platform refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified compliance dashboards reduce IT staffing requirements by half at Texas and Florida chains. |
| Acquisition of Specialist Firm | State certification track purchases accelerate multi-jurisdiction market entry for cloud-native vendors. |
| Strategic Partnership | Crematory equipment hardware convergence expands platform utility beyond core case management functions. |
| Geographic Expansion | GDPR-aligned product lines enable entry into Irish markets from UK operational bases. |
| Product Launch | Smartphone-native interfaces address underserved mobile director access at mid-market chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with funeral home operators, state funeral service board administrators, software platform engineers, and cemetery management executives combined with secondary validation from HIPAA compliance documentation, FDA medical examiner interoperability standards, and state vital statistics reporting protocols. Bottom-up modeling of deployment adoption by location count and top-down triangulation against aggregate software procurement expenditure established market sizing.
Granularity-level modeling operated at deployment mode, end-user scale tier, and solution module depth across the projection horizon. CAGRs derived from regression analysis of replacement cycle compression and cloud migration penetration curves. Industry-specific forecast inputs incorporated state-level pre-need trust audit tightening schedules and cremation rate trajectories by metropolitan statistical area.
Regulatory divergence between federal health-data standards and fragmented state licensing rules, workforce technology fluency gaps, and environmental permit tracking complexity are the dominant revision risks. Forecasts reflect documented assumptions regarding HIPAA enforcement intensity and chain consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Legal Software Market
Software & Services
Global Reporting Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Lead Mining Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Global Data Quality Software Market
Software & Services
Engineering Software Market
Software & Services
Global Church Management Software Market
Software & Services
Sports League Management Software Market
Software & Services
Resonator Design Software Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Batch Management Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Account-Based Advertising Software Market