
 SRM Software Market | 2026-2036
SRM Software Market Size, Share, and Industry Trends Forecast 2026-2036
SRM Software Market Insights
Subscription-based SaaS licensing is rewriting competitive economics in supplier relationship management, allowing mid-market buyers to access enterprise-grade procurement tools without capital-intensive on-premise deployments. SAP Ariba leverages its embedded ERP connectivity to dominate large-corporation RFP cycles. Zycus anchors its position through deep functionality in spend analytics and contract lifecycle management. Coupa differentiates via consumer-grade user interfaces that accelerate frontline procurement adoption.
Supplier relationship management software orchestrates the full vendor lifecycle—from sourcing and onboarding through performance scorecarding, risk monitoring, and contract enforcement—typically delivered through multi-tenant cloud architectures with API-first integration to ERP, finance, and logistics systems. Cloud and SaaS deployment models now capture the majority of new bookings, while on-premise installations retreat to highly regulated environments with data residency requirements. Procurement and supplier management functionality modules generate the deepest user engagement, whereas analytics capabilities command premium pricing due to scarce data-science talent.
The EU AI Act, GDPR, and REACH compliance frameworks compel European manufacturers to deploy traceable, auditable supplier data systems that document ESG credentials and chemical substance flows. In the United States, SEC climate disclosure rules and FDA supplier quality regulations similarly tighten documentation burdens for publicly traded healthcare and industrial firms. Procurement leaders must evaluate whether their current platforms can automate regulatory evidence collection before compliance deadlines harden into competitive disqualifiers.
Market Dynamics
Cloud migration is compressing deployment timelines for supplier management platforms while EU AI Act compliance deadlines force procurement teams to replace legacy systems with auditable architectures before enforcement phases begin.
Growth Catalysts
- EU AI Act documentation mandates:European manufacturers must deploy traceable supplier data systems that automate ESG credential collection and algorithmic decision logging for high-risk procurement categories.
- Automotive cluster demand in Germany:Real-time supply chain visibility requirements from Volkswagen, BMW, and Bosch supplier networks are accelerating multi-tier supplier monitoring adoption.
- SaaS subscription economics:Mid-market enterprises now access enterprise-grade sourcing tools without capital-intensive on-premise infrastructure, expanding addressable buyer pools.
Market Restraints
- Data residency compliance costs:GDPR localization requirements force dual-region cloud deployments, inflating infrastructure spend for vendors serving European industrial clients.
- ERP integration complexity:Legacy SAP and Oracle installations in heavy manufacturing create multi-year migration timelines that stall platform replacement decisions.
- Specialized talent scarcity:Procurement technology implementation requires rare combinations of supply chain domain expertise and API architecture skills, extending project durations.
Strategic Opportunities
- Carbon accounting module expansion:CSRD scope 3 emissions disclosure rules create immediate demand for supplier-level CO2 tracking integrated with existing contract management workflows.
- Small supplier financing integration:Embedded working capital tools within procurement platforms address cash flow gaps for tier-2 and tier-3 vendors in automotive and aerospace supply chains.
- Predictive risk scoring convergence:Machine learning models combining financial health, geopolitical exposure, and ESG metrics offer premium pricing potential in contract lifecycle management segments.
Industry Challenges
- Multi-system data harmonization:Procurement teams struggle to reconcile supplier master data across disparate ERP, logistics, and quality management systems without expensive middleware development.
- Change management resistance:Frontline buyers in industrial sectors resist abandoning spreadsheet-based sourcing workflows despite platform investments, limiting realized ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SRM Software Market |
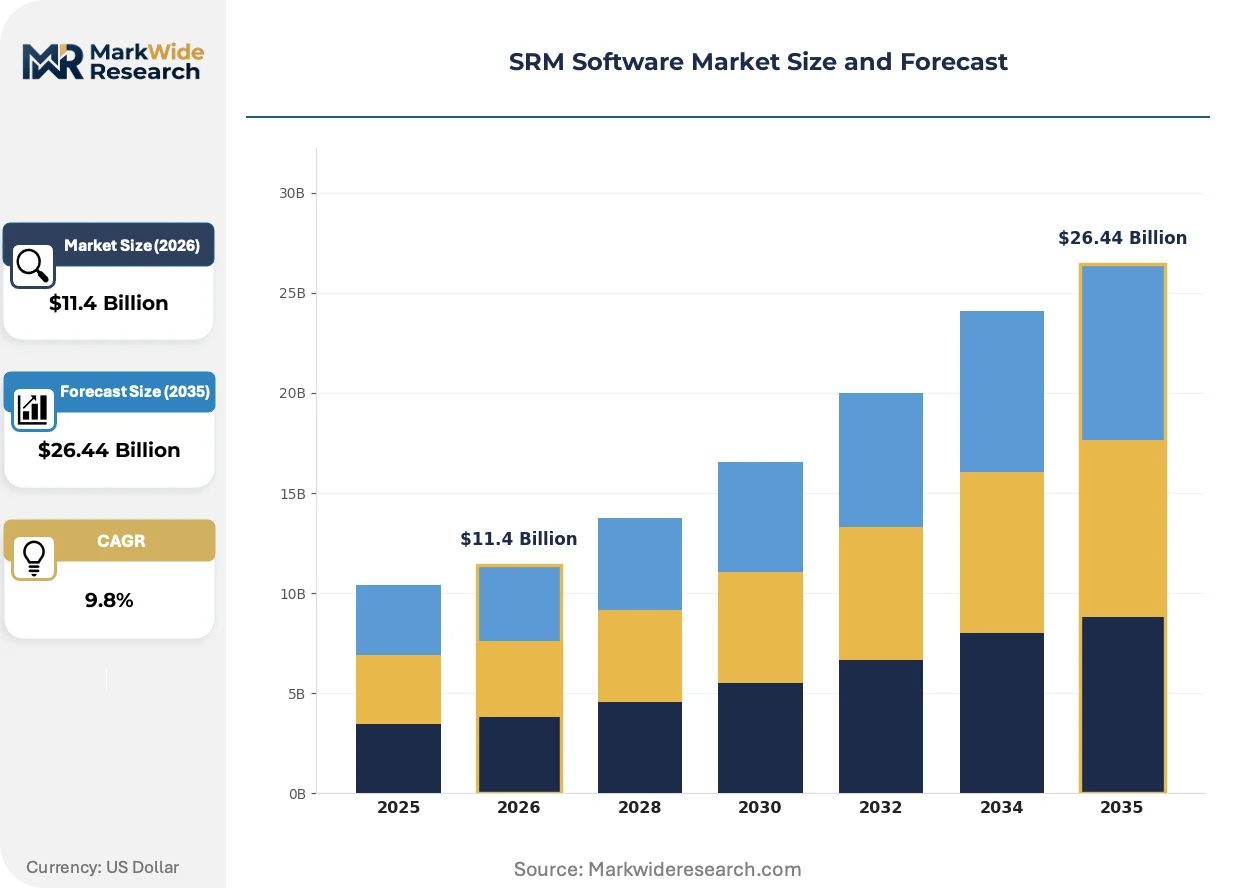
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.44 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-premise, Cloud, Hybrid, SaaS End User: Healthcare, Education, Retail, Manufacturing Functionality: Procurement, Supplier Management, Contract Management, Analytics Company Size: Small Enterprises, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | SAP Ariba, Zycus, Coupa, Jaggaer, Ivalua, Oracle, GEP, SynerTrade, Determine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SRM Software Market Trends and Innovations
Artificial intelligence is embedding into core procurement workflows, transforming supplier selection from static qualification checklists into dynamic, continuously scored risk-adjusted decisions that compress sourcing cycles.
Digital twin architectures are virtualizing supplier network modeling, allowing procurement teams to simulate disruption scenarios across multi-tier automotive and electronics supply chains before committing to sourcing decisions. Siemens and Dassault Systèmes customers in German industrial clusters are deploying these capabilities at pilot scale. The technology is virtualizing traditional supply chain mapping exercises that previously required months of manual supplier surveys.
CSRD and SEC climate disclosure rules are mandating granular supplier emissions documentation, forcing software vendors to build automated carbon data collection APIs that interface directly with supplier ERP systems. Industrial buyers in Germany and France face the tightest compliance deadlines. Heavy manufacturing segments are responding by prioritizing platforms with pre-built sustainability reporting modules over generic procurement suites.
Self-service analytics adoption is accelerating among mid-market procurement functions, displacing centralized business intelligence teams with embedded visualization tools that frontline buyers configure without IT support. Distribution through cloud marketplaces is replacing direct enterprise sales for sub-500-employee accounts. North American industrial distributors are white-labeling these capabilities to defend their position against platform-native competitors.
SRM Software Market Segmentation
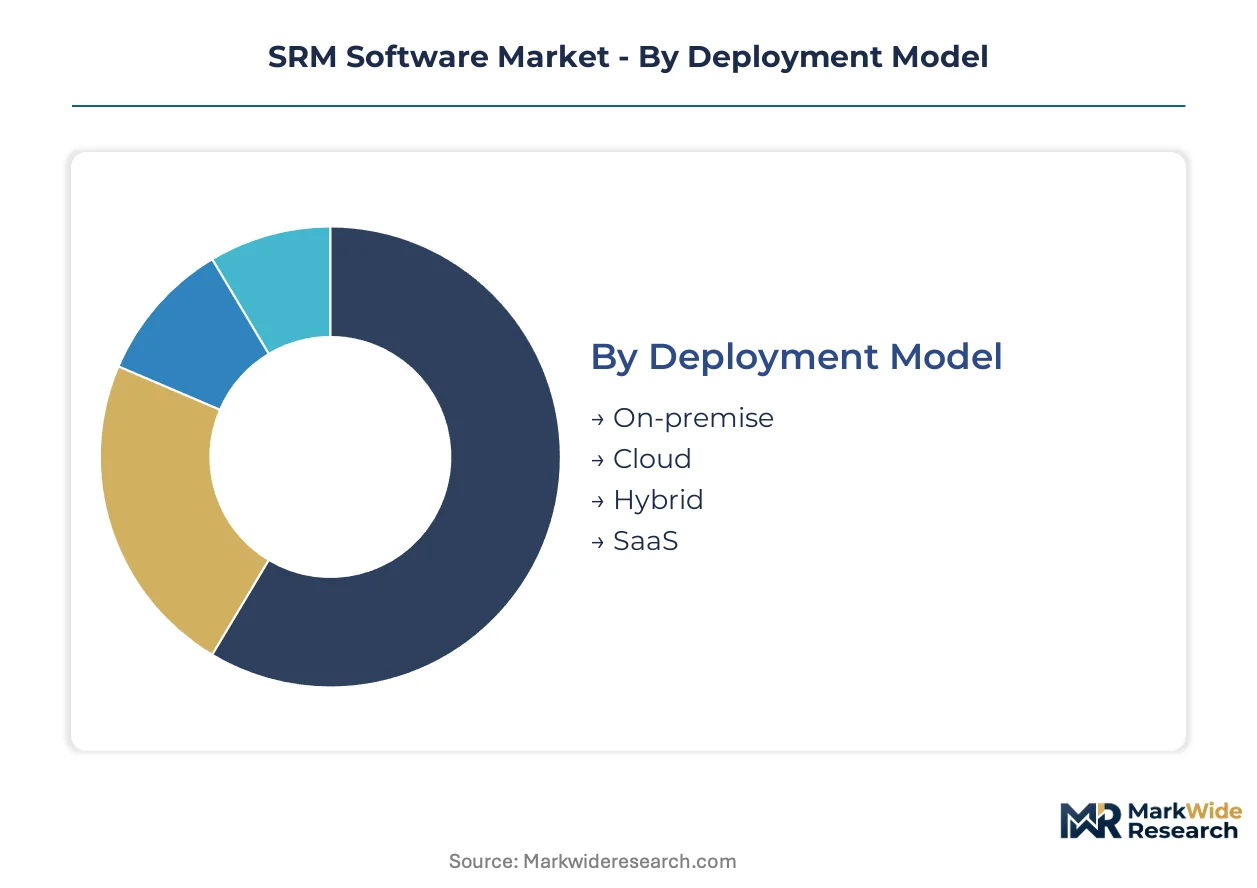
Segmentation in supplier relationship management software reveals how deployment preferences, organizational scale, and functional priorities fragment buyer requirements across incompatible technology architectures. Procurement leaders select platforms based on regulatory exposure, existing ERP investments, and the depth of multi-tier supplier visibility their operations demand.
Deployment Model:
Mature cloud architectures now dominate new bookings while hybrid and on-premise installations retreat to specialized compliance environments.
- SaaS:Multi-tenant subscription platforms deliver continuous feature updates without client-side infrastructure maintenance. German automotive manufacturers and French industrial conglomerates prioritize SaaS deployments to satisfy EU AI Act algorithmic logging requirements without capital expenditure.
- Cloud:Single-tenant hosted solutions offer dedicated instance isolation for buyers with data residency constraints. Healthcare systems in the United States select cloud deployments to maintain HIPAA audit trails while avoiding on-premise hardware refresh cycles.
- Hybrid:Split architectures keep sensitive supplier financial data on-premise while routing transactional workflows through cloud interfaces. Heavy manufacturing firms with legacy SAP installations deploy hybrid models to phase migration risks.
- On-premise:Locally installed software persists in defense contractors and classified government procurement operations where air-gapped networks are mandatory.
SaaS retains volume leadership; Cloud holds the steepest expansion curve among regulated industries.
End User:
Application intensity varies sharply by sector, with manufacturing and healthcare driving platform complexity while retail and education prioritize user adoption simplicity.
- Manufacturing:Multi-tier supplier monitoring, quality scorecarding, and ESG credential verification dominate functional requirements. German automotive clusters demand real-time disruption simulation across Bosch and Continental supplier networks.
- Healthcare:FDA supplier quality regulations and serialized drug traceability mandates create documentation-intensive procurement workflows. Hospital systems integrate SRM platforms with ERP to automate vendor qualification for medical device suppliers.
- Retail:High-volume, low-margin sourcing operations prioritize contract compliance automation and rapid supplier onboarding for seasonal private-label programs.
- Education:Public university systems and K-12 districts select lightweight sourcing modules for grant-funded equipment procurement with simplified approval hierarchies.
Manufacturing commands the deepest functional requirements; Healthcare generates the most complex compliance-driven customization.
Functionality:
Module adoption patterns reveal where procurement organizations concentrate transformation investment versus where they settle for baseline automation.
- Procurement:Requisition-to-pay workflows, catalog management, and purchase order automation form the core engagement layer. Mid-market enterprises in the United States deploy procurement modules first to displace spreadsheet-based buying processes.
- Supplier Management:Onboarding, qualification, risk scoring, and performance tracking orchestrate the vendor lifecycle. CSRD scope 3 disclosure rules push European manufacturers toward automated supplier data collection.
- Contract Management:Clause libraries, obligation extraction, and renewal alerts protect against revenue leakage. Life sciences firms use contract modules to enforce FDA-mandated quality agreements with CMO partners.
- Analytics:Spend classification, supplier consolidation opportunities, and predictive risk modeling command premium pricing due to scarce data science implementation talent.
Procurement modules retain volume leadership; Analytics holds the steepest expansion curve as data-driven sourcing matures.
Company Size:
Buyer scale determines deployment complexity tolerance and integration depth requirements across the customer base.
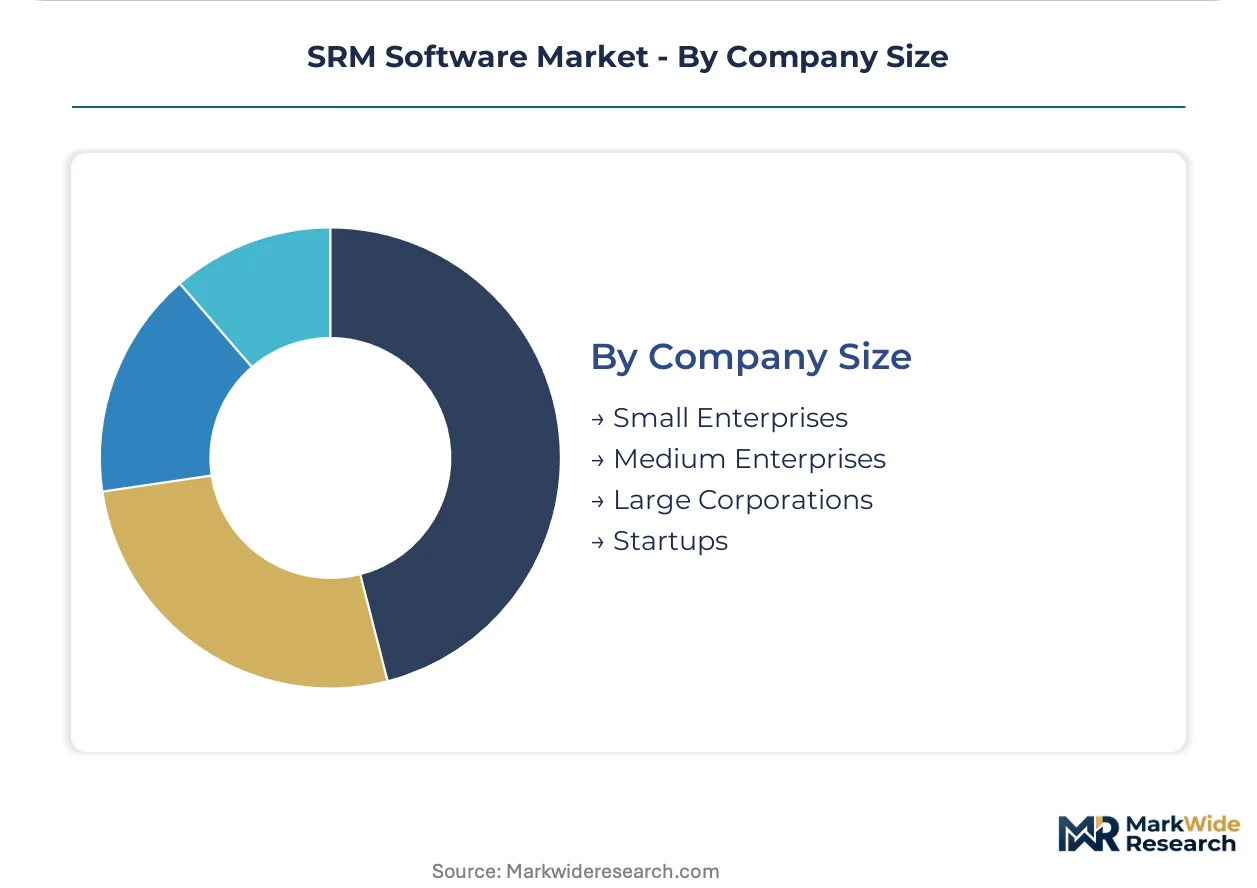
- Large Corporations:Global template standardization, multi-ERP harmonization, and dedicated procurement operations centers define enterprise implementations. Siemens and Volkswagen-scale organizations require API-first architectures connecting SAP, Oracle, and specialized logistics systems.
- Medium Enterprises:Rapid-deployment cloud configurations with pre-built connectors to NetSuite and Microsoft Dynamics attract mid-market industrial distributors seeking competitive parity with larger rivals.
- Small Enterprises:Lightweight, self-service configurations through cloud marketplaces enable sub-500-employee manufacturers to access sourcing automation without implementation teams.
- Startups:Venture-backed technology firms adopt freemium procurement tools for vendor payment scheduling and cap table-aware spend tracking.
Large Corporations retain volume leadership; Medium Enterprises hold the steepest expansion curve as SaaS economics democratize access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border software licensing flows favor export-oriented economies with dense industrial bases. Germany and the United States generate substantial SRM platform demand while India and China emerge as delivery hubs for implementation services.
United States
SEC climate disclosure rules and FDA supplier quality mandates drive documentation-intensive procurement automation. Healthcare systems in the Boston and Research Triangle clusters integrate SRM platforms with ERP to automate medical device vendor qualification. Cloud marketplaces accelerate adoption among mid-market industrial distributors.
Germany
EU AI Act algorithmic logging requirements and CSRD scope 3 disclosure deadlines compress replacement timelines for legacy systems. Volkswagen, BMW, and Bosch supplier networks in Bavaria and Baden-Württemberg demand real-time multi-tier visibility. KBA automotive safety regulations tighten supplier traceability requirements.
United Kingdom
Post-Brexit customs documentation complexity and UK-specific ESG reporting standards reshape supplier data requirements. London-based financial services firms extend procurement governance frameworks to technology vendor ecosystems. Midlands manufacturing clusters pilot carbon accounting modules for supply chain emissions tracking.
India
BIS quality certification mandates and DGFT export incentive compliance drive formalization of supplier management practices. Karnataka and Maharashtra technology corridors host implementation centers serving Asia-Pacific manufacturing clients. PLI scheme beneficiaries in electronics manufacturing adopt cloud-based vendor onboarding platforms.
Japan
METI supply chain resilience initiatives and JIS standards compliance sustain demand for rigorous supplier qualification systems. Toyota and Honda keiretsu networks in Aichi Prefecture require multi-tier risk monitoring across sub-tier vendors. Aging procurement workforce demographics accelerate self-service analytics adoption.
SRM Software Market Competitive Landscape
On the supply side, the industry is consolidating around ERP-embedded platforms and best-of-breed specialists. Tiered competitive dynamics separate full-suite providers from point-solution vendors. Dominant archetypes include ERP-native suites with embedded connectivity, procurement-native platforms with deep category expertise, and vertical specialists serving regulated industries. Strategic moves concentrate on API-first architecture investments and carbon accounting module expansion.
Within the ERP-native tier, SAP Ariba and Oracle exemplify platforms leveraging embedded connectivity to dominate large-corporation RFP cycles. Zycus occupies a position among procurement-native specialists, anchoring market presence through spend analytics and contract lifecycle management depth. These three companies represent contrasting archetypes: ERP-embedded scale versus functional specialization.
| Leading Market Players |
|---|
| SAP Ariba |
| Zycus |
| Coupa |
| Jaggaer |
| Ivalua |
| Oracle |
| GEP |
| SynerTrade |
| Determine |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure concentration in Ireland, Germany, and the Netherlands concentrates compute costs for SRM vendors, pushing margin pools toward API integration layers and carbon accounting modules where specialized development commands premium positioning.
Pricing Analysis
Industrial OEM buyers anchor subscription pricing around per-user SaaS tiers with volume discounts scaling above 500 seats. Price differentiation rests on ERP connector depth and EU AI Act compliance certification levels. Cost compression in mid-market segments intensifies because NetSuite and Microsoft Dynamics pre-built connectors commoditize basic procurement workflows. Small enterprises exhibit highest price sensitivity, while automotive OEMs prioritize real-time multi-tier visibility over per-seat economics.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Wistron, and Flex holding server assembly capacity across Taiwan, Mexico, and Poland. Software development labor draws from India, Poland, and Romania. Supply chain risk centers on single-source vulnerability for GPU acceleration hardware tethered to NVIDIA foundry allocations. Distribution runs through hyperscaler marketplaces—AWS Marketplace, Azure Marketplace, and Google Cloud Marketplace—displacing direct enterprise sales below 500-employee accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of procurement-technology architects combining supply chain domain fluency with API engineering skills constrains implementation velocity and concentrates margin capture among vendors with embedded professional services capabilities.
For Market Incumbents: Pre-empt margin erosion in procurement automation modules by acquiring carbon accounting specialists before CSRD enforcement hardens supplier emissions tracking into table-stakes functionality. Defend against API-native challengers by deepening pre-built connectors to SAP S/4HANA and Oracle Fusion Cloud. Vertical integration into sustainability data verification services protects pricing power as disclosure mandates proliferate. For New Entrants and Emerging Players: Establish a beachhead in tier-2 automotive supplier networks across Baden-Württemberg and Bavaria where real-time disruption monitoring remains underserved by incumbent suites. Target mid-market French industrial conglomerates facing compressed CSRD compliance timelines with lightweight, audit-ready supplier onboarding platforms. Lead with carbon accounting APIs as the wedge capability displacing spreadsheet-based scope 3 tracking. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed procurement-native platforms that have exhausted organic growth in North American mid-markets and now require geographic or capability expansion to justify valuation step-ups. Long-term viability hinges on AI Act compliance architecture and sustainability module attach rates. Monitor EU AI Act enforcement phase transitions as the inflection signal distinguishing audit-ready platforms from legacy replacements.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Module Launch | CSRD scope 3 mandates from EMA and national regulators force automated supplier emissions tracking into contract workflows. |
| API-First Architecture Investment | Pre-built connectors to SAP S/4HANA and Oracle Fusion Cloud compress implementation timelines for German automotive OEMs. |
| Strategic Partnership with Hyperscaler | AWS Marketplace and Azure Marketplace distribution displaces direct sales for sub-500-employee manufacturing accounts. |
| Acquisition of Sustainability Data Specialist | Supplier ESG verification capabilities defend pricing power as EU AI Act documentation requirements harden. |
| Geographic Expansion into Industrial Clusters | Bavaria and Baden-Württemberg automotive networks demand real-time multi-tier visibility that incumbent suites underserve. |
Research Methodology
Desk research of SEC 10-K filings, EU regulatory databases, and hyperscaler marketplace disclosures preceded structured interviews with chief procurement officers, ERP integration architects, sustainability compliance leads, and cloud marketplace strategy heads. Primary fieldwork validated deployment model preferences and carbon accounting module attach rates across manufacturing verticals. Secondary sources included customs filings tracking software licensing flows and trade association procurement technology surveys. Bottom-up segment sizing triangulated against top-down IT spend allocation models.
Assumptions held fixed include EU AI Act enforcement phase sequencing and CSRD disclosure deadline integrity, while cloud adoption curves and API integration complexity were varied across sensitivity scenarios. Segmentation modeling spanned deployment model, organization size, vertical industry, functional module depth, and regional regulatory cluster. CAGRs were derived from installed base growth rates and annual recurring revenue expansion patterns. Forecast inputs incorporated GDPR localization cost inflation and automotive OEM supplier consolidation trends.
Sensitivities concentrate around EU AI Act enforcement delays, GPU supply constraints affecting AI-enabled procurement modules, and mid-market buyer consolidation toward ERP-embedded suites. Forecasts reflect these documented assumptions with explicit scenario boundaries. Quarterly review of hyperscaler marketplace listing growth and CSRD audit failure rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
3D Printing Medical Device Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Data Quality Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Clustering Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Global DevOps Software Market
Software & Services
Website Translation Software Market
Software & Services
Sales Coaching Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
US Digital Marketing Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Test Management Software Market
Software & Services
Home Design Software Market