
 Global Document Management Software Market | 2026-2036
Global Document Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Document Management Software Market Analysis
Buyer concentration is expanding across mid-market enterprises and regulated industries seeking unified content platforms. Adobe Inc. leverages deep integration with creative and document workflows to sustain enterprise loyalty. Microsoft Corporation anchors its position through bundling with productivity suites that control distribution channels. Hyland Software, Inc. specializes in industry-specific content services for healthcare and finance verticals.
Document management software comprises systems that capture, store, index, retrieve, and govern electronic documents through metadata schemas, access controls, and audit trails, with typical deployments supporting millions of indexed records and sub-second retrieval latency for enterprise knowledge management. Cloud-based deployment leads in new installations as organizations prioritize remote accessibility and reduced capital expenditure, while workflow automation solutions capture expanding margin pools by eliminating manual routing bottlenecks. On-premises systems retain dominance in government and defense sectors where data sovereignty requirements restrict external hosting.
The U.S. HIPAA Security Rule and FDA 21 CFR Part 11 shape product requirements for healthcare and life sciences document integrity, while the EU GDPR and AI Act mandate granular access logging and automated retention policies across European deployments. Japan's METI guidelines on digital transformation further standardize interoperability expectations for cross-border enterprise content exchange. Stakeholders must evaluate how evolving multi-jurisdictional compliance frameworks will reshape architectural requirements for audit readiness and data portability.
Market Dynamics
Cloud migration pressure from healthcare and financial services is compressing deployment cycles and forcing vendors to re-architect for zero-trust security models. The EU AI Act's audit trail mandates are accelerating R&D spend on automated governance engines.
Growth Catalysts
- GDPR Retention Mandates:European enterprises must implement granular data lifecycle policies, driving replacement of legacy archiving systems with AI-enabled compliance platforms.
- Healthcare Cloud Migration:Hospital networks in Germany and the United States are consolidating patient records onto unified platforms to satisfy HIPAA Security Rule audit requirements.
- Workflow Automation:Insurance and legal sectors are eliminating manual document routing through robotic process automation integration, compressing processing cycles from days to minutes.
Market Restraints
- Data Sovereignty Friction:Russia and China's data localization laws fragment cloud architectures, forcing vendors to maintain separate infrastructure stacks and raising operational complexity.
- Technical Debt Burden:Decades-old on-premises installations in government agencies resist API-based integration, extending sales cycles and inflating professional services margins.
- Substitution by Native Platforms:Microsoft SharePoint and Google Workspace bundle basic document management, squeezing standalone vendors in price-sensitive mid-market segments.
Strategic Opportunities
- India Digital Transformation:RBI and SEBI compliance deadlines for financial record-keeping are creating first-mover advantage for vendors offering rupee-denominated cloud hosting.
- AI-Document Convergence:Large language model integration with contract analysis and automated redlining is opening premium pricing tiers in legal and procurement verticals.
- API-First Distribution:Embedded finance and insurtech platforms represent new channel economics, with document capabilities white-labeled into vertical SaaS workflows.
Industry Challenges
- Zero-Trust Engineering Talent:Scarce expertise in confidential computing and homomorphic encryption is bottlenecking product development for regulated deployments.
- Multi-Jurisdictional Certification:Simultaneous FDA 21 CFR Part 11, EU MDR, and Japan PMDA validation timelines extend time-to-revenue for life sciences modules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Document Management Software Market |
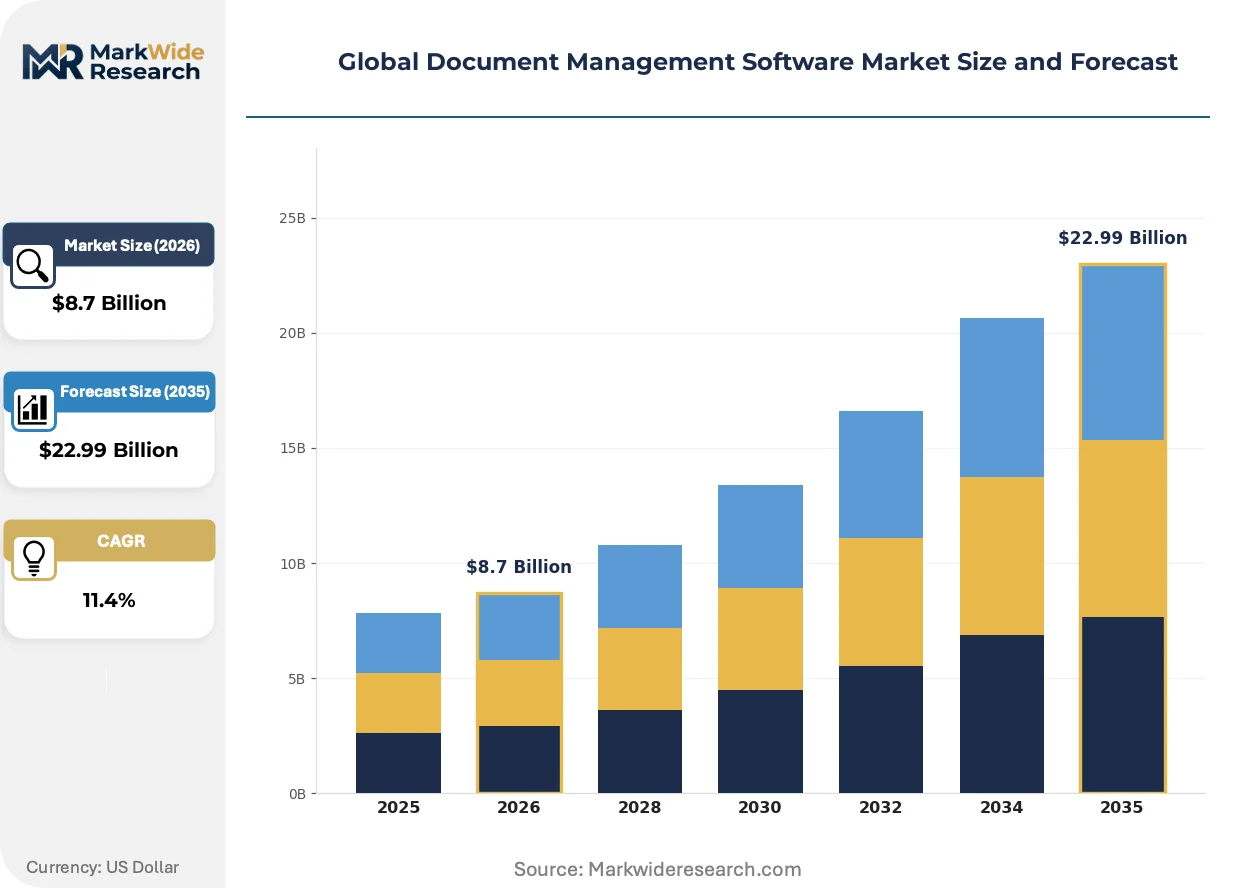
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Healthcare, Legal, Education, Finance Solution: Document Capture, Workflow Automation, Version Control, Archiving Industry Vertical: Manufacturing, Retail, Government, Non-Profit |
| Companies Covered | OpenText Corporation, Adobe Inc., Microsoft Corporation, Xerox Corporation, SAP SE, Oracle Corporation, Hyland Software, Inc., Box, Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Document Management Software Market Emerging Trajectories
Generative AI is compressing the boundary between document creation and management, with automated classification and synthesis capabilities becoming baseline expectations. Vendors are racing to embed these functions without triggering regulatory scrutiny.
Federated learning architectures are rewriting how sensitive documents are processed across organizational boundaries. Pharmaceutical consortiums and banking syndicates are piloting models that train on encrypted document sets without centralizing raw data. This approach is compressing compliance review timelines while satisfying GDPR and HIPAA constraints on data movement.
The EU AI Act's risk classification framework is forcing document vendors to build explainability layers into automated decision systems. High-risk use cases in hiring, lending, and benefits administration now require human-in-the-loop documentation with full audit trails. German and French enterprises are demanding these capabilities preemptively, creating a de facto standard ahead of enforcement deadlines.
Mid-market buyers are consolidating vendor relationships, preferring platform breadth over point solutions. Procurement committees in manufacturing and professional services are bundling document management with adjacent capabilities like e-signature and contract lifecycle management. This pattern is most pronounced in Japan, where METI digital transformation subsidies favor integrated suite purchases over fragmented toolchains.
Global Document Management Software Market Segmentation
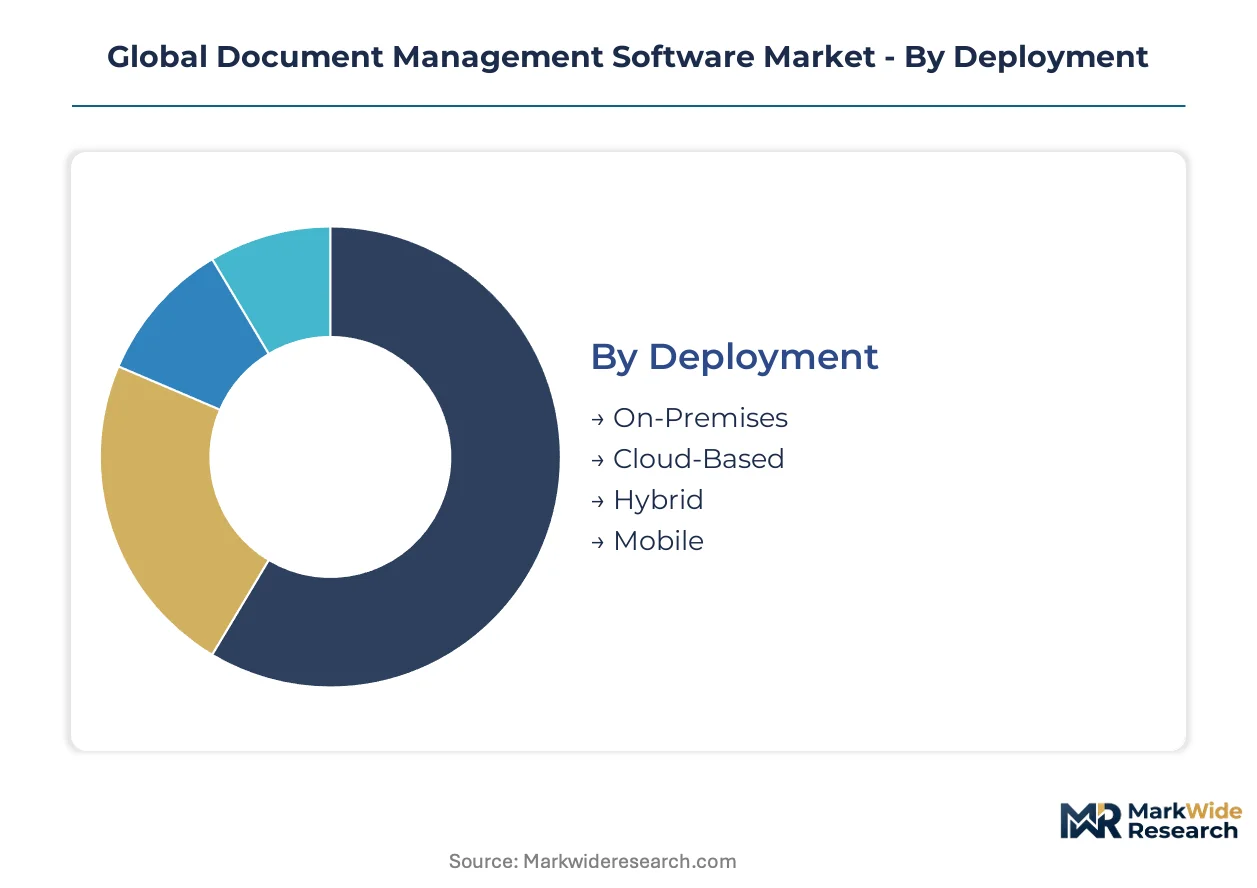
Document management software vendors architect product lines around deployment flexibility, vertical compliance requirements, and workflow integration depth. Segmentation choices directly determine addressable market scope and professional services margin structure.
Deployment:
Cloud-based deployments command premium pricing while on-premises installations retain volume dominance in regulated sectors.
- Cloud-Based:Multi-tenant SaaS architectures with elastic storage and API-native integration. Healthcare networks in Germany and the United States are consolidating patient records onto these platforms to satisfy HIPAA Security Rule audit requirements.
- On-Premises:Dedicated infrastructure with full data sovereignty and air-gapped security controls. Government and defense agencies in Japan and France mandate these deployments under METI guidelines and ANSM data localization directives.
- Hybrid:Tiered storage with sensitive documents on-premises and collaborative content in cloud tiers.
- Mobile:Containerized applications with offline synchronization and biometric access controls.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
End User:
Healthcare and legal sectors drive compliance-heavy procurement with finance and education expanding fastest.
- Healthcare:Electronic health record integration with FDA 21 CFR Part 11 validation for audit trails. Hospital systems across the United States and Germany are replacing legacy PACS and document archives with unified clinical content platforms.
- Legal:Matter-centric organization with ethical wall isolation and automated retention scheduling. Law firms in the United Kingdom and Australia are deploying these systems ahead of Solicitors Regulation Authority and state bar digitization mandates.
- Finance:Trade documentation and KYC record management with RBI and SEBI compliance modules.
- Education:Student record lifecycle management with FERPA-aligned access controls.
Healthcare captures current procurement volume. Finance represents the steepest expansion trajectory as RBI and SEBI deadlines approach.
Solution:
Workflow automation solutions extract premium margins while document capture remains the volume entry point.
- Workflow Automation:Business process orchestration with robotic process automation connectors and SLA monitoring. Insurance carriers in Japan and Germany are eliminating manual underwriting document routing, compressing processing cycles from days to minutes.
- Document Capture:OCR, ICR, and intelligent document classification with straight-through processing rates exceeding 90% for structured forms.
- Version Control:Check-in/check-out protocols with branching, merging, and watermarking for collaborative authoring environments.
- Archiving:WORM-compliant long-term retention with automated tiering and legal hold management.
Workflow Automation leads margin capture. Document Capture anchors installed base expansion.
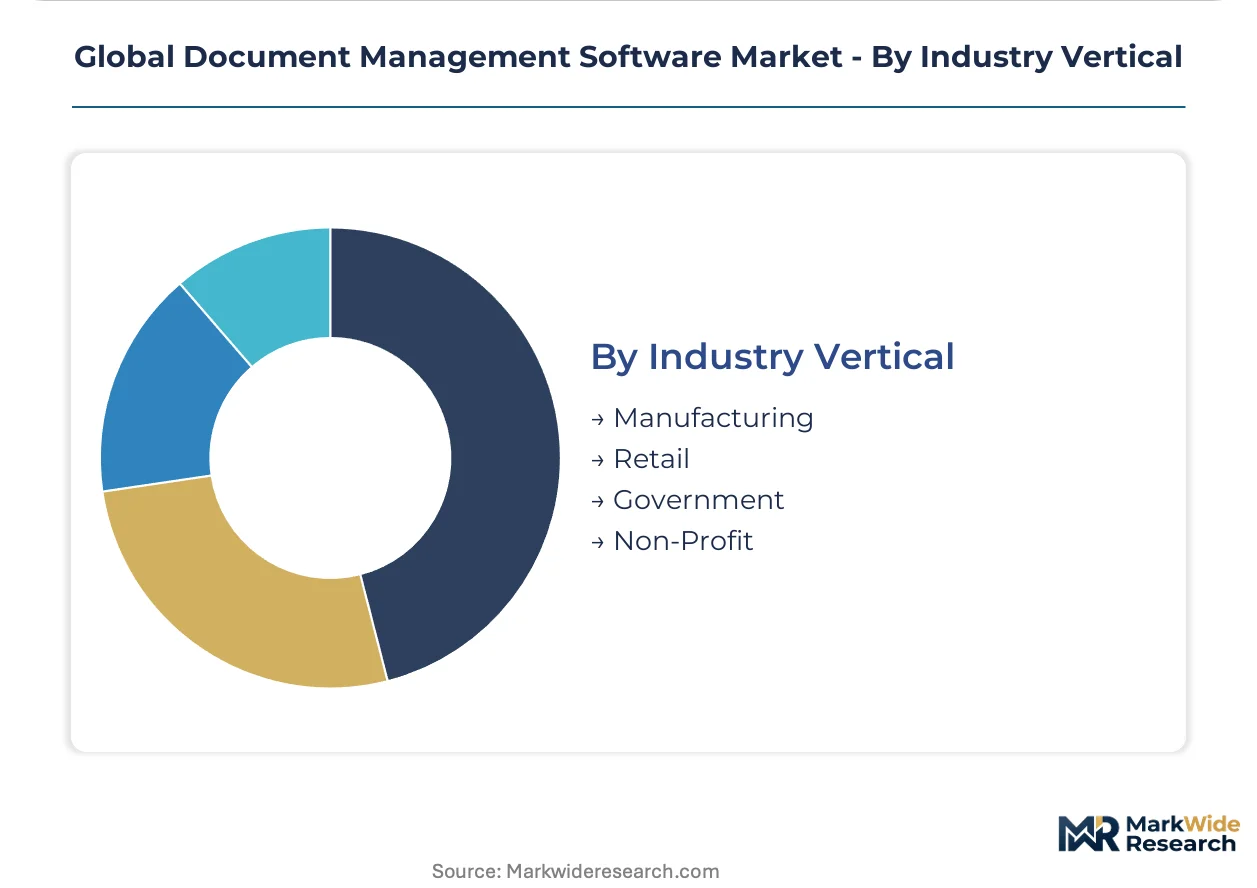
Industry Vertical:
Government and manufacturing concentrate current demand while retail adoption accelerates with supply chain digitization.
- Government:Records management with NARA and MoReq compliance, classified document handling, and FOIA response automation. Federal agencies in the United States and departmental bodies in France are modernizing legacy ECM installations under digital transformation mandates.
- Manufacturing:Engineering document control with CAD integration, BOM synchronization, and ISO 9001 quality record retention.
- Retail:Vendor onboarding, contract repository, and promotional asset management across distributed store networks.
- Non-Profit:Grant documentation, donor record privacy, and volunteer coordination with limited IT staffing.
Government dominates contract value. Retail is climbing the fastest as omnichannel operations demand unified content access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's healthcare networks are consolidating patient records at a faster clip than Japan's manufacturing conglomerates digitizing engineering archives, yet both markets face identical compliance deadlines under divergent regulatory regimes.
United States
Hospital systems and insurance carriers are replacing legacy ECM installations with cloud-native platforms. HIPAA Security Rule audit requirements and FDA 21 CFR Part 11 validation timelines compress procurement cycles. The Boston-Cambridge healthtech corridor and Dallas-Fort Worth hospital networks are piloting zero-trust architectures for clinical content exchange.
Germany
Industrial Mittelstand firms and automotive suppliers are unifying quality documentation across distributed engineering teams. EU AI Act audit trail mandates and GDPR retention policies accelerate replacement of on-premises archives. The Stuttgart engineering cluster and Munich healthcare networks are demanding explainability layers for automated document classification.
Japan
Pharmaceutical consortiums and banking syndicates are piloting federated learning for cross-organizational document processing. METI digital transformation subsidies favor integrated suite purchases over fragmented toolchains. The Osaka-Kobe manufacturing belt and Tokyo financial district are standardizing interoperability protocols for enterprise content exchange.
India
Financial institutions are racing against RBI and SEBI compliance deadlines for record-keeping digitization. Rupee-denominated cloud hosting creates first-mover advantage for vendors with local data centers. The Mumbai financial hub and Bengaluru SaaS corridor are embedding document capabilities into vertical fintech workflows.
United Kingdom
Legal firms and professional services networks are deploying matter-centric organization ahead of Solicitors Regulation Authority digitization mandates. Ethical wall isolation and automated retention scheduling drive premium procurement. The London legal district and Manchester professional services cluster are consolidating vendor relationships around platform breadth.
Global Document Management Software Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modalities and vertical compliance requirements. The vendor base organizes into three strategic tiers: productivity-suite bundlers controlling distribution channels, industry-specific content services firms capturing healthcare and finance verticals, and API-native cloud platforms enabling embedded finance workflows. Dominant competitive moves include zero-trust security re-architecture and automated governance engine development to satisfy multi-jurisdictional certification timelines.
Within the bundler tier, Microsoft Corporation exemplifies distribution control through productivity suite integration, while Adobe Inc. anchors creative-to-document workflow continuity. Hyland Software, Inc. occupies a specialist position in regulated verticals. These three entities represent divergent strategic postures: horizontal platform leverage, creative ecosystem retention, and vertical compliance depth.
| Leading Market Players |
|---|
| OpenText Corporation |
| Adobe Inc. |
| Microsoft Corporation |
| Xerox Corporation |
| SAP SE |
| Oracle Corporation |
| Hyland Software, Inc. |
| Box, Inc. |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists controlling document management portfolios anchor supply discipline through centralized engineering resources and unified go-to-market infrastructure, compressing pricing variance across tiered SaaS offerings while concentrating procurement leverage over cloud infrastructure vendors.
Pricing Analysis
Capacity additions in India are reshaping price floors for cloud-native deployments as rupee-denominated hosting creates localized cost advantages against US and EU-based infrastructure. Three-tier pricing structure across premium, standard, and economy levels dominates, with FDA 21 CFR Part 11 certification and GDPR audit-log capabilities driving differentiation. Pricing pressure stems from Microsoft SharePoint and Google Workspace bundling basic document management at marginal cost. Mid-market enterprises exhibit highest price sensitivity, while healthcare networks under HIPAA Security Rule mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German automotive suppliers and US hospital systems mandate multi-supplier qualification for cloud infrastructure and professional services delivery. Supply concentrates in the United States, Germany, and India for software development and data center operations, with raw material dependencies spanning silicon wafers, specialized storage media, and encryption hardware. Single-source vulnerability sits with hyperscaler cloud platforms controlling elastic compute access. Distribution runs through direct enterprise sales teams, systems integrators, and vertical SaaS platform embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's rupee-denominated cloud hosting and EU GDPR-mandated premium compliance creates margin expansion for vendors with dual-continent infrastructure footprints.
For Market Incumbents: Lock in healthcare and financial services verticals through preemptive zero-trust architecture certification ahead of EU AI Act enforcement deadlines. Deepen API-native integration capabilities to defend against Microsoft SharePoint substitution in mid-market segments. Prioritize automated governance engine R&D to compress multi-jurisdictional validation timelines.
For New Entrants and Emerging Players: Begin with India's financial services digitization wave, where RBI and SEBI compliance deadlines outpace vendor supply. Target legal and procurement verticals for AI-document convergence with contract analysis and automated redlining. Pursue embedded finance channel partnerships with insurtech platforms seeking white-labeled document capabilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among API-native cloud platforms with healthcare vertical penetration but incomplete geographic coverage. Long-term viability favors vendors with federated learning architectures enabling cross-organizational document processing without data centralization. Watch FDA 21 CFR Part 11 validation timeline compression as inflection indicator for life sciences module profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Security Re-architecture | HIPAA Security Rule and EU AI Act mandates accelerate enterprise procurement cycles for certified deployments. |
| Automated Governance Engine Development | GDPR retention policies and FDA 21 CFR Part 11 validation requirements compress time-to-revenue for compliance modules. |
| Federated Learning Architecture Deployment | Pharmaceutical consortiums in Japan pilot encrypted document processing without centralizing raw patient data. |
| API-First Distribution Partnership | Embedded finance and insurtech platforms in India white-label document capabilities into vertical SaaS workflows. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA, EU MDR, and Japan PMDA validation extends addressable market for life sciences content services. |
Methodological Framework
Multiple input streams — primary interviews with CTOs and IT procurement officers at healthcare networks and financial institutions, regulatory filing analysis, and hyperscaler capex disclosures — were reconciled against secondary validation from SEC filings, hospital procurement databases, and GPO contracts. Bottom-up sizing of deployment installations and top-down triangulation against aggregate software spending produced convergent estimates. Conversations with platform engineers, integration specialists, and channel partners informed workflow automation adoption patterns.
Data-stream reconciliation across deployment models, organization size tiers, vertical industries, integration complexity levels, and regional adoption patterns structured the analytical framework. CAGRs were derived from segment-level growth trajectory modeling and cross-referenced against macroeconomic indicators. Federated learning pilot programs and zero-trust architecture deployment timelines served as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including sudden regulatory enforcement delays, hyperscaler pricing wars, and geopolitical fragmentation of cloud infrastructure access. Forecasts reflect documented assumptions about compliance deadline adherence and enterprise modernization budget continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Jewelry Store Management Software Market
Software & Services
Data Visualization Software Market
Software & Services
Global UIUX Software Market
Software & Services
Global Customer Experience Software Market
Software & Services
Global Press Release Distribution Software Market
Software & Services
Legal Software Market
Software & Services
Global Contract Lifecycle Management Software Market
Software & Services
Server Software Market
Software & Services
API Testing Market
Software & Services
Sales Training Software Market
Software & Services
Business Rules Management System Market
Software & Services
Reporter Systems Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Account-Based Data Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
IT Service Management Tools Market