
 Online Recruitment Software Market | 2026-2036
Online Recruitment Software Market Size, Share, and Industry Trends Forecast 2026-2036
Online Recruitment Software Market Outlook
Enterprise buyer concentration is decoupling from traditional staffing agency dominance as mid-market corporations and educational institutions build direct hiring technology stacks. Oracle Corporation leverages its Fusion Cloud HCM ecosystem to anchor enterprise accounts with integrated talent acquisition modules. SAP SE competes through embedded recruitment workflows inside its S/4HANA suite, sustaining cross-sell momentum among existing ERP customers.
Online recruitment software comprises applicant tracking systems, candidate relationship management platforms, and AI-enabled screening engines that automate sourcing, evaluation, and onboarding workflows through cloud-native architectures. Cloud-based deployment leads structural growth due to lower capital requirements and faster implementation cycles, while applicant tracking features capture the deepest margin pools through recurring subscription tiers. Small businesses represent the fastest-expanding customer type as self-service SaaS models reduce traditional implementation barriers.
The EU AI Act imposes algorithmic transparency mandates on automated hiring tools across Europe, while the US Equal Employment Opportunity Commission enforces anti-discrimination protocols for AI-driven candidate screening. ISO 30415 standards for human resource management shape product certification requirements in multiple jurisdictions. Stakeholders must monitor evolving algorithmic accountability rules to determine compliance investment timing and geographic market prioritization.
Market Dynamics
AI-powered candidate screening engines are compressing evaluation timelines from weeks to hours, forcing incumbents to re-architect product roadmaps around predictive analytics rather than workflow automation alone.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European employers must document automated decision logic, creating compliance-driven replacement cycles for opaque legacy systems.
- Small business SaaS penetration:Self-service onboarding tools reduce implementation from months to days, unlocking mid-market corporations previously priced out of enterprise platforms.
- Natural language processing advances:Semantic resume parsing now extracts competency signals from unstructured data, raising match accuracy above keyword-based alternatives.
Market Restraints
- Cloud infrastructure concentration:Three hyperscalers control over seventy percent of hosting capacity, exposing vendors to egress cost volatility and regional outage cascades.
- Biased training data liability:Historical hiring patterns encoded in machine learning models perpetuate demographic skews, triggering EEOC enforcement actions and civil litigation.
- Free-to-freemium substitution:Basic applicant tracking functions commoditize through open-source alternatives and spreadsheet-based workflows, pressuring entry-tier pricing.
Strategic Opportunities
- ISO 30415 certification differentiation:Human resource management standardization creates audit-ready positioning for vendors serving regulated industries like healthcare and finance.
- Skills-based hiring convergence:Integration of credential verification APIs with assessment platforms enables competency-first screening, displacing degree-centric filters.
- Educational institution direct hiring:Universities and vocational colleges bypass staffing agencies to build alumni-to-employer pipelines, representing an underpenetrated vertical.
Industry Challenges
- Machine learning operations talent scarcity:Vendors compete for data scientists capable of productionizing bias detection and model drift monitoring at enterprise scale.
- Enterprise legacy ATS integration friction:Decades-old on-premise systems require custom API bridges and data migration protocols, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Recruitment Software Market |
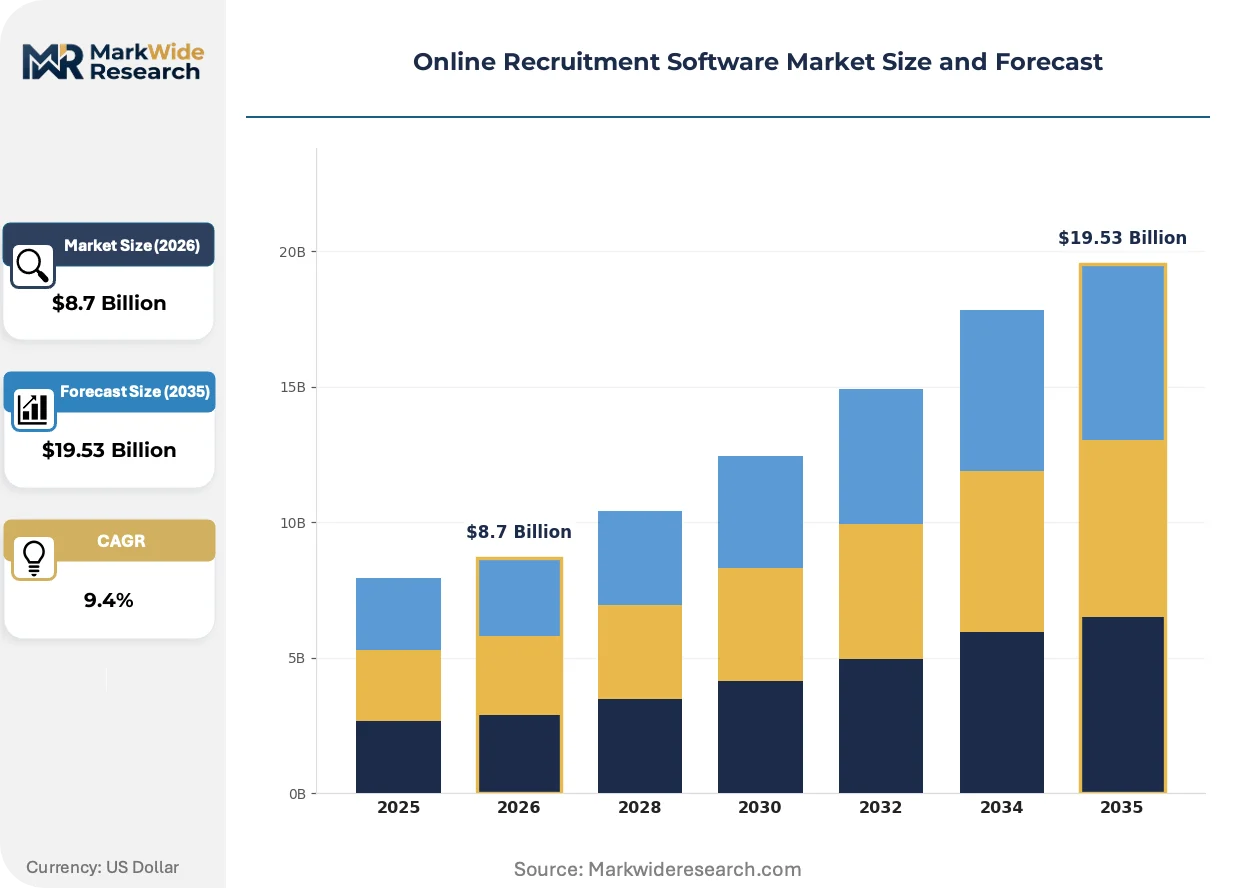
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Corporations, Staffing Agencies, Educational Institutions, Startups Feature: Applicant Tracking, Job Posting, Resume Parsing, Interview Scheduling Customer Type: Small Businesses, Medium Enterprises, Large Enterprises, Freelancers |
| Companies Covered | Oracle Corporation, IBM Corporation, SAP SE, Workday, Inc., LinkedIn Corporation, Freshworks Inc., Zoho Corporation Pvt. Ltd., ServiceNow, Cornerstone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Recruitment Software Market Strategic Shifts
Recruitment technology vendors are racing to embed generative capabilities across the candidate journey, from conversational sourcing bots to automated offer negotiation assistants.
Unified talent intelligence platforms are unifying applicant tracking, workforce planning, and internal mobility data into single-pane workforce architecture. Fortune 500 HR departments are adopting these systems within eighteen-month refresh cycles. This convergence is compressing vendor consolidation timelines as point solutions lose procurement battles to integrated suites.
The EU AI Act risk classification framework is reclassifying high-stakes hiring algorithms as limited-risk or high-risk depending on decision autonomy, forcing European deployments to maintain human-in-the-loop protocols. Vendors must now generate technical documentation and conformity assessments for automated screening tools. German and French employers are prioritizing vendors with pre-certified algorithmic impact assessments.
Subscription fatigue among mid-market buyers is fragmenting purchasing authority from centralized HR procurement to departmental line managers with discretionary software budgets. Self-serve trial-to-paid conversion models displace traditional enterprise sales cycles. This pattern is most visible in United States technology and professional services sectors where hiring velocity outpaces centralized IT governance.
Online Recruitment Software Market Segmentation
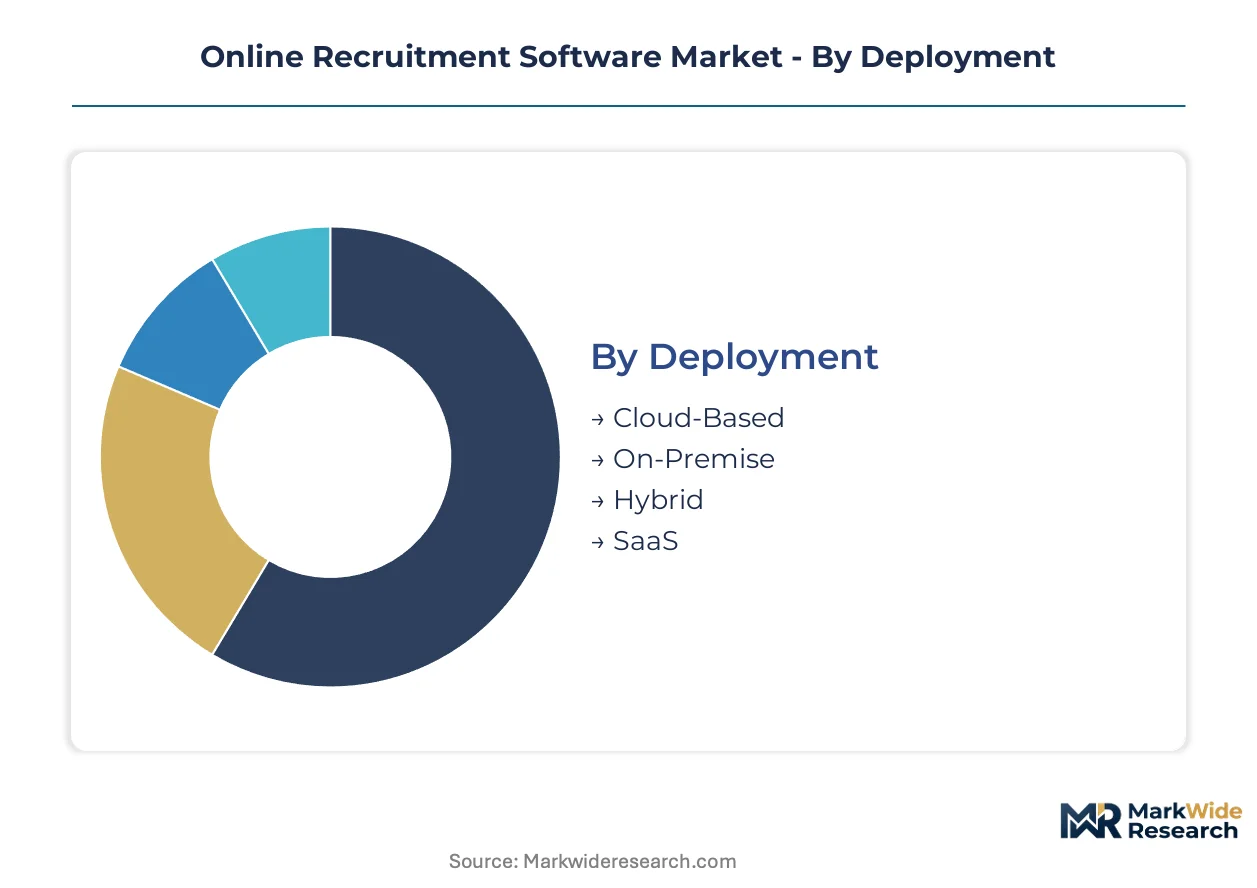
Segmentation in online recruitment software reveals how deployment architecture, user sophistication, and feature depth create distinct commercial territories. Vendors must align product roadmaps with the upgrade cycles and integration constraints specific to each slice.
Deployment:
Replacement cycles in this category accelerate as compliance mandates and remote work patterns render legacy infrastructure obsolete.
- Cloud-Based:Multi-tenant architectures with automatic updates eliminate capital expenditure and reduce implementation timelines. Fortune 500 employers in the United States prioritize these platforms for distributed hiring teams. The EU AI Act's documentation requirements favor cloud-native vendors with built-in audit trails.
- SaaS:Self-service subscription tiers with API-first designs enable rapid scaling without IT intervention. Mid-market corporations and educational institutions adopt these for seasonal hiring spikes. Pricing transparency and month-to-month contracts reduce procurement friction.
- On-Premise:Single-tenant installations retained by defense contractors and financial institutions with data sovereignty requirements.
- Hybrid:Split architectures connecting legacy HRIS cores with cloud-based candidate-facing modules.
Cloud-Based sits at the top of the volume ranking, with SaaS climbing the fastest.
End User:
Cost tier stratification separates buyers by implementation complexity and support expectations.
- Corporations:Enterprise HR departments demand unified talent intelligence platforms integrating applicant tracking with workforce planning. These buyers negotiate multi-year contracts with dedicated customer success teams. Compliance investments for ISO 30415 certification justify premium pricing.
- Staffing Agencies:High-velocity recruiters require CRM-embedded sourcing tools and candidate redeployment analytics. Volume-based pricing models align vendor revenue with placement success.
- Educational Institutions:Universities building direct employer pipelines for alumni career services.
- Startups:Founders with minimal HR infrastructure favor freemium tiers with basic job posting and interview scheduling.
Corporations command the largest contract values, though educational institutions are expanding most quickly as career services digitize.
Feature:
Application maturity determines which modules capture procurement budgets versus which face commoditization pressure.
- Applicant Tracking:Core workflow engines managing requisition approval, candidate progression, and offer generation. Cloud deployment dominates as enterprises replace decade-old on-premise systems. Recurring subscription tiers generate the deepest margin pools.
- AI-Enabled Screening:Predictive models ranking candidates by competency fit and flight risk. Natural language processing advances raise match accuracy above keyword-based alternatives. EEOC enforcement actions create liability exposure for vendors with biased training data.
- Job Posting:Multi-channel distribution to job boards and social platforms with performance analytics.
- Interview Scheduling:Calendar integration and automated reminder sequences reducing coordinator overhead.
Applicant Tracking anchors the largest installed base, while AI-enabled screening gains share fastest as evaluation timelines compress.
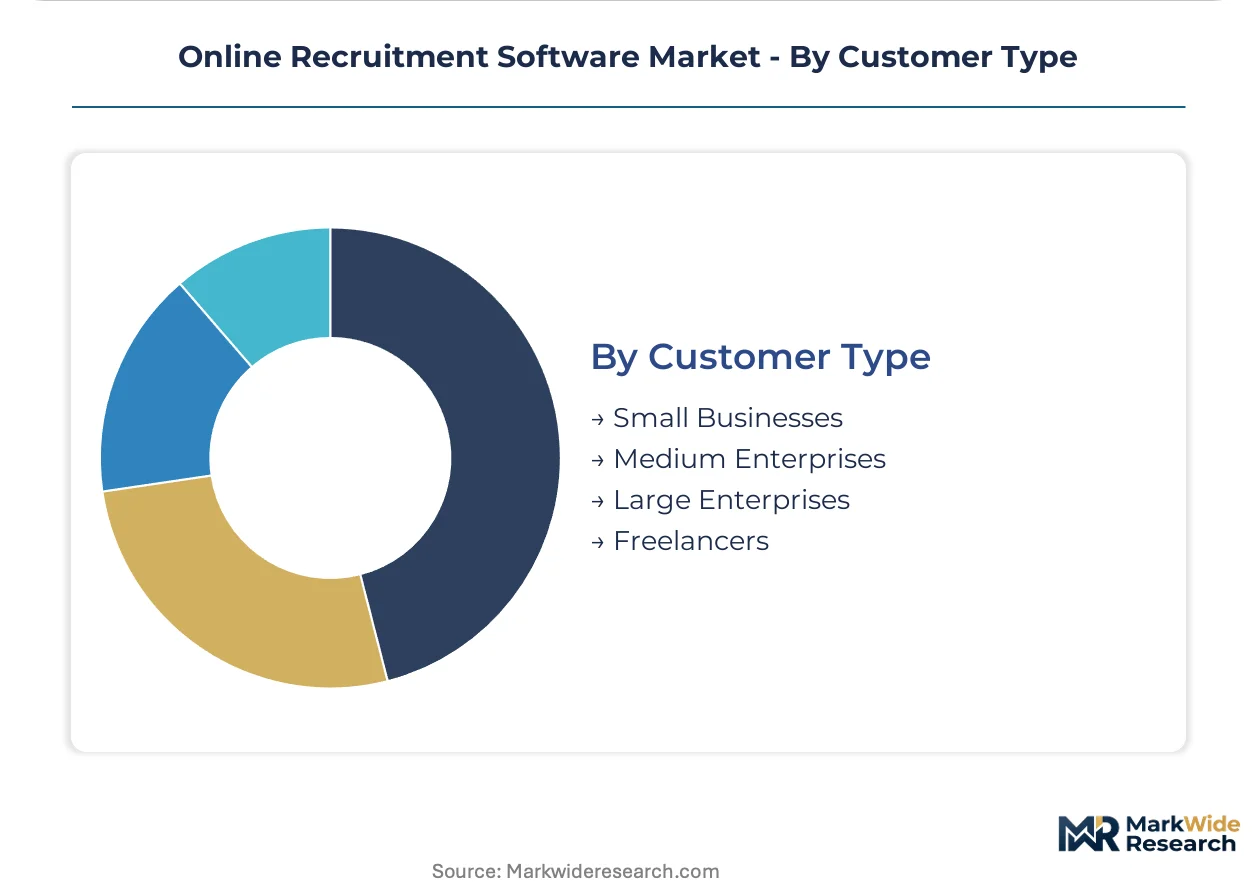
Customer Type:
Volume concentration and margin structure diverge sharply across organizational scale.
- Large Enterprises:Complex implementations requiring custom API bridges to legacy ERP systems. Oracle Fusion Cloud HCM and SAP S/4HANA integration priorities shape vendor selection. Procurement cycles extend twelve to eighteen months.
- Small Businesses:Self-service onboarding tools reduce implementation from months to days. Subscription fatigue is fragmenting purchasing authority to departmental line managers with discretionary budgets.
- Medium Enterprises:Growth-stage companies outgrowing spreadsheet workflows but resisting enterprise complexity.
- Freelancers:Individual recruiters purchasing seat-based licenses for client project management.
Large Enterprises generate the highest absolute revenue, with small businesses showing the steepest expansion trajectory as SaaS penetration unlocks previously excluded buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 employers in the United States generate the deepest platform subscriptions, while European compliance mandates and Asian workforce digitization create divergent growth vectors across national markets.
United States
Technology and professional services sectors drive SaaS adoption through departmental line managers with discretionary software budgets. The EEOC enforces anti-discrimination protocols for AI-driven candidate screening, forcing vendors to document bias detection capabilities. Silicon Valley clusters anchor innovation in predictive analytics, while New York Metro financial services firms demand ISO 30415-certified talent intelligence platforms.
Germany
Industrial Mittelstand employers and automotive OEMs prioritize ERP-integrated recruitment workflows with human-in-the-loop protocols. The EU AI Act risk classification framework mandates technical documentation for automated hiring algorithms, favoring vendors with pre-certified impact assessments. Baden-Württemberg manufacturing hubs and Bavarian technology corridors concentrate procurement authority for unified talent platforms.
United Kingdom
Financial services and professional services firms in London accelerate replacement cycles for decade-old applicant tracking systems. GDPR compliance requirements shape data residency specifications for cloud-native deployments. The Southeast corridor concentrates demand for skills-based hiring platforms that integrate credential verification APIs with assessment engines.
India
IT services exporters and startup ecosystems drive adoption of self-service SaaS models with API-first designs. The country's expanding data protection framework influences vendor selection for multi-tenant architectures. Bengaluru and Hyderabad technology corridors concentrate hiring velocity that outpaces centralized IT governance, fragmenting purchasing authority to departmental managers.
Japan
Lifetime employment norms are eroding as manufacturing and services sectors adopt cloud-based talent acquisition for contingent workforce management. METI industrial policy encourages HR tech modernization through productivity improvement incentives. Tokyo-Osaka corporate headquarters concentrate procurement of applicant tracking systems with Japanese-language semantic resume parsing capabilities.
Online Recruitment Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise software incumbents leverage existing ERP relationships to anchor talent acquisition modules within eighteen-month refresh cycles. Three strategic archetypes dominate: cloud-native SaaS specialists, integrated HCM suite providers, and professional network platforms with native recruiting tools. Competitive intensity centers on M&A consolidation of point solutions and strategic partnerships embedding screening engines within workforce planning architectures.
Within the integrated suite tier, Oracle Corporation and SAP SE exemplify diversified technology conglomerates extending recruitment functionality through existing customer relationships. Workday, Inc. occupies a position among cloud-native HCM specialists that compete through unified talent intelligence architectures. These three anchors represent divergent approaches to enterprise account penetration—incumbent cross-selling versus native cloud replacement cycles.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| Workday, Inc. |
| LinkedIn Corporation |
| Freshworks Inc. |
| Zoho Corporation Pvt. Ltd. |
| ServiceNow |
| Cornerstone |
| Others |
Value Chain & Pricing Dynamics
Fortune 500 HR departments concentrated in the United States negotiate multi-year enterprise contracts that anchor SaaS pricing models, while mid-market buyers with fragmented purchasing authority drive self-service tier proliferation. This buyer bifurcation compresses pricing power at the middle tier while sustaining premium capture for integrated suite vendors.
Pricing Analysis
Bundled talent intelligence platforms versus unbundled point solutions defines the pricing architecture across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 30415-certified enterprise suites from API-first mid-market offerings and freemium entry tiers. Price differentiation rests on compliance certification depth and legacy system integration complexity. Cost compression in the standard tier is intensifying because open-source applicant tracking alternatives commoditize basic workflow functions. Small businesses exhibit highest price sensitivity, while regulated industries in finance and healthcare show lowest sensitivity due to audit-ready positioning requirements.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler cloud infrastructure concentration across the United States, Ireland, and Germany. Cloud-native recruitment platforms draw from compute capacity, API gateway services, and natural language processing model providers concentrated among three dominant vendors. Supply chain risk centers on regional outage cascades and egress cost volatility from hosting lock-in. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for mid-market and small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The online recruitment software market functions as a stable compounder, with enterprise SaaS subscription renewals and compliance-driven replacement cycles generating predictable recurring revenue streams.
For Market Incumbents: To counter cloud-native SaaS specialists eroding mid-market share, Oracle Corporation and SAP SE should deepen API-first interoperability with legacy HRIS systems to extend implementation timeline advantages. Certification investment in pre-audited algorithmic impact assessments for EU AI Act compliance creates switching costs that protect enterprise accounts from point solution displacement. For New Entrants and Emerging Players: The price-point gap between premium integrated suites and economy freemium tiers offers white-space entry for vertical-specific platforms targeting educational institutions with alumni-to-employer pipeline tools. Skills-based hiring convergence presents the most penetrable application layer, with credential verification API integration as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Private equity firms with HR technology portfolios are the most active acquirer in this space, consolidating point solution vendors ahead of eighteen-month enterprise refresh cycles. Long-term viability favors platforms with embedded workforce planning capabilities rather than standalone applicant tracking. The signal to watch is ISO 30415 certification adoption velocity among healthcare and financial services buyers as an inflection indicator for compliance-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified talent intelligence architectures displace point solutions in Fortune 500 procurement cycles. |
| Acquisition of Specialist Firm | AI-enabled screening engines add predictive analytics capabilities to legacy workflow automation stacks. |
| Strategic Partnership | Credential verification API alliances enable skills-based hiring convergence for competency-first screening. |
| Geographic Expansion | EU AI Act pre-certification opens German and French public sector procurement opportunities. |
| Product Launch | Self-service onboarding tools reduce implementation barriers for mid-market corporations and educational institutions. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CHROs, talent acquisition directors, IT procurement officers, and HR technology implementation specialists with secondary validation. SEC filings, hyperscaler capex disclosures, EU regulatory impact assessments, and ISO certification databases anchored market sizing. Bottom-up vendor revenue aggregation and top-down enterprise software spending analysis provided triangulation checks across the analysis window.
Comparable historical periods anchored the projection horizon, with deployment model, organization size, vertical industry, and regional regulatory cluster serving as core segmentation dimensions. CAGRs were derived from trend extrapolation adjusted for compliance mandate timing and technology refresh cycle patterns. Natural language processing advancement trajectories and EU AI Act implementation schedules shaped industry-specific forecast inputs.
Caveats apply where EEOC enforcement action intensity or EU AI Act technical documentation requirements could materially shift the outlook. Forecasts reflect assumptions about enterprise cloud migration velocity and mid-market SaaS penetration ceilings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
App Development Software Market
Software & Services
Packaged Software Market
Software & Services
Productivity Management Software Market
Software & Services
Global ITSM Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Global Driving School Software Market
Software & Services
Global Apparel Management Software Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Simulation Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Compensation Software Market
Software & Services
Ground Handling Software Market
Software & Services
Multiphysics Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Global Business Software Market