
 School Timetable Software Market | 2026-2036
School Timetable Software Market Size, Share, and Industry Trends Forecast 2026-2036
School Timetable Software Market Insights
Legacy server infrastructure is hardening into a cost burden that cloud-native architectures actively displace. Untis leverages decades of European institutional relationships to sustain deployment density across German-speaking education systems. PowerSchool anchors the North American landscape through deep SIS integration and statewide procurement channels. aSc Timetables competes on price-accessibility for mid-tier institutions in Eastern Europe and Latin America.
School timetable software constitutes algorithmic scheduling engines that process constraint variables—room availability, instructor qualifications, student course selections, and regulatory hour limits—to generate conflict-minimized timetables through integer programming or heuristic optimization methods. Cloud-Based deployment now captures the dominant share of new installations as districts abandon on-premises server maintenance; SaaS models concentrate recurring revenue pools while Hybrid configurations persist where data residency requirements fragment procurement. Automated Scheduling functions represent the core value proposition, though Resource Management modules are expanding fastest as facilities-sharing and multi-campus coordination complexity rises.
FCC guidelines on student data transmission shape cloud architecture decisions for US vendors, while GDPR compliance obligations in Europe mandate encryption standards and data-localization terms that extend contract negotiation cycles. The EU AI Act introduces algorithmic transparency requirements that will affect automated scheduling recommendations in member-state deployments. Stakeholders must monitor how procurement officers weigh total cost of ownership against interoperability certifications when evaluating vendor shortlists.
Market Dynamics
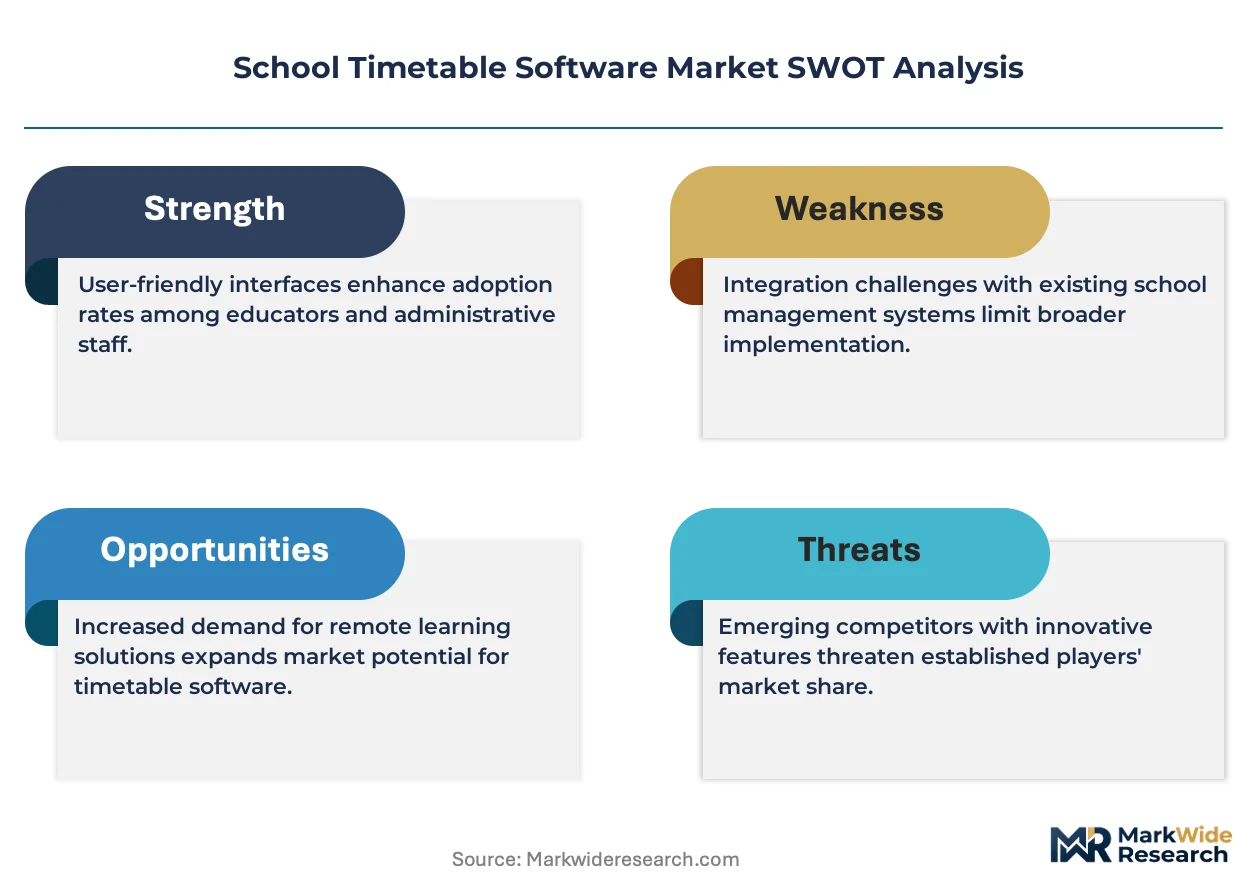
Cloud migration is compressing deployment cycles for K-12 districts while API-first architectures dismantle decades of legacy server infrastructure that previously anchored institutional procurement decisions.
Growth Catalysts
- FCC Guidelines:US federal transmission standards for student data are accelerating cloud architecture investments among vendors serving American school districts, creating compliance-driven upgrade cycles.
- Multi-Campus Coordination:Resource management modules are expanding fastest where facilities-sharing complexity rises across consolidated district footprints in Australia and Germany.
- Integer Programming:Algorithmic scheduling engines now process constraint variables at scale, reducing manual timetable construction hours from weeks to hours for mid-tier institutions.
Market Restraints
- GDPR Compliance:European encryption standards and data-localization terms extend contract negotiation cycles by 40-60 days, delaying SaaS revenue recognition for vendors.
- Legacy Technical Debt:On-premises server maintenance contracts create switching friction that anchors districts to incumbent providers despite superior cloud alternatives.
- Heuristic Limitations:Constraint satisfaction problems with 10,000+ variables occasionally produce suboptimal solutions requiring manual intervention, limiting full automation claims.
Strategic Opportunities
- EU AI Act:Algorithmic transparency requirements for automated scheduling recommendations will create certification premiums for compliant vendors in member-state deployments.
- Eastern Europe:Price-accessible deployment models remain underpenetrated outside German-speaking systems, opening volume opportunities in Poland and Czechia.
- SIS Convergence:Deep integration with student information systems creates platform stickiness that API-first architectures can monetize through modular expansion.
Industry Challenges
- Interoperability Certification:District procurement officers now weight total cost of ownership against IMS Global and Ed-Fi Alliance certifications, extending vendor evaluation timelines.
- Constraint Modeling Talent:Scarce operations research specialists capable of optimizing mixed-integer programming formulations command premium compensation that compresses vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Timetable Software Market |
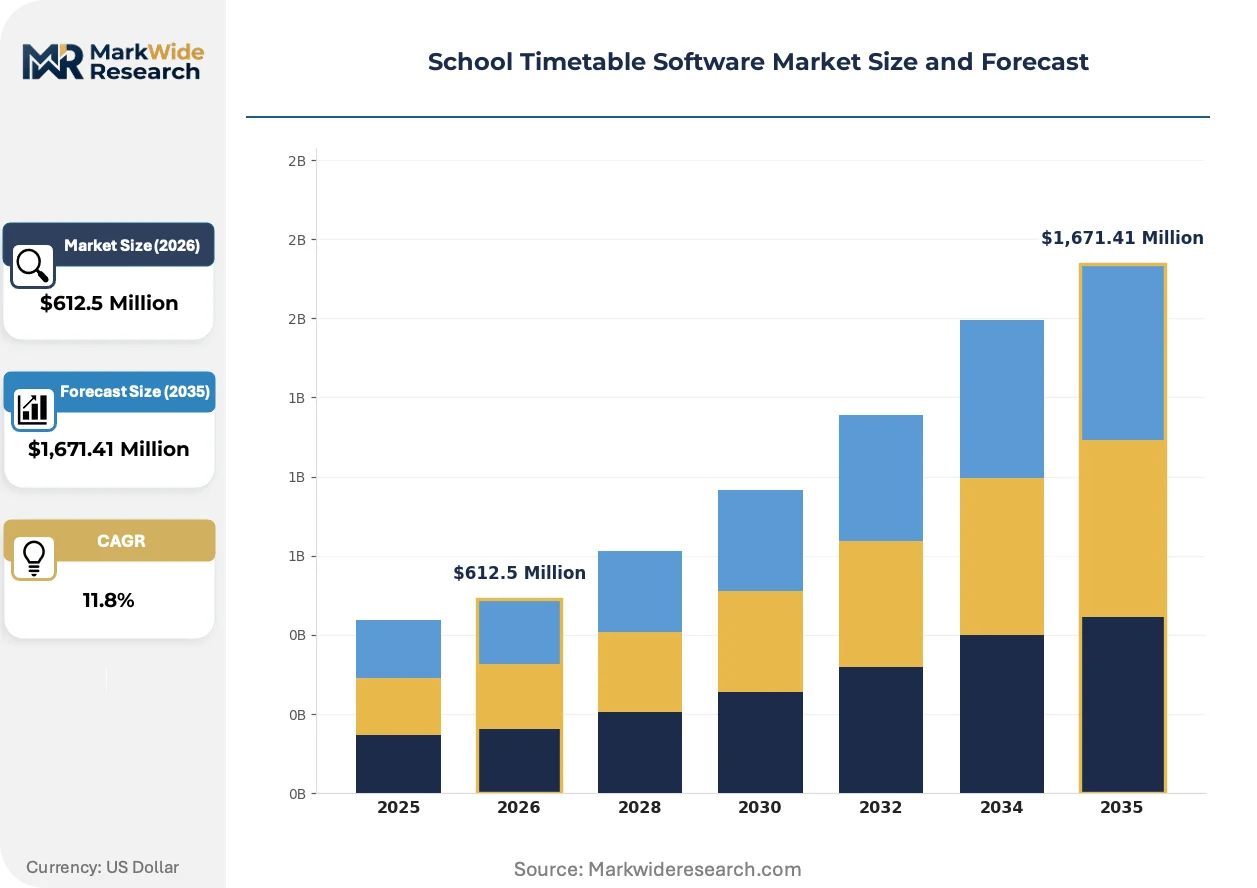
| Market Size in 2026 | $612.5 Million |
| Market Size in 2035 | $1,671.41 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS User Type: Administrators, Teachers, Students, Parents Feature Set: Automated Scheduling, Resource Management, Conflict Resolution, Customization Institution Size: Small Schools, Medium Schools, Large Schools, Educational Districts |
| Companies Covered | Untis, aSc Timetables, TimetableMaster, Prime Timetable, PowerSchool, EduSched, Classter, Skolaris, WebUntis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Timetable Software Market Trends and Innovations
API-first architectures are dismantling monolithic scheduling platforms while regulatory pressure on algorithmic transparency redefines competitive differentiation in European deployments.
Cloud-native SaaS delivery is overtaking hybrid configurations as the default procurement specification for North American K-12 districts. Mid-sized institutions in Texas and Florida are abandoning on-premises maintenance contracts entirely. This shift is compressing vendor revenue recognition from multi-year license fees to monthly recurring models that demand superior retention mechanics.
GDPR encryption mandates and the EU AI Act's algorithmic transparency requirements are reshaping European deployment architectures. Vendors must now document constraint-weighting logic for automated scheduling recommendations. German state education ministries are requiring explainable optimization outputs that expose teacher-to-room assignment rationale.
District procurement committees are consolidating vendor evaluation authority at the state level rather than individual school autonomy. California and New York education departments now maintain pre-approved platform shortlists that exclude non-integrated point solutions. This concentration favors established providers with existing SIS relationships while raising capital requirements for market entry.
School Timetable Software Market Segmentation
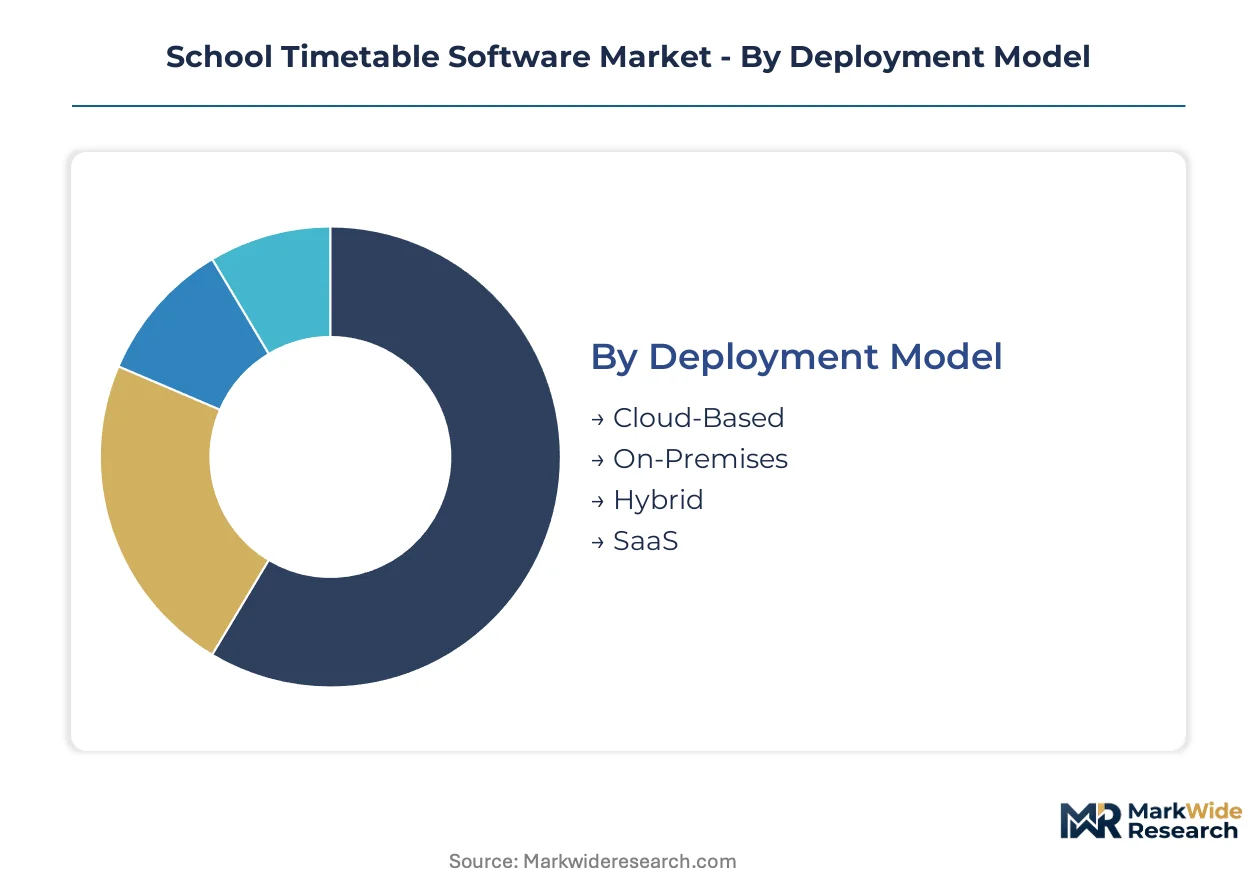
School timetable software procurement varies sharply by institutional capability and regulatory environment. Deployment preferences diverge between cash-constrained districts seeking operational efficiency and state-level buyers prioritizing data sovereignty. Understanding these segment boundaries clarifies where vendors must adapt pricing, compliance architecture, and integration depth.
Deployment Model:
Cloud-native platforms now command premium pricing while legacy installations persist where data residency requirements fragment procurement. Volume concentrates in subscription models that compress customer acquisition costs.
- Cloud-Based:Multi-tenant SaaS architectures deliver automatic updates and elastic scaling for districts abandoning server maintenance. Demand concentrates in Texas and Florida K-12 systems where FCC transmission guidelines accelerate compliant infrastructure investments.
- On-Premises:Single-tenant installations on district-owned hardware persist where German state ministries mandate data localization under GDPR terms. Procurement cycles extend 40-60 days as encryption standards undergo ministry review.
- Hybrid:Split configurations process sensitive student records locally while offloading scheduling computation to cloud instances. Australian multi-campus districts adopt this model where facilities-sharing complexity rises across consolidated footprints.
- SaaS:Pure subscription delivery with monthly recurring revenue recognition demands superior retention mechanics from vendors serving mid-tier institutions in Eastern Europe.
Mature deployment sits with On-Premises installations in German-speaking education systems. Newer deployment is concentrated in Cloud-Based platforms across North American districts.
User Type:
Administrative automation drives enterprise licensing value while parental access portals expand addressable user bases without proportional cost increases.
- Administrators:District scheduling officers require constraint-modeling dashboards that process 10,000+ variables through integer programming engines. Procurement authority has consolidated at state level in California and New York education departments.
- Teachers:Individual instructors need mobile-optimized views for room assignments and qualification-matched course loads. German state ministries now require explainable optimization outputs exposing assignment rationale under EU AI Act transparency mandates.
- Students:Self-service portal access for course selection and timetable viewing extends platform stickiness without core scheduling algorithm costs.
- Parents:Guardian-facing notification systems for schedule changes represent modular upsell opportunities in Australian consolidated district footprints.
Revenue concentration aligns with Administrator licensing. User expansion is climbing the fastest through Parent and Student portal modules.
Feature Set:
Core scheduling automation anchors procurement decisions while resource coordination modules capture expanding facilities-management budgets.
- Automated Scheduling:Algorithmic engines reduce manual timetable construction from weeks to hours using heuristic or mixed-integer programming methods. Constraint satisfaction limitations occasionally produce suboptimal solutions requiring manual intervention.
- Resource Management:Multi-campus room and equipment coordination functionality expands fastest where district consolidation creates shared-facility complexity in Australia and Germany.
- Conflict Resolution:Real-time detection algorithms flag instructor double-booking, room over-allocation, and regulatory hour limit violations before final timetable generation.
- Customization:Rule-configuration interfaces allow non-technical staff to adjust weighting parameters for local scheduling priorities without vendor intervention.
Feature maturity centers on Automated Scheduling. Capability investment is gaining share fastest in Resource Management modules.
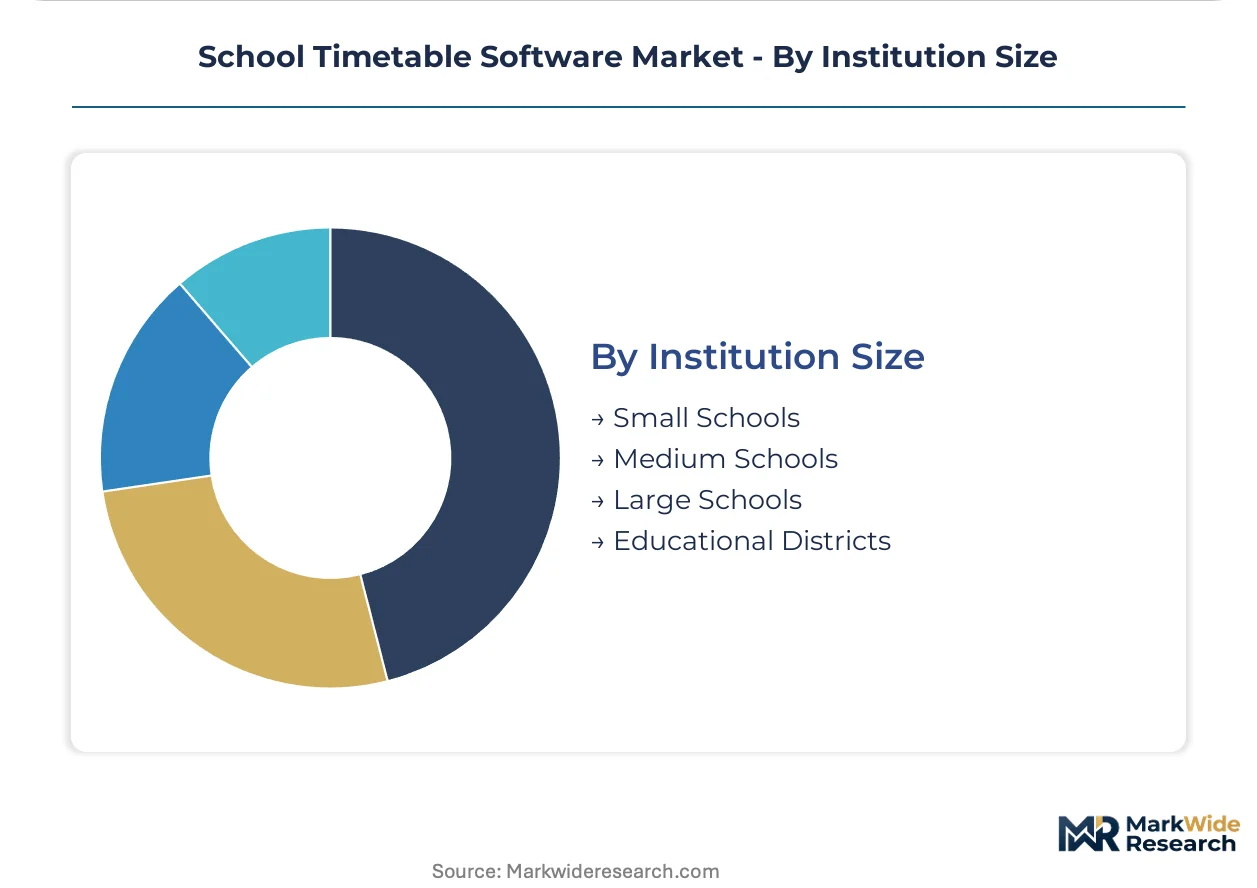
Institution Size:
Large-district procurement concentrates vendor revenue while small-school accessibility opens volume opportunities in underpenetrated markets.
- Small Schools:Price-accessible deployment models with simplified constraint sets serve institutions with limited IT staffing. Eastern European markets in Poland and Czechia show underpenetrated demand relative to German-speaking systems.
- Medium Schools:Mid-tier institutions balance functional depth against total cost of ownership, driving evaluation of API-first alternatives to legacy monolithic platforms.
- Large Schools:Complex multi-building campuses require advanced resource management and real-time conflict resolution at scale.
- Educational Districts:Consolidated procurement across 50+ schools demands SIS integration, statewide certification, and centralized administrative dashboards with role-based access controls.
Platform stickiness concentrates with Educational Districts through deep SIS integration. Addressable market expansion is steepest in Small Schools through price-accessible cloud delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States K-12 districts concentrate procurement authority at state level, with Texas and Florida accelerating cloud-native adoption. German state ministries maintain data localization mandates that fragment deployment models. Australian multi-campus consolidation drives resource management complexity. Eastern European markets remain underpenetrated relative to Western adoption curves.
United States
Texas and Florida districts abandon on-premises contracts entirely, compressing vendor revenue to monthly recurring models. FCC transmission guidelines for student data accelerate compliant cloud architecture investments. California and New York education departments now maintain pre-approved platform shortlists that exclude non-integrated point solutions.
Germany
State education ministries mandate explainable optimization outputs for teacher-to-room assignments under EU AI Act transparency requirements. GDPR encryption standards and data-localization terms extend contract negotiation cycles by 40-60 days. Bavaria and North Rhine-Westphalia sustain deployment density through decades of institutional relationships with specialized scheduling vendors.
Australia
Consolidated district footprints across New South Wales and Victoria create shared-facility coordination complexity that expands resource management module demand. Hybrid configurations persist where sensitive student records process locally while scheduling computation offloads to cloud instances. Queensland multi-campus districts drive fastest adoption of parent-facing notification systems.
Poland
Mid-tier institutions balance functional depth against total cost of ownership, opening volume opportunities for price-accessible deployment models. EU AI Act algorithmic transparency requirements will reshape procurement specifications as member-state compliance deadlines approach. Warsaw and Krakow educational clusters show accelerating evaluation of API-first alternatives to legacy monolithic platforms.
Canada
Ontario and Quebec school boards prioritize interoperability certifications from IMS Global and Ed-Fi Alliance when evaluating vendor shortlists. Provincial procurement committees consolidate evaluation authority, extending vendor assessment timelines. Health Canada data residency guidelines influence hybrid architecture decisions for districts with cross-border student populations.
School Timetable Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with established SIS-integrated platforms commanding premium positioning against modular point solutions. The vendor base concentrates around three strategic archetypes: deep-legacy European specialists with ministry relationships, North American platform consolidators with statewide procurement channels, and price-accessible challengers targeting mid-tier institutions. Competitive moves center on API-first architecture investments and SIS convergence through modular expansion.
Within the European specialist tier, Untis and aSc Timetables represent contrasting geographic anchoring strategies—Untis exemplifies decades-long institutional density in German-speaking education systems, while aSc Timetables occupies a position serving price-sensitive mid-tier markets in Eastern Europe and Latin America. PowerSchool anchors the North American landscape as a platform consolidator with deep SIS integration and statewide procurement relationships.
| Leading Market Players |
|---|
| Untis |
| aSc Timetables |
| TimetableMaster |
| Prime Timetable |
| PowerSchool |
| EduSched |
| Classter |
| Skolaris |
| WebUntis |
| Others |
Pricing and Supply Chain Analysis
Cloud-native SaaS migration simultaneously collapses server infrastructure costs for vendors and concentrates procurement authority among state-level education departments with certified vendor shortlists. This dual compression reshapes margin structures across deployment tiers while elevating compliance architecture to a primary cost driver.
Pricing Analysis
Volume concentrates in subscription SaaS models while margins accrue to API-integrated platform tiers. Three-tier pricing structure across premium, standard, and economy levels separates PowerSchool's statewide SIS bundles from aSc Timetables' mid-tier accessibility plays. Price differentiation hinges on Ed-Fi Alliance certification depth and multi-campus resource management module bundling. Cost compression in economy tiers intensifies as Eastern European districts demand functional parity at reduced licensing fees. Small schools in Poland and Czechia exhibit highest price sensitivity; consolidated Educational Districts in California and Texas show lowest sensitivity given total cost of ownership procurement frameworks.
Supply Chain Analysis
Ed-Fi Alliance and IMS Global certification gating restricts component supplier pools to established integration specialists. Software development concentrates in the United States, Germany, and Australia where regulatory familiarity anchors vendor density. Cloud infrastructure draws from hyperscaler networks with data residency requirements mandating EU-sovereign instances for German state deployments. Single-source vulnerability sits with legacy constraint-modeling algorithm libraries developed by scarce operations research specialists. Distribution runs through direct enterprise sales teams for Educational Districts and value-added resellers serving mid-tier institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The School Timetable Software Market reads as a cost-of-compliance story where EU AI Act algorithmic transparency mandates and GDPR encryption standards erect barrier-to-entry moats favoring incumbent vendors with ministry-established certification pathways.
For Market Incumbents: Deploy API-first architecture investments to dismantle monolithic platform switching costs before modular point solutions gain SIS integration parity. Untis and PowerSchool should deepen Ed-Fi Alliance certification moats against challenger encroachment. Threat vectors include heuristic optimization libraries from open-source constraint programming communities eroding proprietary algorithm premiums. Channel control through statewide procurement relationship lock-in represents the critical defensive lever. For New Entrants and Emerging Players: Specialized SIS integration partners offer the fastest path to procurement committee consideration without multi-year ministry relationship cultivation. White-space targets center on small schools in Poland and Czechia where price-accessible cloud delivery remains underpenetrated relative to German-speaking system density. Parent-facing notification modules in Australian consolidated districts represent modular upsell entry points with minimal core scheduling algorithm development requirements. For Investors and Strategic Acquirers: Re-rating potential sits with API-first challengers exhibiting SIS convergence capability given state-level procurement consolidation trends. Long-term viability over a multi-year horizon favors vendors with demonstrated GDPR and EU AI Act compliance architecture rather than feature-depth alone. Acquisition target archetypes include constraint-modeling specialists with explainable optimization IP. The signal to watch is California or New York education department pre-approved shortlist expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep SIS convergence creates procurement stickiness through Ed-Fi Alliance certification pathways. |
| Geographic Expansion | Eastern European small-school penetration captures volume before German ministry relationships solidify. |
| Product Launch | Explainable optimization dashboards satisfy EU AI Act transparency mandates for German state tenders. |
| Strategic Partnership | Hyperscaler data residency agreements enable GDPR-compliant cloud instances for Bavaria deployments. |
| Acquisition of Specialist Firm | Constraint-modeling talent scarcity makes operations research boutiques attractive capability purchases. |
Research Methodology
Independent corroboration across district procurement officers, SIS integration specialists, and state education department technology directors underwrites the qualitative findings. Primary interviews with CTOs at consolidated Educational Districts, platform engineers at API-first vendors, and channel partners serving Eastern European mid-tier institutions combined with secondary validation. Secondary sources encompassed SEC filings from publicly traded education technology platforms, Ed-Fi Alliance interoperability certification databases, and GDPR compliance disclosure repositories. Bottom-up deployment model sizing and top-down education technology budget allocation analysis provided triangulation anchors.
Historical reference periods anchored the projection horizon to pre-pandemic procurement baselines and post-cloud-migration acceleration phases. Segmentation dimensions modeled encompassed deployment model, institution size, feature set complexity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves across the analysis window. Industry-specific forecast inputs included state-level procurement consolidation timelines and EU AI Act member-state implementation sequencing.
Caveats apply where FCC guideline revisions or GDPR enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions regarding cloud infrastructure cost trajectories and constraint-modeling specialist labor market tightness. A model refresh is warranted upon material change in state education department pre-approved vendor shortlist criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Telecom IT Services Market
Software & Services
Compensation Software Market
Software & Services
Software Construction Components Market
Software & Services
Preventive Maintenance Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
PCB Layout Software Market
Software & Services
ITSM Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Automated Testing Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Global Application Management Services Market
Software & Services
Business Productivity Software Market