
 Content Distribution Software Market | 2026-2036
Content Distribution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Content Distribution Software Market Outlook
Multi-vendor sourcing strategies is broadening procurement flexibility across enterprise buyers. Hootsuite leverages its established social media marketing footprint to sustain channel control among mid-market agencies. Buffer anchors its competitive stance through freemium-to-paid conversion mechanics that dominate small-business segments. HubSpot extends its CRM-integrated content operations to occupy a differentiated position against standalone distribution tools.
Content distribution software orchestrates the routing, formatting, and delivery of digital assets across endpoints including CDNs, social platforms, and proprietary applications through API-driven orchestration layers. The primary commercial purpose centers on reducing latency, ensuring format compliance, and enabling centralized governance of multi-channel publishing workflows. Cloud-based deployment leads structural adoption as enterprises abandon on-premises maintenance overhead, while streaming software within product categories captures accelerated investment tied to live video monetization. Edge computing deployment shows nascent traction among latency-sensitive mobile application publishers seeking sub-second content rendering.
FCC guidelines on digital media accessibility and the EU AI Act's transparency mandates for algorithmic content curation shape vendor certification requirements across transatlantic deployments. GDPR data-localization rules constrain cross-border content routing architectures, forcing hybrid deployment configurations in European operations. Stakeholders must monitor emerging interoperability standards between DAM systems and generative AI pipelines as these integrations determine future platform switching costs.
Market Dynamics
Cloud-native orchestration layers are compressing deployment timelines for enterprise content distribution, forcing vendors to abandon monolithic architectures in favor of API-driven microservices that reduce latency across multi-CDN environments.
Growth Catalysts
- GDPR Data-Localization Mandates:European enterprises must route content through regionally compliant infrastructure, creating sustained demand for hybrid cloud-edge configurations that satisfy CNIL and national DPA requirements.
- Live Video Monetization:Streaming platforms in the United States are deploying real-time ad-insertion stacks that require sub-second content rendering capabilities at the edge.
- API-Driven Orchestration:Mid-market agencies now demand programmable distribution workflows that integrate DAM systems with social publishing endpoints through standardized REST interfaces.
Market Restraints
- Cross-Border Routing Friction:GDPR Article 44 restrictions on international data transfers force European operators to maintain duplicate infrastructure across jurisdictions, elevating operational overhead.
- Compute Cost Volatility:Edge computing deployments for mobile application publishers face unpredictable egress pricing from hyperscale cloud providers, compressing margin predictability.
- Format Fragmentation:Proprietary codecs from device manufacturers create technical lock-in that limits interoperability between distribution stacks and endpoint hardware.
Strategic Opportunities
- Generative AI Pipeline Integration:DAM vendors that embed automated asset variation engines can capture workflow budgets currently allocated to standalone creative tools.
- India PLI Scheme for Digital Infrastructure:Domestic content platforms qualify for production-linked incentives when deploying localized distribution nodes, accelerating capex deployment.
- Outcome-Based Licensing Models:Publishers in Germany and France are piloting consumption-metered contracts that tie vendor fees to actual delivery performance rather than seat counts.
Industry Challenges
- Multi-Cloud Skill Scarcity:Platform engineering teams lack depth in Kubernetes-native orchestration across AWS, Azure, and GCP simultaneously, delaying edge deployment timelines.
- EU AI Act Certification Burden:Algorithmic content curation tools require documented transparency audits before deployment, extending sales cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Distribution Software Market |
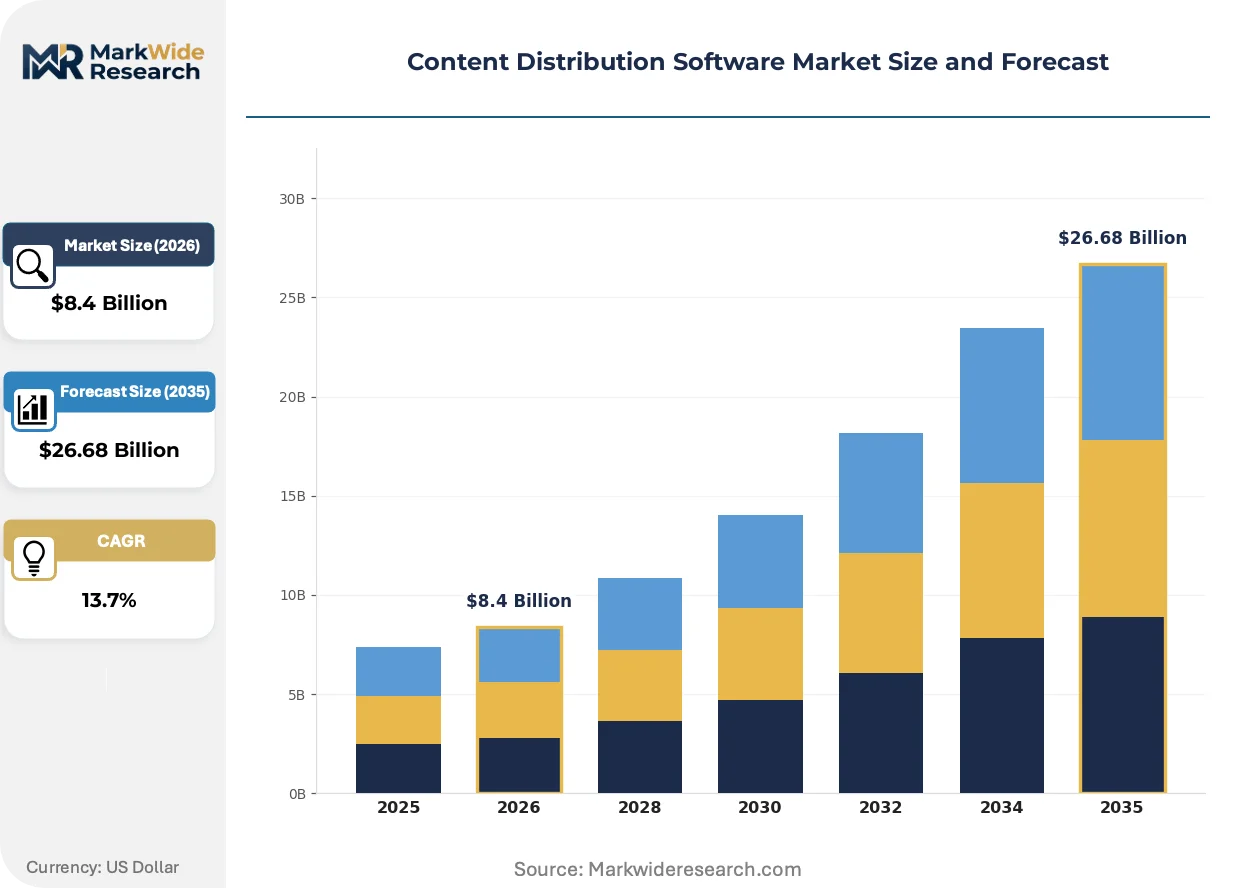
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premises, Cloud-Based, Hybrid, Edge Computing Product Type: Digital Asset Management, Content Delivery Network, Media Asset Management, Streaming Software Application: Video Streaming, E-Learning, Social Media Marketing, Mobile Applications End User: Enterprises, Media Companies, Educational Institutions, Independent Creators |
| Companies Covered | Sprout Social, StoryChief, Hootsuite, SalesboxAI, CoSchedule, Buffer, Bynder, ContentStudio, HubSpot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Distribution Software Market Strategic Shifts
Edge-native rendering stacks and automated compliance tooling are compressing the traditional boundary between content creation and distribution, enabling real-time personalization that was previously architecturally infeasible.
WebAssembly modules executing at the edge are rewriting latency benchmarks for mobile content delivery. Gaming publishers and short-form video platforms are deploying these lightweight runtimes to achieve sub-100 millisecond asset personalization without round-trips to origin servers. This compression of rendering geography is collapsing the distinction between CDN and application server.
The EU AI Act's transparency requirements for algorithmic content ranking are forcing distributors to deploy explainable curation engines. Vendors must now document training data provenance and decision logic for European deployments, with France's CNIL already issuing preliminary guidance on audit scope. Enterprise buyers in Germany are prioritizing vendors with pre-certified compliance documentation.
Mid-market agencies are consolidating vendor relationships around vertically integrated suites that combine scheduling, analytics, and distribution. This preference compression disadvantages standalone point solutions that require manual data export for performance reporting. The United States shows the clearest concentration of this behavior, with independent creator networks driving platform switching at eighteen-month cycles.
Content Distribution Software Market Segmentation
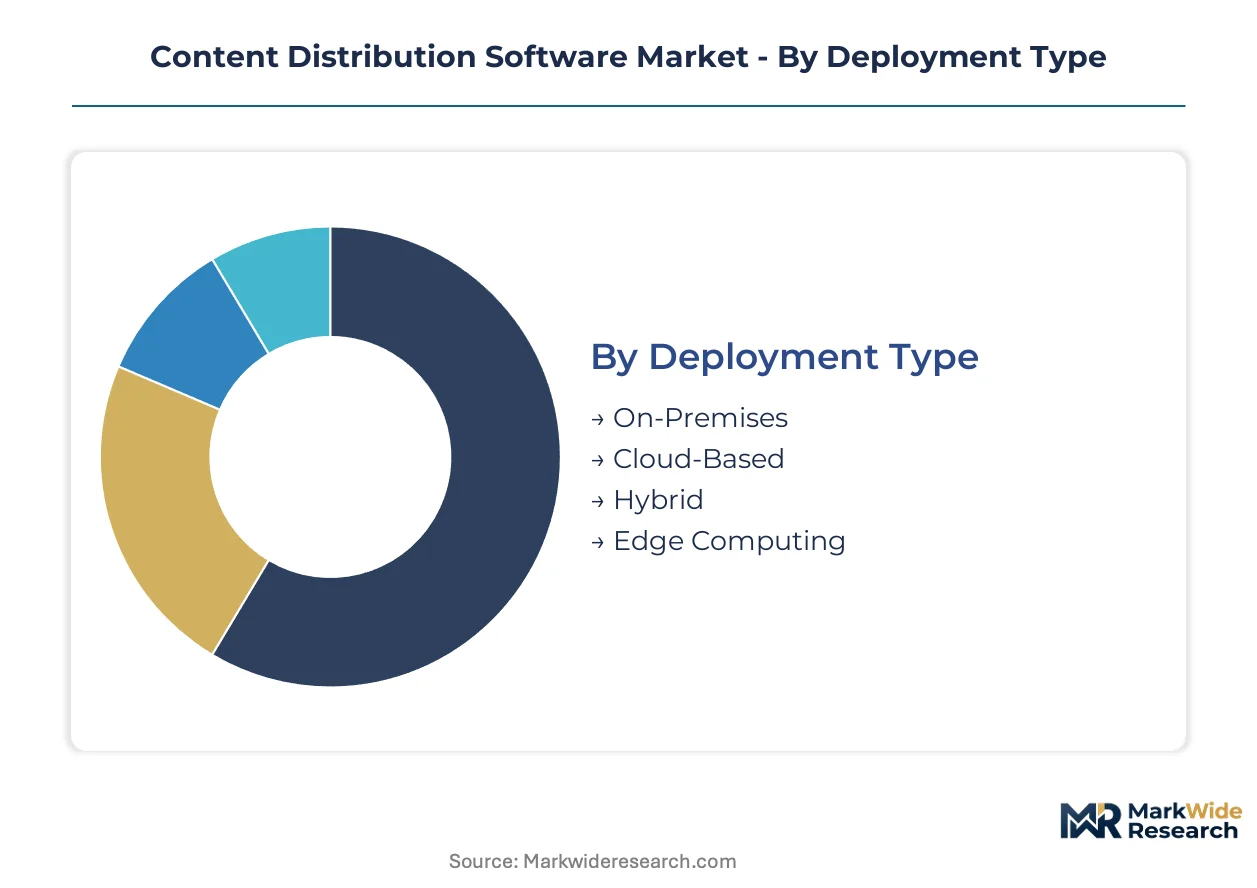
Content distribution software segments reflect divergent infrastructure requirements across latency sensitivity, compliance obligations, and monetization models. Deployment architecture and product category selection directly determine routing economics, regulatory exposure, and integration complexity for buyers.
Deployment Type:
Cloud-native orchestration layers now dominate procurement decisions as enterprises prioritize API-driven scalability over capital-intensive infrastructure ownership.
- Cloud-Based:Fully managed SaaS stacks eliminate on-premises maintenance overhead while enabling elastic scaling across multi-CDN environments. Demand concentrates among mid-market agencies in the United States seeking programmable distribution workflows without platform engineering depth.
- Hybrid:Split architectures route sensitive metadata through private infrastructure while pushing high-volume assets to public edge nodes. European enterprises under GDPR Article 44 constraints deploy hybrid configurations to satisfy CNIL and national DPA data-localization mandates without sacrificing delivery performance.
- On-Premises:Legacy installations persist in highly regulated sectors requiring air-gapped content governance and direct hardware control over encryption key management.
- Edge Computing:Lightweight runtime deployment at network periphery achieves sub-100 millisecond rendering for latency-sensitive mobile gaming and short-form video personalization.
Cloud-Based leads on scale; Edge Computing leads on momentum.
Product Type:
Functional specialization within distribution stacks correlates with buyer maturity and workflow integration depth.
- Streaming Software:Real-time ad-insertion and monetization engines command premium positioning as live video platforms demand sub-second rendering capabilities. Investment concentrates among United States enterprise streaming operators building direct-to-consumer revenue models.
- Digital Asset Management:Centralized repositories with automated metadata tagging and rights management anchor creative-to-distribution pipelines. Mid-market agencies prioritize DAM systems with embedded generative AI variation engines to consolidate workflow budgets.
- Content Delivery Network:Distributed caching infrastructure remains foundational for high-volume publishers, though differentiation shifts toward edge-native WebAssembly execution and programmable traffic routing.
- Media Asset Management:Broadcast-grade transcoding and format compliance tools serve legacy media workflows requiring frame-accurate editing and multi-format distribution to proprietary hardware endpoints.
Streaming Software commands the steepest expansion trajectory; Digital Asset Management captures the broadest addressable base.
Application:
End-use context dictates performance thresholds, compliance scope, and integration architecture for distribution procurement.
- Video Streaming:Live and on-demand video delivery requires adaptive bitrate protocols, DRM integration, and real-time analytics for quality-of-experience monitoring.
- Mobile Applications:Native app publishers prioritize edge-rendered personalization and offline content synchronization to minimize cellular data consumption.
- Social Media Marketing:Cross-platform scheduling and automated format conversion dominate agency requirements, with API reliability determining vendor stickiness.
- E-Learning:Accessibility compliance and progress-tracking metadata shape procurement for educational deployments across institutional and corporate training contexts.
Video Streaming absorbs the largest infrastructure budgets; Mobile Applications show the fastest feature innovation cycle.
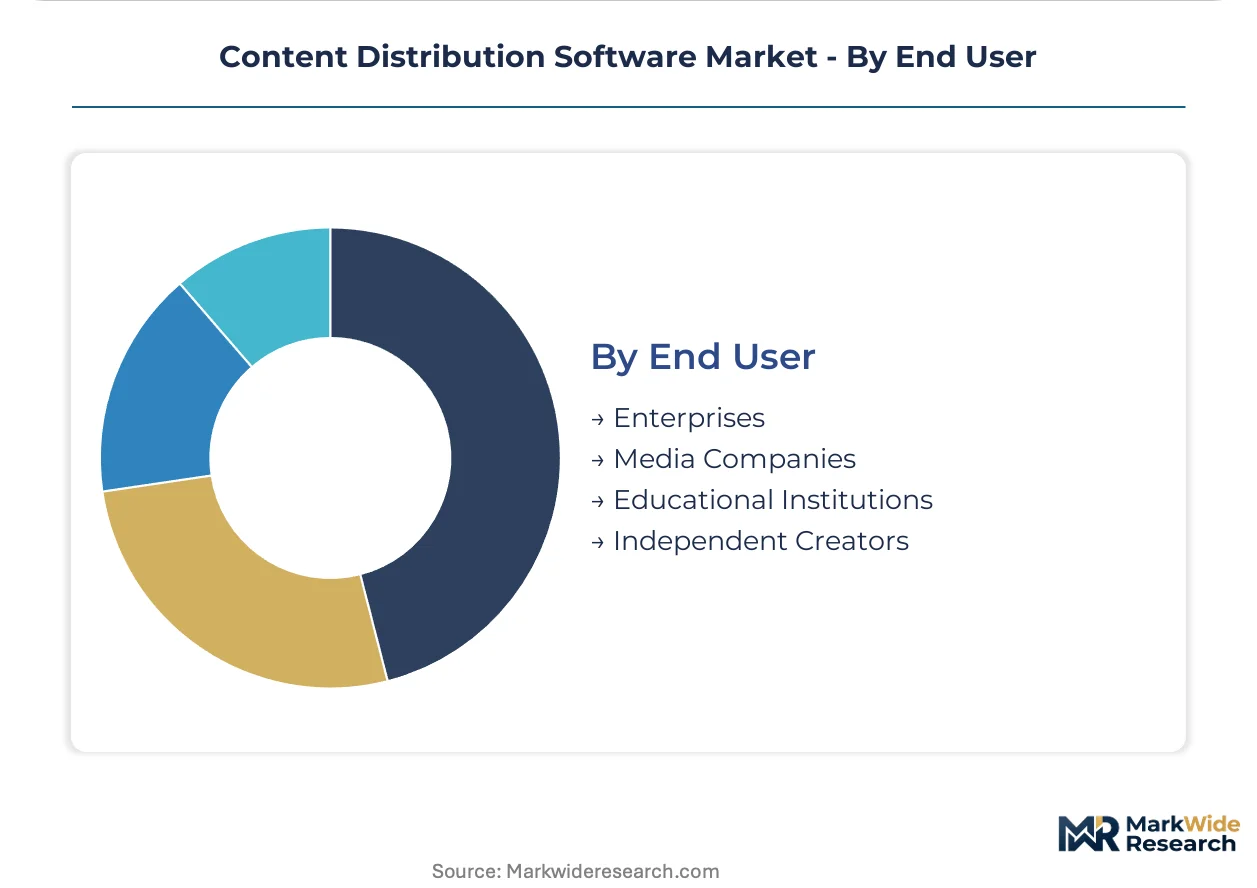
End User:
Organizational scale and content monetization model create distinct purchasing behaviors and platform requirements.
- Enterprises:Fortune 500 corporations deploy integrated suites combining DAM, analytics, and distribution through centralized procurement functions with eighteen-month vendor evaluation cycles.
- Media Companies:Broadcasters and publishers maintain hybrid legacy-cloud architectures while migrating advertising technology stacks to cloud-native infrastructure.
- Independent Creators:Freelance operators and small networks drive platform switching at compressed cycles, prioritizing freemium entry points and intuitive scheduling interfaces over advanced orchestration capabilities.
- Educational Institutions:Universities and K-12 districts require FERPA-compliant routing and accessibility certification under FCC digital media guidelines.
Enterprises anchor aggregate revenue; Independent Creators drive the highest platform churn velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors enterprise streaming platform development, while London's financial services sector drives compliance-heavy procurement. Regulatory fragmentation across data sovereignty regimes is forcing vendors to architect region-specific deployment configurations.
United States
Enterprise streaming platforms and independent creator networks dominate procurement, with real-time ad-insertion stacks commanding premium investment. FCC digital media accessibility guidelines shape vendor certification requirements for broadcast-grade deployments. Los Angeles and New York media clusters drive platform switching at compressed eighteen-month cycles among creator networks.
Germany
Industrial publishers and automotive marketing divisions prioritize GDPR Article 44 compliant hybrid architectures. Germany's national data protection authority enforces strict data-localization mandates that constrain cross-border content routing. Berlin and Munich enterprise clusters pilot outcome-based licensing models tying vendor fees to delivery performance metrics.
United Kingdom
Mid-market agencies consolidate around vertically integrated suites combining scheduling, analytics, and distribution workflows. The UK Information Commissioner's Office enforces GDPR-aligned transparency requirements for algorithmic content curation tools. London's financial services marketing clusters demand sub-second edge rendering for mobile application personalization.
India
Domestic content platforms accelerate capital expenditure through PLI scheme incentives for localized distribution node deployment. TRAI regulations on digital content governance shape infrastructure localization requirements for foreign vendors. Bangalore and Mumbai technology clusters drive API-driven orchestration adoption among mid-market publishers.
France
Media companies deploy explainable curation engines to satisfy CNIL preliminary guidance on EU AI Act audit scope. France's national data protection authority mandates documented training data provenance for algorithmic content ranking systems. Paris broadcast clusters maintain hybrid legacy-cloud architectures while migrating advertising technology stacks to cloud-native infrastructure.
Content Distribution Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue edge-native specialization and generative AI pipeline integration. The vendor base stratifies across three maturity tiers: legacy social media marketing suites, cloud-native orchestration specialists, and CRM-integrated content operations platforms. Strategic archetypes include freemium conversion engines, enterprise workflow consolidators, and API-first infrastructure providers. Dominant competitive moves encompass M&A activity targeting DAM-to-distribution workflow integration and strategic partnerships with hyperscale cloud providers for edge node placement.
Within the social media marketing suite tier, Hootsuite and Buffer exemplify divergent go-to-market architectures—Hootsuite leverages channel control among mid-market agencies while Buffer anchors small-business segments through freemium mechanics. HubSpot occupies a differentiated position against standalone distribution tools through CRM-integrated content operations. Sprout Social represents the premium-agency archetype with scheduling-analytics consolidation. These four companies collectively illustrate how vertical integration depth determines procurement stickiness across organizational scale segments.
| Leading Market Players |
|---|
| Sprout Social |
| StoryChief |
| Hootsuite |
| SalesboxAI |
| CoSchedule |
| Buffer |
| Bynder |
| ContentStudio |
| HubSpot |
| Others |
Value Chain & Pricing Dynamics
EU AI Act compliance mandates gate both qualified supply and premium-tier pricing access, as vendors must document algorithmic transparency and training data provenance before deploying curation engines in European operations. Buyers in Germany and France now demand pre-certified documentation, compressing procurement timelines for compliant vendors while elevating price floors for non-compliant alternatives.
Pricing Analysis
Input-cost pass-through from hyperscale cloud egress fees is compressing margin predictability for edge computing deployments, particularly among mobile application publishers. Three-tier pricing structure across premium, standard, and economy levels dominates SaaS procurement, with differentiation anchored in API call volume thresholds and GDPR certification status. Pricing pressure stems from outcome-based licensing pilots in Germany and France that tie vendor fees to delivery performance rather than seat counts. Independent creator networks exhibit highest price sensitivity, while Fortune 500 enterprises prioritize integration depth over unit cost.
Supply Chain Analysis
Warehouse-distribution layer configurations for content delivery networks concentrate in the United States, Ireland, and Singapore to minimize latency across transatlantic and Asia-Pacific corridors. Infrastructure deployment draws from specialized edge hardware manufacturers, hyperscale cloud compute providers, and proprietary transcoding chip fabricators. Single-source vulnerability persists in WebAssembly runtime modules, where limited qualified vendors constrain substitution options. Distribution runs through hub-and-spoke architectures with regional edge nodes feeding last-mile ISP interconnections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States live video monetization investment and European compliance-heavy procurement creates divergent margin profiles, with GDPR-constrained deployments commanding premium pricing for hybrid infrastructure.
For Market Incumbents: Cement channel control among mid-market agencies through API reliability guarantees and vertically integrated scheduling-analytics suites. Invest in pre-certified EU AI Act documentation to compress sales cycles in France and Germany. Acquire generative AI pipeline specialists to capture workflow budgets currently allocated to standalone creative tools. For New Entrants and Emerging Players: API-first infrastructure routes offer the most penetrable entry vector for latency-sensitive mobile gaming publishers seeking sub-100 millisecond rendering alternatives. Target India PLI scheme beneficiaries with localized distribution node offerings. Lead with consumption-metered pricing to differentiate from incumbent seat-based models. For Investors and Strategic Acquirers: Roll-up economics work for DAM-to-distribution workflow integrators because mid-market agencies are consolidating vendor relationships around vertically integrated suites. Long-term viability favors vendors with edge-native WebAssembly execution capabilities and pre-built GDPR compliance documentation. Watch for hyperscale cloud provider edge partnership announcements as inflection indicators for infrastructure scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Pipeline Integration | Captures creative workflow budgets by embedding automated asset variation engines within DAM systems. |
| EU AI Act Pre-Certification | Compresses sales cycles by four to six months in France and Germany through documented transparency audits. |
| Edge Node Localization | Qualifies India-based platforms for PLI scheme incentives while satisfying TRAI data governance requirements. |
| Outcome-Based Licensing | Aligns vendor fees with delivery performance metrics, piloting among publishers in Berlin and Munich clusters. |
| Hyperscale Cloud Partnership | Secures preferential egress pricing and geographic node placement for latency-sensitive mobile applications. |
Study Parameters
Coverage spans the United States, Germany, United Kingdom, India, and France, with primary inputs from each market combining executive interviews with platform engineers, IT procurement officers, channel partners, and integration specialists. Secondary validation draws from SEC filings, hyperscaler capex disclosures, TRAI regulatory circulars, and CNIL guidance documents. Bottom-up deployment estimates and top-down market sizing were triangulated to reconcile vendor-reported metrics with infrastructure investment patterns.
Rate-of-change decomposition across the analysis window segments projections by deployment model, organization size, vertical integration depth, and regional compliance framework. CAGRs were derived from elasticity modeling of infrastructure investment against monetization revenue growth, with specific inputs including live video ad-insertion stack deployment rates and GDPR-constrained procurement cycle durations.
The model assumes a particular technology adoption path for WebAssembly edge execution; alternative pathways for containerized microservices would alter the outlook for latency benchmark achievement. Forecasts reflect documented assumptions regarding cloud egress pricing stability and EU AI Act enforcement timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Sweepstakes Software Market
Software & Services
Global Database Management Software Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Stone Analysis Software Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
Video Converter Software Market
Software & Services
Geomechanics Software and Service Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
System Infrastructure Software Market
Software & Services
Global Polling Software Market
Software & Services
Collaboration Software Market
Software & Services
Human Identification Analysis Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Change Control Management Software Market