
 Keratoacanthoma Market | 2026-2036
Keratoacanthoma Market Size, Share, and Industry Trends Forecast 2026-2036
Keratoacanthoma Market Foresight
The gap between premium biologic interventions and commodity surgical excision is broadening as payers impose stricter prior-authorization tiers. Glenmark Pharmaceuticals leverages its generic dermatology portfolio to compete on cost across emerging markets. Siemens sustains technology leadership through advanced dermoscopy imaging systems that guide precision excision. Pfizer anchors its position via oncology-aligned R&D pipelines targeting squamous proliferative disorders.
Keratoacanthoma denotes a rapidly growing, dome-shaped squamous epidermal tumor typically measuring 1-2 centimeters with a central keratin plug, treated primarily to prevent misdiagnosis as squamous cell carcinoma and to achieve definitive cosmetic outcomes. Surgical interventions occupy the dominant revenue position due to immediate pathological confirmation and lowest recurrence rates, while topical agents represent the fastest-expanding category as patient preference shifts toward non-scarring alternatives. The extremity lesions segment navigates higher recurrence complexity, creating specialized margin requirements that sustain premium pricing for advanced modalities.
The FDA regulates all pharmacologic treatments through dermatologic division pathways, while the EMA's MDR framework governs surgical device conformity across European markets, collectively elevating clinical evidence thresholds for market entry. Health Canada and Australia's TGA impose parallel post-market surveillance obligations that extend compliance costs for multinational manufacturers. Stakeholders must monitor evolving histopathological classification standards that could reclassify keratoacanthoma management pathways entirely.
Market Dynamics
The FDA's accelerated dermatologic approval pathways are compressing commercialization timelines for novel lesion management modalities while simultaneously elevating evidentiary requirements for surgical device clearance.
Growth Catalysts
- Specialist procedural volume expansion:Dermatology clinics in the United States are expanding excision capacity to address rising patient throughput for suspicious dome-shaped lesions.
- EMA MDR framework harmonization:Streamlined surgical device conformity assessments across European markets are reducing multi-country registration burdens for excision tool manufacturers.
- Non-scarring topical innovation:Patient preference migration toward cosmetic-preserving alternatives is pulling R&D investment into pharmacologic lesion regression agents.
Market Restraints
- Histopathological classification uncertainty:Ongoing debate over keratoacanthoma versus squamous cell carcinoma diagnostic boundaries complicates reimbursement coding and clinical trial design.
- Specialist workforce concentration:Board-certified dermatologists cluster in urban United States corridors, leaving rural and exurban markets underserved for complex margin planning.
- Prior-authorization tier escalation:United States commercial payers are tightening biologic coverage criteria, forcing patients toward lower-reimbursement surgical alternatives.
Strategic Opportunities
- Telemedicine-integrated triage:Remote dermoscopic screening platforms in Australia are expanding access to specialist assessment for remote and indigenous populations.
- Combination therapy protocols:Sequential topical-surgical regimens are emerging as a reimbursable category for extremity lesions with elevated recurrence risk.
- Health Canada parallel review:Synchronized FDA-TGA-Health Canada submission pathways are compressing time-to-market for novel lesion management devices.
Industry Challenges
- Dermoscopy interpretation standardization:Variable training curricula across residency programs produce inconsistent diagnostic accuracy for keratoacanthoma versus malignant mimics.
- Margin width protocol fragmentation:Absent consensus guidelines force individual practices to develop institution-specific excision parameters, complicating multi-site clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keratoacanthoma Market |
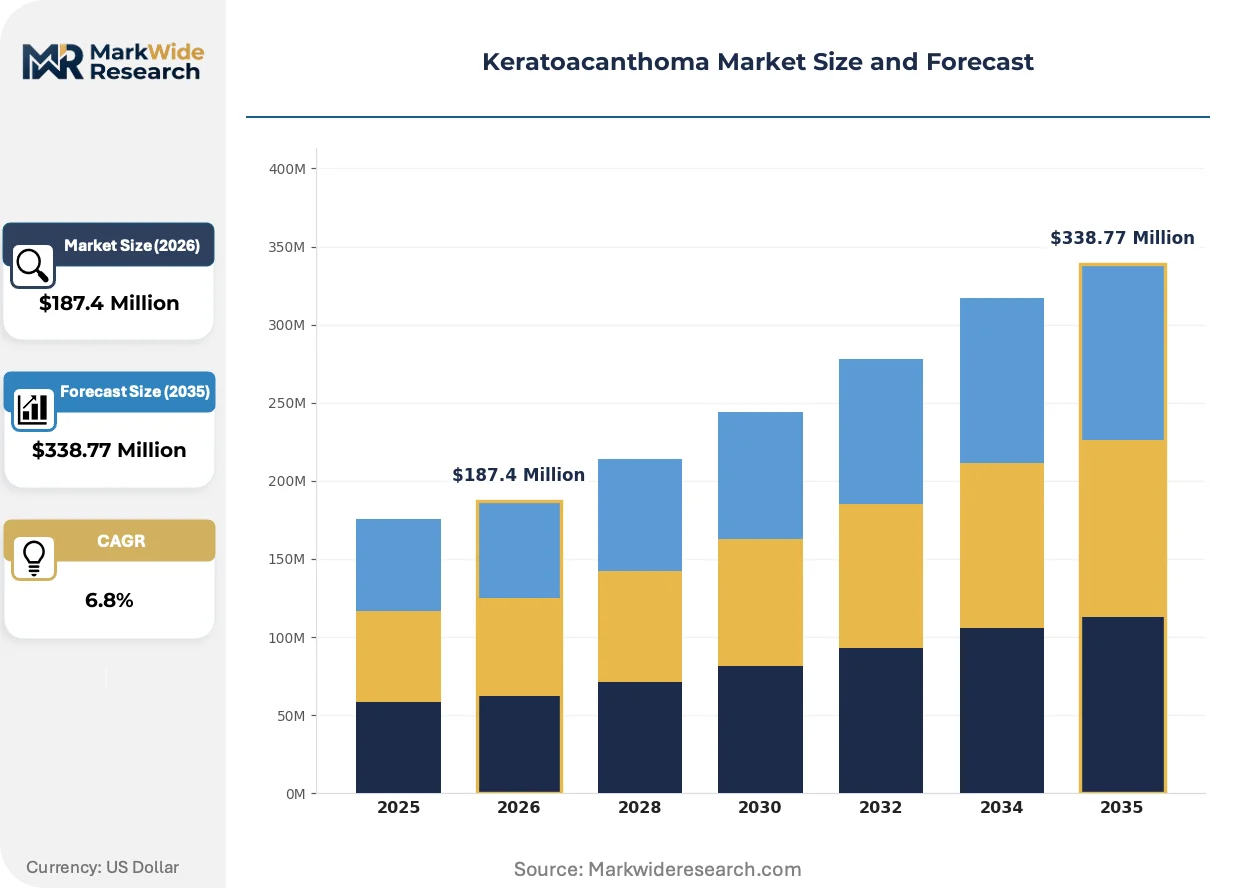
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Medications, Surgical Interventions, Radiation Therapy Indication: Facial Lesions, Scalp Lesions, Extremity Lesions, Rare Variants End User: Dermatology Clinics, Hospitals, Research Institutions, Home Care Treatment Phase: Diagnosis, Initiation, Maintenance, Follow-up |
| Companies Covered | Glenmark Pharmaceuticals Ltd, Siemens, Cipla, Almirall, Biofrontera AG, GE HealthCare, Sun Pharmaceutical Industries Ltd, Bristol Myers Squibb, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keratoacanthoma Market Shifts & Advancements
Digital pathology integration and artificial intelligence-assisted margin assessment are restructuring how lesion management decisions are made, validated, and reimbursed across outpatient settings.
Reflectance confocal microscopy is overtaking traditional dermoscopy for pre-excisional characterization of dome-shaped lesions. United States academic medical centers are deploying this technology to reduce unnecessary wide-local excisions. The shift is compressing demand for invasive diagnostic biopsies while elevating capital requirements for outpatient dermatology practices.
REACH chemical safety assessments are extending compliance obligations for topical formulation excipients across European manufacturing operations. Suppliers must now document full substance toxicity profiles for preservative systems used in lesion regression creams. German and French formulators are responding by reformulating toward bio-based alternatives with established safety dossiers.
Patient-initiated second-opinion platforms are disrupting traditional referral pathways for suspicious skin lesions. United States consumers now upload dermoscopic images to subscription services before scheduling in-person consultations. This behavior concentrates demand in metropolitan markets with rapid turnaround pathology services while delaying presentation in underserved regions.
Keratoacanthoma Market Segmentation
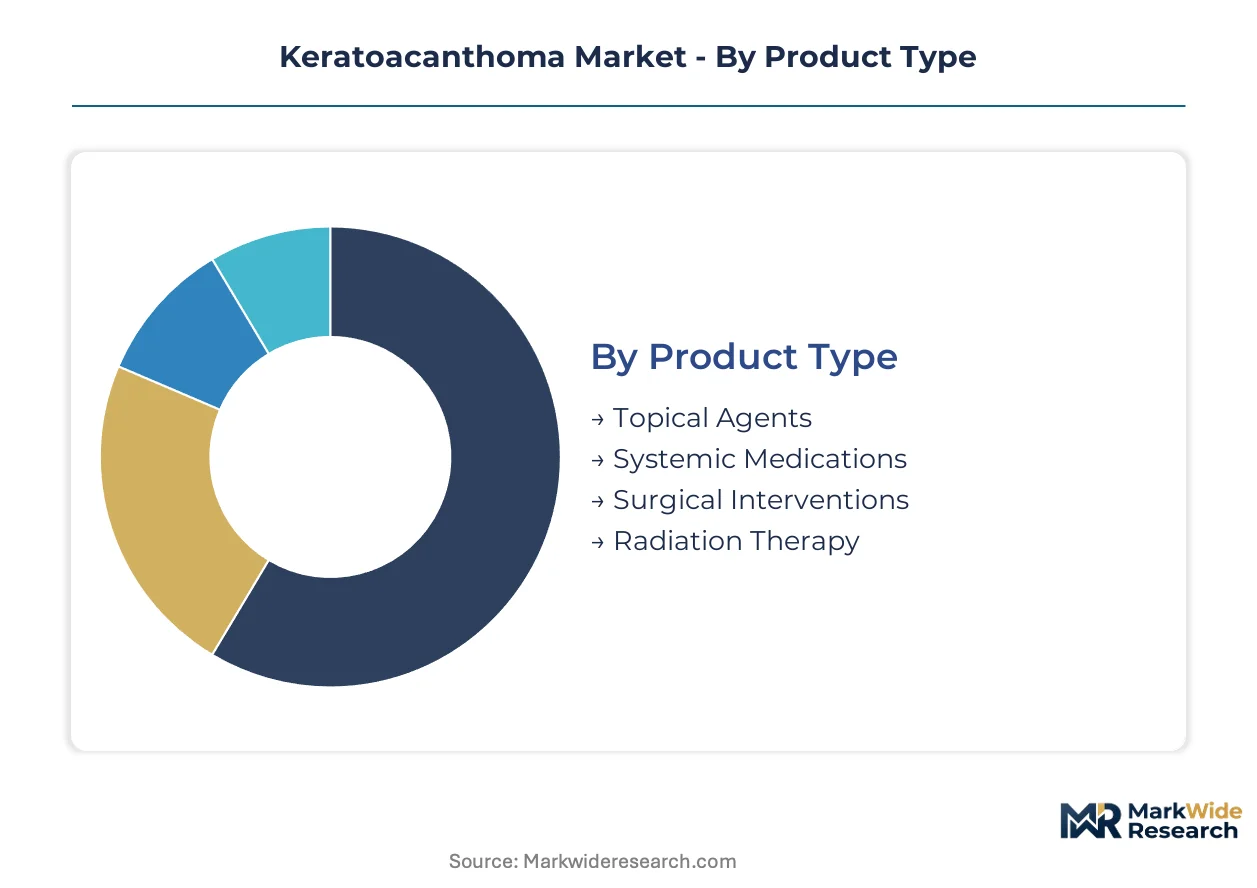
Segmentation in keratoacanthoma management reveals how treatment modality selection varies by lesion location, care setting, and disease progression stage. Each dimension carries distinct reimbursement codes, regulatory pathways, and capital requirements that shape commercial strategy.
Product Type:
Integration depth varies sharply: surgical interventions function as standalone definitive procedures, while topical agents embed within multi-phase regimens requiring sequential monitoring.
- Surgical Interventions:Excision with margin control provides immediate histopathological confirmation and lowest recurrence rates. Demand concentrates in United States metropolitan dermatology clinics where specialist density supports complex facial reconstructions and payers reimburse wide-local excision at premium rates.
- Topical Agents:Pharmacologic lesion regression creams and immune-modulating gels target patients prioritizing cosmetic preservation. Research institutions in Germany and Australia are driving protocol development for sequential topical-surgical combinations in extremity lesions.
- Systemic Medications:Oral retinoids and targeted agents address rare disseminated variants or patients with multiple synchronous lesions.
- Radiation Therapy:Adjunctive electron beam applications serve surgical contraindications in elderly patients or challenging anatomical sites.
Surgical interventions lead volumes today; topical agents are gaining share fastest.
Indication:
Cost tier stratification emerges from margin complexity and reconstruction requirements across anatomical zones.
- Facial Lesions:Central aesthetic zone tumors demand Mohs micrographic surgery or staged excision with flap closure. United States academic medical centers report highest procedural volumes due to concentrated reconstructive expertise and favorable cosmetic outcome reimbursement.
- Extremity Lesions:Lower recurrence complexity on limbs permits narrower margins, though hand and foot locations sustain premium pricing for functional preservation. Australian rural telemedicine programs prioritize this segment for remote triage protocols.
- Scalp Lesions:Hair-bearing tissue complicates margin assessment and reconstruction planning.
- Rare Variants:Keratoacanthoma centrifugum marginatum and multiple self-healing variants require specialized multidisciplinary management.
Facial lesions command highest revenue per procedure; extremity lesions show steepest expansion trajectory through community clinic penetration.
End User:
Volume distribution tracks specialist workforce geography and capital equipment availability.
- Dermatology Clinics:Outpatient surgical suites equipped with dermoscopy and histopathology partnerships manage standard excisions and topical protocols. United States private practice networks in Florida and California are expanding dedicated lesion management capacity.
- Hospitals:Academic centers handle complex reconstructions, rare variants, and combination therapy trials. German university hospitals lead European protocol standardization efforts.
- Research Institutions:Phase II topical agent studies and diagnostic biomarker development occur primarily in Australian and Canadian centers with aligned regulatory pathways.
- Home Care:Post-excision wound management and topical agent application support limited monitoring functions.
Dermatology clinics capture majority volume; research institutions are expanding fastest through clinical trial site activation.
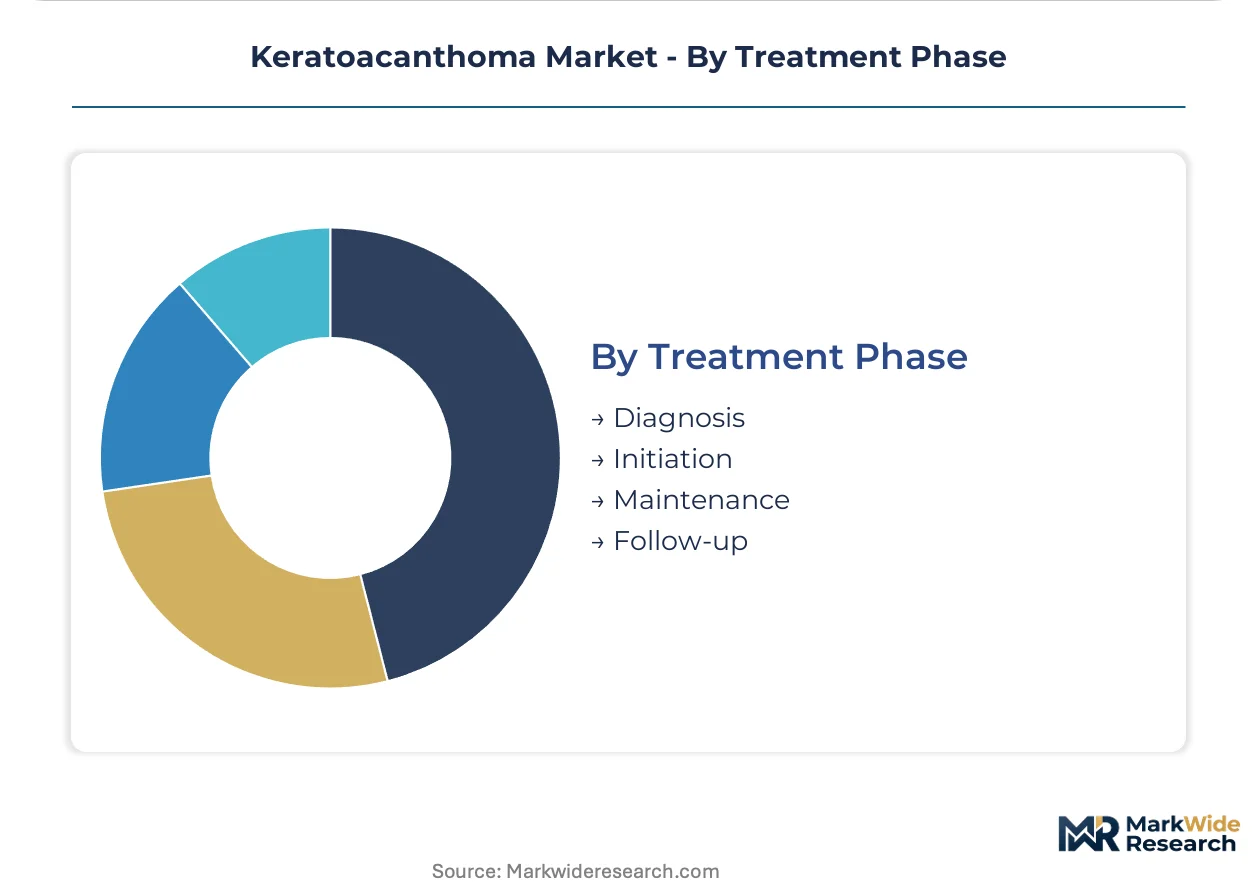
Treatment Phase:
Margin structure differs by phase maturity, with diagnostic and initiation phases commanding technology premiums.
- Diagnosis:Reflectance confocal microscopy and dermoscopic triage platforms require capital investment but reduce unnecessary excisions. United States academic centers are deploying this technology to differentiate keratoacanthoma from squamous cell carcinoma mimics.
- Initiation:First-line treatment selection between surgical, topical, or combination protocols determines total episode cost and cosmetic outcome.
- Maintenance:Topical agent continuation and wound surveillance protocols vary by lesion location and patient risk profile.
- Follow-up:Recurrence monitoring and scar management extend care timelines without proportional reimbursement.
Diagnosis phase leads technology investment; initiation phase is climbing the fastest as combination protocols gain protocol acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains higher procedural volumes per capita than Germany, yet Australian telemedicine networks achieve broader geographic coverage for remote lesion triage. Canada and the United Kingdom concentrate academic research capacity, while Japan maintains conservative surgical protocols that limit topical agent penetration.
United States
Florida and California dermatology clinics drive excision volume growth through dedicated lesion management suites. FDA accelerated approval pathways compress commercialization timelines for novel topical agents. Greater Boston academic medical centers deploy reflectance confocal microscopy to reduce unnecessary wide-local excisions.
Germany
University hospitals in Bavaria and North Rhine-Westphalia standardize combination therapy protocols for extremity lesions. REACH chemical safety assessments extend compliance obligations for topical formulation excipients. Frankfurt and Munich formulators reformulate toward bio-based preservative alternatives with established safety dossiers.
Australia
Rural telemedicine programs prioritize extremity lesion triage for remote and indigenous populations. TGA parallel review pathways with FDA and Health Canada compress device registration timelines. Sydney and Melbourne research institutions anchor Phase II topical agent studies with aligned regulatory frameworks.
Canada
Post-market surveillance obligations under Health Canada extend compliance costs for multinational surgical device manufacturers. Ontario and Quebec academic centers lead diagnostic biomarker development for histopathological classification refinement. Toronto dermatology networks integrate digital pathology platforms across provincial health systems.
United Kingdom
NHS reimbursement coding complexity for keratoacanthoma versus squamous cell carcinoma boundaries delays topical agent formulary inclusion. London and Southeast England concentrate Mohs micrographic surgery capacity for facial lesion reconstruction. MHRA convergence with EMA MDR frameworks streamlines surgical device conformity for British manufacturers.
Keratoacanthoma Market Competitive Landscape
Top-tier vendors anchor oncology-aligned pharmaceutical development, while mid-tier dermatology specialists compete on generic topical cost positions. Siemens and GE HealthCare occupy imaging technology tiers that guide precision excision workflows. Consolidation pressures favor portfolio diversification into sequential topical-surgical combination protocols and telemedicine-integrated diagnostic platforms.
Within the pharmaceutical archetype, Pfizer Inc and Bristol Myers Squibb occupy positions aligned with squamous proliferative disorder pipelines, while Glenmark Pharmaceuticals Ltd exemplifies cost-competitive generic dermatology portfolio strategies. Siemens anchors the imaging systems tier that sustains technology leadership through advanced dermoscopy platforms. These three entities represent distinct competitive vectors: biologic R&D investment, emerging market cost positioning, and capital equipment innovation.
| Leading Market Players |
|---|
| Glenmark Pharmaceuticals Ltd |
| Siemens |
| Cipla |
| Almirall |
| Biofrontera AG |
| GE HealthCare |
| Sun Pharmaceutical Industries Ltd |
| Bristol Myers Squibb |
| Pfizer Inc |
| Others |
Supply & Pricing Matrix
Captive integration into dermoscopy device manufacturing anchors supply positions for United States outpatient dermatology networks while simultaneously preserving premium pricing power for precision-guided excision workflows. This integration choice insulates leading vendors from commodity pressure in generic surgical instruments.
Pricing Analysis
Capacity additions in Germany and Australia are reshaping price floors for topical lesion regression agents as REACH-compliant bio-based preservatives achieve scale. Three-tier pricing structure across premium Mohs micrographic surgery, standard wide-local excision, and economy shave biopsy separates cosmetic outcome guarantees from basic pathological confirmation. Pricing pressure stems from United States commercial payer prior-authorization tier escalation forcing patients toward lower-reimbursement surgical alternatives. Community dermatology clinics exhibit highest price sensitivity; academic medical centers with reconstructive expertise demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Sydney, and Toronto feed hub-and-spoke patterns serving dermatology clinic networks across their respective national health systems. Geographic supply concentrates in Germany for precision excision instruments, India for generic topical formulation APIs, and the United States for reflectance confocal microscopy systems. Raw material dependencies include medical-grade keratin plugs, immune-modulating gel excipients, and dermoscopy optical components. Single-source vulnerability runs through German precision optics suppliers for confocal microscopy devices. Distribution runs through GPO-affiliated procurement channels in the United States and provincial health authority contracts in Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA accelerated dermatologic approval pathways continuously elevate evidentiary thresholds while compressing commercialization timelines for novel lesion management modalities.
For Market Incumbents: Lock in dermoscopy-integrated workflow dominance by acquiring telemedicine triage platforms serving remote Australian and Canadian populations. Prioritize backward integration into bio-based preservative manufacturing to neutralize REACH compliance cost escalation threatening topical agent margins. Defend against emerging generic dermatology specialists by embedding sequential topical-surgical protocols into United States dermatology clinic GPO contracts. For New Entrants and Emerging Players: Telemedicine-integrated dermoscopy platforms offer the most penetrable entry vector for extremity lesion triage in Australian rural markets underserved by board-certified dermatologist concentration. Target combination therapy protocol development partnerships with German university hospitals standardizing sequential topical-surgical regimens. Pursue Health Canada parallel review pathway synchronization to compress time-to-market versus FDA-only submission strategies. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap dermatology clinic networks because specialist workforce concentration in United States urban corridors creates acquisition targets with embedded referral moats. Five-to-ten year viability hinges on positioning for histopathological classification standardization that could reclassify keratoacanthoma management pathways entirely. Watch for TGA-FDA-Health Canada submission pathway convergence signals as inflection indicators for device registration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Integration | Expands extremity lesion triage access for remote Australian indigenous populations. |
| REACH-Compliant Reformulation | Preserves German topical agent market access as ECHA chemical safety assessments tighten. |
| FDA Accelerated Approval Pathway | Compresses novel topical agent commercialization timelines for United States launch. |
| Mohs Micrographic Surgery Capacity Expansion | Captures premium facial lesion reconstruction demand in Florida and California. |
| Health Canada Parallel Review Synchronization | Aligns device registration with FDA and TGA to accelerate North American market entry. |
Research Methodology
Multiple input streams — dermatology clinic procedural volume databases, pharmaceutical regulatory filing repositories, and surgical device customs records — were reconciled through bottom-up and top-down triangulation. Primary interviews with Mohs surgeons, formulary directors at United States commercial payers, and Health Canada regulatory affairs specialists were validated against secondary sources including FDA 510(k) clearance databases, EMA MDR conformity assessment documentation, and Australian TGA registration filings.
Data-stream reconciliation across product type, indication anatomical zone, end-user facility tier, and treatment phase progression generated volume and value outputs throughout the forecast period. CAGRs were derived from segmented growth trajectory modeling incorporating procedural volume expansion rates, reimbursement code valuation shifts, and regulatory pathway timeline assumptions. Industry-specific forecast inputs included dermoscopy device replacement cycles and topical agent protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to histopathological classification standardization debates and FDA dermatologic division leadership transitions. Outputs reflect documented assumptions regarding specialist workforce geographic distribution and payer prior-authorization tier stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Software Market
Dermatology
China Scar Treatment Market
Dermatology
Darier Disease Drugs Market
Dermatology
Folliculitis Market
Dermatology
Immunodermatology Market
Dermatology
Folliculitis Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Dermatology Devices Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Global Radiodermatitis Market
Dermatology
Global Onychomycosis Market
Dermatology
Dermal Facial Fillers Market
Dermatology
UK Scar Treatment Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Seborrheic Keratosis Market