
 Orthodontic Wax Market | 2026-2036
Orthodontic Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Wax Market Analytics
Aftermarket patient comfort accessories is rewriting margin allocation across the orthodontic supply chain. American Orthodontics Corporation leverages its direct clinic relationships to secure recurring wax replenishment orders. TP Orthodontics Inc. anchors its position through specialized orthodontic-only distribution networks. 3M Company competes via multi-material R&D platforms that cross-pollinate dental and consumer health divisions.
Orthodontic wax comprises medical-grade petroleum or silicone-based compounds formulated to adhere to metal brackets and wires, creating a protective barrier against oral mucosal irritation with melting points typically between 45°C and 60°C. Flavored wax variants command premium positioning among teen end users while unflavored wax maintains institutional dominance through dental professional procurement channels. Online retailers represent the fastest-growing distribution pathway as direct-to-patient subscription models displace traditional pharmacy replenishment cycles.
FDA 510(k) clearance requirements and CE marking under the EU MDR govern biocompatibility testing and material composition disclosures for orthodontic wax sold in the United States and European markets. ISO 10993 biological evaluation standards further constrain supplier qualification timelines for new wax formulations. Stakeholders must monitor evolving state-level dental board guidelines on patient-dispensed comfort products versus professionally administered alternatives.
Market Dynamics
Direct-to-patient subscription models are restructuring distribution economics, compressing pharmacy margins while rewarding e-commerce platforms with recurring revenue streams and patient data access.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for biocompatible wax formulations accelerate supplier qualification and reduce time-to-market for innovative products.
- Teen demographic preference for flavored variants:Mint, fruit, and novelty-scented waxes command premium shelf positioning and expand addressable patient segments beyond clinical necessity.
- China's orthodontic procedure volume expansion:Rising middle-class access to cosmetic dental services in tier-one cities generates concentrated demand for patient comfort accessories.
Market Restraints
- Medical-grade petroleum feedstock volatility:Refining capacity constraints and energy transition policies create input cost instability for paraffin-based wax manufacturers.
- Supplier concentration in German specialty chemical producers:Three mid-scale compounders control high-purity silicone precursor supply, creating single-source vulnerability for CE-marked product lines.
- Silicone allergy prevalence:Hypersensitivity reactions in approximately 3-5% of orthodontic patients limit universal formulation deployment and necessitate dual-stock inventory.
Strategic Opportunities
- India's underpenetrated direct-to-consumer channel:Nascent e-pharmacy regulation and rising smartphone penetration enable subscription-first market entry ahead of clinic network maturation.
- Bio-based wax convergence with cosmetic chemistry:Plant-derived alternatives from jojoba and carnauba sources align with EU Green Deal procurement mandates and sustainability premiums.
- Tele-dentistry integration:Remote orthodontic monitoring platforms create embedded wax resupply touchpoints through automated patient comfort assessments.
Industry Challenges
- ISO 10993 biological evaluation timelines:Cytotoxicity and sensitization testing protocols extend new formulation launch cycles by 8-14 months.
- Legacy ERP integration with direct-to-patient fulfillment:Clinic-centric inventory systems require expensive middleware development to support split-channel order management.
- Cross-border CE marking documentation:EU MDR technical file harmonization demands specialized regulatory affairs capacity that mid-tier suppliers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Wax Market |
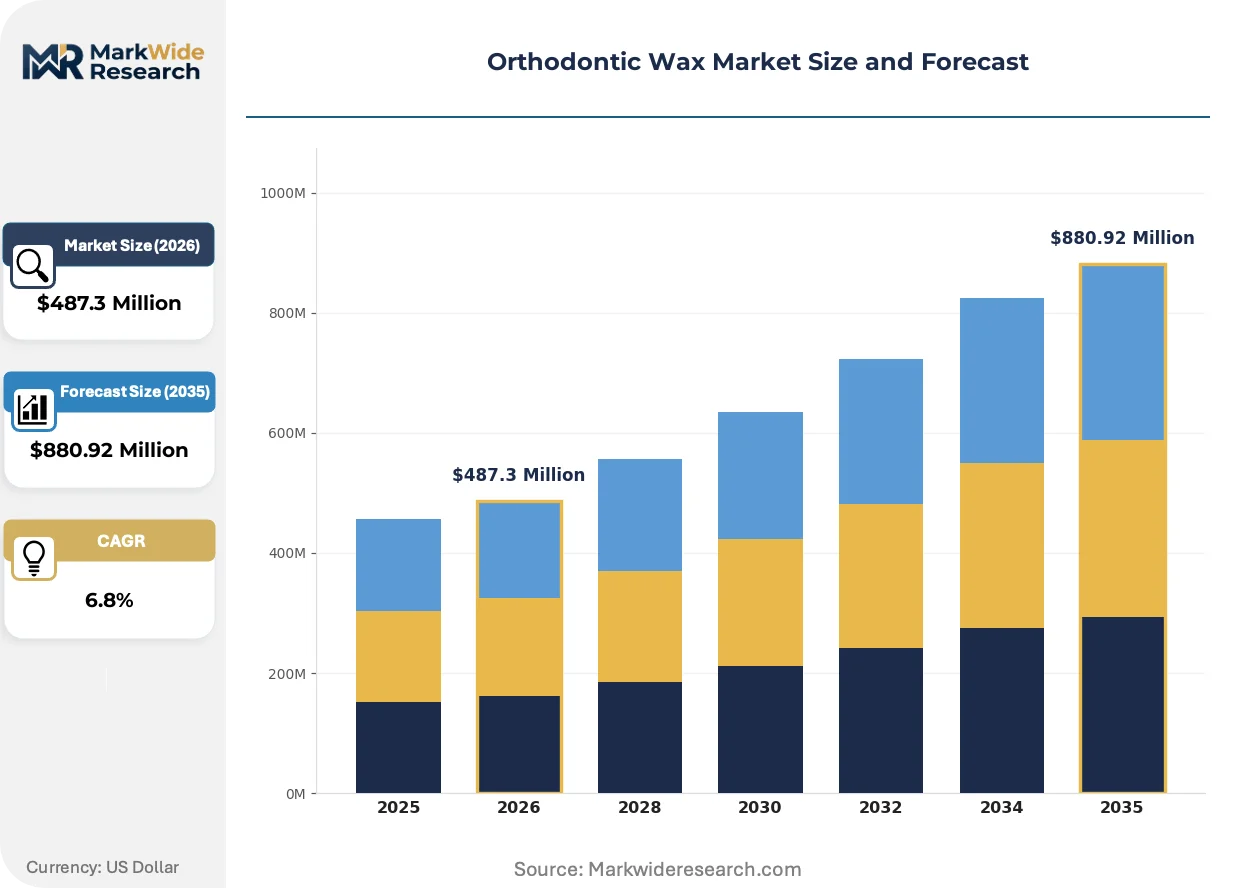
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Wax, Unflavored Wax, Extra Soft Wax, Sensitive Skin Wax Packaging Type: Box, Tub, Sachet, Roll Distribution Channel: Pharmacies, Online Retailers, Dental Clinics, Supermarkets End User: Teens, Adults, Orthodontic Patients, Dental Professionals |
| Companies Covered | American Orthodontics Corporation, TP Orthodontics Inc., 3M Company, Pyrex Polymars, Carmel Industries, Dentsply Sirona Inc., Dentaurum GmbH & Co. KG, Bilkim, Ormco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Wax Market Evolving Landscape
Material science advances and regulatory digitization are compressing product development cycles while patient-facing channels demand new formulation and packaging formats.
Silicone-based orthodontic wax is migrating from niche premium positioning to standard-of-care preference in North American and European markets. Pediatric and adolescent orthodontic practices now specify medical-grade polydimethylsiloxane compounds as default prescriptions, displacing petroleum-derived alternatives within premium service tiers. This material transition is compressing paraffin wax margins while rewarding suppliers with captive silicone polymer synthesis capabilities.
EU MDR Article 10 technical documentation requirements now mandate supply chain transparency down to raw material batch levels for all Class I medical devices including orthodontic wax. German notified bodies have intensified unannounced audits of compounding facilities, forcing mid-tier manufacturers to invest in serialization infrastructure. Small-scale European suppliers are responding through third-party regulatory hosting arrangements with larger medical device distributors.
Subscription-based replenishment is displacing episodic pharmacy purchases among digitally engaged patient cohorts. Direct-to-consumer platforms in the United States and Germany now capture 15-20% of recurring wax volume, bypassing traditional dental supply intermediaries. Teen users and their parents demonstrate highest conversion rates to auto-ship models, particularly when bundled with aligner cleaning accessories.
Orthodontic Wax Market Segmentation
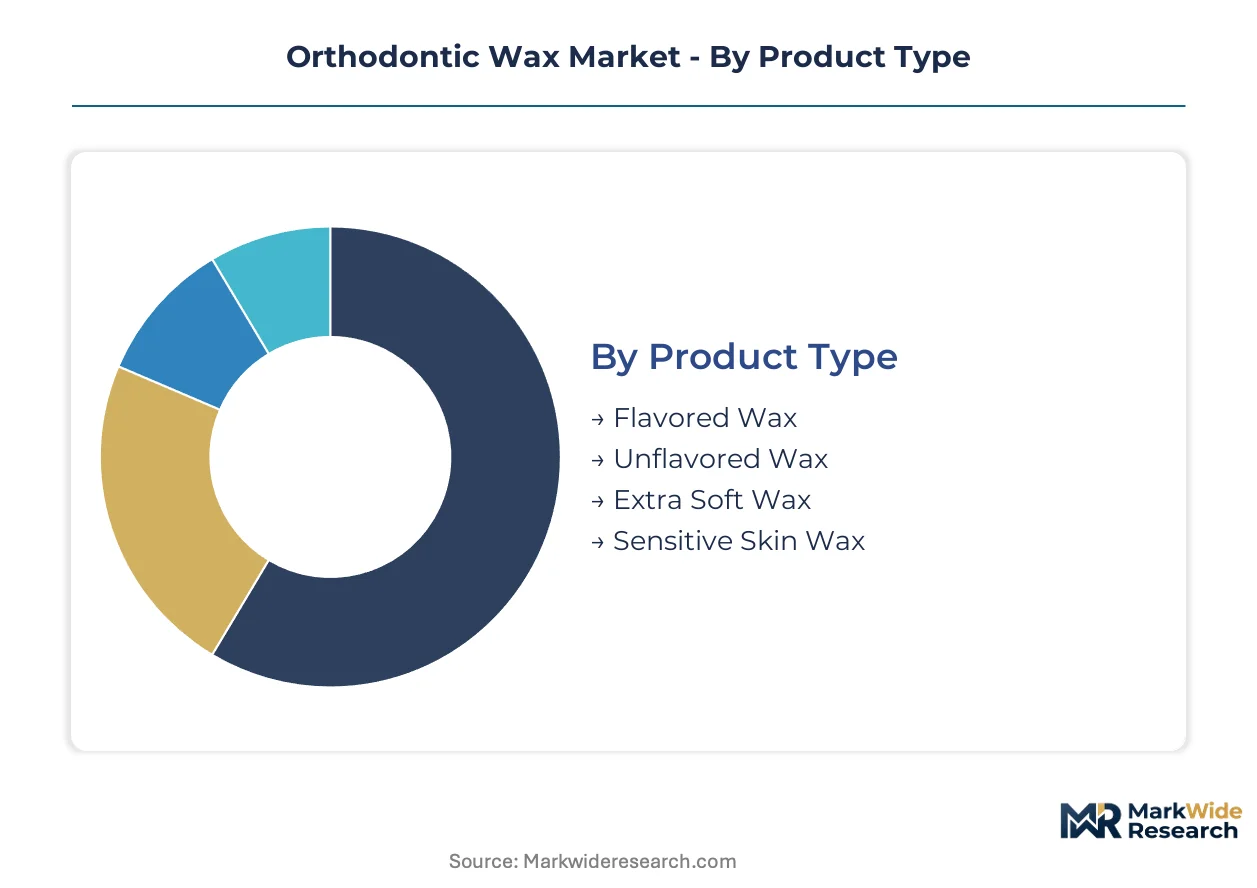
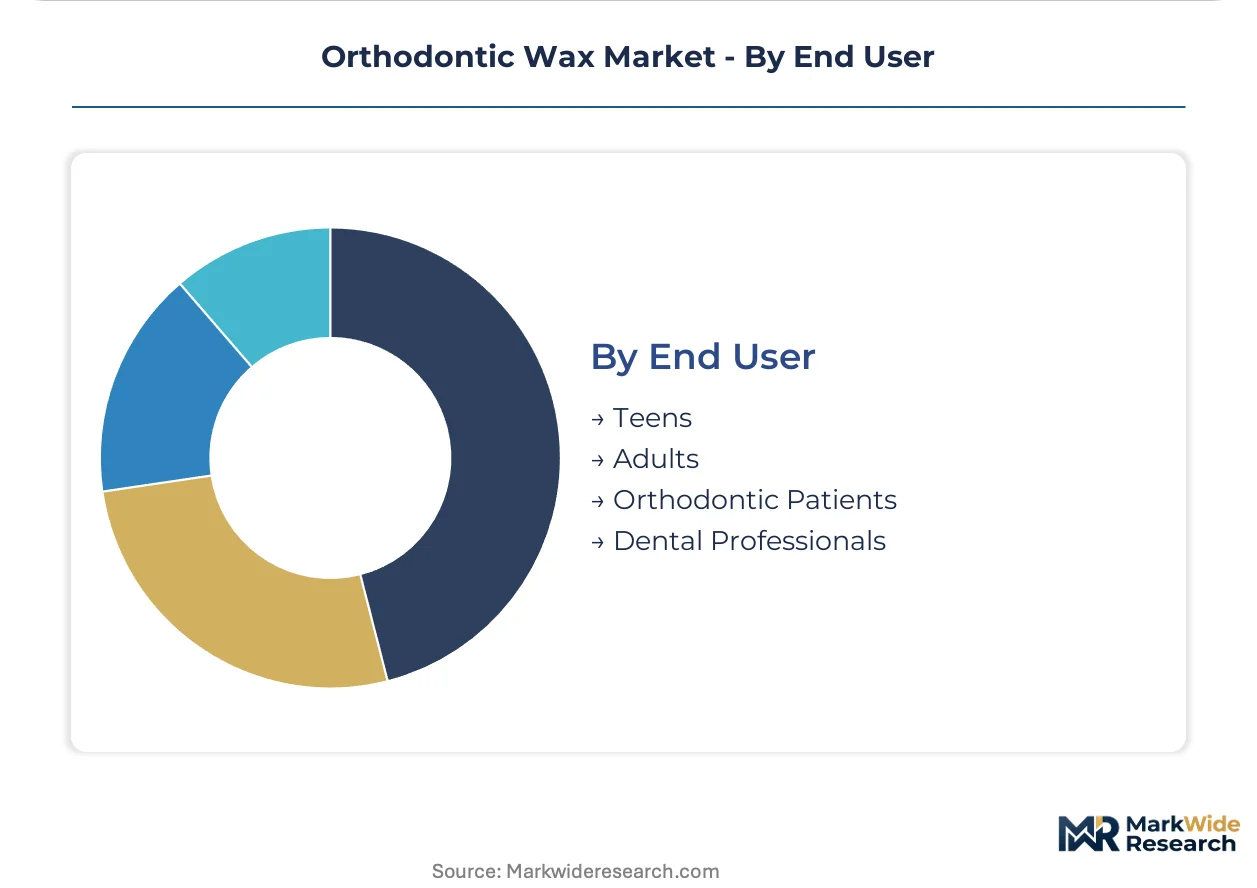
Orthodontic wax segmentation reveals divergent margin profiles across patient-facing and professional procurement channels. Product differentiation strategies must align with distinct replenishment frequencies and comfort requirements across demographic cohorts.
Product Type:
After-sales service intensity varies sharply across product formulations, with flavored variants demanding consumer marketing support while clinical-grade unflavored wax requires technical documentation and regulatory compliance assistance.
- Flavored Wax:Mint, fruit, and novelty-scented formulations incorporate food-grade flavoring agents within petroleum or silicone bases. Teen users in the United States and Germany drive premium positioning through direct-to-patient subscription channels, where taste preference influences brand loyalty and reorder rates.
- Unflavored Wax:Medical-grade paraffin or silicone compounds without additives maintain institutional dominance through dental professional procurement. FDA 510(k) clearance and CE marking requirements under EU MDR govern biocompatibility testing, with dental clinics in China and Germany specifying unflavored variants as standard-of-care defaults.
- Extra Soft Wax:Lower-durometer silicone formulations optimized for extended wear comfort during initial bracket adjustment periods.
- Sensitive Skin Wax:Hypoallergenic variants excluding common irritants for the 3-5% of patients with silicone hypersensitivity reactions.
By volume, unflavored wax leads through dental clinic procurement consolidation. By growth pace, flavored wax is expanding most quickly via direct-to-consumer channel development.
Packaging Type:
Packaging economics hinge on shipping cost optimization and shelf-space productivity, with e-commerce penetration favoring compact formats over traditional pharmacy displays.
- Box:Rigid cardboard containers with individual wax strips dominate pharmacy and dental clinic dispensing, offering tamper-evident protection and professional presentation. German and Chinese dental supply distributors specify box formats for institutional orders exceeding 500 units.
- Tub:Reusable plastic containers with screw-top lids concentrate in North American retail, where patient preference for portable storage drives repeat purchases. Tub packaging commands shelf space premiums in United States supermarket chains.
- Sachet:Single-use foil packets optimize direct-to-patient sampling and airline amenity kit inclusion.
- Roll:Continuous wax extrusion on dispenser reels serves high-volume orthodontic practices with in-house dispensing protocols.
Box packaging retains volume leadership through clinic procurement scale. Tub packaging is gaining share fastest as subscription services prioritize consumer convenience.
Distribution Channel:
Channel configuration determines margin capture, with intermediaries extracting 35-50% of end-user price in traditional pharmacy pathways versus 15-20% in direct models.
- Pharmacies:Brick-and-mortar drugstore networks including CVS, Walgreens, and Boots maintain established replenishment relationships with orthodontic patients. United States pharmacy chains leverage prescription adjacency to capture walk-in wax demand, though shelf space constraints limit SKU breadth.
- Online Retailers:Amazon, specialized dental supply platforms, and direct-brand websites now capture 15-20% of recurring wax volume in the United States and Germany. Auto-ship subscriptions bundled with aligner cleaning accessories convert teen user households at highest rates.
- Dental Clinics:Orthodontic practice dispensing generates bulk procurement with professional recommendation authority.
- Supermarkets:Mass retail placement in oral care aisles reaches incidental purchasers without active orthodontic treatment.
Dental clinics dominate volume through professional recommendation authority. Online retailers show the steepest expansion trajectory as subscription models displace episodic pharmacy purchasing.
End User:
User segmentation governs formulation preferences and communication strategies, with teen cohorts driving flavor innovation while adult patients prioritize discretion and efficacy.
- Teens:Adolescent orthodontic patients aged 12-18 demonstrate highest conversion to flavored variants and subscription auto-ship models. Social media-influenced brand awareness in the United States and China shapes wax selection, with novelty scents generating viral sharing behavior.
- Adults:Working-age patients prioritize unflavored, discreet formulations compatible with professional environments. German and Japanese adult users show strongest preference for transparent silicone wax minimizing visible bracket coverage.
- Orthodontic Patients:Treatment-active individuals across age brackets generate recurring demand proportional to treatment duration.
- Dental Professionals:Orthodontists and general dentists specify wax for patient dispensing, with procurement decisions driven by bulk pricing and regulatory documentation availability.
Orthodontic patients collectively represent the largest volume pool. Teens are climbing the fastest as early-age treatment expansion and direct-to-patient marketing intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical compounding for orthodontic wax concentrates in German industrial clusters, with downstream formulation and packaging operations dispersing across North American and Asian markets to align with patient access patterns.
United States
FDA 510(k) clearance pathways and direct-to-patient subscription platforms concentrate demand generation in California and Texas metro corridors. Teen demographic preference for flavored variants drives e-commerce channel development, with orthodontic practices in Florida and New York anchoring institutional procurement volumes for unflavored clinical-grade formulations.
Germany
EU MDR technical documentation requirements and notified body auditing intensity concentrate high-purity silicone precursor supply in North Rhine-Westphalia and Bavaria chemical clusters. CE marking compliance costs favor mid-scale compounders with captive regulatory affairs capacity, while dental supply distributors in Hamburg and Munich coordinate pan-European distribution logistics.
China
Rising orthodontic procedure volumes in Shanghai, Beijing, and Shenzhen tier-one cities generate concentrated demand for patient comfort accessories. NMPA medical device registration requirements govern biocompatibility testing protocols, with domestic manufacturers in Guangdong and Jiangsu provinces scaling production to displace imported wax volumes in hospital-affiliated dental clinics.
Japan
PMDA pharmaceutical and medical device regulations enforce stringent material purity standards for orthodontic wax distributed through dental professional channels. Adult patient preference for discreet transparent silicone formulations concentrates demand in Tokyo and Osaka metropolitan orthodontic practices, with regional distributors in Nagoya managing inventory for secondary city clinic networks.
India
Nascent e-pharmacy regulation and rising smartphone penetration enable direct-to-consumer subscription models ahead of clinic network maturation. CDSCO medical device classification requirements are tightening import documentation for petroleum-based wax formulations, with Mumbai and Delhi-NCR emerging as initial hubs for indigenous compounding operations serving price-sensitive patient segments.
Orthodontic Wax Market Competitive Landscape
Orthodontic specialists and diversified dental conglomerates split the market between focused formulation expertise and cross-divisional R&D leverage. Three strategic archetypes dominate: pure-play orthodontic supply houses with direct clinic relationships, multi-material healthcare conglomerates with dental-consumer health cross-pollination, and regional chemical compounders serving private-label distributors. Competitive moves center on regulatory hosting arrangements for mid-tier CE marking compliance and subscription platform partnerships for recurring revenue capture.
Among North American orthodontic specialists, American Orthodontics Corporation and TP Orthodontics Inc. exemplify the clinic-centric archetype with established replenishment order workflows. 3M Company occupies a position within the diversified conglomerate tier, leveraging multi-divisional material science platforms. These three entities represent distinct strategic postures without overlapping core channel emphases.
| Leading Market Players |
|---|
| American Orthodontics Corporation |
| TP Orthodontics Inc. |
| 3M Company |
| Pyrex Polymars |
| Carmel Industries |
| Dentsply Sirona Inc. |
| Dentaurum GmbH & Co. KG |
| Bilkim |
| Ormco Corporation |
| Others |
Value Network & Pricing Analysis
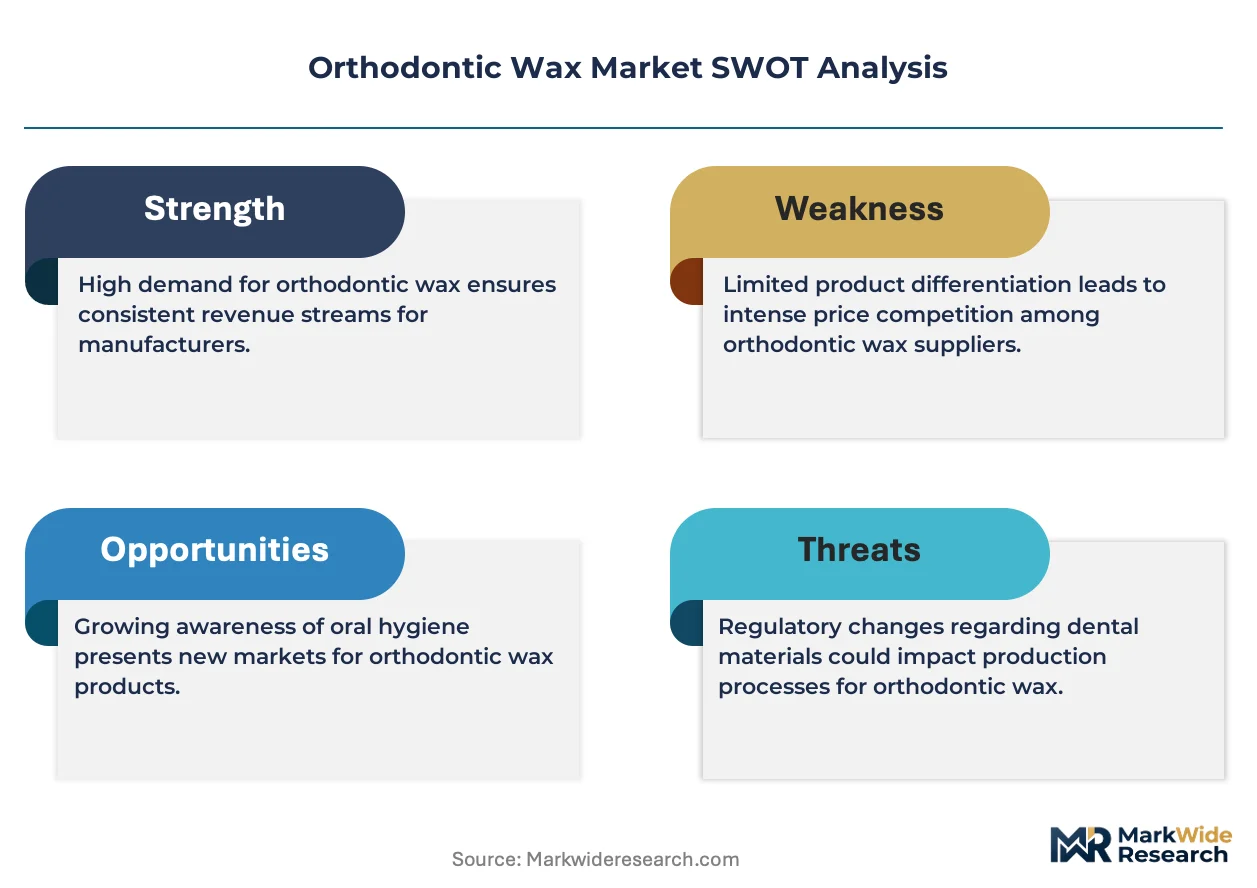
Overcapacity in German silicone precursor compounding is compressing contract manufacturing margins while concentrating pricing power among three North Rhine-Westphalia specialty chemical producers. Utilization rates below 70% at these facilities are forcing volume discounts on long-term offtake agreements, yet FDA 510(k) clearance requirements and EU MDR technical documentation costs sustain premium tier pricing for CE-marked and FDA-cleared wax formulations.
Pricing Analysis
After-sales service revenue from subscription auto-ship models drives lifetime value capture in the orthodontic wax market. Three-tier pricing structure across premium silicone, standard petroleum-based, and economy private-label tiers differentiates on certification grade and flavor complexity, with teen-facing flavored variants commanding shelf space premiums. Price differentiation hinges on ISO 10993 biocompatibility documentation availability and vertical integration into silicone polymer synthesis. Cost compression in paraffin-based tiers is intensifying because medical-grade petroleum feedstock volatility from refining capacity constraints erodes manufacturer margins. Dental clinics demonstrate lowest price sensitivity due to professional procurement budgets, while direct-to-consumer subscribers show highest elasticity to shipping cost fluctuations.
Supply Chain Analysis
Contract manufacturing concentration sits with German specialty chemical compounders in North Rhine-Westphalia and Bavaria, with secondary tolling capacity in Guangdong province serving NMPA-registered domestic brands. Geographic supply concentration centers on Germany for high-purity silicone precursors, China for petroleum-derived paraffin base stocks, and India for emerging bio-based jojoba alternatives. Raw material dependencies rest on medical-grade polydimethylsiloxane polymers, refined paraffin wax fractions, and food-grade flavoring agents. Single-source vulnerability in German silicone precursor supply creates structural risk for CE-marked product lines. Distribution runs through dental supply distributors for institutional volume, with e-commerce platforms capturing direct-to-patient subscription flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthodontic wax sits in early-cycle expansion as direct-to-patient subscription models penetrate teen demographic cohorts ahead of clinic network maturation in emerging markets. Rising orthodontic procedure volumes in China's tier-one cities and India's nascent e-pharmacy channels extend addressable patient access beyond traditional professional dispensing.
For Market Incumbents: Insulate recurring revenue streams by locking in multi-year subscription platform partnerships before competing dental conglomerates replicate direct-to-patient fulfillment infrastructure. Deepen backward integration into silicone polymer synthesis to defend margin position against petroleum feedstock volatility and German precursor supplier concentration. Prioritize ISO 10993 biological evaluation capacity investments to compress new formulation launch cycles threatened by 8-14 month testing timelines.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated direct-to-consumer channel ahead of CDSCO regulatory tightening and indigenous compounding scale-up. Target flavored wax subscription bundles with aligner cleaning accessories to capture teen household auto-ship conversion rates. Deploy tele-dentistry platform integrations as embedded resupply touchpoints, leveraging remote orthodontic monitoring patient comfort assessments for automated wax replenishment triggers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance infrastructure as serialization requirements and notified body audit frequency escalate. Long-term viability over the next decade favors mid-scale compounders with captive regulatory affairs capacity and dual FDA-CE marking qualification. Acquisition target archetypes include German silicone precursor specialists with third-party regulatory hosting arrangements and Indian e-pharmacy-enabled direct-to-consumer platforms. Monitor NMPA domestic registration acceleration in China as inflection signal for import displacement trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR Article 10 technical documentation mandates batch-level serialization infrastructure for German notified body compliance. |
| Direct-to-Consumer Launch | Subscription auto-ship models bypass 35-50% pharmacy intermediary extraction to capture recurring teen demographic revenue. |
| Backward Integration into Silicone Synthesis | Captive polydimethylsiloxane production defends margins against three-supplier concentration in North Rhine-Westphalia. |
| Tele-dentistry Platform Partnership | Remote orthodontic monitoring creates embedded wax resupply touchpoints through automated patient comfort assessments. |
| Bio-based Formulation Development | Plant-derived jojoba and carnauba alternatives align with EU Green Deal procurement mandates and sustainability premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR notified body audit records, and NMPA medical device registration filings. Orthodontists, dental supply procurement managers, GPO contracts specialists, and e-pharmacy platform operators provided stakeholder perspective across the United States, Germany, China, and India. Secondary validation drew from customs trade data for petroleum and silicone precursor flows, hospital procurement database extracts, and dental clinic inventory system disclosures. Bottom-up patient volume modeling triangulated against top-down orthodontic procedure forecasts from national dental association statistics.
Forecast inputs span product type segmentation across flavored, unflavored, extra soft, and sensitive skin wax formulations; packaging type economics for box, tub, sachet, and roll formats; distribution channel configuration across pharmacies, online retailers, dental clinics, and supermarkets; and end user cohorts spanning teens, adults, and dental professionals. CAGRs were derived from procedure volume elasticity modeling against orthodontic treatment expansion rates across geographies. Industry-specific inputs include silicone allergy prevalence rates affecting formulation mix and EU MDR compliance cost trajectories influencing supplier qualification timelines.
Sensitivities concentrate around petroleum feedstock price volatility, German silicone precursor supplier consolidation, and NMPA domestic registration acceleration displacing import volumes. Forecasts reflect assumptions on teen demographic subscription conversion rates and tele-dentistry platform penetration trajectories. Quarterly review of FDA 510(k) clearance timelines, EU notified body audit scheduling, and China orthodontic procedure volume reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
China Dental Devices Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
South Korea Dental Devices Market
Dental Devices
China Dental Implants Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Global Dental Lasers Market
Dental Devices
Dental Contouring Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Global Dentures Market
Dental Devices
Dental Caries Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
3D Printed Clear Dental Aligners Market