
 Warranty Management Software Market | 2026-2036
Warranty Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Warranty Management Software Market Outlook
Modular subscription bundling is pivoting how enterprises procure warranty platforms, unbundling core claims processing from predictive analytics add-ons. Oracle Corporation leverages its enterprise database footprint to anchor multi-industry deployments. SAP SE competes through deep ERP integration that sustains renewal rates among large manufacturers. Syncron specializes in aftermarket service networks, dominating automotive and heavy equipment verticals where parts availability ties directly to warranty performance.
Warranty management software orchestrates the full lifecycle of product guarantees, from registration and claims adjudication to supplier recovery and reserve forecasting, typically deployed through multi-tenant cloud architectures with API connectivity to ERP and CRM systems. Cloud-based deployment leads absolute spending as enterprises retire legacy on-premise installations, while hybrid configurations capture growing interest from regulated industries requiring data sovereignty controls. The automotive vertical generates the deepest functionality requirements, with electronics retail trailing but expanding fastest as consumer device protection plans proliferate.
FDA medical device tracking requirements, EU consumer protection directives enforced by national regulators, and China's SAMR product liability standards each elevate traceability mandates that software platforms must address. GDPR and emerging state-level privacy laws in the United States constrain cross-border claims data flows, forcing vendors to architect region-specific tenant isolation. Stakeholders must evaluate whether their platform roadmap prioritizes vertical depth in automotive or horizontal expansion across consumer electronics and industrial equipment.
Market Dynamics
Cloud migration is compressing deployment timelines while AI-driven predictive analytics restructures how automotive OEMs and industrial manufacturers reserve capital against future claims exposure.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers must maintain digital records of every component through warranty periods, forcing platform upgrades across European supply chains.
- Automotive extended coverage programs:OEMs now offer 10-year powertrain warranties, requiring sophisticated supplier recovery systems to manage cost allocation across tiered networks.
- China SAMR enforcement:Stricter product liability standards in consumer electronics are driving domestic manufacturers toward automated claims adjudication to reduce settlement exposure.
Market Restraints
- Data sovereignty compliance costs:GDPR and emerging US state privacy laws force vendors to maintain region-isolated tenant architectures, inflating infrastructure expenditure.
- Legacy ERP integration complexity:Decades-old manufacturing execution systems in heavy equipment sectors resist API connectivity, delaying cloud migration timelines.
- Specialized talent scarcity:Warranty data science roles require hybrid expertise in actuarial forecasting and IoT sensor analytics, with limited training pipelines available.
Strategic Opportunities
- India BIS certification expansion:Mandatory quality tracking for electronics imports creates demand for warranty registration platforms among domestic distributors.
- Embedded insurance convergence:Point-of-sale device protection plans are merging with warranty management systems, opening retail banking channels for platform vendors.
- Japan METI carbon accounting:Warranty reserve forecasting now incorporates lifecycle emissions data, creating premium functionality tiers for sustainability reporting.
Industry Challenges
- Multi-tenant security architecture:Segregating competitor data within shared cloud instances demands continuous penetration testing and compliance auditing.
- Supplier network onboarding:Tier-3 and tier-4 automotive component makers lack digital maturity, creating data quality gaps in root-cause analysis workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warranty Management Software Market |
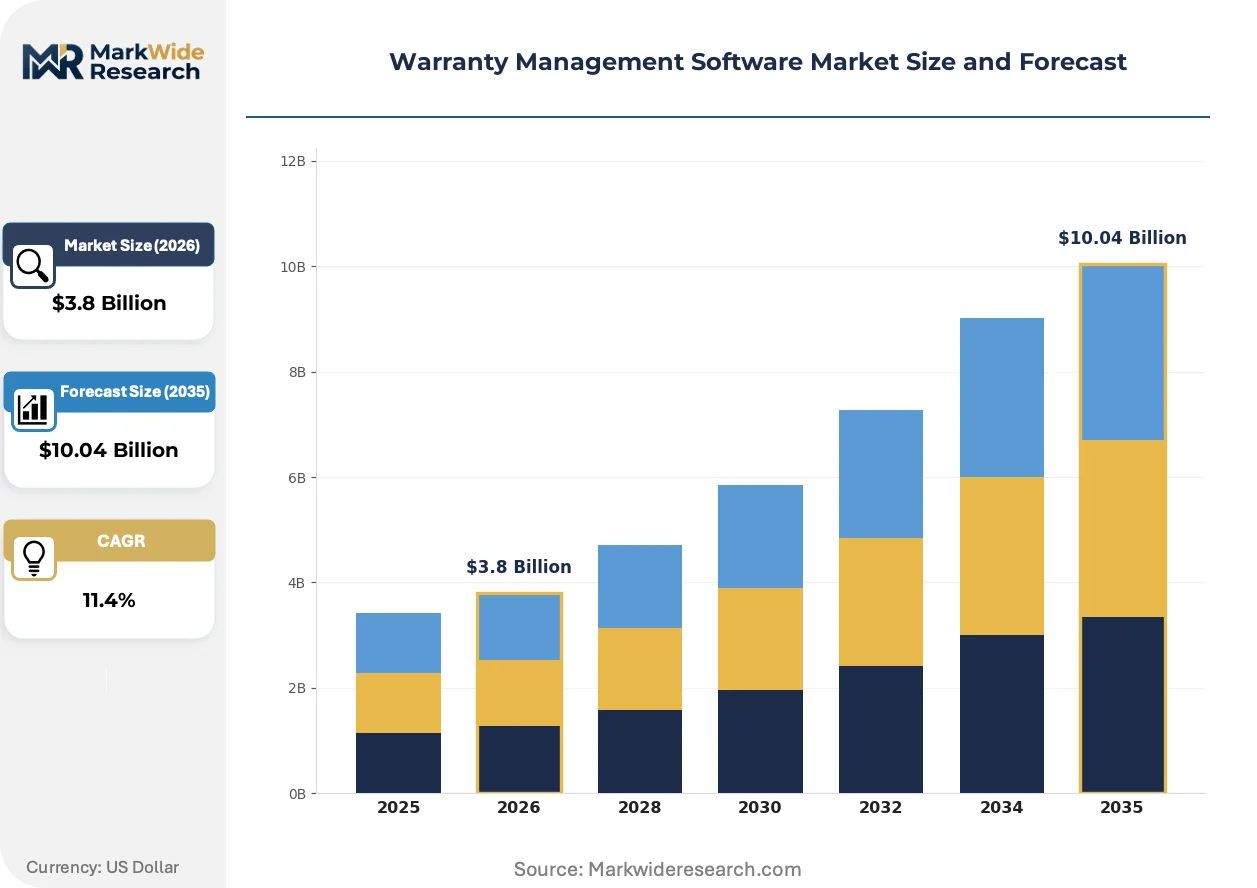
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Custom Solutions Industry Vertical: Automotive, Electronics, Manufacturing, Retail Deployment: Private Cloud, Public Cloud, SaaS, On-Premises Customer Type: SMEs, Large Enterprises, Service Providers, Distributors |
| Companies Covered | Simply Warranty, Snap-On Business Solutions, Oracle Corporation, SAP SE, Pegasystems, PTC, Zafire Ltd, WarrantyHub, Syncron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warranty Management Software Market Strategic Shifts
Artificial intelligence and API-first architectures are dissolving the boundary between warranty administration and broader aftermarket service ecosystems, compressing vendor consolidation timelines.
Machine learning models trained on historical failure patterns are consolidating predictive reserve forecasting into unified platforms. Automotive OEMs in Germany and the United States are deploying these systems across multi-brand portfolios. This capability compression is eliminating standalone actuarial software vendors from procurement shortlists.
EU CSRD sustainability disclosure rules now require warranty claim rates as material ESG metrics. Industrial equipment manufacturers must report failure frequencies by product line and geography. European machinery exporters are retrofitting warranty databases with carbon footprint attribution to satisfy auditor verification requirements.
Subscription bundling of core claims processing with predictive analytics add-ons is restructuring enterprise procurement patterns. Large manufacturers now negotiate modular contracts rather than monolithic platform licenses. This unbundling is most pronounced in United States electronics retail, where seasonal volume spikes favor usage-based pricing models over fixed annual fees.
Warranty Management Software Market Segmentation
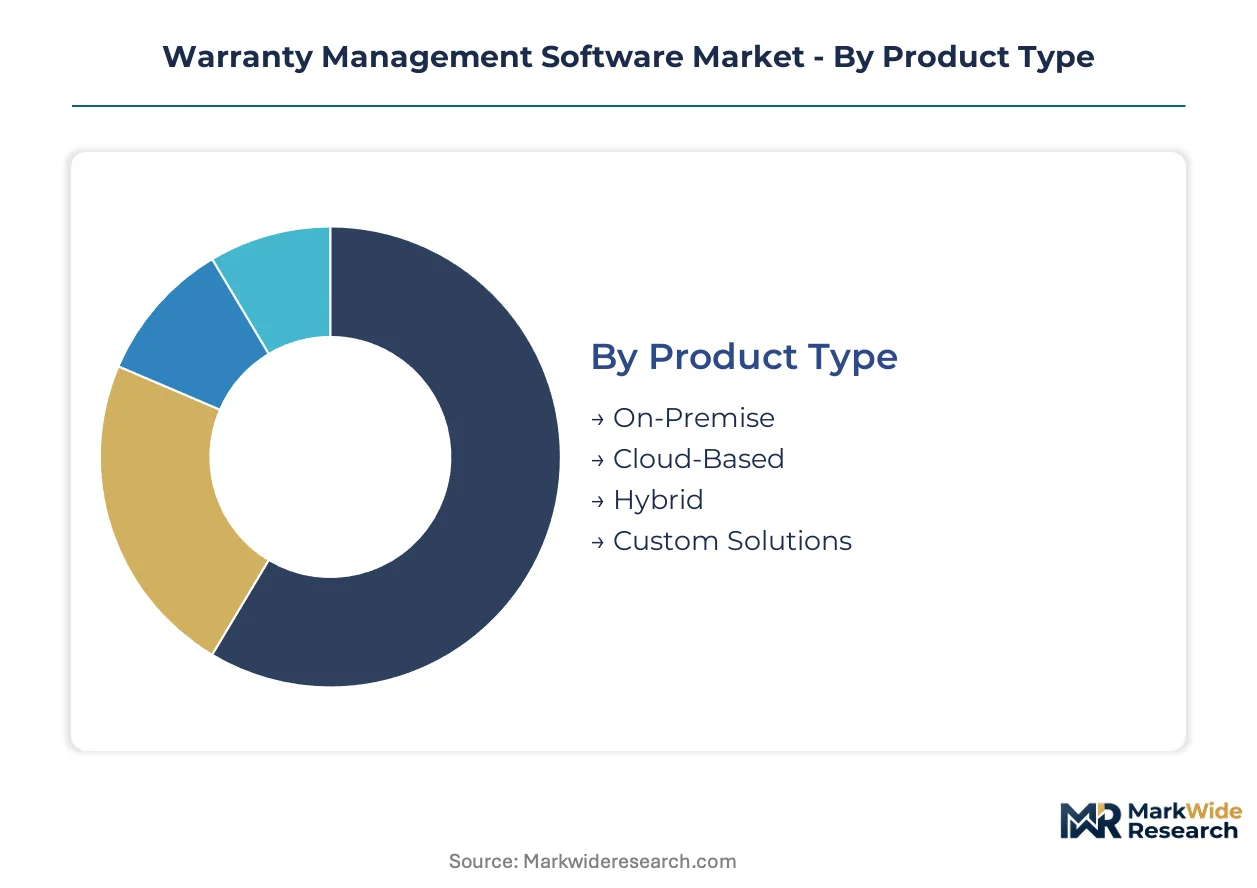
Warranty management software architectures diverge sharply across deployment modes and customer scale, with cloud migration compressing legacy upgrade cycles while specialized vertical requirements fragment platform standardization. Understanding these segment boundaries clarifies where vendor consolidation will accelerate versus where niche specialization sustains pricing power.
Product Type:
Deployment architecture determines integration complexity, data sovereignty compliance burden, and total cost of ownership across enterprise procurement cycles.
- Cloud-Based:Multi-tenant SaaS architectures with API connectivity to ERP and CRM systems dominate new procurement. Automotive OEMs in Germany and the United States favor these platforms for supplier network scalability, though GDPR and emerging US state privacy laws force region-isolated tenant configurations.
- On-Premise:Legacy installations persist in heavy equipment sectors where decades-old manufacturing execution systems resist API connectivity. These deployments maintain relevance where data sovereignty mandates or air-gapped security requirements override cloud economics.
- Hybrid:Configurations split sensitive claims data on-premise while routing analytics workloads to cloud infrastructure. Regulated industries requiring data sovereignty controls drive adoption here.
- Custom Solutions:Bespoke builds serve automotive OEMs with complex tiered supplier recovery systems or medical device manufacturers tracking EU MDR traceability mandates.
Cloud-Based leads on scale; Hybrid leads on momentum as regulated manufacturers seek middle-ground architectures.
Industry Vertical:
Functional requirements intensify with product complexity, warranty duration, and supplier network depth, creating divergent platform specification profiles.
- Automotive:Extended coverage programs now reach 10-year powertrain terms, demanding sophisticated supplier recovery systems for cost allocation across tiered networks. OEMs deploy predictive analytics for reserve forecasting against multi-brand portfolios.
- Electronics:Point-of-sale device protection plans proliferate in United States retail, merging warranty administration with embedded insurance. Seasonal volume spikes favor usage-based pricing models over fixed annual fees.
- Manufacturing:Industrial equipment producers retrofit databases with carbon footprint attribution to satisfy EU CSRD auditor verification requirements. Warranty claim rates now materialize as ESG disclosure metrics.
- Retail:Consumer device protection distribution concentrates through retail banking channels, with modular subscription bundling restructuring procurement patterns toward analytics add-ons.
Automotive leads on scale; Electronics leads on momentum as protection plan convergence accelerates.
Deployment:
Infrastructure control preferences segment along regulatory exposure, IT modernization pace, and cross-border data flow constraints.
- SaaS:Subscription delivery compresses deployment timelines and shifts capital expenditure to operational budgets. This model captures growing interest from mid-market manufacturers retiring legacy installations.
- Private Cloud:Single-tenant dedicated environments satisfy data residency requirements in China under SAMR enforcement and across European jurisdictions under GDPR. Medical device manufacturers leverage these for FDA and EU MDR audit trails.
- Public Cloud:Shared infrastructure delivers cost efficiency for seasonal claims volume variability, particularly in United States electronics retail with promotional cycle spikes.
- On-Premises:Air-gapped installations persist where national security classifications or critical infrastructure designations prohibit external connectivity.
SaaS leads on scale; Private Cloud leads on momentum as data sovereignty compliance costs escalate.
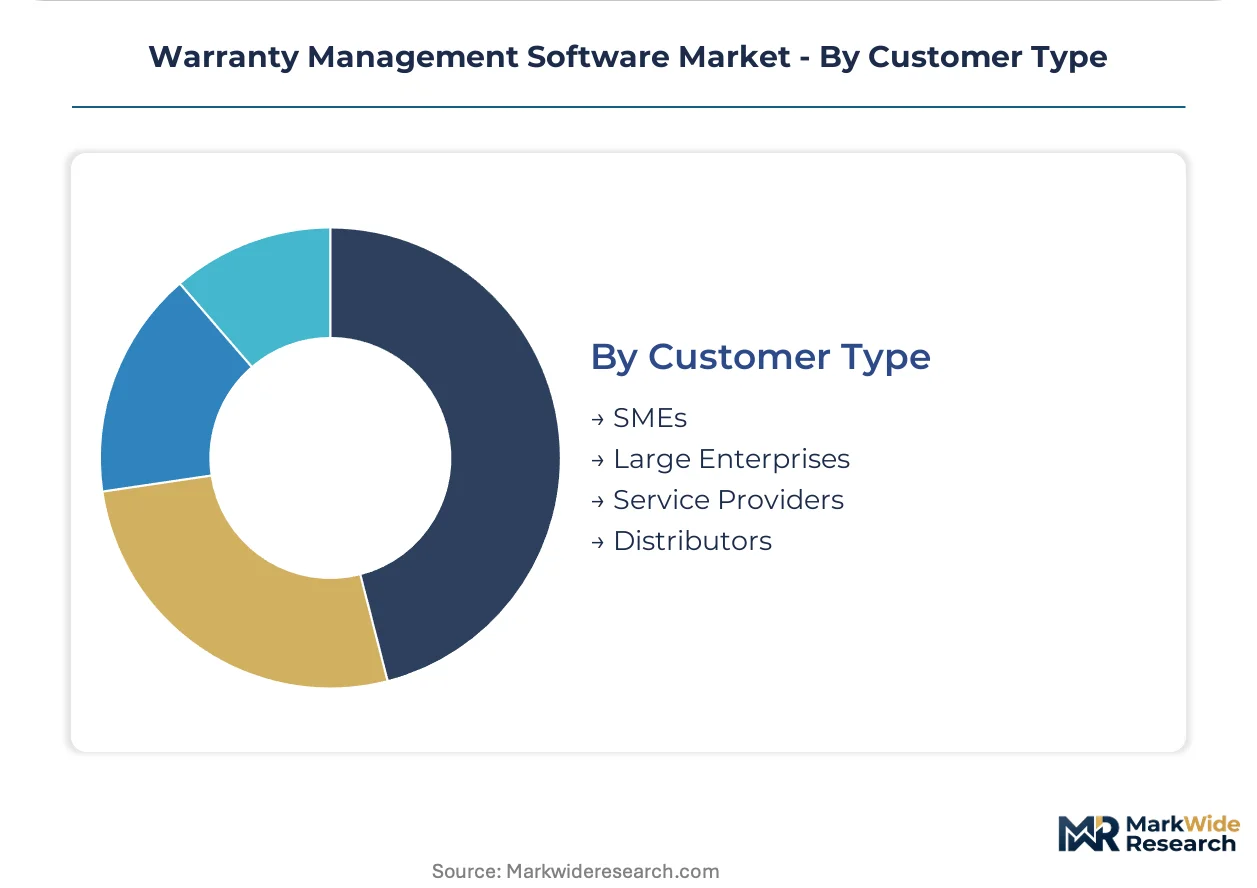
Customer Type:
Organizational scale dictates platform sophistication, integration depth, and pricing model elasticity across procurement negotiations.
- Large Enterprises:Multi-division manufacturers negotiate modular contracts unbundling core claims processing from predictive analytics add-ons. These buyers sustain renewal rates through deep ERP integration requirements.
- SMEs:Mid-market manufacturers prioritize rapid deployment and standardized workflows over customization. Cloud migration compresses their upgrade timelines as legacy maintenance costs escalate.
- Service Providers:Third-party administrators managing warranty programs for multiple OEMs demand multi-tenant security architectures with continuous penetration testing and compliance auditing.
- Distributors:Domestic distributors in India face mandatory BIS certification quality tracking for electronics imports, creating demand for warranty registration platforms with import compliance modules.
Large Enterprises lead on scale; SMEs lead on momentum as cloud economics democratize platform access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warranty management software originated in United States automotive manufacturing during the 1980s, when Detroit-based OEMs first computerized claims processing for supplier recovery. German industrial machinery exporters subsequently developed traceability systems to satisfy emerging EU product liability frameworks. These two innovation clusters established the functional templates—supplier network management and regulatory compliance—that now define global platform architectures.
United States
Automotive OEMs in Michigan and Ohio deploy predictive analytics for 10-year powertrain reserve forecasting. NHTSA defect reporting mandates and emerging state-level privacy laws in California and Virginia force region-isolated tenant configurations. Silicon Valley SaaS vendors anchor cloud-native architectures serving seasonal electronics retail spikes.
Germany
Industrial machinery producers in Baden-Württemberg retrofit warranty databases with carbon footprint attribution for EU CSRD compliance. KBA type-approval requirements extend traceability through tiered supplier networks. Munich-based automotive headquarters drive demand for multi-brand portfolio management systems.
China
SAMR enforcement of stricter product liability standards in consumer electronics accelerates automated claims adjudication adoption. Yangtze River Delta manufacturing clusters demand warranty registration platforms for BIS-equivalent quality tracking. Domestic software vendors compete on data sovereignty compliance for state-owned enterprise procurement.
India
BIS certification expansion for electronics imports creates warranty registration platform demand among Mumbai and Delhi-NCR distributors. RBI oversight of embedded insurance convergence opens retail banking distribution channels. Karnataka's technology services corridor hosts implementation partners for cloud migration programs.
Japan
METI carbon accounting rules now incorporate lifecycle emissions data into warranty reserve forecasting for industrial equipment exporters. Tokyo-based automotive suppliers deploy predictive maintenance integration with warranty systems. Osaka machinery manufacturers lead premium functionality tier adoption for sustainability reporting.
Warranty Management Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across ERP integration depth and predictive analytics sophistication. The market structures around three tiers: enterprise database incumbents with multi-industry footprints, vertical specialists dominating automotive aftermarket networks, and emerging SaaS vendors attacking mid-market electronics retail. Consolidation pressures intensify as AI-driven capability compression eliminates standalone actuarial software vendors. Strategic moves concentrate on API-first architecture investments and modular subscription unbundling.
Within the enterprise platform tier, Oracle Corporation and SAP SE occupy positions anchored by database and ERP integration requirements that sustain renewal rates among large manufacturers. Syncron exemplifies the vertical specialist archetype, representing aftermarket service network dominance where parts availability ties directly to warranty performance metrics. These three anchors illustrate how competitive positioning stratifies between horizontal scale and vertical depth.
| Leading Market Players |
|---|
| Simply Warranty |
| Snap-On Business Solutions |
| Oracle Corporation |
| SAP SE |
| Pegasystems |
| PTC |
| Zafire Ltd |
| WarrantyHub |
| Syncron |
| Others |
Value Chain & Pricing Dynamics
Enterprise-SME deployment bifurcation separates premium predictive analytics bundles from standardized SaaS claims processing, with automotive OEMs in Germany and the United States absorbing premium tiers while mid-market electronics retailers in India and Southeast Asia drive commoditization through usage-based contracts. This tier divergence concentrates margin capture among Oracle and SAP database incumbents while fragmenting downstream supplier recovery systems across tiered automotive networks.
Pricing Analysis
Modular subscription bundling across core claims processing and predictive analytics add-ons anchors enterprise procurement negotiations. Price differentiation hinges on ERP integration depth and AI-driven reserve forecasting sophistication, with automotive OEMs least sensitive due to multi-brand portfolio complexity. Pricing pressure stems from cloud-native SaaS vendors attacking mid-market electronics retail with seasonal usage-based models. SME distributors in India and Brazil exhibit highest price sensitivity as BIS certification mandates force platform adoption on constrained budgets.
Supply Chain Analysis
Reverse-logistics flows for refurbished electronics and remanufactured automotive parts create warranty data integration points between OEMs and aftermarket service networks. Software development concentrates in the United States, Germany, and India, with implementation services drawing from Bangalore and Hyderabad technology corridors. Cloud infrastructure rests on hyperscaler capacity in Ireland, Singapore, and Virginia. Single-source vulnerability runs through API gateway providers linking legacy ERP systems to modern SaaS architectures. Distribution runs through Oracle and SAP partner networks for enterprise accounts, with direct SaaS sales capturing mid-market electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in warranty management software hinges on AI capability compression eliminating standalone actuarial vendors, with predictive analytics bundling driving premium-tier upgrades among automotive OEMs.
For Market Incumbents: Extend predictive reserve forecasting into carbon accounting modules for EU CSRD compliance, capturing sustainability reporting budgets from industrial machinery exporters in Germany and Japan. Deepen API-first architecture investments to defend against cloud-native SaaS entrants attacking mid-market electronics retail with faster deployment timelines. Consolidate supplier network data quality through tier-3 automotive component maker onboarding programs. For New Entrants and Emerging Players: Embedded insurance distributors in Indian retail banking channels represent the most penetrable white-space target, with RBI oversight creating compliant entry pathways for warranty-registration platforms. Target SME manufacturers in Southeast Asia retiring legacy on-premise installations, where cloud migration cost compression outweighs brand loyalty to incumbent ERP vendors. Lead with rapid-deployment standardized workflows rather than customization depth. For Investors and Strategic Acquirers: Consolidation pressure builds where AI-driven capability compression eliminates standalone actuarial software vendors from automotive OEM procurement shortlists. Long-term viability favors platforms with vertical depth in automotive aftermarket networks or horizontal API connectivity spanning ERP and CRM ecosystems. Acquisition target archetypes include regional SaaS vendors with BIS certification compliance modules for Indian electronics distributors. Monitor EU MDR enforcement intensity as inflection indicator for medical device traceability platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity sustains renewal rates among large German automotive manufacturers. |
| Acquisition of Specialist Firm | Carbon accounting modules capture EU CSRD compliance budgets from machinery exporters. |
| Product Launch | AI-driven predictive analytics bundles displace standalone actuarial software vendors. |
| Strategic Partnership | Embedded insurance convergence opens retail banking distribution channels in India. |
| Geographic Expansion | Data-isolated tenant architectures address SAMR enforcement in Chinese consumer electronics. |
Study Parameters
Bottom-up enterprise deployment modeling reconciled against top-down cloud infrastructure spending tracking forms the analytical core. Primary interviews with warranty operations directors, IT procurement officers at automotive OEMs, aftermarket service network managers, and SaaS platform engineers combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and EU MDR regulatory filings. Triangulation across these sources anchors segmentation splits by deployment mode, vertical, and customer scale.
Historical trendline analysis of cloud migration timelines and AI capability adoption rates informed projection frameworks across the modeling period. Segmentation dimensions modeled include deployment architecture, industry vertical, organization size, integration complexity, and regional regulatory cluster. CAGRs derived from slope analysis of technology substitution curves and enterprise software procurement cycle patterns, with specific inputs from automotive extended warranty program expansions and electronics protection plan convergence trends.
Revisions become necessary when data sovereignty enforcement intensifies beyond current GDPR and emerging US state privacy law trajectories, or when automotive supplier network digitization accelerates faster than tier-3 component maker readiness allows. Forecasts reflect assumptions about cloud economics continuing to compress SME upgrade timelines and AI model accuracy improving sufficiently to consolidate predictive analytics markets. Practitioners should monitor EU CSRD auditor verification requirements and China SAMR product liability enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
3D Printing Medical Device Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
PLM Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Japan Qualitative Data Analysis Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Board Portal Market
Software & Services
Construction Simulation Software Market
Software & Services
Web Scraping Software Market
Software & Services
ID Photo Software Market
Software & Services
PAC Programming Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Plant Design Software Market