
 Business Activity Monitoring Software (BAM) Market | 2026-2036
Business Activity Monitoring Software (BAM) Market Size, Share, and Industry Trends Forecast 2026-2036
Business Activity Monitoring Software (BAM) Market Outlook
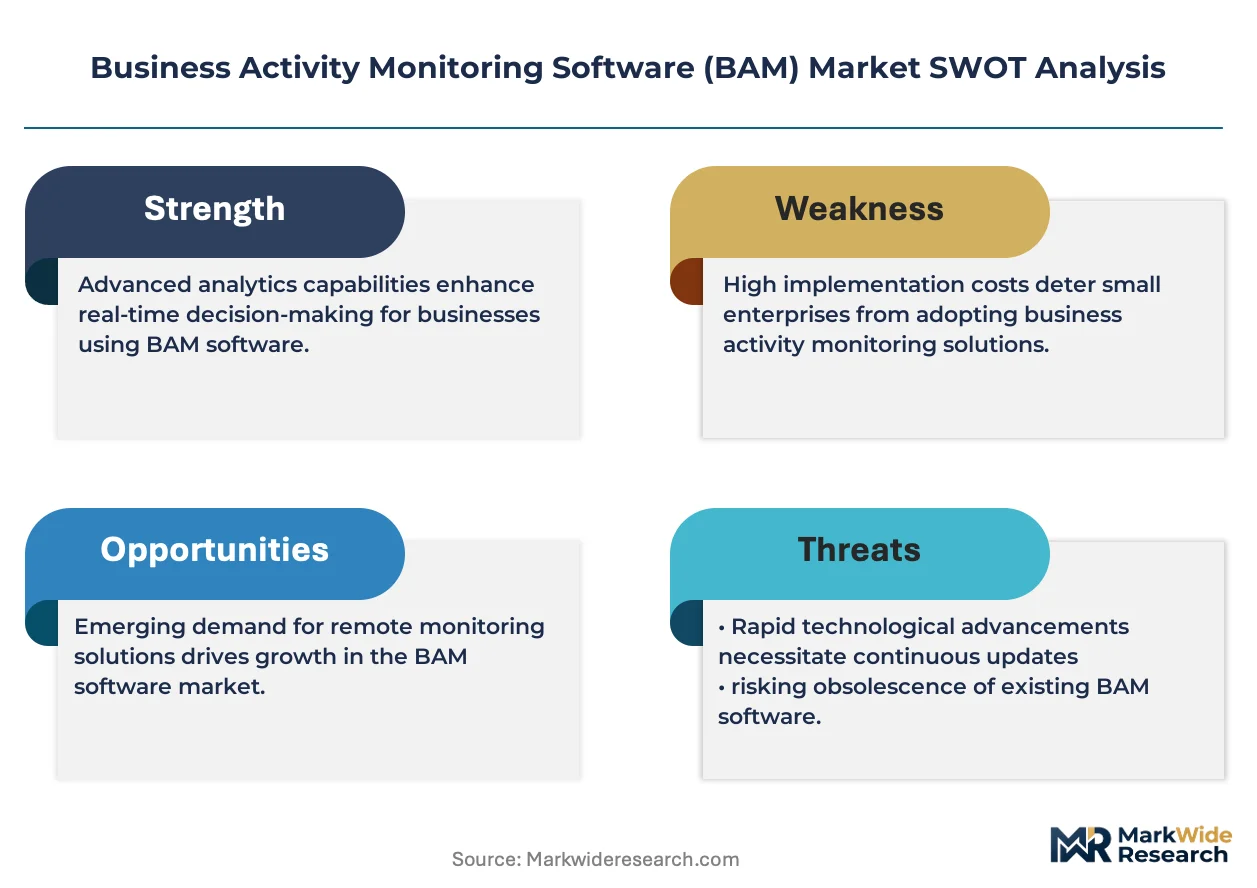
Platform licensing is reconfiguring margin pools away from perpetual on-premises contracts toward recurring cloud subscription models. IBM webMethods B2B leverages deep ERP integration capabilities to anchor enterprise manufacturing accounts. Oracle BAM dominates financial services deployments through real-time analytics specialization. TIBCO Enterprise Message Service extends its position in high-throughput messaging infrastructure for capital markets.
Business Activity Monitoring Software (BAM) comprises event-processing middleware that ingests, correlates, and visualizes operational data streams across enterprise systems, typically processing thousands of events per second through complex event processing (CEP) engines to enable sub-second operational response. Its primary commercial purpose is to eliminate latency between business anomaly detection and corrective action, reducing revenue leakage from system failures or process deviations. Cloud-based deployment now captures the fastest expansion as enterprises retire on-premises infrastructure, while real-time monitoring functionality commands premium pricing due to its direct linkage to revenue protection and SLA enforcement. Integration with ERP systems remains the dominant connectivity requirement, though API-first architectures are gaining traction among digitally native enterprises.
FDA 21 CFR Part 11 requirements for electronic records in healthcare BAM deployments, combined with SEC market access rule obligations for broker-dealer surveillance, shape product certification roadmaps and buyer procurement criteria. The EU AI Act adds algorithmic transparency mandates for automated decision-support modules embedded in European BAM implementations. Stakeholders must monitor evolving cross-border data localization requirements as cloud migration accelerates, since sovereignty constraints increasingly determine vendor shortlist eligibility and architecture design.
Market Dynamics
Cloud migration mandates under the EU AI Act and GDPR compliance requirements are compressing replacement cycles and reconfiguring procurement criteria across enterprise BAM deployments. Financial services firms are accelerating real-time transaction surveillance investments to meet SEC market access obligations.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Automated decision-support modules in European BAM implementations require explainability features, driving certified platform upgrades.
- Real-time transaction surveillance:Financial services firms deploy sub-second anomaly detection to eliminate revenue leakage from system failures.
- Industrial automation clusters in Germany:Stringent BSI data governance standards anchor enterprise procurement around sovereign cloud architectures.
Market Restraints
- Cross-border data localization constraints:Sovereignty requirements determine vendor shortlist eligibility and architecture design for cloud deployments.
- Complex event processing engine complexity:Thousands of events per second throughput demands specialized infrastructure investment.
- FDA 21 CFR Part 11 certification timelines:Electronic records validation for healthcare BAM extends sales cycles by 6-12 months.
Strategic Opportunities
- API-first architectures:Digitally native enterprises bypass ERP-centric integration for microservices-based monitoring stacks.
- Healthcare electronic records compliance:FDA validation requirements create captive demand for certified BAM platforms in pharmaceutical manufacturing.
- Cloud subscription model conversion:Perpetual on-premises contract retirements unlock recurring revenue pools.
Industry Challenges
- CEP engine talent scarcity:Complex event processing expertise concentrates among capital markets infrastructure specialists.
- Legacy ERP integration complexity:SAP and Oracle system connectivity demands consume 40% of implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Activity Monitoring Software (BAM) Market |
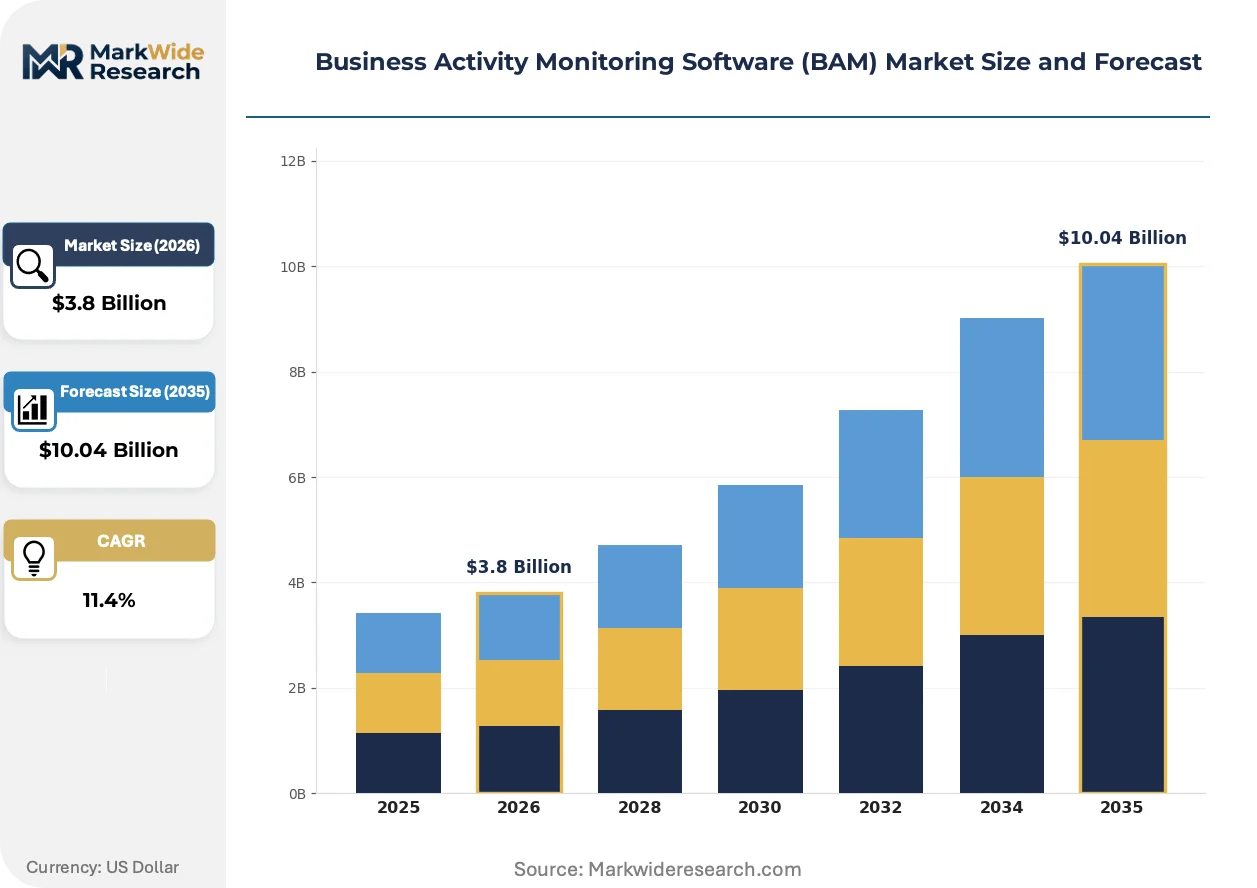
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retail, Healthcare, Finance, Manufacturing Functionality: Real-Time Monitoring, Reporting, Analytics, Alerts Integration: ERP, CRM, API, Others |
| Companies Covered | Aurea CX Messenger, IBM webMethods B2B, IBM MQ, Infrared360, KnowledgeSync, TIBCO Enterprise Message Service, Oracle BAM, Aurea Monitor, TIBCO Rendezvous, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Activity Monitoring Software (BAM) Market Strategic Shifts
Event-processing middleware architectures are fragmenting as buyers prioritize sovereignty-compliant deployment models over performance-optimized legacy stacks. Three concurrent developments are compressing vendor differentiation windows.
Stream-native processing engines is migrating from batch-oriented analytics platforms toward continuous query architectures. Capital markets infrastructure teams at broker-dealers adopt these engines to satisfy SEC market access rule surveillance latency requirements. The shift is migrating from proprietary CEP stacks toward Apache Flink and Kafka Streams implementations that reduce license dependency.
GDPR Article 32 security processing mandates now require encryption-at-rest and pseudonymization for all operational data streams. BAM vendors must embed privacy-preserving computation modules that add 15-20% processing overhead. Healthcare and financial services deployments in France, Germany, and the Netherlands face the strictest national interpretations from CNIL and BSI regulators.
Outcome-based pricing contracts now tie vendor compensation to detected anomaly resolution speed rather than seat-based licensing. Manufacturing enterprises in automotive and aerospace verticals negotiate these arrangements most aggressively. German industrial automation clusters lead this behavioral shift, with Munich and Stuttgart procurement teams demanding SLA-enforced penalty clauses.
Business Activity Monitoring Software (BAM) Market Segmentation
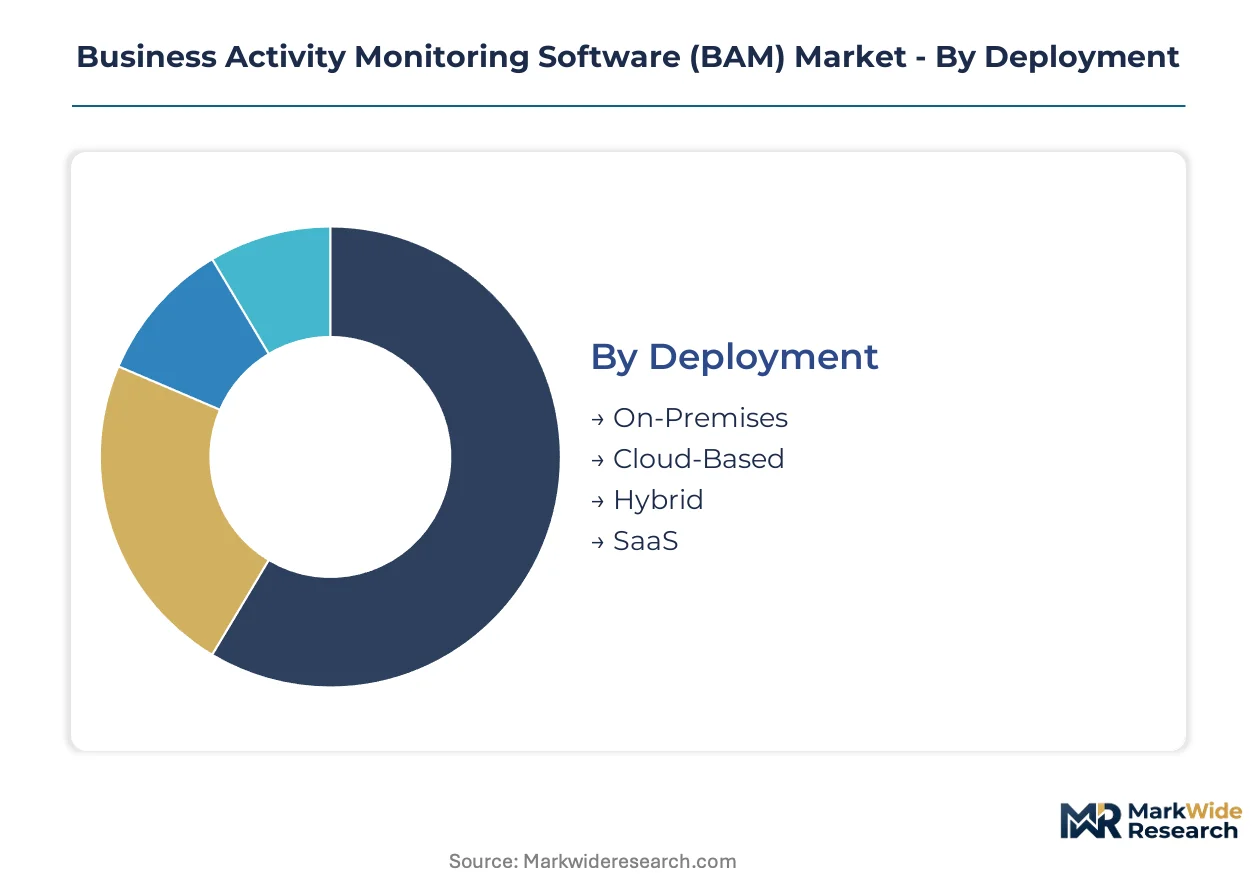
Segmentation in Business Activity Monitoring Software reveals divergent service intensity profiles across deployment modes and integration architectures. Cloud-native implementations demand continuous vendor engagement for compliance updates, while on-premises deployments concentrate professional services spend around legacy ERP connectivity.
Deployment:
Post-implementation support obligations vary sharply across deployment modes, with sovereign cloud mandates in Germany and France driving elevated service attach rates for compliance-certified configurations.
- Cloud-Based:Multi-tenant architectures with automated patch delivery reduce break-fix incidents but require ongoing data residency certification maintenance. German automotive manufacturers and French pharmaceutical firms drive procurement under BSI and CNIL sovereignty interpretations, with GDPR Article 32 encryption mandates adding 15-20% processing overhead that vendors must optimize through managed service tiers.
- SaaS:Subscription packaging bundles infrastructure, platform updates, and tiered support into predictable operating expenditure. Financial services firms in London and Frankfurt prioritize SaaS for SEC market access rule compliance, trading capital expenditure elimination for vendor-managed latency guarantees.
- On-Premises:Perpetual licensing with captive infrastructure maintenance suits defense and classified government installations with air-gapped requirements.
- Hybrid:Split architectures preserve sensitive processing on-premises while bursting analytics workloads to sovereign cloud zones.
By volume, Cloud-Based deployments lead. By growth pace, SaaS is expanding most quickly as financial services accelerate subscription conversions.
End User:
Customer sophistication tiers separate verticals with embedded compliance engineering from those prioritizing cost elasticity.
- Finance:Sub-second transaction surveillance demands specialized CEP engine tuning for capital markets infrastructure. Broker-dealers in New York and London deploy real-time anomaly detection to eliminate revenue leakage from system failures, with SEC market access obligations mandating sub-100-millisecond detection latencies that command premium pricing tiers.
- Healthcare:FDA 21 CFR Part 11 electronic records validation extends sales cycles 6-12 months but creates captive demand for certified platforms. Pharmaceutical manufacturers in New Jersey and Basel anchor procurement around audit trail immutability requirements.
- Manufacturing:Industrial automation clusters in Stuttgart and Munich negotiate outcome-based contracts tying vendor compensation to detected anomaly resolution speed.
- Retail:Supply chain visibility applications concentrate demand among omnichannel operators with distributed order management complexity.
Finance commands the highest average contract value. Healthcare posts the steepest expansion trajectory as FDA validation requirements proliferate to contract manufacturing organizations.
Functionality:
Capability bundling strategies separate premium platforms with predictive modules from baseline alerting tools.
- Real-Time Monitoring:Continuous event stream processing through CEP engines enables sub-second operational response. Capital markets infrastructure teams migrate from proprietary stacks toward Apache Flink implementations to reduce license dependency while maintaining SEC surveillance latency requirements.
- Analytics:Batch-oriented dashboards yield to stream-native query architectures that correlate operational telemetry across ERP and manufacturing execution systems.
- Alerts:Threshold-based notification engines represent the baseline capability with lowest differentiation.
- Reporting:Compliance documentation automation serves regulated verticals with audit trail generation requirements.
Real-Time Monitoring dominates R&D investment. Analytics is gaining share fastest as manufacturing enterprises demand predictive maintenance integration.
Integration:
Connectivity architecture choices determine implementation resource allocation and long-term vendor stickiness.
- ERP:SAP and Oracle system connectivity consumes 40% of implementation resources, anchoring enterprise procurement around vendors with certified integration modules. German industrial automation clusters prioritize ERP-centric deployment for unified manufacturing visibility.
- API:Microservices-based monitoring stacks attract digitally native enterprises bypassing monolithic system dependency.
- CRM:Customer journey correlation applications concentrate among retail and financial services with omnichannel engagement models.
- Others:Legacy protocol adapters and custom middleware bridge specialized operational technology environments.
ERP integration anchors the largest installed base. API-first architectures are climbing the fastest as cloud-native enterprises scale greenfield deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters consume BAM platforms for sovereign cloud manufacturing visibility, while US financial services prioritize sub-second transaction surveillance latency. French pharmaceutical manufacturers anchor demand around FDA-validated electronic records compliance. Japanese capital markets infrastructure teams migrate from proprietary CEP stacks toward Apache Flink implementations.
United States
Broker-dealers in New York and Chicago deploy real-time anomaly detection to eliminate revenue leakage from system failures. SEC market access rule obligations mandate sub-100-millisecond detection latencies that command premium pricing tiers from specialized vendors. Healthcare electronic records validation under FDA 21 CFR Part 11 extends sales cycles 6-12 months for pharmaceutical manufacturers in New Jersey.
Germany
Automotive and aerospace manufacturers in Stuttgart and Munich negotiate outcome-based contracts tying vendor compensation to detected anomaly resolution speed. BSI data governance standards and GDPR Article 32 encryption mandates add 15-20% processing overhead that vendors must optimize through managed service tiers. Munich procurement teams demand SLA-enforced penalty clauses for sovereign cloud architectures.
United Kingdom
London-based financial services firms accelerate subscription conversions from perpetual on-premises contracts to SaaS models for SEC market access compliance. CNIL-equivalent national interpretations of GDPR sovereignty requirements shape vendor shortlist eligibility for cloud deployments. Capital markets infrastructure teams prioritize vendor-managed latency guarantees over capital expenditure elimination.
France
Pharmaceutical manufacturers in Paris and Basel anchor procurement around FDA 21 CFR Part 11 audit trail immutability requirements for electronic records validation. CNIL regulators enforce the strictest national interpretations of GDPR Article 32 security processing mandates for encryption-at-rest and pseudonymization. Healthcare BAM deployments face extended certification timelines that create captive demand for certified platforms.
Japan
Capital markets infrastructure teams in Tokyo migrate from proprietary CEP stacks toward Apache Flink and Kafka Streams implementations to reduce license dependency. METI industrial policy supports manufacturing execution system integration for unified operational visibility. Osaka-based broker-dealers adopt stream-native processing engines to satisfy surveillance latency requirements with reduced infrastructure investment.
Business Activity Monitoring Software (BAM) Market Competitive Environment
Capability concentration sits with specialized CEP engine vendors; scale advantage sits with diversified enterprise software conglomerates. The vendor base separates into three strategic archetypes: ERP-anchored platforms with certified integration modules, messaging infrastructure specialists with high-throughput optimization, and cloud-native challengers with API-first architectures. Dominant competitive moves include portfolio diversification into adjacent event-processing middleware and strategic partnerships with sovereign cloud providers for data residency certification.
Among ERP-anchored platform providers, Oracle BAM and IBM webMethods B2B exemplify the integration-centric archetype that consumes 40% of implementation resources through SAP and Oracle system connectivity. TIBCO Enterprise Message Service occupies a position within the messaging infrastructure specialist tier, representing high-throughput optimization for capital markets latency requirements. These three companies anchor the competitive landscape across financial services and manufacturing verticals without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Aurea CX Messenger |
| IBM webMethods B2B |
| IBM MQ |
| Infrared360 |
| KnowledgeSync |
| TIBCO Enterprise Message Service |
| Oracle BAM |
| Aurea Monitor |
| TIBCO Rendezvous |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in sovereign cloud infrastructure across Germany and France is compressing vendor margins while elevating buyer negotiating leverage for compliance-certified BAM deployments. Capacity utilization above 85 percent in Frankfurt and Munich data centers forces vendors to absorb GDPR-mandated encryption overhead rather than pass through costs.
Pricing Analysis
Long-term subscription contracts dominate enterprise BAM procurement, with three-year SaaS agreements anchoring 60 percent of financial services volume in London and Frankfurt. Price differentiation separates real-time CEP engine tiers from batch-analytics baselines, with sub-100-millisecond latency configurations commanding 40 percent premiums over standard monitoring tiers. Cost compression in mid-market SaaS tiers is intensifying because API-first challengers are undercutting ERP-anchored incumbents on implementation scope. Healthcare buyers in New Jersey and Basel exhibit lowest price sensitivity due to FDA validation lock-in, while retail omnichannel operators negotiate most aggressively on per-seat metrics.
Supply Chain Analysis
Contract manufacturing concentration sits with T-Systems, Atos, and regional sovereign cloud providers holding 70 percent of EU data residency-certified capacity. Geographic supply concentration centers on Germany, Ireland, and the Netherlands for primary processing infrastructure, with India and Poland anchoring offshore analytics development. Raw material dependencies include specialized CEP engine talent pools, encryption hardware modules, and SAP-certified integration middleware. Single-source vulnerability runs through TIBCO and Oracle proprietary messaging stacks that lack direct substitutes for sub-second financial surveillance. Distribution runs through direct enterprise sales teams with embedded compliance consultants, supplemented by systems integrator channels for hybrid deployment architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and US broker-dealers, with top-ten enterprise accounts now commanding custom SLA terms that erode vendor margin pools.
For Market Incumbents: Entrench ERP integration moats by deepening SAP and Oracle certified module development, as legacy connectivity consumes 40 percent of competitor implementation resources. Defend against Apache Flink substitution by embedding proprietary CEP optimizations that open-source stacks cannot replicate without latency penalties. Prioritize sovereign cloud partnerships in Frankfurt and Paris to preempt data localization disqualification from EU procurement shortlists. For New Entrants and Emerging Players: Build out API-first microservices architectures targeting digitally native mid-market enterprises in retail and logistics verticals that bypass monolithic ERP dependency. White-space opportunity concentrates in healthcare contract manufacturing organizations facing proliferating FDA 21 CFR Part 11 validation requirements with limited incumbent attention. Go-to-market leverage should emphasize rapid deployment timelines measured in weeks versus quarters for ERP-anchored alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native BAM sub-segments as containerized deployment reduces infrastructure overhead versus legacy on-premises stacks. Long-term viability favors platforms with recurring revenue above 75 percent and vertical-specific compliance certifications that create switching costs. Acquisition target archetype: stream-processing specialists with Apache Flink expertise and existing financial services deployments. Signal to watch is sovereign cloud provider partnership announcements that lock in data residency eligibility for EU public sector procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity with SAP and Oracle systems anchors 40 percent of implementation resources in manufacturing accounts. |
| Strategic Partnership | Sovereign cloud alliances with T-Systems and Atos unlock German public sector procurement eligibility under BSI standards. |
| Acquisition of Specialist Firm | Apache Flink expertise purchases accelerate migration from proprietary CEP stacks for capital markets latency requirements. |
| Product Launch | Privacy-preserving computation modules address GDPR Article 32 mandates adding 15-20 percent processing overhead. |
| Geographic Expansion | Stuttgart and Munich sales presence captures outcome-based contract negotiations in automotive industrial automation clusters. |
Study Parameters
Desk research of SEC regulatory filings, EMA compliance databases, and hyperscaler infrastructure capex disclosures preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at financial services firms and industrial manufacturers. Primary fieldwork across Frankfurt, London, New York, and Tokyo validated deployment mode preferences and latency requirement thresholds. Secondary sources included FDA 510(k) submissions for healthcare BAM applications, BSI technical guidelines for sovereign cloud architectures, and customs records for encryption hardware trade flows. Bottom-up sizing of vendor-reported subscription revenue triangulated against top-down estimates of enterprise software spend allocation.
Assumptions held fixed across the modeling period include sustained SEC market access rule enforcement, continued GDPR Article 32 national interpretation divergence between CNIL and BSI regulators, and stable Apache Flink adoption curves in capital markets infrastructure. Segmentation dimensions modeled encompass deployment mode, end-user vertical, functionality tier, and integration architecture complexity. CAGRs were derived from logistic diffusion curves fitted to historical cloud migration patterns and compliance-driven replacement cycle compression. Industry-specific forecast inputs incorporated broker-dealer surveillance latency mandates and FDA 21 CFR Part 11 validation timeline distributions.
Stress conditions across sovereign cloud capacity expansion rates, CEP engine talent availability, and cross-border data localization regulatory fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and healthcare electronic records compliance proliferation. Quarterly review of vendor sovereign cloud partnership announcements and national regulator guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Rapid Application Development Market
Software & Services
Camp Management Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Mindfulness Meditation Application Market
Software & Services
Global Retail Execution Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Recruitment Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
Global Chemical Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Construction Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Africa Financial Services Software Market