
 Decision Support System (DSS) Software Market | 2026-2036
Decision Support System (DSS) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Decision Support System (DSS) Software Market Analysis
Subscription-based access to software-defined analytics features is realigning how enterprises procure decision-support capabilities. Oracle Analytics Cloud leverages deep database integration to anchor its position in on-premises-to-cloud migration scenarios. Microsoft Power BI competes aggressively through native embedding within productivity suites that dominate corporate desktops. ThoughtSpot differentiates by extending natural-language query interfaces to non-technical business users.
Decision Support System software comprises interactive computational tools that ingest structured and unstructured data, apply analytical models—ranging from rule-based engines to neural networks—and present actionable recommendations through dashboards or automated alerts. Its primary commercial purpose is reducing decision latency and cognitive bias in complex operational environments where data volume exceeds unaided human processing capacity. Cloud-based deployment now captures the fastest expansion as enterprises retire capital-intensive server farms, while predictive analytics functionality commands premium pricing due to specialized machine-learning engineering requirements. On-premises installations persist in financial services and defense segments where data sovereignty concerns override cost optimization.
The United States Federal Trade Commission scrutinizes algorithmic fairness in consumer-facing DSS applications, while the European Union's AI Act imposes conformity assessments on high-risk automated decision systems. The Securities and Exchange Commission's disclosure rules for predictive analytics in investment advice further constrain product architecture for financial services vendors. Stakeholders must monitor evolving cross-border data-localization requirements that could fragment cloud delivery architectures and force region-specific platform instances.
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing vendors to re-architect platforms for algorithmic transparency, compressing deployment timelines while elevating compliance costs across financial services and defense procurement channels.
Growth Catalysts
- Federal Modernization Mandates:United States defense contractors and intelligence agencies are replacing legacy analytical infrastructure with interoperable cloud-native systems, creating sustained procurement pipelines for compliant vendors.
- EU AI Act Conformity Assessments:Automated decision systems classified as high-risk must undergo third-party auditing, generating recurring revenue streams for platform providers offering built-in explainability modules.
- Neural Network Integration:Predictive analytics functionality incorporating deep learning architectures commands premium pricing as financial institutions automate credit-risk decisions and fraud detection workflows.
Market Restraints
- Machine Learning Engineering Scarcity:Specialized talent required for predictive model development limits vendor scaling capacity and inflates implementation costs for complex deployments.
- Data Sovereignty Requirements:Financial services and defense segments in Germany, France, and the United States mandate on-premises or region-locked cloud instances, fragmenting platform architectures and diluting economies of scale.
- Algorithmic Fairness Scrutiny:The United States Federal Trade Commission's enforcement actions against biased consumer-facing DSS applications create litigation exposure that slows product release cycles.
Strategic Opportunities
- Natural Language Interface Expansion:Non-technical business users in mid-market enterprises represent an underpenetrated segment for query tools that bypass SQL and dashboard dependencies.
- Cross-Border Compliance Bundling:Vendors offering simultaneous SEC disclosure rule alignment and EU AI Act conformity assessment positioning capture financial services firms operating across jurisdictions.
- Edge Deployment Architectures:Convergence of containerized analytics and 5G infrastructure enables real-time decision support for manufacturing and logistics operations requiring sub-second latency.
Industry Challenges
- Explainability Engineering Bottlenecks:Translating neural network outputs into auditable decision trails consumes development resources and extends certification timelines for high-risk system classifications.
- Legacy System Integration Friction:Mainframe data architectures in established financial institutions resist API-based connectivity, requiring costly middleware development for hybrid cloud deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decision Support System (DSS) Software Market |
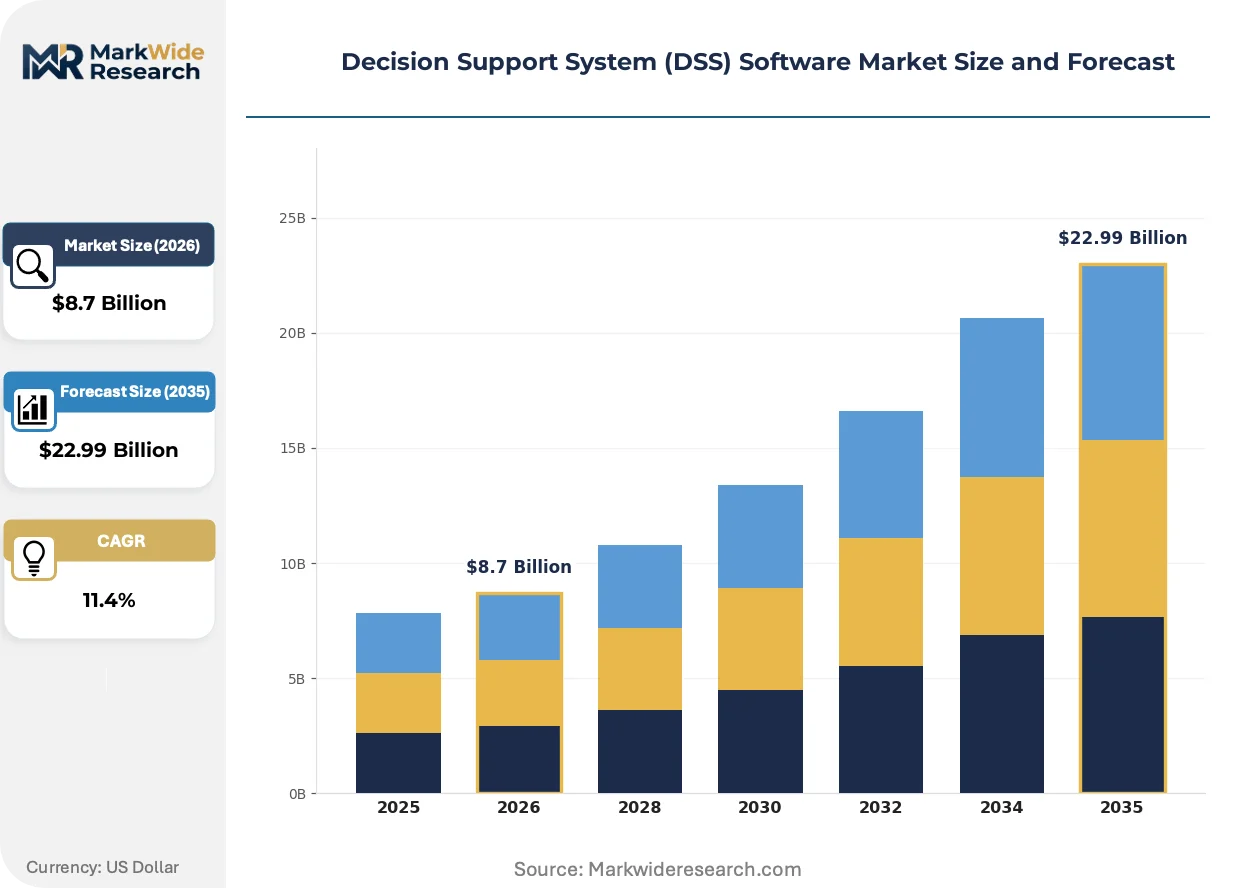
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Retail, Manufacturing, Financial Services Functionality: Predictive Analytics, Data Visualization, Reporting Tools, Geographic Information Industry Vertical: Telecommunications, Agriculture, Education, Transportation |
| Companies Covered | Google Looker, Oracle Analytics Cloud, Microsoft Power BI, Aera Decision Cloud, SAP Analytics Cloud, Salesforce Tableau, ThoughtSpot, FICO Decision Management Platform, Qlik Sense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decision Support System (DSS) Software Market Emerging Trajectories
Decision-support platforms are converging around composable architectures that embed analytical capabilities directly into operational workflows rather than functioning as standalone applications requiring context switching.
Natural language processing engines are consolidating query interfaces across enterprise software stacks. Business users in retail and healthcare operations are adopting conversational analytics tools that bypass traditional dashboard dependencies. This interface standardization is compressing training requirements and expanding addressable user bases beyond data science specialists.
The EU AI Act's risk-based classification system is mandating conformity assessments for automated credit and insurance decision engines. Vendors must maintain technical documentation and human oversight protocols for high-risk deployments. Financial services firms in France and Germany are prioritizing platforms with pre-certified explainability modules to accelerate regulatory approval timelines.
Subscription-based access models are displacing perpetual license structures in mid-market procurement. Chief information officers in United States healthcare and manufacturing verticals favor consumption-aligned pricing that scales with query volume rather than fixed-capacity deployments. This shift pressures traditional vendors to restructure revenue recognition and customer success functions around usage metrics rather than upfront commitments.
Decision Support System (DSS) Software Market Segmentation
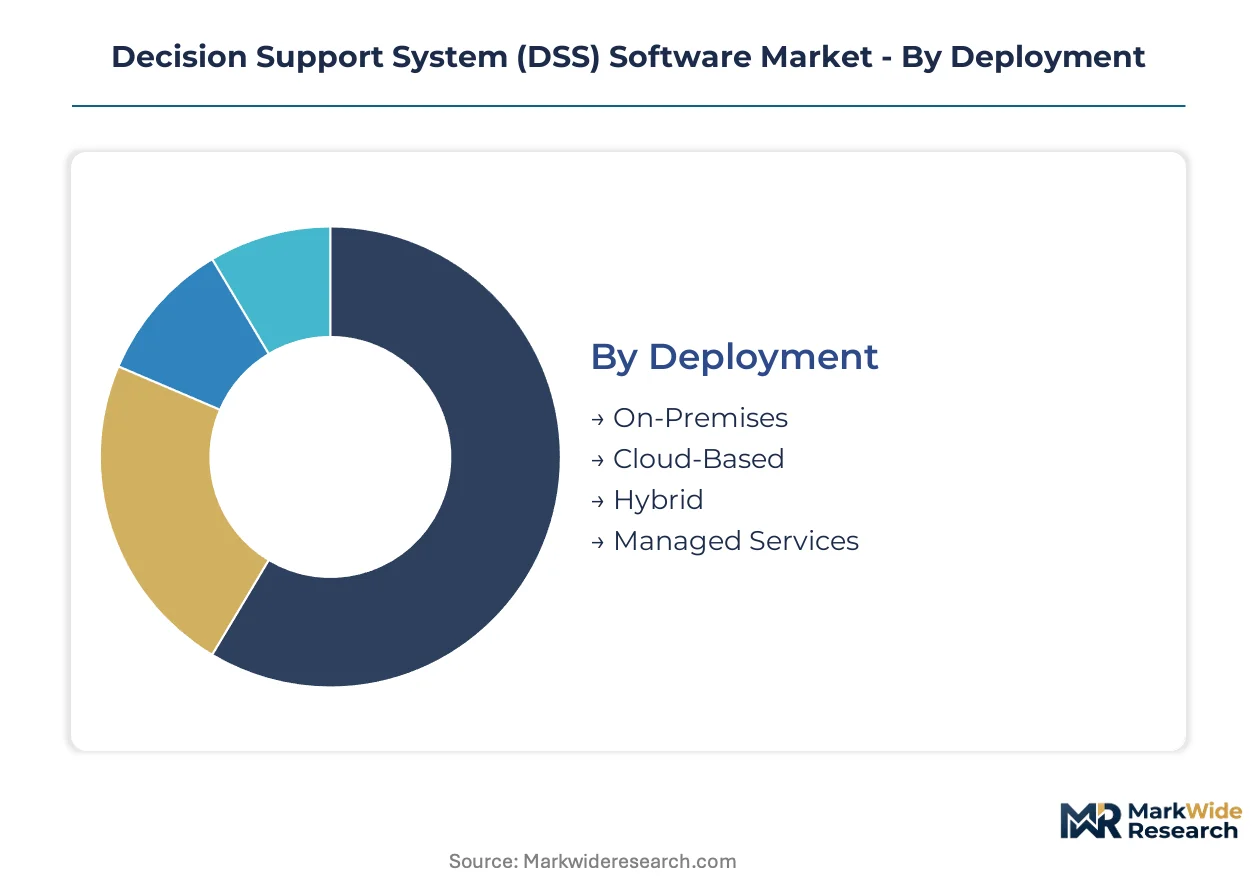
Deployment architecture and functional specialization determine pricing power and customer retention in the Decision Support System software market. Vendors configure platform modules around data sovereignty requirements, end-user technical sophistication, and vertical-specific compliance obligations.
Deployment:
Standardized cloud instances compete against heavily customized on-premises installations across this spectrum, with hybrid architectures emerging where regulatory fragmentation forces architectural compromise.
- On-Premises:Hardware-resident installations with direct database integration serve defense contractors and German financial institutions where data localization laws prohibit cross-border cloud transmission. Bundesbank supervision requirements and United States Department of Defense security classifications sustain premium pricing despite higher total cost of ownership.
- Cloud-Based:Multi-tenant SaaS architectures with API-first design enable rapid provisioning for mid-market healthcare systems and retail chains. United States hospital networks accelerating electronic health record consolidation favor consumption-based pricing that aligns with fluctuating patient volume analytics needs.
- Hybrid:Split workloads maintaining sensitive data on-premises while routing computational tasks to cloud infrastructure address French insurance carriers navigating CNIL guidance on automated underwriting systems.
- Managed Services:Vendor-operated dedicated instances with guaranteed uptime SLAs attract Japanese manufacturing conglomerates lacking internal data engineering capacity for predictive maintenance deployments.
Leading the category by volume: Cloud-Based. Expanding most quickly: Hybrid.
End User:
Procurement sophistication varies dramatically across this category, from centralized IT governance in financial services to distributed departmental purchasing in healthcare systems.
- Healthcare:Clinical decision support modules integrating electronic health records dominate hospital procurement, with United States health systems prioritizing HIPAA-compliant predictive readmission risk scoring.
- Retail:Real-time inventory optimization and demand forecasting tools command premium pricing as omnichannel fulfillment networks require sub-hour replenishment decisions.
- Manufacturing:Shop-floor quality control systems with computer vision integration attract German automotive suppliers modernizing legacy MES architectures.
- Financial Services:Credit risk engines with explainable AI documentation accelerate under SEC disclosure rules and EU AI Act high-risk system classifications, generating recurring compliance revenue for platform vendors.
Dominating procurement value: Financial Services. Steepest expansion trajectory: Healthcare.
Functionality:
Engineering intensity and talent scarcity create margin stratification across functional modules, with neural network development commanding specialized pricing.
- Predictive Analytics:Machine learning pipelines incorporating time-series forecasting and anomaly detection automate fraud detection for United States card issuers and equipment failure prediction for offshore energy operators.
- Data Visualization:Self-service dashboard builders with drag-and-drop interfaces expand addressable user bases beyond SQL-proficient analysts into operational management layers.
- Reporting Tools:Scheduled distribution engines with regulatory template libraries serve European banking supervisors requiring standardized risk exposure disclosures under ECB guidelines.
- Geographic Information:Spatial analytics layering demographic and infrastructure data support telecommunications network planning and precision agriculture yield optimization.
Highest revenue concentration: Predictive Analytics. Gaining share fastest: Data Visualization.
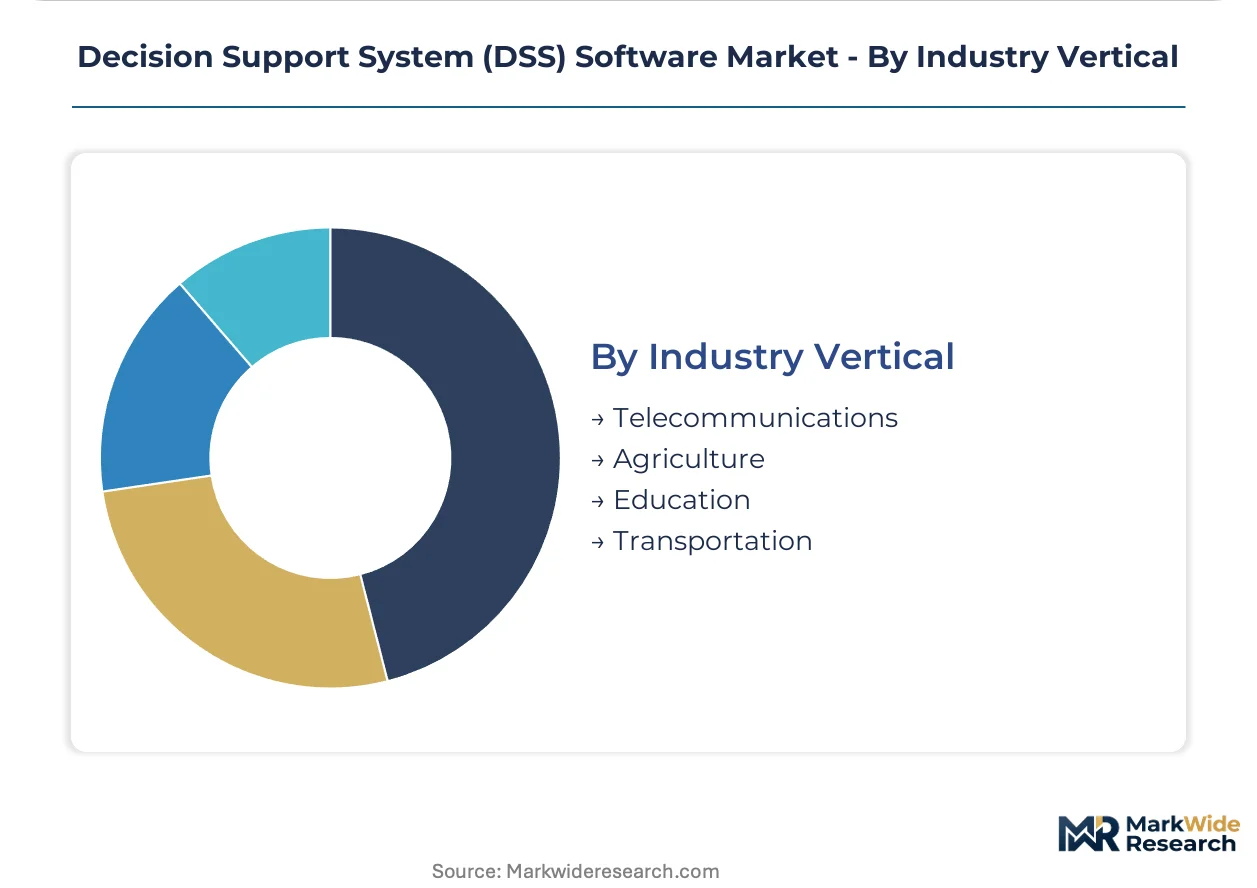
Industry Vertical:
Maturity cycles and infrastructure investment timing differentiate vertical adoption patterns, with early-digitizing sectors now consolidating fragmented point solutions.
- Telecommunications:Network capacity planning and churn prediction models process subscriber behavior data at scale, with 5G rollout investments driving demand for real-time decision engines.
- Agriculture:Variable rate input optimization and commodity price forecasting tools penetrate large-scale farming operations in Brazil and the United States Corn Belt.
- Education:Student retention analytics and enrollment forecasting modules attract United States public university systems facing demographic headwinds.
- Transportation:Route optimization and predictive maintenance systems integrate IoT sensor streams for logistics fleets and rail operators.
Current spending leader: Telecommunications. Emerging fastest: Agriculture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent concentrates disproportionately in the United States and India, while enterprise procurement spending distributes across mature European and Asian markets. Cloud infrastructure investment patterns diverge sharply between data-sovereignty-conscious jurisdictions and deregulated commercial environments.
United States
Federal defense contractors and intelligence agencies drive specialized procurement for classified analytical infrastructure. The SEC mandates disclosure frameworks for predictive analytics in investment advice, forcing architecture redesigns among financial services vendors. Silicon Valley clusters anchor cloud-native development, while Washington D.C. metro corridors concentrate security-cleared implementation teams serving federal accounts.
Germany
Automotive suppliers and industrial conglomerates demand hybrid deployment models balancing on-premises data control with cloud computational scale. Bundesbank supervision requirements and BSI technical guidelines enforce strict audit trails for automated credit decisions. Munich and Stuttgart industrial corridors host dedicated implementation practices serving Mittelstand manufacturers modernizing legacy MES architectures.
United Kingdom
Financial services firms in the City of London prioritize cross-border compliance bundling for simultaneous SEC and EU AI Act alignment. The Financial Conduct Authority scrutinizes algorithmic trading systems for market manipulation risks. London's fintech cluster attracts vendor engineering teams configuring explainability modules for investment banking workflows.
India
IT services exporters and captive centers of multinational corporations drive demand for cost-optimized analytics platforms. RBI guidelines on digital lending algorithms impose documentation requirements for automated credit decisions. Bangalore and Hyderabad technology corridors concentrate engineering talent developing predictive maintenance solutions for global manufacturing clients.
Japan
Manufacturing conglomerates lacking internal data engineering capacity favor managed service arrangements with guaranteed uptime commitments. METI's AI governance guidelines emphasize human oversight protocols for high-risk automated systems. Tokyo and Nagoya industrial zones host vendor delivery centers serving automotive and electronics producers implementing shop-floor quality control analytics.
Decision Support System (DSS) Software Market Vendor Landscape
Capital-heavy platform vendors compete with asset-light specialists for enterprise analytics budgets. Market structure tilts toward consolidation as database incumbents leverage deep integration advantages against standalone visualization tools. Three archetypes dominate: hyperscale cloud providers with productivity suite distribution, enterprise software vendors with vertical-specific modules, and pure-play analytics specialists with natural-language interfaces. Competitive dynamics center on M&A activity absorbing point-solution vendors and strategic partnerships embedding analytical capabilities within operational software stacks.
Within the hyperscale tier, Microsoft and Google exemplify platform consolidation through productivity and cloud infrastructure integration. Oracle anchors the enterprise database incumbent position, leveraging on-premises-to-cloud migration scenarios. Among pure-play specialists, ThoughtSpot occupies a distinct position targeting non-technical business users through conversational query interfaces.
| Leading Market Players |
|---|
| Google Looker |
| Oracle Analytics Cloud |
| Microsoft Power BI |
| Aera Decision Cloud |
| SAP Analytics Cloud |
| Salesforce Tableau |
| ThoughtSpot |
| FICO Decision Management Platform |
| Qlik Sense |
| Others |
Supply Flow & Price Mechanics
Captive engineering capacity in India and Poland anchors supply positions for mid-market vendors while hyperscale cloud providers leverage in-house infrastructure to compress third-party hosting costs. This integration choice separates premium explainability modules from commodity visualization tiers.
Pricing Analysis
Margin tightening in cloud-native tiers reflects hyperscaler bundling strategies that subsidize analytics seats through productivity suite attachment. Three-tier pricing structure across premium, standard, and economy levels stratifies by explainability certification depth and model complexity. Price differentiation hinges on EU AI Act conformity documentation and SOC 2 Type II attestation. Mid-market healthcare buyers exhibit highest price sensitivity; defense contractors accept premium positioning for air-gapped deployments.
Supply Chain Analysis
Machine learning engineering scarcity in Bangalore and Warsaw constrains vendor scaling velocity despite abundant cloud infrastructure. Talent pipelines draw from Indian Institutes of Technology and Warsaw Polytechnic programs feeding captive development centers. GPU cluster procurement rests on NVIDIA allocation priority and spot-market pricing volatility. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with implementation partner overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineering scarcity props pricing power for vendors with certified explainability modules, constraining supply expansion faster than demand absorption.
For Market Incumbents: Deepen vertical integration into specialized compliance documentation services to capture recurring EU AI Act conformity revenue. Anchor defensive positioning through pre-certified deployment templates that accelerate procurement timelines for financial services buyers threatened by emerging natural-language interface specialists. For New Entrants and Emerging Players: Enter via underpenetrated mid-market manufacturing segments in Japan and Germany lacking internal data engineering capacity. Target managed service arrangements with guaranteed uptime SLAs as the most penetrable wedge. Lead with edge-deployment architectures converging containerized analytics and 5G infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscale platform absorption of point-solution vendors with differentiated natural-language interfaces. Long-term viability favors vendors with simultaneous SEC disclosure alignment and EU AI Act certification positioning. Watch regulatory enforcement velocity against algorithmic fairness as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding within Microsoft 365 and Google Workspace compresses procurement friction for enterprise buyers. |
| Acquisition of Specialist Firm | Absorption of natural-language query vendors accelerates non-technical user penetration in mid-market segments. |
| Geographic Expansion | Dedicated cloud instances in Frankfurt and Singapore address Bundesbank and MAS data sovereignty mandates. |
| Strategic Partnership | System integrator alliances with Accenture and Deloitte extend implementation capacity for hybrid deployments. |
| Product Launch | Pre-certified explainability modules reduce EU AI Act conformity assessment timelines for French insurers. |
Methodological Framework
Multi-period observation of vendor pricing disclosures, regulatory filing patterns, and cloud infrastructure capex trajectories anchored the trend analysis, supplemented by interviews with chief information officers, procurement leads at financial services firms, platform engineers at hyperscalers, and compliance officers navigating EU AI Act implementation. Secondary validation drew from SEC 10-K risk factor disclosures, EU Official Journal regulatory texts, and cloud provider trust center documentation. Bottom-up deployment volume estimates triangulated against top-down enterprise software spending benchmarks.
Segment-weighting applied deployment architecture splits, vertical concentration indices, and functionality tier distributions across the projection horizon. CAGRs derived from logistic adoption curves fitted to historical cloud migration patterns and regulatory compliance deadline clustering. Forecast inputs incorporated Federal Trade Commission enforcement velocity and European Securities and Markets Authority guidance evolution on algorithmic trading disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or sudden tariff disruption to cross-border data flows. Material deviation in regulatory interpretation timelines or hyperscaler bundling strategy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
US Software Consulting Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Reporting Software Market
Software & Services
Customs Declaration Software Market
Software & Services
Parametric Design Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Terminal Emulator Software Market
Software & Services
Software Consulting Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Non-Profit Software Market