
 Test Automation Market | 2026-2036
Test Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Test Automation Market Outlook
India's software services corridor is reshaping how enterprises source automated testing capabilities. IBM leverages its hybrid cloud platform to anchor multi-environment test orchestration for Fortune 500 clients. Tricentis sustains technology leadership through model-based test automation that reduces script maintenance overhead. Keysight Technologies dominates hardware-in-the-loop validation for 5G and semiconductor applications where software meets physical systems.
Test automation encompasses the use of specialized software frameworks, scripts, and AI-driven engines to execute preconfigured test cases against applications, APIs, and embedded systems without manual intervention, typically operating through CI/CD pipelines with execution speeds measured in milliseconds per test case. Its primary purpose is to accelerate release cycles while maintaining defect detection coverage across increasingly complex distributed architectures. Cloud-based tool types are capturing the fastest expansion as organizations retire on-premise server farms for elastic consumption models. SaaS deployment models concentrate margin pools through recurring revenue structures that lock in multi-year enterprise commitments. System testing and acceptance testing levels command premium pricing due to their direct linkage with production release authorization workflows.
FDA validation requirements for medical device software enforce traceable test documentation that elevates demand for compliant automation platforms in regulated industries. The EU AI Act and GDPR impose algorithmic accountability mandates that force enterprises to automate bias detection and decision-audit trails across AI-infused applications. ISO 25010 quality standards and IEC 62304 medical device software frameworks further tighten test coverage requirements for safety-critical systems. Stakeholders must weigh vendor lock-in risks against the operational agility gained through cloud-native test infrastructure as regulatory scope widens beyond traditional software into autonomous and AI-generated code domains.
Market Dynamics
CI/CD pipeline acceleration is compressing test execution windows from hours to minutes, forcing enterprises to abandon manual validation for autonomous test orchestration frameworks that self-heal when application interfaces shift.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:Enterprises must automate bias detection and decision-audit trails across AI-infused applications, elevating demand for compliant validation platforms.
- Medical device software traceability requirements:FDA validation standards enforce documented test coverage that drives adoption of automation tools in regulated healthcare technology development.
- India's IT services corridor expansion:Offshore testing capacity concentrated in Bangalore and Hyderabad delivers cost-efficient automation talent pools for North American and European enterprises.
Market Restraints
- Specialized engineering talent scarcity:Shortage of professionals combining software development expertise with domain-specific testing knowledge inflates labor costs and extends implementation timelines.
- Script maintenance burden accumulation:Test automation frameworks require continuous refactoring when underlying applications undergo frequent UI or API modifications, eroding efficiency gains.
- Cloud infrastructure dependency concentration:Reliance on hyperscale cloud providers for elastic test execution environments creates single-point-of-failure risks and egress cost volatility.
Strategic Opportunities
- Embedded systems hardware-in-the-loop validation:Convergence of physical semiconductor testing with software automation opens expansion paths in automotive and telecommunications equipment manufacturing.
- ISO 25010 quality standard adoption:Systematic quality attribute measurement frameworks create demand for automated non-functional testing across safety-critical software domains.
- Outcome-based service contracting models:Enterprise buyers increasingly prefer pricing tied to defect detection rates and release velocity improvements rather than seat-based licensing.
Industry Challenges
- Test data provisioning complexity:Synthetic data generation and privacy-compliant dataset management consume disproportionate engineering resources in GDPR-regulated environments.
- Cross-platform environment fragmentation:Device and browser multiplicity in mobile application testing multiplies execution matrix complexity and infrastructure costs.
- AI-generated code validation gaps:Large language model outputs lack deterministic behavior patterns, complicating traditional assertion-based test design methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Automation Market |
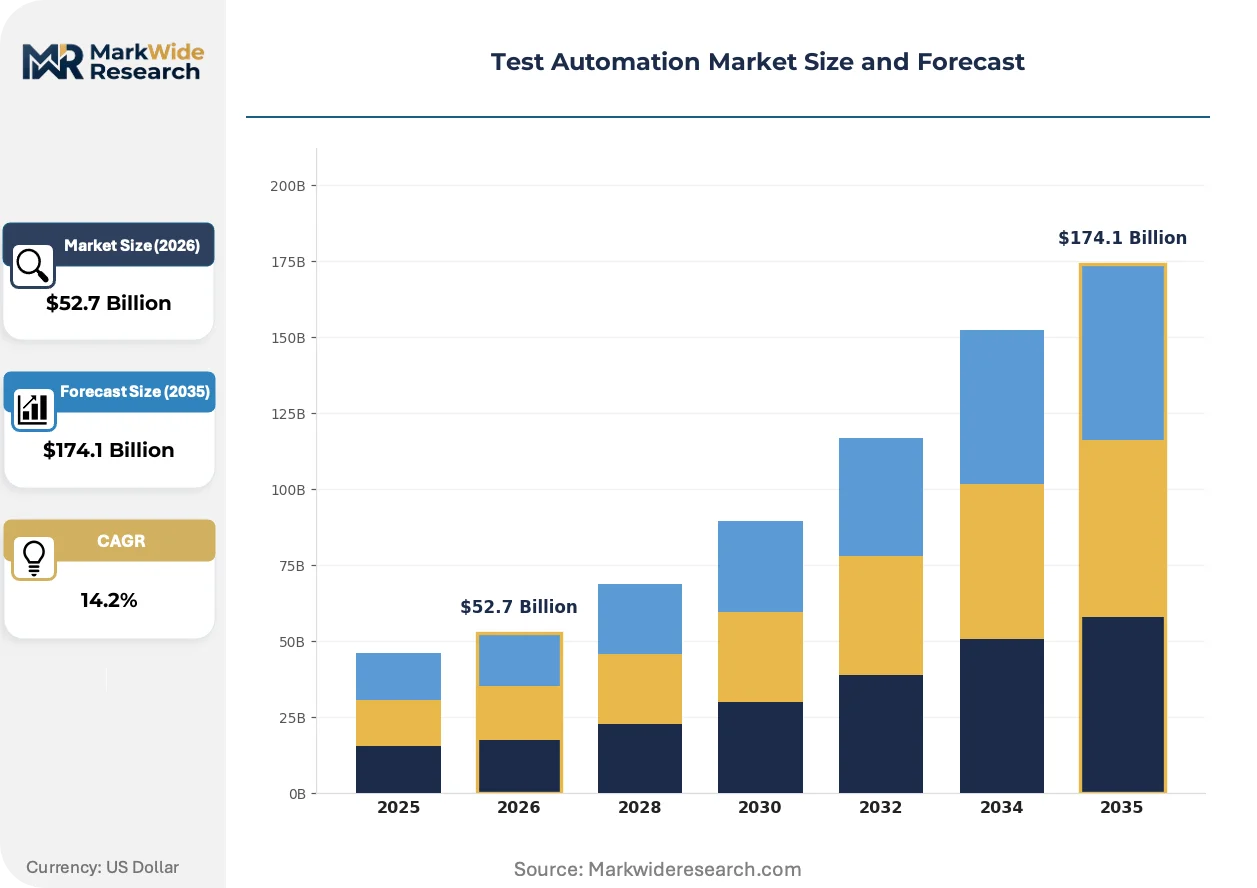
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $174.1 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Open Source, Commercial, Hybrid, Cloud-based Deployment Model: On-Premise, SaaS, PaaS, Managed Services Test Level: Unit Testing, Integration Testing, System Testing, Acceptance Testing End User: Software Developers, QA Engineers, Enterprises, Startups |
| Companies Covered | IBM, Tricentis, Capgemini, OpenText, Accenture, Cigniti Technologies, Keysight Technologies, Parasoft, SmartBear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Automation Market Strategic Shifts
Model-based test automation is supplanting script-heavy frameworks as the dominant architectural paradigm, compressing maintenance overhead while expanding coverage across microservices architectures.
Self-healing test scripts are migrating from experimental implementations to production-grade capabilities. Financial services firms with high-frequency release cycles deploy machine learning algorithms that automatically adapt locators when application interfaces change. This capability is compressing the traditional test maintenance tax that previously consumed thirty to fifty percent of automation engineering hours.
The EU AI Act's algorithmic accountability requirements are reshaping validation workflows for machine learning systems. Enterprises must now maintain automated audit trails documenting training data provenance and decision logic across model inference pipelines. Healthcare and financial services sectors in Germany and France are investing most aggressively in bias detection automation to preempt regulatory enforcement actions.
Consumption-based pricing models are displacing perpetual licensing in enterprise procurement patterns. Buyers now prioritize vendors offering elastic compute allocation that scales with actual test execution volume rather than fixed seat counts. This shift is most pronounced among mid-market software companies in the United States and United Kingdom seeking to align validation costs with release frequency fluctuations.
Test Automation Market Segmentation
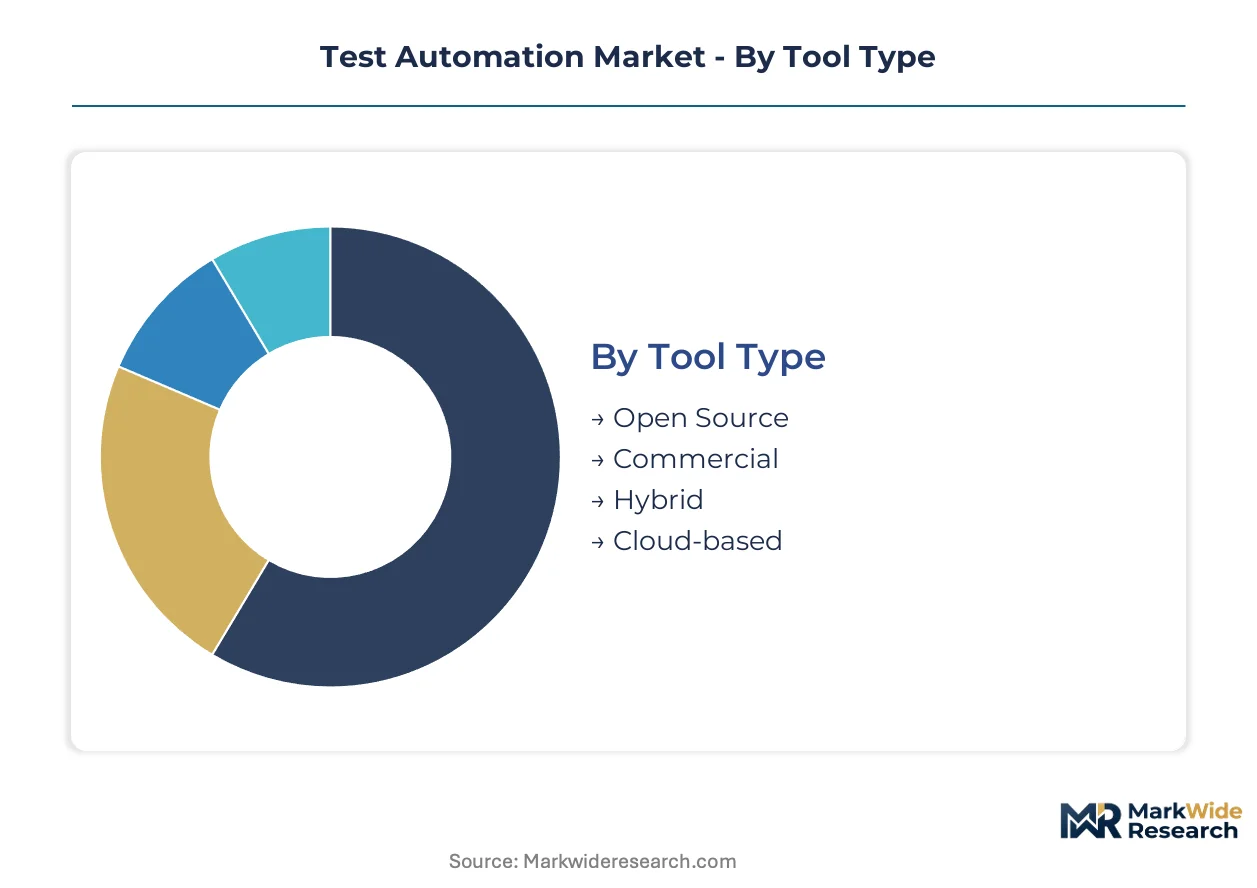
Test automation procurement patterns diverge sharply across tooling philosophies and infrastructure commitments. Deployment choices directly determine capital intensity and operational agility for validation workflows.
Tool Type:
Cloud-based frameworks turn over fastest as enterprises abandon perpetual licenses for elastic consumption, while open-source tooling exhibits the slowest replacement cycles due to embedded engineering investments.
- Cloud-based:Elastic compute allocation scales execution capacity with actual test volume rather than fixed infrastructure. Financial services firms in Germany and France prioritize these platforms to satisfy EU AI Act audit trail mandates without capital expenditure spikes.
- Commercial:Proprietary platforms bundle enterprise support, compliance documentation, and vendor accountability for regulated industries. Healthcare technology developers in the United States select these tools to streamline FDA validation documentation and reduce regulatory submission preparation time.
- Open Source:Community-maintained frameworks like Selenium and Appium dominate early-stage adoption with zero licensing friction.
- Hybrid:Blended architectures combine open-source execution engines with commercial orchestration layers.
Commercial platforms dominate installed base through multi-year enterprise lock-in. Cloud-based tooling is where expansion concentrates as consumption-based pricing gains procurement preference.
Deployment Model:
SaaS deployments command premium pricing through recurring revenue structures, while on-premise installations concentrate among defense and classified-environment contractors with data sovereignty requirements.
- SaaS:Browser-delivered test management eliminates infrastructure provisioning overhead and accelerates team onboarding. Mid-market software companies in the United Kingdom favor this model to align validation costs with release frequency fluctuations.
- Managed Services:Third-party providers assume full responsibility for environment provisioning, execution scheduling, and results analysis. North American enterprises with limited internal automation expertise contract these services to compress implementation timelines.
- On-Premise:Self-hosted infrastructure persists where data residency regulations or security classifications prohibit external processing.
- PaaS:Platform-native testing services from hyperscale cloud providers integrate directly with CI/CD pipelines and container orchestration.
SaaS subscriptions capture the steepest expansion trajectory as procurement shifts from capital to operational expenditure. On-premise retains entrenched position in government and defense segments.
Test Level:
Unit testing executes at millisecond speeds within developer workstations, while system and acceptance testing cycles stretch across days due to environment complexity and stakeholder coordination requirements.
- System Testing:End-to-end validation across integrated components verifies functional completeness before production release. Automotive software suppliers in Germany invest heavily here to satisfy ISO 26262 safety requirements for autonomous driving systems.
- Acceptance Testing:Formal validation against contractual requirements authorizes production deployment and triggers payment milestones. Financial services firms in India deploy automation here to accelerate compliance sign-off for offshore-delivered applications.
- Unit Testing:Isolated component validation runs within integrated development environments with minimal latency.
- Integration Testing:Interface verification between services and APIs catches contract-breaking changes early.
System testing dominates revenue concentration through environment complexity and compliance linkage. Acceptance testing is climbing fastest as outcome-based contracting ties vendor compensation to release authorization velocity.
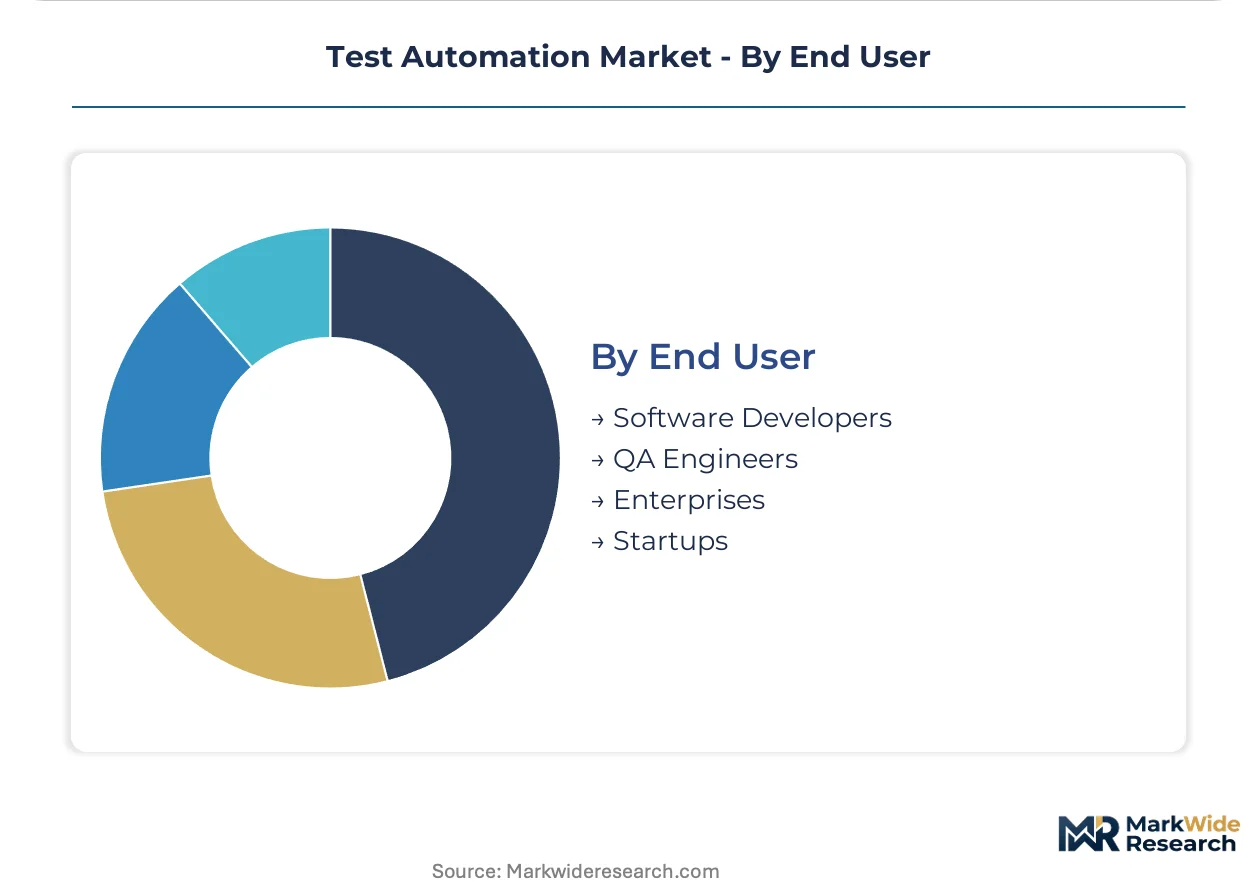
End User:
Enterprises rotate tooling slowest due to procurement bureaucracy and change management overhead, while startups exhibit rapid framework churn as engineering teams pivot between technology stacks.
- Enterprises:Fortune 500 organizations operate centralized automation centers of excellence spanning multiple business units. These buyers prioritize vendor stability, compliance certification, and professional services depth over feature velocity.
- QA Engineers:Specialized validation professionals select tools balancing script maintainability with cross-platform coverage. Their procurement influence is expanding as DevOps organizational models elevate quality assurance to shared responsibility.
- Software Developers:Engineering practitioners favor frameworks integrating seamlessly with version control and CI/CD pipelines.
- Startups:Resource-constrained early-stage companies prioritize zero-cost entry points and minimal configuration overhead.
Enterprises anchor revenue stability through multi-year commitments. QA Engineers are gaining share fastest as quality accountability shifts left into development workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA validation requirements anchor demand in the United States, while EU AI Act mandates reshape European procurement patterns. India's IT services corridor supplies cost-efficient automation talent to North American and European enterprises.
United States
Financial services firms and healthcare technology developers drive enterprise automation adoption. FDA validation standards enforce documented test coverage for medical device software, elevating demand for compliant platforms. Automation engineering talent concentrates in the San Francisco Bay Area and Seattle metropolitan clusters.
Germany
Automotive software suppliers and industrial equipment manufacturers prioritize hardware-in-the-loop validation. ISO 26262 safety requirements for autonomous driving systems mandate rigorous system testing protocols. Engineering competence clusters in Bavaria and Baden-Württemberg host specialized automation consultancies.
India
Offshore testing delivery for North American and European enterprises expands capacity in Bangalore and Hyderabad. IT services hubs leverage cost arbitrage to capture system testing and acceptance testing workflows. Domestic demand from banking and telecommunications sectors accelerates cloud-based tooling procurement.
United Kingdom
Mid-market software companies favor SaaS deployment models to align validation costs with release frequency. GDPR compliance requirements complicate test data provisioning for synthetic dataset generation. London's financial technology corridor drives demand for CI/CD-integrated automation frameworks.
France
Healthcare and banking sectors invest aggressively in bias detection automation to preempt EU AI Act enforcement. CNIL oversight tightens algorithmic accountability requirements for automated decision systems. Paris-based enterprise software vendors anchor regional distribution channels.
Test Automation Market Competitive Environment
Capability concentration sits with specialized testing pure-plays; scale advantage sits with diversified technology conglomerates and global IT services networks. The market structures around three tiers: enterprise platform vendors with hybrid cloud orchestration, boutique automation specialists with domain-specific tooling, and offshore delivery networks with labor-cost leverage. Competitive positioning hardens through strategic partnerships embedding testing platforms into CI/CD pipelines, and through outcome-based contracting that ties vendor compensation to defect detection rates.
Within the enterprise platform tier, IBM and Tricentis occupy positions as archetypes of hybrid cloud orchestration and model-based test automation respectively. Keysight Technologies exemplifies hardware-in-the-loop specialization for 5G and semiconductor validation where software intersects physical systems. These three companies represent distinct capability vectors: multi-environment orchestration, script maintenance reduction, and embedded systems convergence.
| Leading Market Players |
|---|
| IBM |
| Tricentis |
| Capgemini |
| OpenText |
| Accenture |
| Cigniti Technologies |
| Keysight Technologies |
| Parasoft |
| SmartBear |
| Others |
Value Chain & Pricing Dynamics
The Mumbai-Dubai freight corridor channels cloud infrastructure hardware into Indian IT services hubs, where logistics cost differentials between air and sea freight shape margin structures across SaaS and on-premise deployment tiers. This corridor's cost volatility feeds directly into vendor pricing power, concentrating premium pricing among orchestration platforms while compressing margins for script-heavy tool categories.
Pricing Analysis
Price spreads between North American and Indian delivery markets reach three-to-one multiples for equivalent automation engineering capacity. Three-tier pricing structure across premium orchestration platforms, standard commercial frameworks, and open-source execution engines dominates procurement patterns. Pricing pressure stems from hyperscaler cloud providers bundling native testing services at marginal cost, eroding standalone vendor margins. Mid-market software companies exhibit highest price sensitivity, while Fortune 500 enterprises prioritize compliance certification over cost optimization.
Supply Chain Analysis
Upstream compute infrastructure feeds from Taiwan semiconductor foundries, South Korean memory module suppliers, and US hyperscaler cloud data centers. Test automation software draws from these hardware layers while integrating open-source execution engines and proprietary orchestration algorithms. Single-source vulnerability concentrates in Taiwan's advanced node chip production, where geopolitical friction threatens elastic compute allocation for cloud-based testing workloads. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and Indian IT services channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test automation vendors command defensive moats through regulatory entrenchment, as FDA validation requirements and EU AI Act mandates create certification barriers that lock enterprise buyers into compliant platforms. Switching costs compound through embedded CI/CD pipeline integrations and multi-year audit trail dependencies.
For Market Incumbents: Pre-empt displacement by self-healing AI-native entrants through accelerated R&D in autonomous test maintenance algorithms. Defensive consolidation should prioritize acquiring boutique compliance documentation specialists in Germany and France to tighten EU AI Act positioning. Channel control through embedded hyperscaler marketplace listings represents the priority lever against margin compression. For New Entrants and Emerging Players: Establish a beachhead in hardware-in-the-loop validation for automotive semiconductor applications, where incumbent tooling gaps persist around 5G and autonomous driving test protocols. India's domestic banking sector offers the most penetrable geography for cloud-native SaaS testing platforms. Go-to-market execution should anchor through outcome-based contracting that ties fees to defect detection rates rather than seat licenses. For Investors and Strategic Acquirers: Specialized testing pure-plays with ISO 26262 safety certification and FDA validation documentation capabilities represent the priority acquisition archetype. Long-term viability hinges on regulatory scope expansion into AI-generated code validation domains. The signal to watch is enforcement action velocity under the EU AI Act, which will accelerate enterprise replacement cycles for non-compliant legacy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding test orchestration into GitLab and Jenkins CI/CD pipelines reduces customer acquisition friction for enterprise DevOps teams. |
| Strategic Partnership | Alliances with hyperscale cloud providers unlock marketplace distribution and co-selling motions with infrastructure procurement cycles. |
| Acquisition of Specialist Firm | Buying hardware-in-the-loop validation boutiques addresses capability gaps in automotive and telecommunications equipment testing. |
| Geographic Expansion | Establishing delivery centers in Bangalore and Hyderabad captures cost arbitrage for North American and European enterprise contracts. |
| Product Launch | Releasing bias detection modules satisfies EU AI Act algorithmic accountability mandates for financial services and healthcare buyers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, hyperscaler capex reports, and regulatory filing databases. Primary interviews engaged CTOs at Fortune 500 enterprises, QA engineering directors at mid-market software companies, platform integration specialists at Indian IT services firms, and procurement officers at automotive Tier 1 suppliers. Secondary validation drew from SEC 10-K filings, EU regulatory impact assessments, ISO certification registries, and cloud infrastructure spending disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from enterprise automation spending surveys.
Forecast inputs span deployment model adoption curves, vertical penetration rates by regulated industry, and regional talent cost differentials. The analytical framework projects growth across the analysis window by modeling SaaS subscription expansion, on-premise license renewal patterns, and managed services contract velocity. Segmentation dimensions include tool type, test level, organization size tier, and regional regulatory cluster. CAGR derivation incorporated CI/CD pipeline proliferation rates and compliance mandate enforcement timelines as industry-specific variables.
Sensitivities concentrate around EU AI Act enforcement velocity, Taiwan semiconductor supply disruptions, and hyperscaler pricing aggression in bundled testing services. Forecasts embed assumptions regarding sustained enterprise cloud migration and regulatory scope expansion into autonomous systems. Cross-checking against hyperscaler earnings call commentary on developer tooling attach rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Audience Response Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Global Headless CMS Software Market
Software & Services
Dealer Management System Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Camp Management Software Market
Software & Services
Global Forestry Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Global Customer Service Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Microsoft Office 365 Integration Services Market