
 Performing Arts Software Market | 2026-2036
Performing Arts Software Market Size, Share, and Industry Trends Forecast 2026-2036
Performing Arts Software Market Analysis
Regional theatre companies is pivoting toward integrated patron relationship management, replacing fragmented point solutions. Tessitura leverages deep specialization in arts-specific CRM workflows to anchor enterprise-tier deployments. Spektrix competes on cloud-native architecture that reduces IT overhead for mid-size venues. AudienceView sustains brand strength through vertical control over both ticketing and fundraising modules.
Performing Arts Software encompasses cloud-based and on-premise platforms that manage ticket inventory, patron databases, event calendars, and marketing automation for live entertainment venues, typically integrating with payment gateways and access control hardware. Ticketing Software occupies the largest revenue pool due to per-transaction fee structures, while Cloud-Based Solutions represent the fastest-expanding technology layer as venues retire legacy server installations. Management Platforms command higher retention rates because switching costs embed deeply across donor records, subscription histories, and venue scheduling dependencies.
The United States Federal Trade Commission and state-level biometric privacy statutes constrain how venues collect and retain patron facial recognition data at entry points. Europe's GDPR and the EU AI Act impose additional layers of consent management and algorithmic transparency on recommendation engines embedded in promotion tools. Stakeholders must monitor whether emerging accessibility mandates from the Department of Justice reshape interface design requirements before their next platform procurement cycle.
Market Dynamics
The migration from on-premise server installations to cloud-native architectures is compressing implementation timelines and redistributing IT budgets across venue networks. This infrastructure shift forces incumbent vendors to rearchitect legacy codebases while enabling new entrants to capture mid-market share through subscription pricing.
Growth Catalysts
- GDPR and state-level biometric privacy statutes:Compliance mandates in Europe and the United States are accelerating replacement cycles for outdated patron data systems as venues face audit exposure from legacy databases.
- Dynamic pricing algorithms:Revenue optimization tools embedded in cloud ticketing platforms are unifying yield management practices previously fragmented across spreadsheet workflows.
- United Kingdom theatre subsidy networks:Arts Council England capital grants for digital transformation are concentrating procurement authority among regional consortiums seeking unified vendor relationships.
Market Restraints
- Data migration costs:Decades of donor records and subscription histories locked in proprietary formats create switching friction that extends procurement cycles by 18-24 months.
- Payment processor concentration:Dependency on Stripe, Adyen, and PayPal for embedded checkout exposes venues to fee hikes and service term changes outside platform control.
- Hardware integration gaps:Turnstile access control and seat-level beacon systems from disparate manufacturers require custom API development, inflating deployment budgets.
Strategic Opportunities
- German state theatre digitization:Underpenetrated municipal venues in Bavaria and Baden-Württemberg lack integrated patron management, creating whitespace for modular platform entry.
- Accessibility mandate convergence:Department of Justice ADA enforcement and Web Content Accessibility Guidelines 2.1 are forcing interface redesigns that favor vendors with pre-certified accessible templates.
- Mobile wallet and NFT ticketing fusion:Convergence of Apple Wallet distribution with programmable ticket smart contracts enables secondary market royalty capture for producers.
Industry Challenges
- Specialized CRM talent scarcity:Venues struggle to hire administrators fluent in arts-specific patron segmentation, slowing platform optimization and reducing renewal rates.
- Legacy system integration complexity:SOAP-based fundraising databases from the 2000s resist REST API connectivity, requiring middleware investments that erode cloud migration ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Performing Arts Software Market |
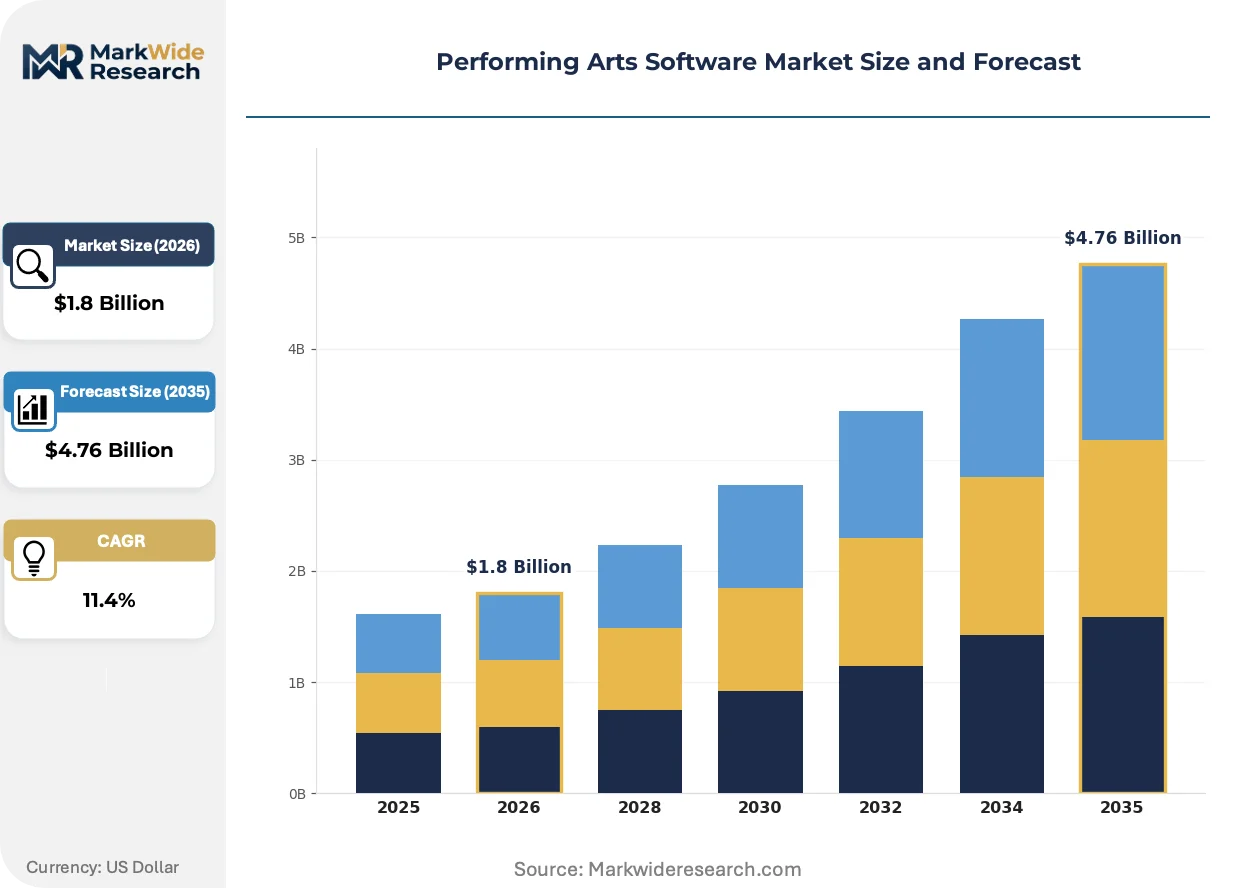
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ticketing Software, Management Platforms, Promotion Tools, Event Scheduling End User: Theatre Companies, Event Organizers, Music Festivals, Performing Arts Schools Technology: Cloud-Based Solutions, On-Premise Software, Mobile Applications, Integrated Systems Feature: Analytics Dashboard, User-Friendly Interface, Payment Integration, Marketing Automation |
| Companies Covered | Spektrix, Altru, Tessitura, ArtifaxEvent, Showare, AudienceView, Theatre Manager, iTheatre, PatronManager, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Performing Arts Software Market Emerging Trajectories
Artificial intelligence is penetrating recommendation engines and dynamic pricing modules, compressing the gap between broadway-scale optimization capabilities and regional venue resources. This algorithmic diffusion is redistributing competitive advantage toward data-science-capable vendors.
Unified patron data platforms are unifying previously siloed ticketing, fundraising, and marketing workflows into single tenant architectures. Regional theatre consortiums in the United Kingdom and Germany are adopting these systems fastest, consolidating vendor relationships from an average of four point solutions to one integrated stack. The structural consequence is collapsing IT headcount requirements and shifting budget allocation toward subscription fees and away from internal technical staff.
Europe's GDPR and the EU AI Act are imposing algorithmic transparency requirements on automated pricing and patron segmentation tools. Vendors must now document decision logic for dynamic price adjustments and obtain explicit consent for AI-driven marketing recommendations. United States venues exporting tours to European markets are most affected, forcing dual compliance architectures that increase development overhead.
Subscription fatigue among millennial and Gen-Z audiences is compressing traditional season-ticket commitment windows toward flexible membership models. Venues in the United States are responding with credit-based systems replacing fixed-seat subscriptions, while German state theatres experiment with pay-what-you-decide post-show models. This behavioral shift demands platform reconfiguration to handle variable pricing, partial refunds, and loyalty-point fungibility across productions.
Performing Arts Software Market Segmentation
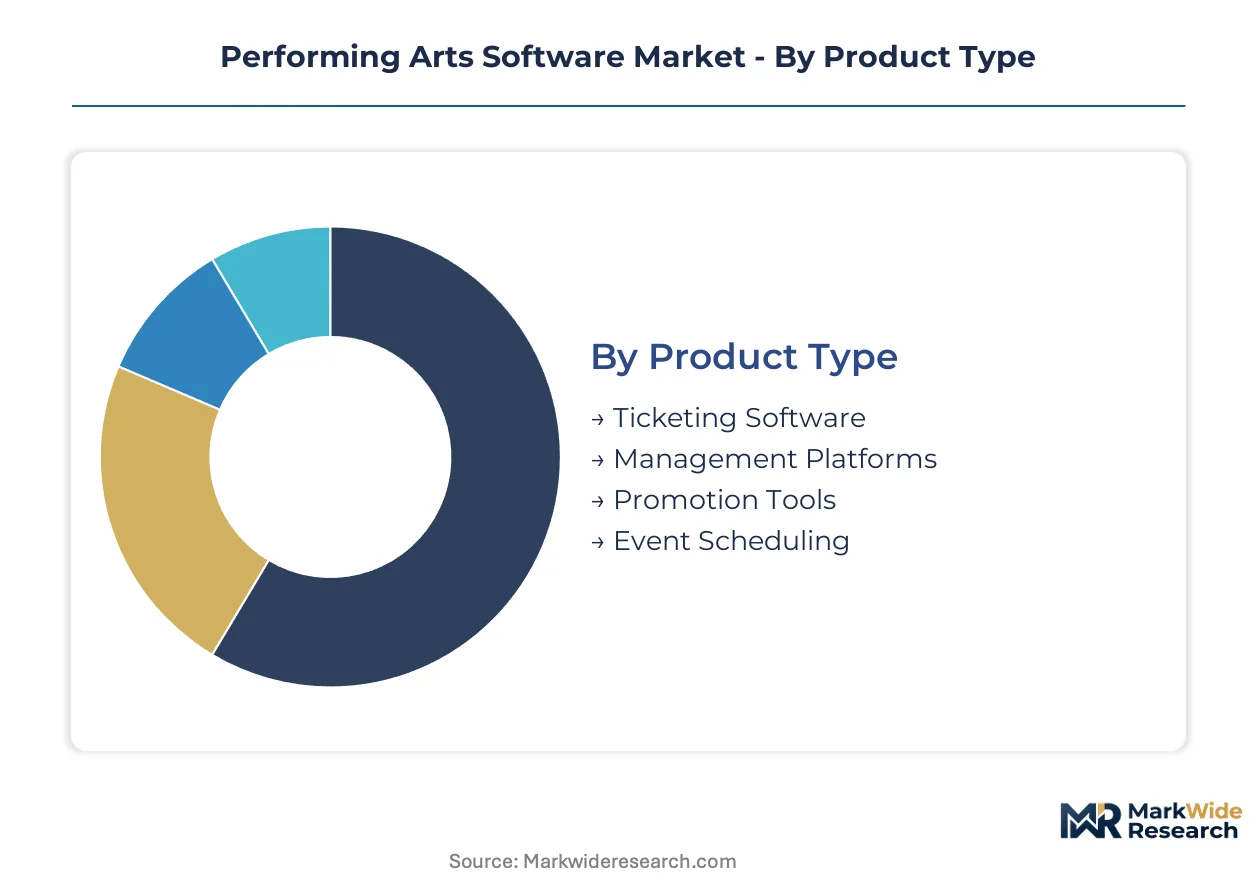
Segmentation in performing arts software reveals how procurement authority concentrates among high-volume transaction processors versus premium workflow integrators. Understanding these splits enables vendors to calibrate R&D investment between scalability and specialization.
Product Type:
Ticketing Software commands the largest revenue pool through per-transaction economics, while Management Platforms extract premium pricing from deep workflow integration.
- Ticketing Software:Transaction-processing engines handle inventory allocation, seat selection, and payment authorization in real time. Theatre companies in the United States and United Kingdom drive volume here, prioritizing uptime reliability over feature breadth during peak on-sale windows.
- Management Platforms:Unified architectures consolidate patron databases, fundraising pipelines, and venue scheduling into single tenant environments. German state theatres and subsidized United Kingdom regional networks represent concentrated demand, compelled by Arts Council England digitization mandates and GDPR audit requirements to retire fragmented point solutions.
- Promotion Tools:Marketing automation modules for email segmentation, social retargeting, and dynamic creative optimization.
- Event Scheduling:Calendar coordination systems managing rehearsal blocks, load-in logistics, and staff rostering.
Today's leader: Ticketing Software. Tomorrow's challenger: Management Platforms.
End User:
Theatre Companies anchor procurement budgets with year-round subscription cycles, while Music Festivals concentrate seasonal demand spikes that stress platform elasticity.
- Theatre Companies:Permanent institutions with multi-decade donor histories and complex subscription hierarchies. United Kingdom and German venues exhibit highest switching costs, embedding vendor relationships across development, marketing, and box office departments.
- Music Festivals:Temporary productions requiring rapid deployment, surge capacity, and post-event data portability. European multi-day events and United States destination festivals are expanding fastest, demanding mobile-first architectures and NFT-compatible ticket formats.
- Event Organizers:Independent producers managing touring productions, corporate entertainment, and one-off cultural programming.
- Performing Arts Schools:Educational institutions coordinating student showcases, facility rentals, and conservatory admissions events.
Revenue concentrates with Theatre Companies. Growth accelerates fastest among Music Festivals.
Technology:
Cloud-Based Solutions are displacing capital-intensive on-premise installations, while Integrated Systems command premium positioning through API consolidation.
- Cloud-Based Solutions:Multi-tenant architectures with automatic scaling, zero-downtime updates, and subscription pricing. United States mid-market venues and United Kingdom regional consortiums are migrating fastest, reallocating IT headcount budgets toward vendor fees.
- Integrated Systems:Pre-connected stacks unifying ticketing, CRM, fundraising, and access control through unified data models. German municipal theatres and large United States performing arts centers pay premiums here to avoid middleware development costs.
- On-Premise Software:Legacy server installations retained by institutions with strict data sovereignty requirements or sunk infrastructure investments.
- Mobile Applications:Native iOS and Android clients for patron self-service, digital ticket storage, and proximity-based engagement.
Deployment gravity shifts toward Cloud-Based Solutions. Integrated Systems defend margin at the top.
Feature:
Payment Integration functions as table stakes across all tiers, while Marketing Automation separates premium platform positioning from basic utility.
- Payment Integration:Embedded checkout flows connecting to Stripe, Adyen, and PayPal with PCI-DSS compliance. All end-user segments demand this, though processor concentration creates vulnerability to fee hikes outside platform control.
- Marketing Automation:Triggered email sequences, patron segmentation algorithms, and attribution modeling. Theatre Companies in subscription-heavy markets prioritize this for retention, while GDPR and EU AI Act compliance burdens favor vendors with pre-built consent management.
- Analytics Dashboard:Business intelligence layers visualizing revenue per seat, donor lifetime value, and campaign ROI.
- User-Friendly Interface:Accessibility-certified design systems meeting ADA and WCAG 2.1 standards for patron and staff interactions.
Payment Integration anchors every deal. Marketing Automation unlocks expansion revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance cost differentials between jurisdictions are redirecting vendor development resources and venue procurement decisions toward regulatory-friendly environments. The United States, United Kingdom, and Germany concentrate platform adoption, while data sovereignty requirements fragment cloud deployment architectures across borders.
United States
Theatre companies in New York, Chicago, and Los Angeles drive enterprise-tier deployments with complex subscription hierarchies and multi-decade donor databases. The Federal Trade Commission and state-level biometric privacy statutes in Illinois and California constrain facial recognition data collection at venue entry points. Regional theatre consortiums in the Southeast and Pacific Northwest are consolidating vendor relationships from fragmented point solutions toward unified cloud stacks.
United Kingdom
Arts Council England capital grants for digital transformation are concentrating procurement authority among regional theatre networks in the Midlands and North England. GDPR compliance mandates from the Information Commissioner's Office are accelerating replacement cycles for legacy patron data systems. London's West End venues and subsidized regional theatres in Scotland and Wales exhibit the highest switching costs, embedding vendor relationships across development and box office departments.
Germany
Municipal theatres in Bavaria and Baden-Württemberg lack integrated patron management, creating whitespace for modular platform entry. The Federal Commissioner for Data Protection and Freedom of Information enforces GDPR audit requirements that compel state theatres to retire fragmented point solutions. Berlin's dense network of subsidized institutions and Hamburg's commercial producing venues represent contrasting procurement profiles within a unified regulatory framework.
France
The CNIL enforces algorithmic transparency requirements on automated pricing tools used by Parisian theatres and Lyon-based regional venues. National Centre for Theatre subsidy programs are digitizing box office operations across subsidized institutions in Île-de-France and Provence-Alpes-Côte d'Azur. Festival producers in Avignon and Cannes demand mobile-first architectures with surge capacity for seasonal demand spikes.
Canada
Stratford Festival and Toronto's commercial theatre district anchor enterprise procurement with year-round subscription cycles. The Office of the Privacy Commissioner constrains cross-border data flows, forcing dual compliance architectures for venues touring to United States markets. Vancouver and Montreal venues are migrating fastest to cloud-native solutions, reallocating IT headcount budgets toward vendor subscription fees.
Performing Arts Software Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-tier venues favoring deep workflow integration while mid-market buyers prioritize subscription economics. The vendor base clusters around three strategic archetypes: arts-specialized CRM platforms, cloud-native ticketing engines, and vertically integrated stack providers. Competitive moves concentrate on API consolidation partnerships and accessibility certification pre-builds that compress procurement cycles.
Within the arts-specialized tier, Tessitura and Spektrix exemplify divergent architectural bets—one anchoring enterprise deployments through deep patron segmentation workflows, the other capturing mid-market share through multi-tenant cloud infrastructure. AudienceView occupies a position between these poles, sustaining brand recognition through unified control over ticketing and fundraising modules. PatronManager and Theatre Manager represent the long-tail of venue-specific solutions serving smaller institutions with lighter integration requirements.
| Leading Market Players |
|---|
| Spektrix |
| Altru |
| Tessitura |
| ArtifaxEvent |
| Showare |
| AudienceView |
| Theatre Manager |
| iTheatre |
| PatronManager |
| Others |
Supply Flow & Price Mechanics
Venue procurement consolidation around unified cloud stacks is compressing vendor margins and forcing platform providers to absorb migration costs that were previously passed through. This buyer-side concentration redistributes pricing power toward theatre networks with multi-venue contracts, while squeezing standalone point-solution vendors into defensive bundling strategies.
Pricing Analysis
Direct-to-venue subscription contracts dominate revenue capture, with SaaS-tiered pricing stratifying across enterprise, professional, and essential levels. Price differentiation rests on integration depth and GDPR compliance certification, with German state theatres paying premiums for audit-ready architectures. Cost compression in the mid-market tier is intensifying because Spektrix and cloud-native entrants are undercutting legacy per-seat licensing models. Small regional venues exhibit highest price sensitivity, while West End and Broadway institutions prioritize uptime guarantees over subscription fees.
Supply Chain Analysis
Domestic-content mandates in France and Germany are reshaping vendor sourcing for data residency and GDPR-aligned hosting. Cloud infrastructure concentrates in Ireland, Germany, and the United States for primary compute, while payment processing draws from Stripe, Adyen, and PayPal as concentrated gateways. Single-source vulnerability sits with payment processor fee schedules that platforms cannot hedge. Distribution runs through direct enterprise sales teams for large venues and partner-led channel deployment for mid-market theatre consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The performing arts software market functions as a stable compounder, with recurring subscription revenue from deeply embedded patron databases generating predictable renewal economics. Cloud migration tailwinds and regulatory replacement cycles sustain expansion independent of discretionary arts funding volatility.
For Market Incumbents: Acquire specialized accessibility compliance assets to preempt Department of Justice enforcement actions. Tessitura and AudienceView should consolidate API middleware providers that bridge legacy SOAP fundraising databases to modern REST architectures, neutralizing the integration friction that slows cloud migration ROI for their installed base.
For New Entrants and Emerging Players: Begin with modular patron management modules targeting underpenetrated municipal theatres in Bavaria and Baden-Württemberg. White-space opportunity concentrates in German state theatres lacking integrated CRM, with pay-per-use pricing and rapid deployment timelines as the decisive go-to-market angle against incumbent rearchitecture cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms serving mid-market venue consortiums with subscription economics and negative churn profiles. Long-term viability favors vendors with pre-built GDPR and ADA compliance architectures that compress procurement cycles. Watch Arts Council England grant disbursement velocity as the inflection indicator for United Kingdom regional theatre digitization momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies ticketing, fundraising, and marketing workflows into single-tenant architectures that reduce IT headcount requirements for theatre networks. |
| Accessibility Certification | Pre-certified WCAG 2.1 templates compress procurement timelines for venues facing Department of Justice enforcement actions. |
| Strategic Partnership | API consolidation with payment processors and access control hardware vendors eliminates custom development costs for German municipal theatres. |
| Acquisition of Specialist Firm | Middleware providers bridging legacy SOAP databases to REST architectures accelerate cloud migration ROI for incumbent vendors. |
| Geographic Expansion | Modular entry into Bavaria and Baden-Württemberg captures whitespace in underpenetrated German state theatre networks. |
Methodological Framework
Direct dialogue with venue technology directors, box office operations managers, fundraising CRM administrators, and Arts Council England procurement leads grounded qualitative findings in operational reality. Secondary validation drew from SEC filings of publicly traded venue operators, GDPR enforcement actions by the Information Commissioner's Office, Arts Council England capital grant disbursement records, and cloud vendor hyperscaler capex disclosures. Bottom-up venue census data and top-down software spend estimates were triangulated to anchor market sizing.
Bottom-up modeling aggregated individual venue software spend across deployment models, organization size tiers, integration complexity levels, and regional adoption patterns. Top-down validation cross-referenced aggregate performing arts institution IT budgets against vendor-reported subscription revenues. CAGRs were derived from segment-level growth rate distributions applied across the projection horizon, with cloud migration velocity and regulatory replacement cycle timing as primary forecast inputs.
Several conditions sit outside the modeled scope, including potential federal arts funding discontinuities, biometric privacy statute expansions beyond Illinois and California, and breakthrough AI pricing algorithms that displace current dynamic pricing modules. Forecasts reflect assumptions about sustained cloud migration momentum and GDPR enforcement continuity. A small set of named triggers warrants ongoing watch: Department of Justice ADA enforcement intensity, payment processor fee schedule revisions, and Arts Council England grant allocation shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
CAD Modeling Software Market
Software & Services
Global Audit Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Software Construction Components Market
Software & Services
Software Containers Market
Software & Services
Collaborative Whiteboard Software Market
Software & Services
Global Application Release Automation Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Classified Platform Market
Software & Services
Data Compression Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
Family Law Software Market
Software & Services
Collaboration Tools Market
Software & Services
Problem Management Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market