
 Global Data Virtualization Market | 2026-2036
Global Data Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Virtualization Market Analysis
Enterprise buyer concentration in the BFSI sector is decoupling from traditional IT services procurement patterns as healthcare and retail organizations independently adopt data virtualization platforms. IBM Corporation leverages its hybrid cloud infrastructure to anchor enterprise deployments across regulated industries. Oracle Corporation competes through database-native virtualization that sustains existing customer relationships. Microsoft Corporation extends its Azure ecosystem to capture cloud-native workloads.
Data virtualization constitutes a logical data integration approach that creates abstracted access layers across distributed sources without requiring physical data movement, typically employing query optimization engines, semantic modeling, and caching mechanisms to deliver real-time unified views. Its primary commercial purpose centers on enabling agile analytics, reducing data replication costs, and accelerating time-to-insight for business intelligence and operational applications. Cloud-based deployment now leads growth trajectories as enterprises prioritize elastic scalability and reduced infrastructure overhead, while data governance solutions command premium positioning due to escalating regulatory complexity. The IT services end-user segment remains mature with established vendor relationships, though healthcare is emerging as a high-margin expansion vertical driven by interoperability mandates.
FDA guidelines on clinical data integrity and HIPAA security requirements shape healthcare adoption patterns by mandating auditable, governed data access pathways. The EU AI Act and GDPR impose algorithmic transparency and data minimization standards that directly influence European product roadmaps. ISO 27001 and SOC 2 Type II certifications function as baseline market access credentials for vendor selection across regulated sectors. Stakeholders must evaluate whether their architecture investments align with emerging cross-border data localization requirements before committing to platform standardization.
Market Dynamics
Cloud-native query optimization engines are compressing deployment timelines from months to weeks, forcing incumbent vendors to rearchitect legacy caching layers around Kubernetes-orchestrated infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises require auditable data lineage for algorithmic decision systems, accelerating investment in governed virtualization layers that embed policy enforcement at query runtime.
- Real-time analytics workloads:Financial services trading desks and fraud detection systems demand sub-second latency across distributed sources, pulling elastic compute architectures into production environments.
- FHIR interoperability standards:US healthcare providers modernizing electronic health record exchanges need semantic abstraction layers that normalize heterogeneous clinical data formats without replication.
Market Restraints
- Specialized talent scarcity:Query optimization engineering and semantic modeling expertise concentrates in Silicon Valley and Bangalore, inflating implementation costs for enterprises outside these clusters.
- Hybrid cloud complexity:Data sovereignty requirements in Germany, France, and Saudi Arabia fragment platform architectures, forcing redundant deployment patterns that erode cost advantages of centralized virtualization.
- Physical data warehouse substitution:Snowflake and Databricks cloud-native warehouses offer competitive query performance with simpler operational models, capturing budget allocations that might otherwise flow to virtualization layers.
Strategic Opportunities
- Edge computing convergence:Manufacturing IoT deployments in Germany and Japan require localized query processing that federates plant-floor sensor streams with centralized ERP systems without full replication.
- India's data localization mandates:RBI and SEBI requirements for financial data residency create demand for domestic-hosted virtualization platforms that comply while enabling cross-border analytics.
- GraphQL-semantic layer integration:API-first application architectures combine with knowledge graph technologies to enable self-service data products that bypass traditional BI toolchains.
Industry Challenges
- ISO 27001 certification timelines:Vendor audits for healthcare and government procurement cycles extend 9-14 months, compressing revenue recognition windows for emerging platform providers.
- Mainframe integration friction:Fortune 500 enterprises with COBOL-based core banking or insurance systems face complex API mediation requirements that delay virtualization ROI realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Virtualization Market |
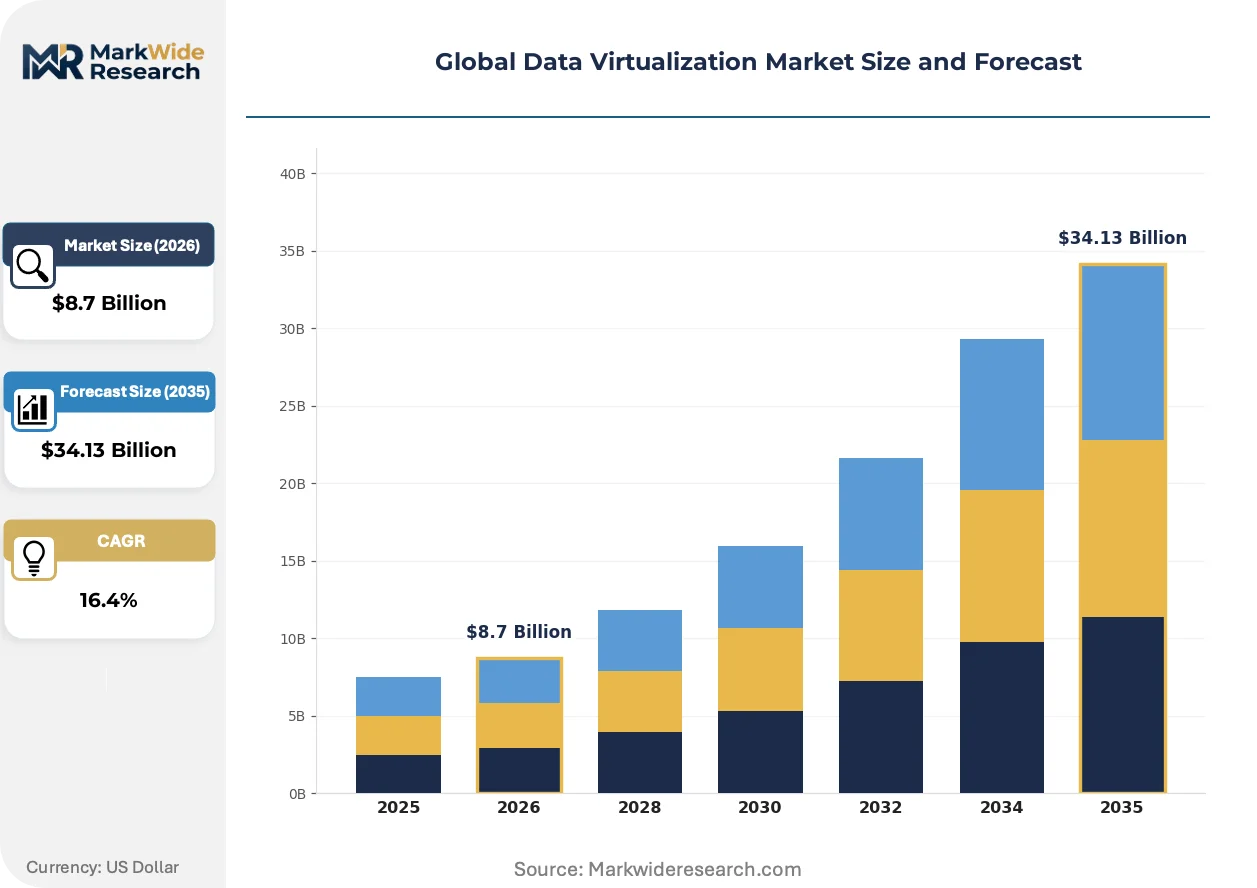
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution: Data Integration, Data Quality, Data Governance, Metadata Management End User: IT Services, BFSI, Healthcare, Retail Industry Vertical: Telecommunications, Education, Government, Manufacturing |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Microsoft Corporation, Informatica, Denodo Technologies, TIBCO Software, Red Hat, SAS Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Virtualization Market Emerging Trajectories
Query federation architectures are fragmenting into specialized engines optimized for specific workload patterns, displacing general-purpose platforms that once dominated enterprise procurement.
Vectorized query execution engines leveraging Apache Arrow in-memory formats are rewriting performance benchmarks for analytical workloads. Retail demand forecasting teams at multinational chains adopt these engines for real-time inventory optimization. The technology is compressing the gap between virtualization and physical ETL pipelines for read-heavy use cases.
GDPR Article 30 record-keeping requirements and the EU AI Act risk management framework are mandating embedded data governance. European pharmaceutical manufacturers must demonstrate algorithmic training data provenance for regulatory submissions. This is pulling policy-as-code capabilities from niche features to baseline platform requirements.
Consumption-based pricing models are displacing perpetual license structures across enterprise software procurement. Healthcare systems in the United States negotiate platform access through clinical outcome metrics rather than seat counts. This reconfigures vendor-customer relationships around shared risk rather than upfront capital commitment.
Global Data Virtualization Market Segmentation
Data virtualization procurement patterns diverge sharply across deployment modes and end-user sophistication, with regulated industries prioritizing governance capabilities while cloud-native enterprises optimize for query performance economics.
Deployment:
Capital expenditure tolerance and data sovereignty obligations drive platform selection across enterprise tiers.
- Cloud-Based:Kubernetes-orchestrated query engines deliver elastic compute scaling for variable analytical workloads. Financial services trading desks in New York and London deploy these architectures to compress latency for real-time fraud detection without permanent infrastructure commitment.
- Hybrid:Split processing models maintain sensitive data on-premises while federating queries to cloud analytics environments. German automotive manufacturers leverage this pattern to comply with KBA data residency mandates while accessing centralized ERP systems.
- On-Premises:Dedicated hardware deployments serve defense contractors and classified government facilities with air-gapped security requirements.
- Managed Services:Third-party operational support reduces specialized staffing burdens for mid-market healthcare systems navigating HIPAA technical safeguard complexity.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as sovereignty requirements proliferate.
Solution:
Functional module selection correlates directly with regulatory exposure and audit frequency in buyer organizations.
- Data Governance:Policy-as-code engines embed GDPR Article 30 record-keeping and EU AI Act risk management protocols at query runtime. European pharmaceutical manufacturers require these capabilities to demonstrate algorithmic training data provenance for EMA submissions.
- Data Integration:Federated query optimization layers abstract heterogeneous source systems without physical consolidation. US healthcare providers modernizing EHR exchanges deploy semantic normalization for FHIR interoperability mandates.
- Data Quality:Automated profiling and cleansing pipelines support clinical trial data integrity requirements under FDA guidelines.
- Metadata Management:Business glossary and lineage tracking tools enable self-service analytics governance in distributed Fortune 500 environments.
Revenue concentrates in Data Integration; steepest expansion trajectory belongs to Data Governance as compliance automation becomes non-negotiable.
End User:
Vertical-specific procurement patterns reflect divergent latency tolerances and regulatory oversight intensity.
- BFSI:Sub-second query federation supports algorithmic trading and real-time risk calculation across fragmented legacy core banking systems. RBI and SEBI data localization requirements in India drive domestic-hosted platform demand.
- Healthcare:Semantic abstraction layers normalize electronic health record exchanges without replication costs. US hospital systems negotiate platform access through clinical outcome metrics rather than traditional seat-based licensing.
- IT Services:Established vendor relationships and mature procurement processes characterize this segment, though margin pressure intensifies from cloud-native competitors.
- Retail:Real-time inventory optimization across distributed supply chains pulls vectorized query engines into production for demand forecasting teams.
IT Services holds installed base dominance; Healthcare claims the fastest share gain as interoperability mandates harden.
Industry Vertical:
Operational technology integration requirements differentiate adoption patterns across physical and digital service economies.
- Manufacturing:Edge computing convergence federates plant-floor sensor streams with centralized ERP systems. German and Japanese industrial IoT deployments require localized query processing without full data replication to cloud environments.
- Telecommunications:Network function virtualization infrastructure demands low-latency data access for customer experience analytics across distributed cell tower databases.
- Government:FedRAMP and ISO 27001 certification requirements extend procurement cycles, compressing revenue recognition windows for emerging platform providers.
- Education:Research data management and cross-institutional collaboration platforms drive modest but steady demand from university consortiums.
Manufacturing anchors vertical expansion; Government sustains longest sales cycles but highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in the United States, where cloud migration and real-time analytics investments pull the majority of platform spending. European demand accelerates under compliance pressure. Asia-Pacific adoption diversifies across financial centers and manufacturing hubs.
United States
Fortune 500 enterprises drive cloud-native virtualization deployments for trading desks and fraud detection systems. HIPAA technical safeguards shape healthcare procurement patterns. Hospital systems in the Northeast Corridor negotiate platform access through clinical outcome metrics rather than traditional licensing structures.
Germany
Automotive manufacturers and industrial IoT deployments demand hybrid architectures that federate plant-floor sensor streams with centralized ERP systems. KBA data residency mandates force split processing models that keep sensitive production data on-premises. Munich and Stuttgart industrial clusters anchor edge computing convergence investments.
India
Domestic-hosted platform demand surges as RBI and SEBI data localization requirements harden for financial services. Bangalore and Hyderabad technology corridors concentrate query optimization engineering talent. SEBI mandates for financial data residency create procurement urgency among brokerage and insurance enterprises.
United Kingdom
Financial services firms in the City of London deploy sub-second query federation for algorithmic trading across fragmented legacy core banking systems. GDPR Article 30 record-keeping requirements pull policy-as-code capabilities into baseline procurement specifications. London's fintech corridor drives cloud-native workload adoption.
Japan
Manufacturing IoT deployments in the Chubu and Kansai regions require localized query processing that federates sensor streams with centralized systems. METI industrial data policies influence platform architecture decisions. Toyota City and Osaka manufacturing clusters anchor edge computing virtualization investments.
Global Data Virtualization Market Vendor Landscape
United States-based technology conglomerates anchor one tier; European specialists and open-source infrastructure vendors hold differentiated positions. Market structure tilts toward consolidation as hybrid cloud complexity favors platforms with existing enterprise relationships. Three archetypes dominate: database-native incumbents extending virtualization from core data assets, cloud hyperscalers capturing elastic workloads, and independent specialists leading semantic modeling capabilities. Competitive moves center on Kubernetes-orchestrated infrastructure rearchitecture and embedded governance feature expansion.
Within the database-native tier, Oracle Corporation and IBM Corporation exemplify incumbents leveraging installed base relationships to sustain enterprise deployments. Microsoft Corporation occupies a position among cloud hyperscalers extending Azure ecosystem integration for cloud-native workloads. Denodo Technologies represents the independent specialist archetype, anchoring semantic modeling and data governance capabilities for regulated industries.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Informatica |
| Denodo Technologies |
| TIBCO Software |
| Red Hat |
| SAS Institute |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic transparency mandates gate both qualified supply and premium-tier pricing access, as vendors embedding policy-as-code governance engines command subscription premiums while uncertified platforms face procurement exclusion from European pharmaceutical and financial services buyers.
Pricing Analysis
Volume concentrates in consumption-based SaaS tiers while margin pools in enterprise governance bundles. Pricing stratifies across premium policy-as-code tiers, standard federated query licenses, and economy managed service offerings, with differentiation anchored in ISO 27001 certification status and semantic modeling depth. Cost compression in standard tiers is intensifying because cloud-native query engines commoditize baseline federation capabilities. Mid-market healthcare systems exhibit highest price sensitivity; Fortune 500 BFSI enterprises show lowest, prioritizing sub-second latency guarantees over per-seat economics.
Supply Chain Analysis
Single-source vulnerability sits with Bangalore and Hyderabad for query optimization engineering talent. Platform development draws from distributed source systems across the United States, Germany, and India, with critical dependencies on Apache Arrow in-memory formats, Kubernetes orchestration layers, and semantic knowledge graph libraries. Tariff exposure runs through cross-border data localization mandates fragmenting deployment architectures. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data virtualization is becoming a vertical-integration race as database-native incumbents pursue upstream control over semantic modeling capabilities and cloud hyperscalers deepen downstream integration into customer BI toolchains.
For Market Incumbents: Extend Kubernetes-native rearchitecture investments to compress deployment timelines against cloud-native challengers. Fortify ISO 27001 and SOC 2 Type II certification pipelines to defend government and healthcare procurement cycles from emerging platform providers. Prioritize semantic layer acquisitions that anchor policy-as-code capabilities for EU AI Act compliance. For New Entrants and Emerging Players: Channel partners specializing in FHIR interoperability implementation offer the fastest route to healthcare penetration. Target mid-market US hospital systems modernizing EHR exchanges under interoperability mandates. Lead with consumption-based pricing tied to clinical outcome metrics rather than traditional seat-based licensing. For Investors and Strategic Acquirers: SEBI and RBI data localization enforcement in India is the leading indicator that domestic-hosted platform demand will concentrate procurement urgency among brokerage and insurance enterprises. Position for 5-10 year consolidation around hybrid cloud complexity favoring vendors with existing enterprise relationships. Watch for edge computing convergence in German and Japanese manufacturing IoT as inflection signal for federated plant-floor query processing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Policy-as-Code Platform Launch | Embeds GDPR Article 30 and EU AI Act compliance at query runtime for pharmaceutical submissions. |
| Semantic Modeling Acquisition | Denodo Technologies' governance capabilities demonstrate premium positioning in regulated verticals. |
| Domestic India Hosting Partnership | RBI and SEBI data residency requirements create captive demand for localized infrastructure. |
| Edge Computing Integration | German KBA mandates and Japanese METI policies federate plant-floor sensor streams without cloud replication. |
| Consumption-Based Pricing Restructure | US hospital systems negotiate through clinical outcome metrics, reconfiguring vendor risk allocation. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and EU regulatory submission databases formed the secondary backbone, cross-referenced with primary interviews across CTOs at Fortune 500 enterprises, IT procurement officers in BFSI and healthcare, platform engineers at cloud-native competitors, and channel partners specializing in FHIR interoperability. Bottom-up deployment estimates triangulated against top-down addressable market calculations derived from cloud infrastructure spending patterns.
Historical trendline analysis of virtualization platform adoption across deployment modes, solution modules, end-user verticals, and regional regulatory clusters anchored the projection framework. Segmentation modeling incorporated cloud-based versus hybrid versus on-premises deployment economics, data governance versus integration versus quality solution depth, and BFSI versus healthcare versus manufacturing end-user intensity. CAGRs were derived from elasticity-adjusted spend trajectories across the analysis window, with specific inputs from query optimization engine performance benchmarks and certification timeline compression effects.
Caveats apply where EU AI Act enforcement intensity, RBI data localization timeline shifts, or Snowflake and Databricks warehouse substitution acceleration could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
United States ICT Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Morocco ICT Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Legaltech Market
Digital Solutions
Global Digital Art Software Market