
 Global Data Extraction Software Market | 2026-2036
Global Data Extraction Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Extraction Software Market Foresight
Enterprise-grade accuracy tiers with sub-second latency benchmarks are redrawing competitive expectations for data extraction platforms. Microsoft Corporation leverages its Azure cloud backbone to anchor hybrid deployment architectures across regulated industries. IBM Corporation specializes in AI-powered document understanding for legal discovery and compliance monitoring workflows. Oracle Corporation competes through deep database integration that sustains customer retention in financial analysis segments.
Data extraction software encompasses programmable systems that identify, capture, and structure information from unstructured sources using optical character recognition, natural language parsing, and machine learning classification algorithms with throughput metrics exceeding thousands of pages per hour. These tools serve commercial purposes including automated regulatory filing, contract analysis, and real-time risk signal detection. Cloud-based deployment is capturing the fastest expansion as organizations retire on-premise legacy infrastructure, while intelligent document processing commands the richest margin pools due to specialized AI training requirements. Web scraping maintains steady utility for market intelligence applications despite intensifying anti-bot countermeasures from target platforms.
The EU AI Act and GDPR impose algorithmic transparency and data lineage requirements that reshape product roadmaps for vendors serving European enterprises. The SEC in the United States enforces structured data mandates through XBRL filing rules that directly stimulate demand for parsing and validation tools. India's Digital Personal Data Protection Act introduces consent-layer complexity that platforms must architect around to maintain market access. Stakeholders should monitor evolving cross-border data transfer restrictions as these will determine which deployment architectures and geographic hosting strategies preserve operational viability.
Market Dynamics
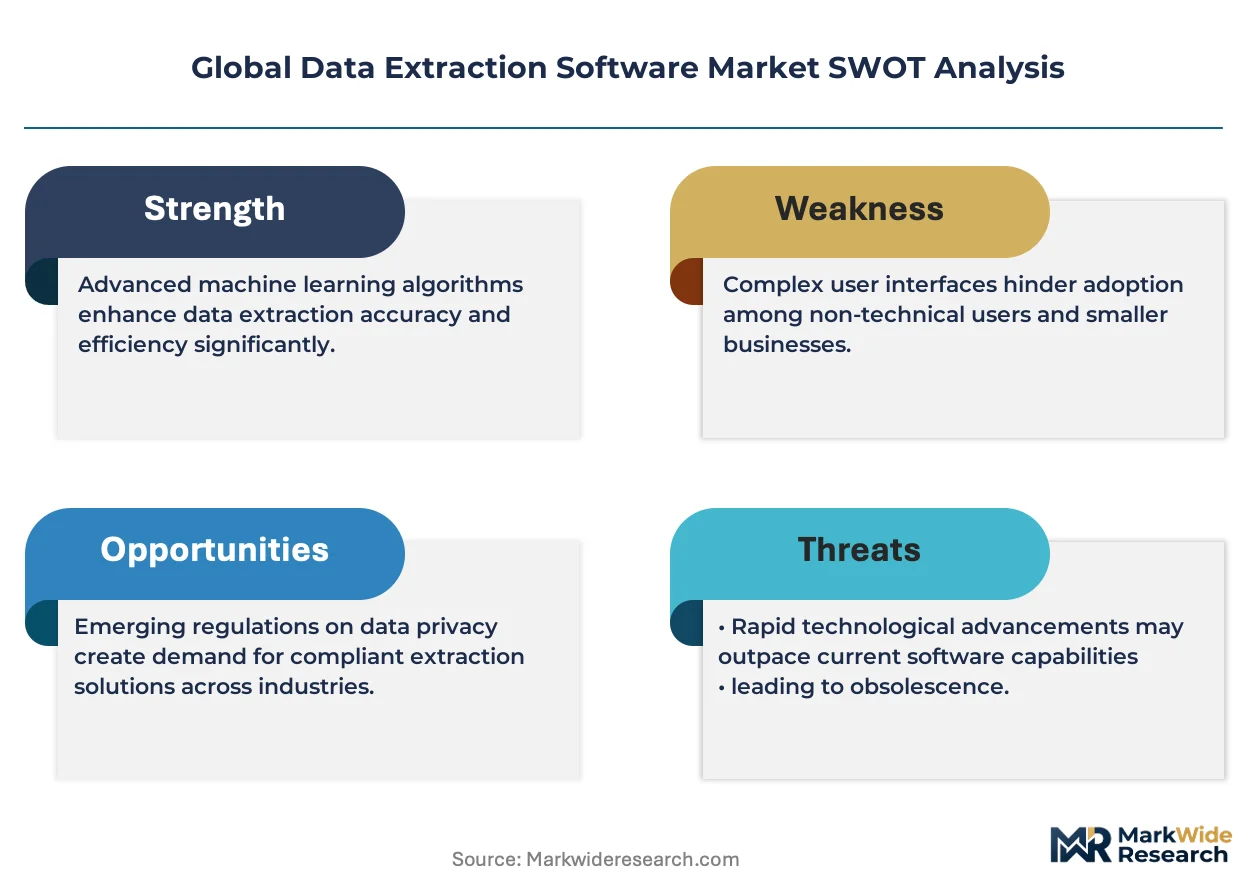
Cloud-native extraction architectures are compressing deployment timelines from quarters to weeks, forcing incumbent vendors to re-engineer delivery models or cede mid-market contracts to agile competitors.
Growth Catalysts
- EU AI Act compliance deadlines:European banking and insurance enterprises must deploy auditable document processing pipelines by fixed regulatory milestones, creating immediate procurement urgency for explainable extraction platforms.
- Optical character recognition at the edge:Manufacturing quality-control operations in Germany and Japan now embed OCR directly into inspection hardware, eliminating latency from cloud round-trips.
- India's Digital Personal Data Protection Act:Consent-layer requirements for cross-border data flows are stimulating demand for sovereign-hosted extraction infrastructure among multinational back-office operations.
Market Restraints
- GPU compute cost volatility:Training and inference for large language model-based document understanding faces input cost swings tied to NVIDIA supply allocation and cloud provider pricing tiers.
- Anti-bot countermeasure escalation:Target platforms including LinkedIn, Amazon, and X deploy sophisticated detection systems that degrade web scraping reliability and increase engineering overhead for data aggregation vendors.
- Algorithmic transparency mandates:GDPR Article 22 and EU AI Act explainability requirements impose documentation burdens that extend sales cycles and inflate professional services attachment rates.
Strategic Opportunities
- Small and medium enterprise penetration:India's mid-tier logistics and pharmaceutical distributors remain underserved by current extraction suites optimized for Fortune 500 document volumes.
- Convergence of computer vision and natural language processing:Unified models that parse both visual layouts and semantic content open new application areas in engineering drawing analysis and patent portfolio management.
- SEC structured data mandates:XBRL filing rules for financial disclosures create recurring revenue potential for validation and error-correction modules within extraction platforms.
Industry Challenges
- Annotation labor scarcity:Specialized document-type training requires domain-expert labelers in legal, medical, and engineering fields where qualified annotators command premium wages.
- Legacy system integration friction:Mainframe-era data warehouses in US financial institutions resist API-based connectivity, forcing costly middleware development or manual bridge implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Extraction Software Market |
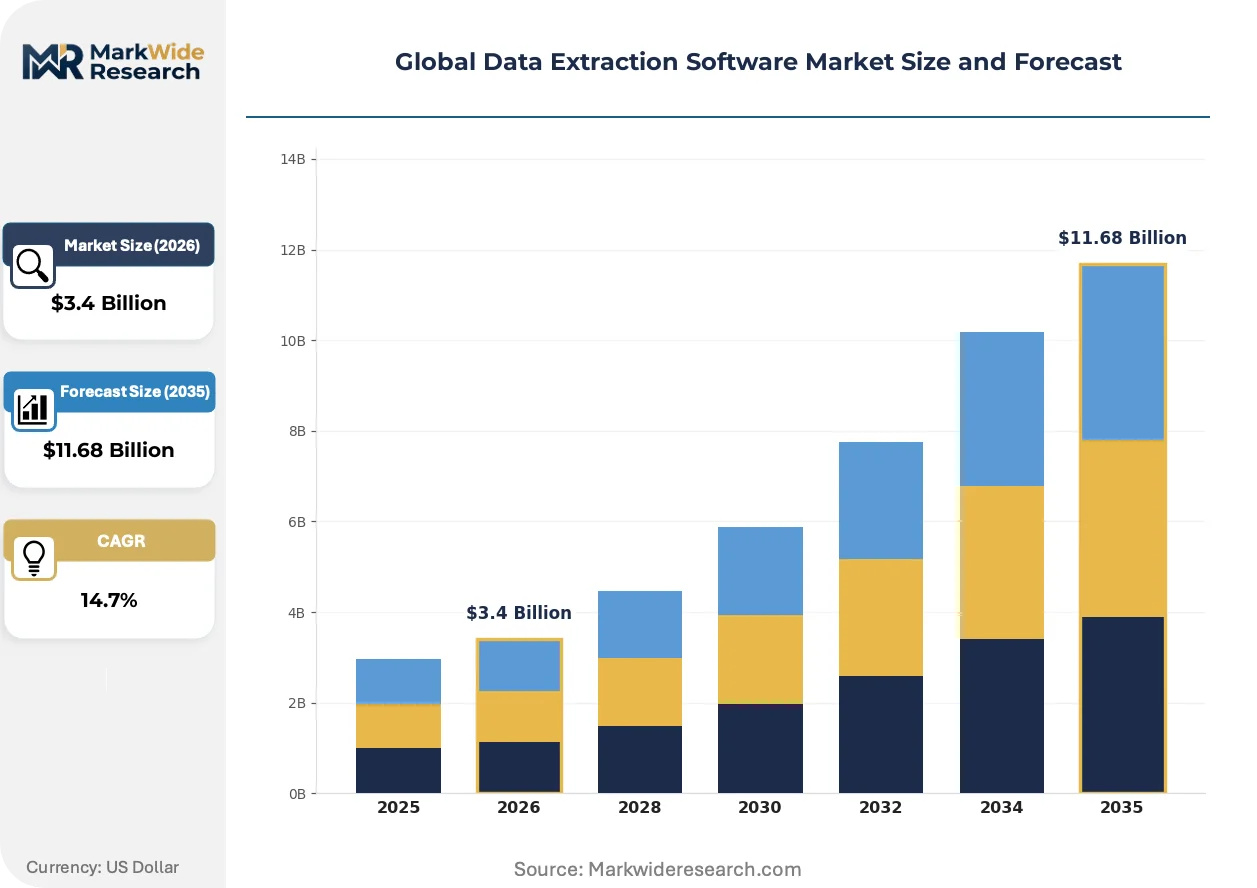
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $11.68 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
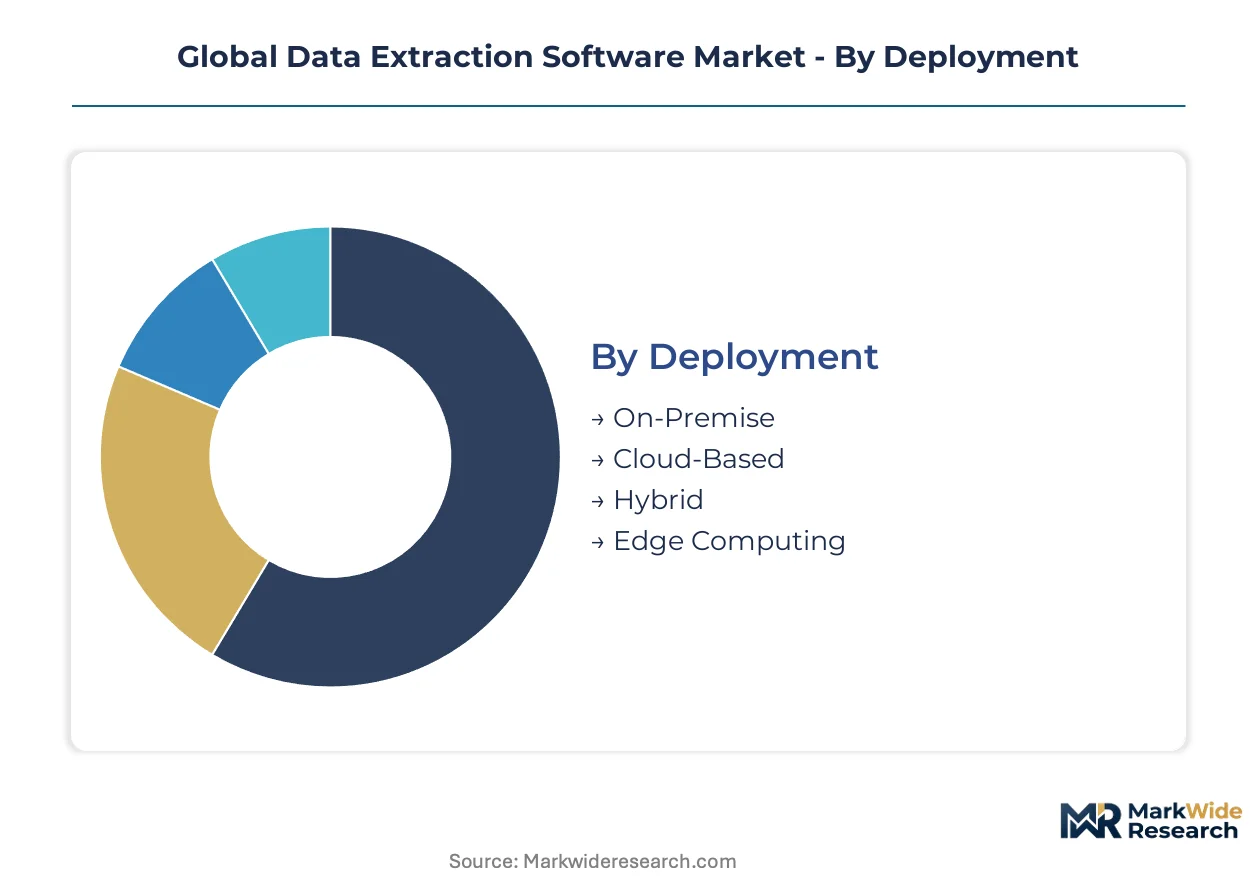
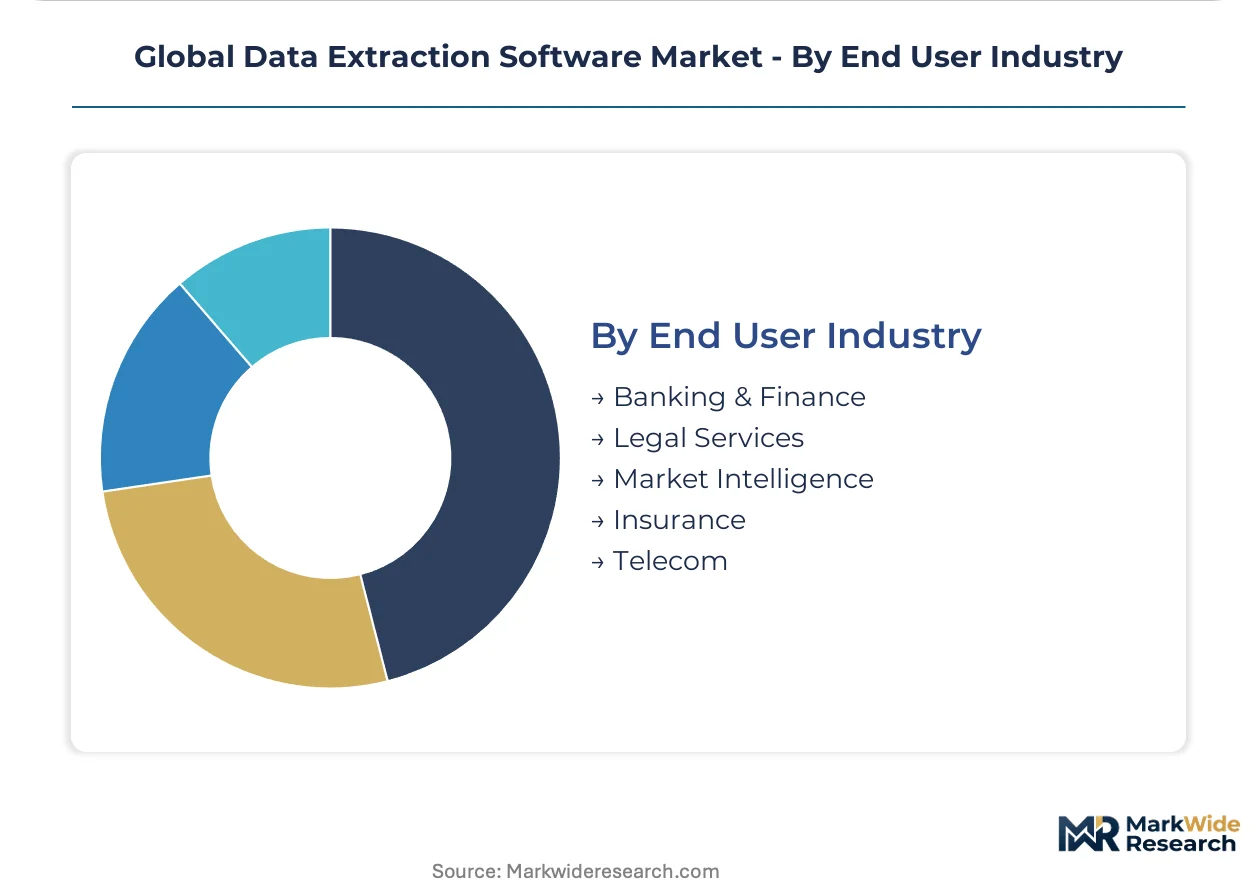
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: OCR Software, Web Scraping, Data Parsing, Intelligent Document Processing, Screen Scraping Application: Financial Analysis, Legal Discovery, Market Research, Risk Management, Compliance Monitoring End User Industry: Banking & Finance, Legal Services, Market Intelligence, Insurance, Telecom |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Informatica LLC, SAS Institute Inc., Alteryx, Inc., Talend S.A., UiPath Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Extraction Software Market Shifts & Advancements
Foundation model architectures are collapsing the traditional pipeline of discrete OCR, layout analysis, and entity extraction into single-pass inference, compressing both latency and total cost of ownership for document-heavy workflows.
Multimodal transformer models is displacing rule-based template extraction in insurance claims processing. US property and casualty carriers now deploy these systems for damage assessment photos paired with adjuster notes. The displacement is compressing vendor margins in the traditional optical character recognition segment while concentrating value capture in model training and fine-tuning services.
REACH and RoHS substance documentation requirements are forcing electronics manufacturers to automate supplier certificate extraction. EU-based industrial distributors must verify component compliance across multi-tier supply chains. German automotive tier-1 suppliers are prioritizing extraction platforms with pre-trained European regulatory document schemas to accelerate audit readiness.
Subscription-based consumption is replacing perpetual licensing in enterprise procurement of extraction capabilities. Channel partners and systems integrators in the United States now bundle extraction APIs into broader automation service offerings rather than reselling standalone software. This unbundling is most visible in legal technology, where e-discovery vendors absorb extraction functionality into matter-based pricing rather than licensing separate tools.
Global Data Extraction Software Market Segmentation
Segmentation reveals how regulatory mandates and infrastructure constraints fragment procurement patterns across enterprise tiers. Vendors must architect separate go-to-market motions for cloud-native entrants versus legacy-bound incumbents.
Deployment:
GDPR Article 44 cross-border transfer rules and India's data localization directives create divergent hosting requirements that reshape deployment preferences by geography.
- Cloud-Based:Multi-tenant architectures with regional data residency options now dominate new procurement cycles. Financial services firms in Germany and India prioritize sovereign cloud instances to satisfy RBI and BaFin supervisory expectations.
- Hybrid:Split pipelines process sensitive PII on-premise while routing anonymized analytics to public cloud. US healthcare systems deploy this architecture to preserve HIPAA audit trails for OCR while leveraging cloud NLP scale.
- On-Premise:Air-gapped installations persist in defense and classified government environments where export control regulations prohibit external data flows.
- Edge Computing:Embedded extraction modules in manufacturing inspection hardware eliminate latency for German and Japanese quality-control operations.
Cloud-Based handles the majority of throughput; Edge Computing is gaining share fastest among industrial IoT deployments.
Solution Type:
Margin pools concentrate where AI training requirements create defensible moats against commodity OCR alternatives.
- Intelligent Document Processing:Foundation-model architectures collapse OCR, layout analysis, and entity extraction into single-pass inference. US property and casualty carriers deploy multimodal transformers for damage assessment photos paired with adjuster notes.
- OCR Software:Rule-based template extraction faces margin compression as unified models displace discrete pipeline components. Legacy installations persist in back-office operations with low document variability.
- Web Scraping:Anti-bot countermeasures from LinkedIn, Amazon, and X degrade reliability and inflate engineering overhead for data aggregation vendors.
- Data Parsing:Structured format converters support SEC XBRL filing mandates and ISO 20022 payment message standards.
- Screen Scraping:Legacy system bridge technology maintains relevance for mainframe-era data warehouses resisting API connectivity.
Intelligent Document Processing commands the richest margin structure; Web Scraping faces the steepest headwinds from platform defense mechanisms.
Application:
Regulatory filing mandates directly stimulate demand for specific validation and parsing capabilities.
- Compliance Monitoring:Auditable document processing pipelines satisfy EU AI Act explainability requirements and SEC structured data mandates. European banking procurement cycles accelerate around fixed regulatory milestones.
- Financial Analysis:XBRL validation modules integrate with extraction platforms to automate error detection in regulatory submissions. Oracle's database-centric retention strategies concentrate in this segment.
- Legal Discovery:E-discovery vendors absorb extraction functionality into matter-based pricing rather than licensing separate tools, compressing standalone software margins.
- Risk Management:Real-time signal detection from unstructured sources supports credit and operational risk frameworks.
- Market Research:Steady utility persists despite anti-bot friction as competitive intelligence remains mission-critical for CPG and pharmaceutical strategy functions.
Compliance Monitoring carries the highest regulatory urgency; Legal Discovery is experiencing the fastest unbundling into broader automation services.
End User Industry:
Industry-specific document schemas and audit protocols create vertical integration incentives for specialized vendors.
- Banking & Finance:Intelligent document processing automates KYC, AML, and loan origination workflows. EU AI Act deadlines force immediate procurement of explainable extraction platforms.
- Insurance:Claims processing automation drives multimodal transformer adoption for damage assessment. German automotive tier-1 suppliers prioritize pre-trained European regulatory document schemas.
- Legal Services:E-discovery and contract analysis demand specialized training data from domain-expert annotators where qualified labelers command premium wages.
- Market Intelligence:Web scraping dependencies expose operations to platform countermeasure volatility.
- Telecom:Customer onboarding and billing dispute resolution generate structured data extraction requirements at scale.
Banking & Finance anchors current revenue concentration; Insurance is expanding most quickly on AI-driven claims automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Germany demonstrate the sharpest price elasticity, squeezing vendor margins on standardized extraction tools, while US financial institutions absorb premium pricing for compliance-grade accuracy tiers without procurement friction.
United States
SEC structured data mandates through XBRL filing rules generate recurring procurement cycles for validation modules. HIPAA audit trail requirements preserve hybrid deployment architectures across healthcare systems. New York and Chicago financial centers anchor demand for real-time risk signal detection from unstructured regulatory filings.
Germany
BaFin supervisory expectations drive sovereign cloud instance preferences for banking extraction pipelines. REACH and RoHS substance documentation requirements force electronics manufacturers to automate supplier certificate verification. Stuttgart automotive tier-1 suppliers prioritize platforms with pre-trained European regulatory document schemas.
India
RBI data localization directives stimulate demand for sovereign-hosted extraction infrastructure among multinational back-office operations. SEBI disclosure mandates accelerate platform upgrades for broker-dealer compliance workflows. Bengaluru and Hyderabad technology corridors concentrate mid-tier logistics and pharmaceutical distributor modernization projects.
Japan
METI industrial digitization programs embed OCR directly into manufacturing quality-control hardware. JIS standards compliance creates documentation burdens for export-oriented machinery producers. Nagoya and Osaka industrial clusters eliminate latency through edge-computing extraction modules in inspection equipment.
United Kingdom
FCA regulatory reporting requirements sustain demand for auditable document processing pipelines in insurance and asset management. CSRD alignment pressures drive procurement of explainable extraction platforms for sustainability disclosure automation. London's legal technology corridor experiences fastest unbundling of extraction functionality into broader automation services.
Global Data Extraction Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where specialized AI training capabilities command margin premiums while standardized OCR vendors face commoditization pressure. The vendor base separates into three strategic archetypes: cloud-native platform providers with hybrid deployment expertise, database-centric incumbents leveraging deep enterprise integration, and automation specialists converging extraction into broader workflow orchestration. Dominant competitive moves include strategic partnerships between extraction specialists and systems integrators, plus geographic expansion through sovereign cloud instances to satisfy data residency mandates.
Within the cloud-native platform tier, Microsoft Corporation and IBM Corporation exemplify divergent positioning strategies. Microsoft anchors hybrid deployment architectures through its Azure cloud backbone, while IBM occupies a position emphasizing AI-powered document understanding for regulated industries. Oracle Corporation represents the database-centric archetype, sustaining customer relationships through deep integration with existing financial analysis infrastructure. These three players collectively illustrate how competitive differentiation in extraction software increasingly depends on ecosystem lock-in rather than discrete feature superiority.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Informatica LLC |
| SAS Institute Inc. |
| Alteryx, Inc. |
| Talend S.A. |
| UiPath Inc. |
| Others |
Supply & Pricing Matrix
GPU cluster utilization rates above eighty percent in United States hyperscale regions anchor cost structures for foundation-model training, concentrating supply leverage among NVIDIA-allied cloud providers while compressing margin floors for independent software vendors lacking captive silicon access. This scale asymmetry forces mid-tier extraction platforms into partnership-dependent delivery models that surrender pricing autonomy to infrastructure gatekeepers.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for European banking procurement, mandating explainability documentation that separates premium compliance-grade platforms from standard OCR alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency benchmarks and audit trail depth, with German BaFin-supervised institutions absorbing premium tiers without procurement friction. Price differentiation hinges on sovereign cloud certification and sub-second inference guarantees. Cost compression in the standard tier is intensifying because Indian mid-market logistics distributors negotiate aggressively against per-page transactional models.
Supply Chain Analysis
NVIDIA H100 allocation queues through Singapore distribution hubs create chokepoint exposure for European and Indian vendors dependent on cloud-provider GPU leasing. Supply concentration rests on Taiwan semiconductor fabrication, United States chip design, and Malaysia backend assembly for edge-computing OCR modules. Raw material dependencies span high-bandwidth memory from South Korea, advanced packaging substrates from Japan, and rare earth elements from China for magnetics in manufacturing inspection hardware. Single-source vulnerability runs through TSMC advanced node capacity. Distribution runs through hyperscaler marketplaces and systems integrator channel partners rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation-model commoditization sits at an early-cycle inflection, with enterprise penetration below fifteen percent in Indian mid-tier distributors and German automotive tier-2 suppliers creating runway for specialized vertical solutions.
For Market Incumbents: Compound ecosystem lock-in through deep Oracle-database integration and Azure-sovereign cloud certification investments that raise switching costs for financial services clients. Defend against open-source multimodal transformers by embedding extraction modules into broader workflow orchestration suites. Prioritize vertical integration into domain-expert annotation labor pools for legal and medical document training. For New Entrants and Emerging Players: ISO 27001 and SOC 2 Type II fast-track certification opens procurement doors at US healthcare systems and German automotive suppliers where compliance documentation gates vendor selection. White-space concentration in Indian pharmaceutical distributor modernization and Japanese manufacturing quality-control edge deployments offers penetrable entry points. Lead with API-first consumption models bundled through systems integrator channel partners rather than direct enterprise sales cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among intelligent document processing specialists with pre-trained European regulatory schemas and existing BaFin or RBI supervisory relationships. Long-term viability over the coming decade favors acquisition targets combining sovereign cloud deployment expertise with multimodal transformer fine-tuning capabilities for insurance claims automation. Monitor SEBI and SEC structured data mandate enforcement intensity as the primary inflection signal for validation-module revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Systems integrator alliances in the United States absorb extraction into bundled automation services. |
| Geographic Expansion | Sovereign cloud instances in Germany and India satisfy RBI and BaFin data residency mandates. |
| Platform Integration | Deep Oracle database embedding sustains retention in financial analysis customer segments. |
| Acquisition of Specialist Firm | Domain-expert annotation labor pools in legal and medical fields command defensible margin premiums. |
| Product Launch | Edge-computing OCR modules for Japanese manufacturing inspection eliminate cloud latency penalties. |
Research Methodology
A spread of perspectives from platform engineering leads at hyperscalers, IT procurement officers at German automotive tier-1 suppliers, compliance directors at US property and casualty carriers, and integration specialists at systems integrators converged on the working assumptions for deployment model preferences and latency benchmarks. Primary interview insights were cross-validated against secondary sources including SEC XBRL filing disclosures, RBI circulars on data localization, EU AI Act regulatory texts, and hyperscaler capex allocation reports. Bottom-up segment sizing triangulated against top-down market aggregation across the analysis window.
Segmentation dimensions modeled encompass deployment architecture, solution type, application workflow, and end-user industry vertical, with regional adoption patterns further disaggregated by sovereign cloud availability and regulatory enforcement intensity. CAGRs were derived from installed base growth rates and replacement cycle compression in legacy OCR estates, with foundation-model inference cost curves and GPU supply allocation schedules serving as key industry-specific forecast inputs throughout the projection horizon.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement timelines and NVIDIA supply allocation stability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as cross-border data transfer restriction frameworks and anti-bot countermeasure escalation trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
HCS Software and Services Market
Software & Services
Global Data Quality Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Global Cinema Software Market
Software & Services
Automated Testing Software Market
Software & Services
Jobsite Management Software Market
Software & Services
Payroll and HR Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Cursor Reviewer Market
Software & Services
Global Absence Management Software Market
Software & Services
App Building Software Market
Software & Services
CGI Software Market
Software & Services
Machine Translation Software Market
Software & Services
Towing Software Market
Software & Services
Debt Collection Software Market