
 Jobsite Management Software Market | 2026-2036
Jobsite Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Jobsite Management Software Market Outlook
Multi-source vendor strategies is pivoting how construction enterprises procure jobsite management platforms. Procore leverages its cloud-native architecture to anchor North American mid-market and enterprise accounts. Autodesk Construction Cloud competes through deep BIM integration and design-to-field workflow continuity. Fieldwire specializes in task-level field coordination for specialty trade contractors navigating fragmented project environments.
Jobsite management software encompasses digital platforms that orchestrate construction project workflows through real-time data capture, resource synchronization, and stakeholder communication across distributed field and office teams. These systems typically integrate GPS-tagged progress tracking, automated safety incident logging, and material inventory dashboards to compress project timelines and reduce rework costs. Cloud-Based deployment leads segment value generation due to minimal infrastructure overhead and rapid multi-site rollout capability, while AI-Driven technology represents the fastest-expanding capability layer as predictive risk modeling and automated schedule optimization penetrate tier-one contractor operations. Project Management functions retain the largest margin pool within product type segmentation because modules span bidding, scheduling, and closeout across full project lifecycles.
FAA coordination protocols influence software requirements for aviation-adjacent construction, while OSHA mandates drive digitization of safety documentation and incident traceability. The EPA's stormwater and emissions tracking rules push environmental compliance modules into standard platform configurations. Stakeholders must evaluate how evolving interoperability standards between field data systems and enterprise ERP architectures will reshape procurement criteria and vendor lock-in risks.
Market Dynamics
Cloud-native coordination platforms are compressing project timelines by eliminating data latency between field crews and back-office planning systems. General contractors now mandate real-time visibility as a baseline procurement criterion.
Growth Catalysts
- Federal infrastructure spending:United States appropriations for commercial and residential build segments are accelerating software procurement cycles. Large-scale projects require multi-stakeholder coordination tools.
- OSHA digitization mandates:Workplace safety documentation requirements are forcing paper-based contractors onto incident-logging platforms. Compliance automation reduces audit preparation time.
- AI-driven scheduling protocols:Predictive risk modeling is penetrating tier-one contractor operations. Automated optimization compresses buffer allocation and resource idle time.
Market Restraints
- Legacy ERP integration costs:Enterprise resource planning architectures in established construction firms resist field-data interoperability. Custom API development consumes implementation budgets.
- Connectivity infrastructure gaps:Rural jobsites in Australia and Canada lack reliable broadband for cloud synchronization. Offline-first mobile architectures add development complexity.
- Specialty trade fragmentation:Subcontractor ecosystems in residential construction operate on thin margins that resist per-seat licensing models. Platform penetration stalls below commercial build tiers.
Strategic Opportunities
- Aviation-adjacent construction:FAA coordination protocols for airfield projects create specialized compliance modules. Software vendors can capture premium pricing for certified workflows.
- Environmental compliance automation:EPA stormwater and emissions tracking rules push monitoring dashboards into standard configurations. Carbon accounting integration opens new module revenue.
- Convergence of BIM and field data:Design-to-field workflow continuity eliminates rework from specification drift. Autodesk Construction Cloud and emerging competitors are anchoring this integration layer.
Industry Challenges
- Interoperability standard delays:Field data exchange formats lack industry-wide consensus. Vendor lock-in risks complicate multi-platform procurement strategies for enterprise accounts.
- Construction technologist talent scarcity:Firms struggle to hire personnel who bridge heavy civil expertise with software administration. Training cycles extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jobsite Management Software Market |
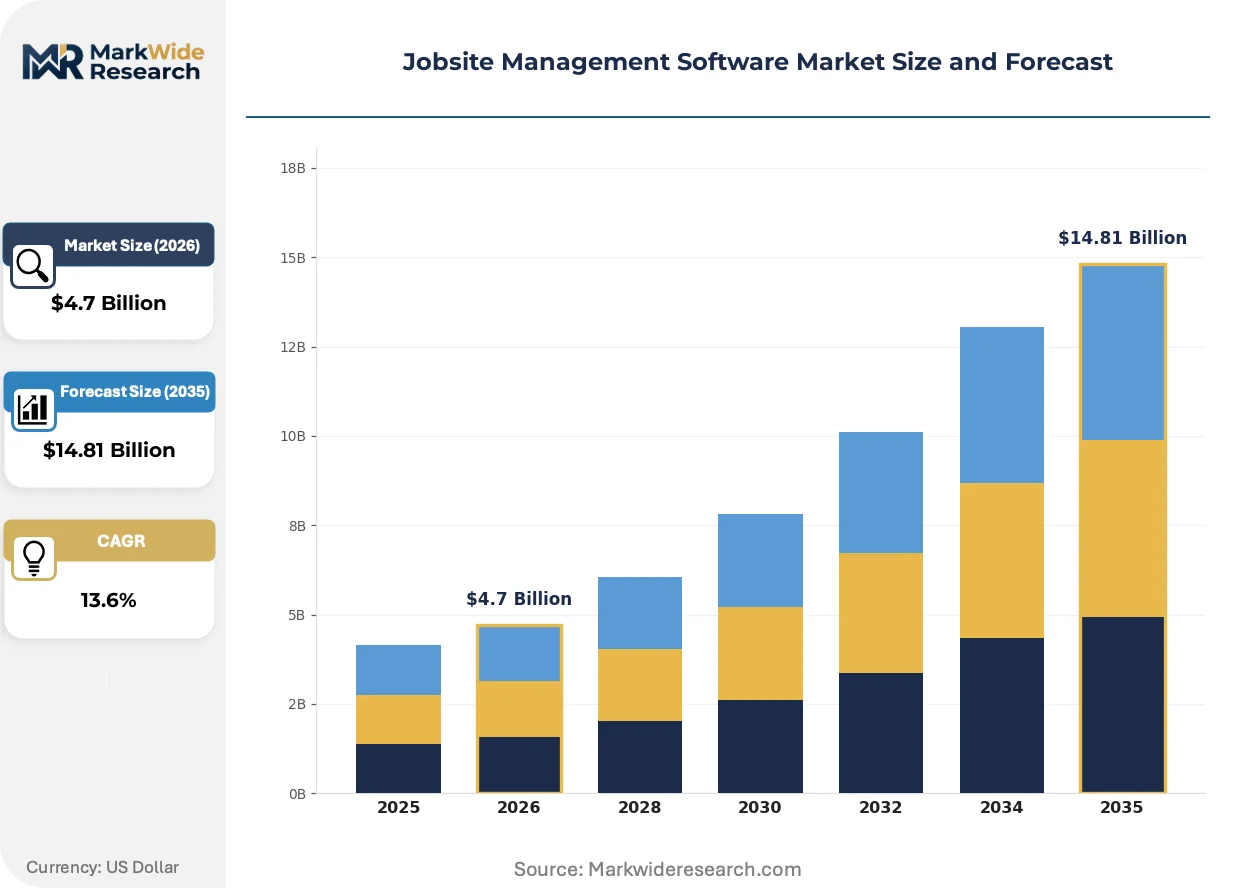
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
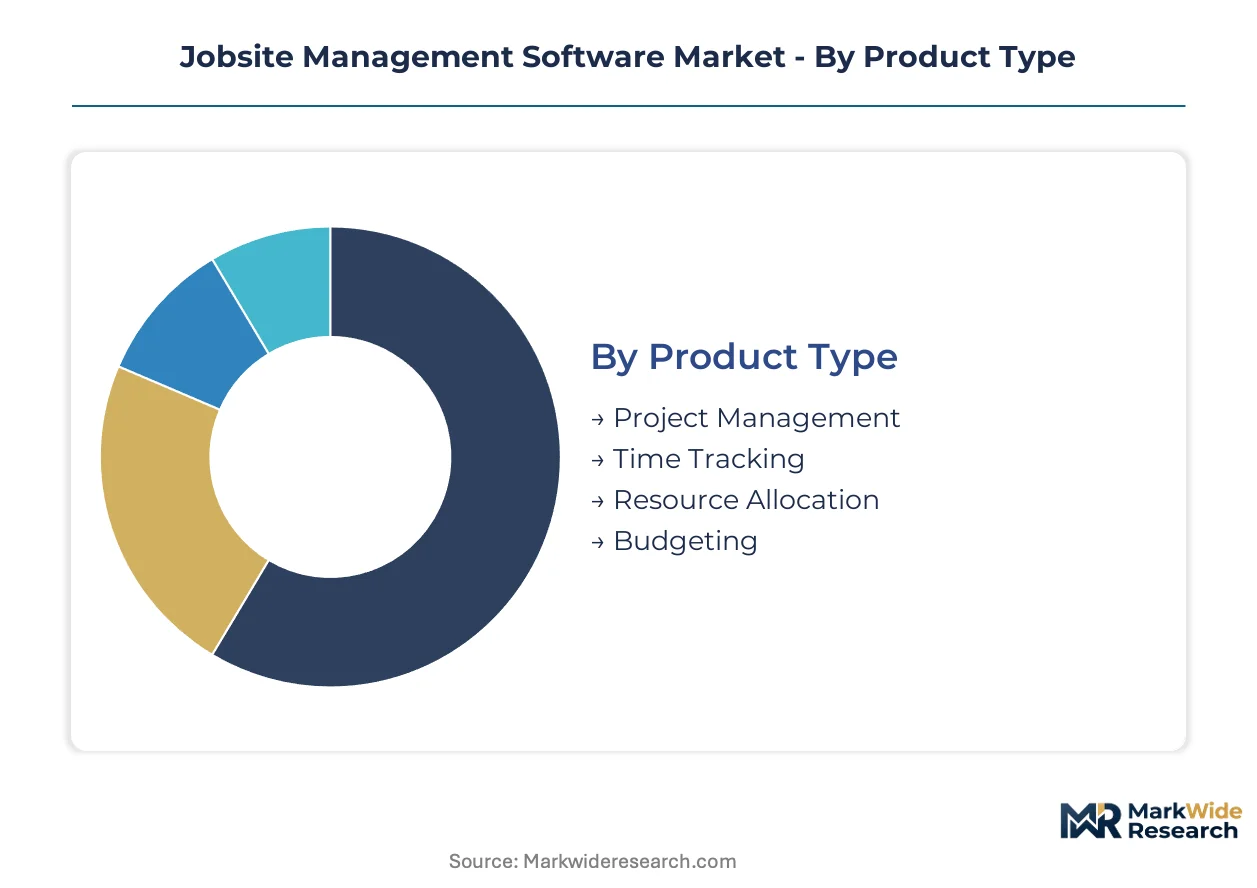
| Segmentation | Product Type: Project Management, Time Tracking, Resource Allocation, Budgeting Deployment: On-Premise, Cloud-Based, Hybrid Cloud, Mobile End User: Construction Companies, Contractors, Subcontractors, Project Managers Technology: AI-Driven, IoT Integration, Mobile Applications, Data Analytics |
| Companies Covered | Autodesk Construction Cloud, RedTeam Flex, Procore, LetsBuild, Workyard, Fieldwire, JobTread, Jonas Construction Software, Buildertrend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jobsite Management Software Market Strategic Shifts
Digital thread architectures are dissolving boundaries between design intent and field execution. Three distinct vectors are reshaping how construction enterprises evaluate and deploy coordination platforms.
Machine learning is absorbing variance in schedule risk prediction by ingesting historical project data and weather patterns. Tier-one contractors in the United States are deploying these models across portfolios exceeding five hundred concurrent jobsites. The technology is absorbing uncertainty buffers that previously inflated project timelines by eight to fifteen percent.
EU CSRD disclosure requirements are mandating granular carbon accounting from construction material sourcing through project completion. General contractors with European Union exposure must trace embodied carbon across concrete, steel, and timber supply chains. Specialty software modules for environmental product declarations are becoming standard procurement criteria in Germany and France.
Subscription fatigue among mid-market builders is fragmenting software stacks into best-of-breed point solutions. Project managers are assembling task-level field coordination tools alongside standalone safety platforms rather than accepting unified suites. This pattern concentrates in residential construction segments where per-project variability resists enterprise licensing commitments.
Jobsite Management Software Market Segmentation
Jobsite management software procurement splits along capability depth versus deployment flexibility. Contractors weighing full-lifecycle modules against point solutions face diverging integration costs and user adoption curves.
Product Type:
Project Management commands premium pricing through end-to-end workflow orchestration, while Time Tracking spreads across cost-sensitive subcontractor tiers.
- Project Management:Modules span bidding, scheduling, and closeout with unified data repositories. Demand concentrates among United States general contractors managing portfolios exceeding fifty concurrent jobsites, driven by federal infrastructure coordination requirements.
- Time Tracking:GPS-stamped clock-in systems and labor cost allocation tools dominate specialty trade adoption. Penetration stalls in residential construction where per-project variability resists enterprise licensing commitments.
- Resource Allocation:Equipment and crew dispatch optimization with real-time availability dashboards.
- Budgeting:Cost forecasting modules integrating procurement and change order workflows.
Today's leader: Project Management. Tomorrow's challenger: Resource Allocation.
Deployment:
Cloud-Based deployment minimizes infrastructure overhead for multi-site rollouts, while On-Premise retains footholds in data-sensitive aviation and defense-adjacent construction.
- Cloud-Based:Browser-accessible platforms with automatic updates and elastic storage. United States commercial builders prioritize these for rapid field-to-office synchronization without dedicated IT staffing.
- On-Premise:Locally hosted servers with custom security hardening. FAA-regulated airfield projects mandate these for sensitive coordination data.
- Hybrid Cloud:Core data on-premises with field sync through cloud gateways.
- Mobile:Offline-first smartphone applications for connectivity-challenged rural jobsites.
Cloud-Based deployment anchors current procurement. Mobile architectures are gaining share fastest where broadband gaps persist.
End User:
Construction Companies purchase enterprise suites, while Subcontractors fragment into task-specific point solutions.
- Construction Companies:General contractors with self-perform capabilities deploy integrated platforms across estimating, scheduling, and safety. OSHA digitization mandates accelerate replacement of paper-based systems.
- Contractors:Prime contractors managing multiple trade partners require stakeholder communication portals.
- Subcontractors:Specialty trades with thin margins resist per-seat licensing. Electrical and mechanical contractors in fragmented residential markets favor standalone field coordination tools.
- Project Managers:Individual practitioners assembling best-of-breed stacks for portfolio oversight.
Construction Companies drive current revenue concentration. Subcontractors represent the steepest expansion trajectory as platform vendors introduce consumption-based pricing.
Technology:
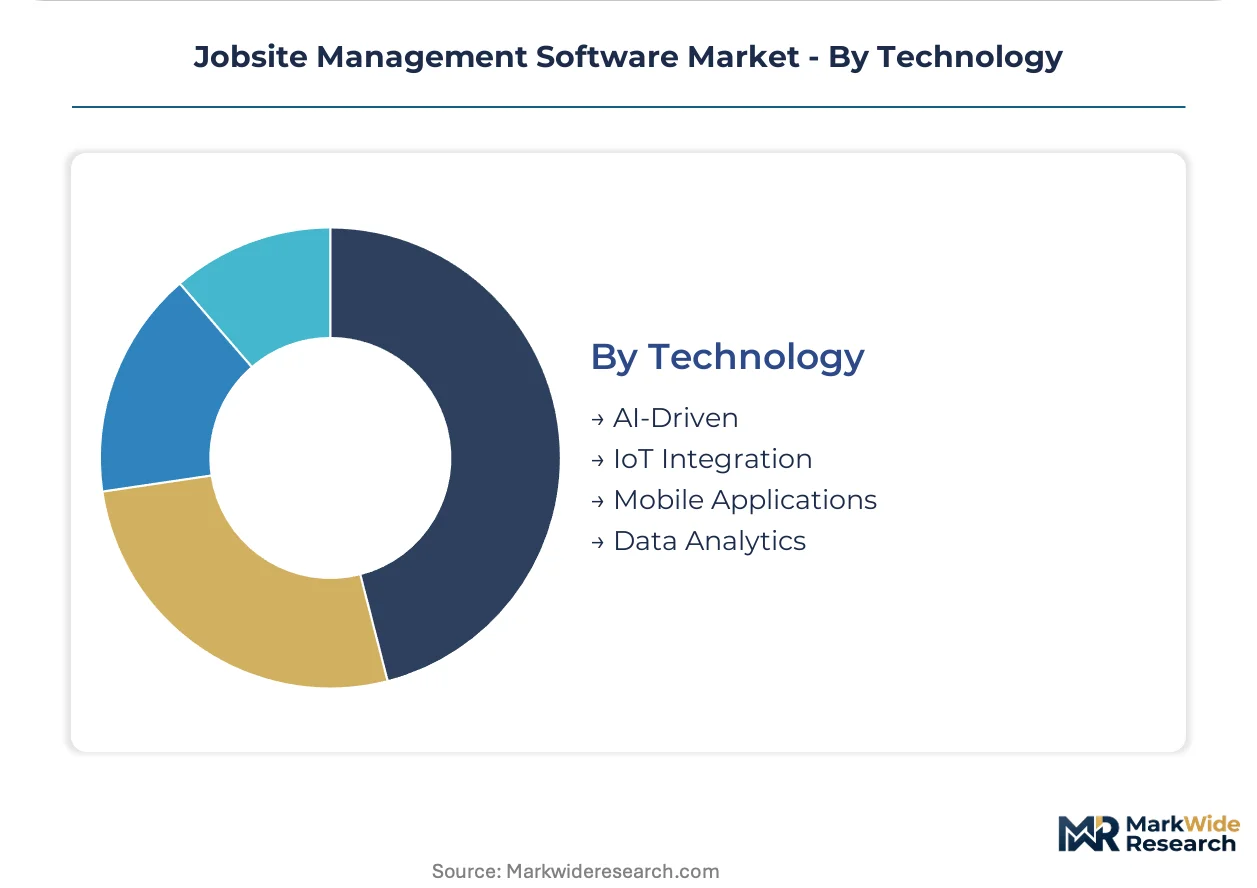
AI-Driven capabilities attract tier-one contractor investment, while Mobile Applications penetrate cost-constrained mid-market segments.
- AI-Driven:Predictive risk models ingesting historical project data and weather patterns. United States-based general contractors with five-hundred-plus concurrent jobsites deploy automated schedule optimization.
- Mobile Applications:Smartphone-native interfaces for field data capture. These dominate Australian and Canadian rural construction where broadband infrastructure gaps persist.
- IoT Integration:Sensor networks for equipment telematics and environmental monitoring.
- Data Analytics:Dashboards aggregating safety incidents, productivity metrics, and cost variance.
AI-Driven technology leads R&D investment. IoT Integration is climbing the fastest as equipment OEMs embed standardized telemetry APIs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where construction technology vendors prioritize deployment. Compliance cost gaps between jurisdictions with stringent digitization mandates and those with paper-based tolerance are accelerating software procurement in high-standard markets while delaying adoption elsewhere.
United States
Federal infrastructure spending and OSHA workplace safety digitization mandates are compressing procurement cycles for cloud-based coordination platforms. General contractors managing portfolios exceeding fifty concurrent jobsites now require real-time visibility as a baseline criterion. Texas and California anchor demand concentration, with Dallas-Fort Worth and Los Angeles metro areas driving enterprise suite adoption for commercial and residential build segments.
Germany
EU CSRD disclosure requirements and granular carbon accounting mandates are pushing environmental compliance modules into standard platform configurations. Construction firms with European Union exposure must trace embodied carbon across concrete, steel, and timber supply chains. Bavaria and North Rhine-Westphalia industrial clusters are pioneering BIM-to-field workflow integration for design-to-execution continuity.
United Kingdom
Post-Brexit regulatory divergence from EU standards is creating procurement uncertainty for cross-border contractors. London and Southeast England concentrate demand for AI-driven scheduling protocols among tier-one operators with five-hundred-plus concurrent jobsites. Midlands construction hubs are adopting mobile-first architectures to address rural broadband infrastructure gaps.
Australia
Connectivity infrastructure limitations in rural construction zones are accelerating offline-first mobile application deployment. Queensland and Western Australia mining-adjacent projects require specialized environmental monitoring dashboards for EPA-equivalent stormwater and emissions tracking. Sydney and Melbourne commercial builders prioritize cloud-native coordination for multi-site portfolio management.
Canada
Provincial safety regulator digitization timelines vary, creating patchwork compliance environments across Ontario, Quebec, and Alberta. Toronto and Vancouver metropolitan areas lead enterprise software procurement for large-scale infrastructure coordination. Prairie provinces and northern territories resist per-seat licensing models due to specialty trade fragmentation and thin subcontractor margins.
Jobsite Management Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-native scheduling and environmental compliance automation as differentiation vectors. The vendor landscape fragments across cloud-native incumbents, BIM-integrated design-to-field specialists, and task-level field coordination tools for subcontractor ecosystems. Three strategic archetypes dominate: enterprise platform consolidators, vertical specialists in aviation-adjacent or environmental compliance niches, and mobile-first challengers targeting connectivity-constrained markets. Competitive moves concentrate on strategic partnerships for ERP interoperability and portfolio diversification into carbon accounting modules.
Among cloud-native platform providers, Procore and Autodesk Construction Cloud exemplify the enterprise consolidation archetype, anchoring North American mid-market and large general contractor accounts through unified data repositories spanning bidding to closeout. Fieldwire occupies a position within the task-level specialization tier, representing vendors that fragment procurement by serving specialty trade contractors navigating thin-margin residential environments. These three companies illustrate how competitive positioning diverges between full-lifecycle orchestration and point-solution penetration.
| Leading Market Players |
|---|
| Autodesk Construction Cloud |
| RedTeam Flex |
| Procore |
| LetsBuild |
| Workyard |
| Fieldwire |
| JobTread |
| Jonas Construction Software |
| Buildertrend |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up software specialists have consolidated fragmented field-coordination vendors across North America and Europe, compressing channel margins while enforcing disciplined SaaS pricing tiers that tether subscription costs to project portfolio scale rather than per-seat headcount.
Pricing Analysis
Distributor margin layers in construction technology channels have compressed as direct-to-contractor SaaS sales displace legacy reseller networks. Three-tier pricing structure across premium, standard, and economy levels separates enterprise general contractors with fifty-plus concurrent jobsites from mid-market builders and specialty trade subcontractors. Price differentiation hinges on integration depth with ERP systems and FAA-certified compliance modules for aviation-adjacent work. Cost compression in the subcontractor tier is intensifying because thin-margin electrical and mechanical trades resist per-seat licensing models.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts platform vendor access to enterprise construction accounts with federal infrastructure exposure. Cloud infrastructure supply concentrates in the United States, Ireland, and Germany, with core compute and storage services drawing from hyperscaler regions with OSHA-equivalent data residency requirements. Software development labor pools rest on India and Eastern European delivery centers for cost-efficient engineering scale. Single-source vulnerability in AI model training data—particularly historical project schedules and weather pattern archives—threatens predictive analytics differentiation. Distribution runs through direct sales teams for enterprise accounts and self-service portals for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction technology procurement operates as a geographic-arbitrage play where contractors with European Union exposure absorb CSRD carbon accounting compliance costs that US-based competitors currently avoid, creating margin structure divergences across transatlantic operations.
For Market Incumbents: Anchor enterprise platform consolidation by acquiring task-level field coordination specialists serving fragmented subcontractor ecosystems. Threat from AI-native scheduling entrants with automated risk modeling capabilities demands accelerated R&D investment in predictive analytics. Certification investment in FAA-compliant workflow modules secures premium pricing for aviation-adjacent construction verticals. For New Entrants and Emerging Players: Regional system integrators with construction ERP expertise represent the fastest channel to enterprise penetration. White-space targets include offline-first mobile architectures for Australian and Canadian rural jobsites with persistent broadband gaps. Consumption-based pricing models unlock subcontractor segments where per-seat licensing stalls adoption. For Investors and Strategic Acquirers: Private equity firms with vertical software portfolios are the most active acquirers in this space, rolling up point-solution vendors into unified construction platforms. Five-to-ten year viability hinges on AI-driven automation depth and carbon accounting module integration. Acquisition target archetype: mobile-first field coordination tools with proven adoption in specialty trade segments. Signal to watch: tier-one contractor RFP language shifting from "real-time visibility" to "predictive risk mitigation" as mandatory procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies BIM design data with field execution workflows, eliminating specification drift rework for general contractors. |
| Acquisition of Specialist Firm | Captures FAA-certified compliance modules and aviation-adjacent customer relationships at premium pricing tiers. |
| Geographic Expansion | Establishes EU data residency for CSRD carbon accounting mandates affecting Germany and France construction markets. |
| Strategic Partnership | Secures ERP interoperability APIs that reduce legacy system integration costs for enterprise contractor accounts. |
| Product Launch | Introduces consumption-based pricing to unlock specialty trade subcontractor segments resistant to per-seat licensing. |
Study Parameters
Coverage spans North America, Europe, Asia-Pacific, and Australia, with primary inputs from each region combining structured interviews with general contractor technology officers, construction ERP integration specialists, specialty trade subcontractor operations managers, and FAA compliance officers with secondary validation. Secondary sources include SEC 10-K filings from listed construction technology vendors, OSHA regulatory docket analyses, EU CSRD implementation guidance documents, and hyperscaler infrastructure expansion disclosures. Bottom-up and top-down triangulation reconciles vendor-reported subscription metrics with contractor procurement survey data.
Rate-of-change decomposition separates volume expansion from pricing evolution across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical specialization, integration complexity with legacy ERP systems, and regional regulatory adoption pattern. CAGRs derive from trend extrapolation of software procurement cycles against infrastructure spending authorization timelines. Industry-specific forecast inputs incorporate FAA coordination protocol update schedules and EU carbon disclosure phase-in requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI model accuracy validation and interoperability standard consensus timelines. Forecasts reflect documented assumptions about federal infrastructure appropriation continuity and OSHA digitization mandate enforcement intensity. A model refresh is warranted upon material change in tier-one contractor AI adoption thresholds or EU carbon accounting technical specification finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Archiving Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
UI Design Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Global MSP Software Market
Software & Services
Global Reporting Software Market
Software & Services
Europe CMMS Software Market
Software & Services
MRP Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market