
 Debt Collection Software Market | 2026-2036
Debt Collection Software Market Size, Share, and Industry Trends Forecast 2026-2036
Debt Collection Software Market Intelligence
Buyer concentration across large financial institutions is restructuring procurement patterns for debt collection platforms. Experian leverages its credit data infrastructure to anchor integrated recovery solutions. FIS competes through embedded payment processing capabilities within its banking technology stack. TransUnion specializes in analytics-driven collections that merge credit intelligence with workflow automation.
Debt collection software encompasses platforms that automate account recovery workflows through predictive analytics, omnichannel communication orchestration, and regulatory compliance monitoring. These systems process delinquency data through machine learning models that score recovery probability and optimize contact timing across email, voice, SMS, and digital payment portals. Cloud-based deployment leads segment expansion as multi-tenant architectures reduce infrastructure overhead for mid-sized collection agencies. Compliance management features command premium pricing due to escalating regulatory complexity across jurisdictions. Automated communications modules sustain the fastest growth trajectory as lenders prioritize self-service repayment portals over call center dependency.
The US Consumer Financial Protection Bureau enforces FDCPA standards that mandate disclosure timing and restrict contact frequency, forcing vendors to embed consent management and audit trails. The EU AI Act classifies certain automated decisioning tools as high-risk, requiring human oversight protocols in European deployments. India's RBI guidelines on fair practices code for lenders impose structured communication windows and grievance escalation paths. Stakeholders must monitor divergence between regional compliance architectures when architecting platform roadmaps for cross-border financial services clients.
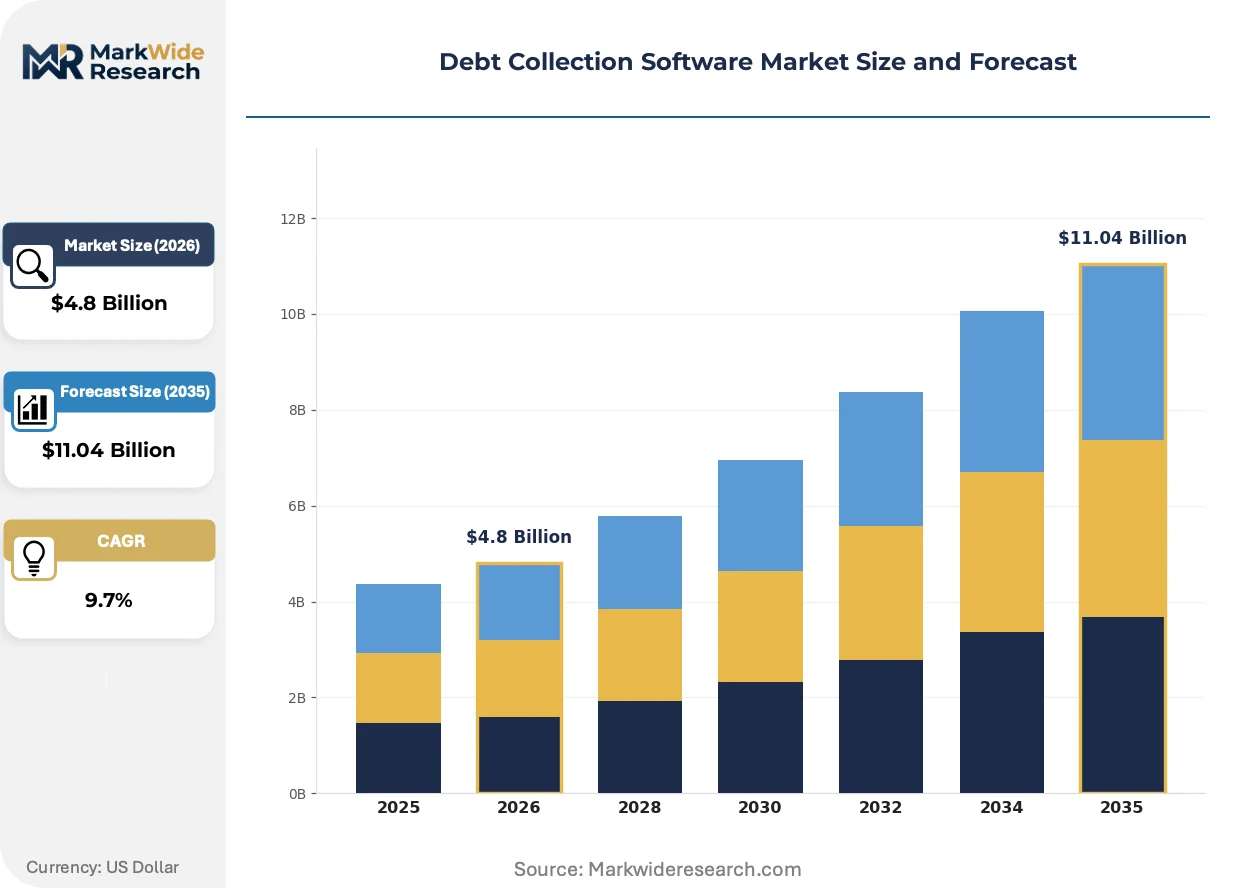
Market Dynamics
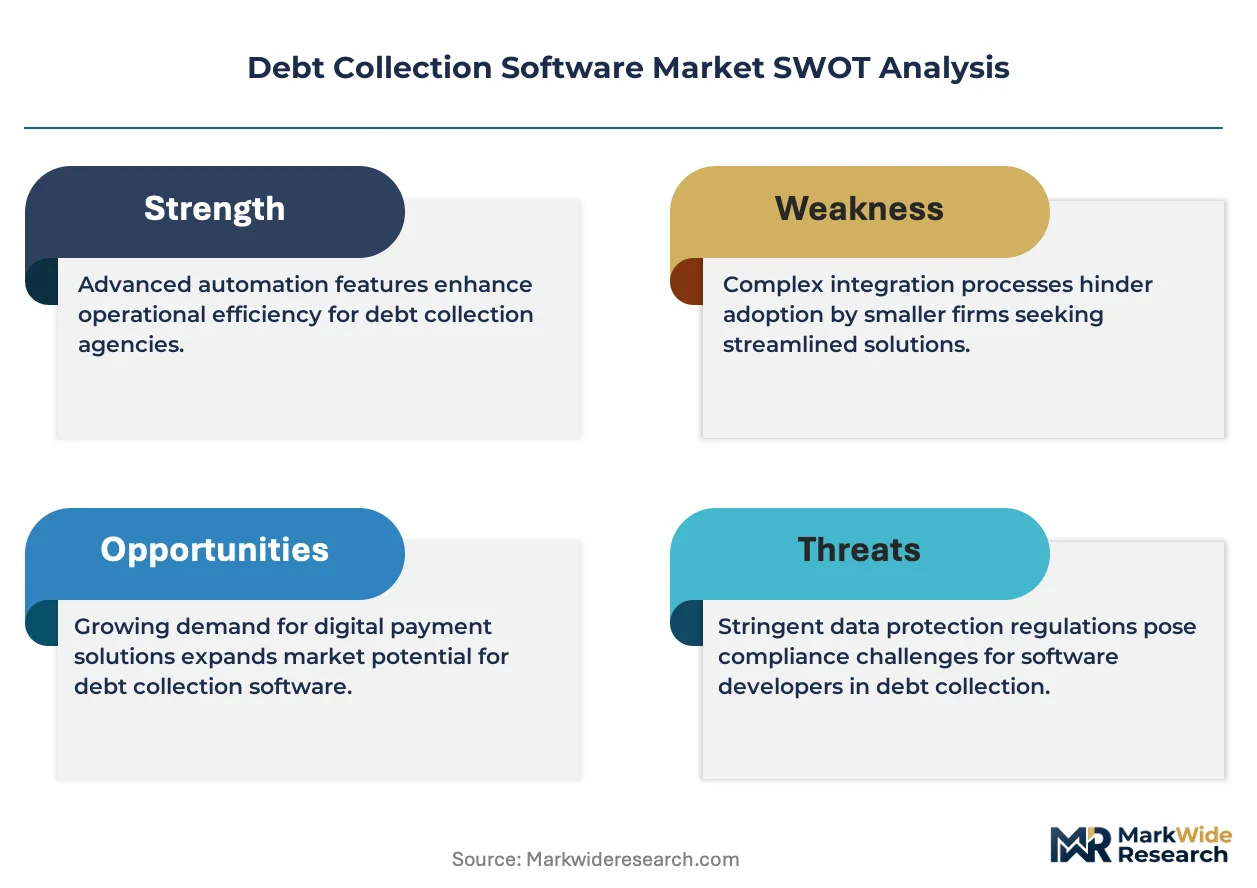
Cloud-native architectures are compressing deployment cycles for collection agencies while embedding compliance automation directly into recovery workflows, forcing legacy on-premise vendors to restructure pricing models or lose mid-market share.
Growth Catalysts
- FDCPA enforcement escalation:The US Consumer Financial Protection Bureau's intensified audit protocols mandate granular consent tracking and contact-frequency logging, driving replacement demand for systems lacking native audit trails.
- Self-service repayment portals:Borrowers now expect SMS-triggered payment links and chatbot-negotiated settlement plans, pushing lenders to retire call-center-dependent recovery models.
- Machine learning scoring engines:Predictive models that rank accounts by recovery probability and optimal contact timing are reducing operational cost per dollar collected for first-party issuers.
Market Restraints
- Cloud infrastructure concentration:AWS, Microsoft Azure, and Google Cloud control the multi-tenant hosting layer for most SaaS collection platforms, creating single-point-of-failure exposure during regional outages.
- EU AI Act compliance burden:Automated decisioning tools classified as high-risk require human-in-the-loop protocols, extending implementation timelines and inflating professional services costs for European deployments.
- Substitution by in-house development:Large banks with captive IT teams are building proprietary recovery modules on core banking platforms, bypassing third-party vendor relationships entirely.
Strategic Opportunities
- India's digital lending expansion:RBI-mandated grievance escalation paths and structured communication windows create demand for compliant workflow automation among non-bank financial companies issuing micro-loans.
- Embedded finance convergence:Buy-now-pay-later providers integrating recovery triggers at the point of transaction need lightweight, API-first collection modules that traditional vendors lack.
- Outcome-based pricing models:Vendors can capture upside by tying license fees to percentage of debt recovered rather than seat-based subscriptions, aligning incentives with issuer performance.
Industry Challenges
- Data science talent scarcity:Collection agencies struggle to hire machine learning engineers capable of tuning recovery models without triggering disparate impact concerns under fair lending rules.
- Core banking integration complexity:Legacy mainframe systems at regional banks require expensive middleware development to expose delinquency data to modern cloud recovery platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Debt Collection Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Financial Institutions, Collection Agencies, Businesses, Government Deployment: Single Tenant, Multi-Tenant, Private Cloud, Public Cloud Feature: Automated Communications, Reporting Tools, Payment Processing, Compliance Management |
| Companies Covered | Experian, FIS, CGI, TransUnion, FICO, Temenos, Nucleus Software Exports Ltd., Pegasystems, Chetu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debt Collection Software Market Strategic Shifts & Innovations
Artificial intelligence is compressing the timeline from account delinquency to recovery while fragmenting vendor competitive advantage around specialized compliance engines rather than generic workflow tools.
Conversational AI is rewriting how collection agencies interact with debtors. Natural language processing engines now handle payment negotiation, dispute intake, and hardship documentation through voice and chat interfaces. Tier-two collection agencies are deploying these tools fastest to offset rising labor costs in contact centers. The technology is rewriting cost structures by reducing agent headcount requirements for routine interactions while elevating human staff to complex negotiation and legal escalation work.
The EU AI Act's high-risk system classification is forcing structural redesign of automated decisioning modules. Vendors must now engineer explicit human oversight checkpoints before finalizing settlement offers or payment plan terms. European issuers are responding by bifurcating their technology stacks—deploying simplified rule-based systems for the EU market while maintaining full automation elsewhere. This regulatory friction is creating geographic product fragmentation that complicates vendor roadmap prioritization.
Subscription pricing for collection software is yielding to performance-linked commercial structures. Issuers now demand contracts where vendor compensation scales with recovery rates achieved rather than user licenses provisioned. This shift is most visible among fintech lenders with thin margins who cannot absorb fixed technology costs during economic downturns. The model pressures vendors to invest in predictive accuracy while exposing them to revenue volatility tied to macroeconomic conditions outside their control.
Debt Collection Software Market Segmentation
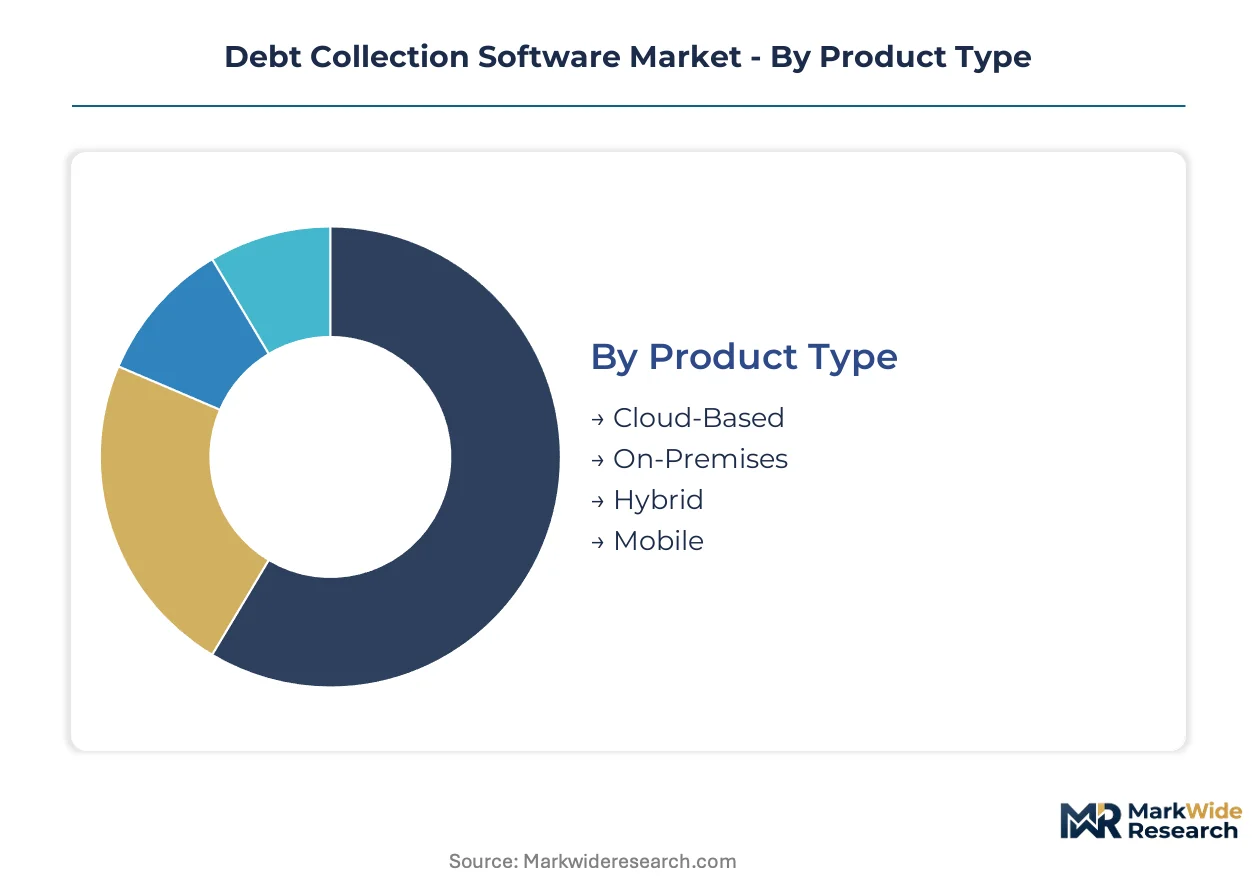
Segmentation in debt collection software reveals how deployment architecture, user sophistication, and regulatory exposure shape purchasing decisions. Vendors must align product configurations to the compliance burden and integration depth each buyer segment demands.
Product Type:
Deployment architecture determines infrastructure overhead, update velocity, and data sovereignty compliance for recovery operations.
- Cloud-Based:Multi-tenant SaaS platforms deliver automatic regulatory patches and elastic compute for seasonal delinquency spikes. Demand concentrates among mid-sized collection agencies in the US and Germany seeking to avoid capital expenditure on server infrastructure while maintaining FDCPA and GDPR audit trails.
- On-Premises:Self-hosted installations keep delinquency data within institutional firewalls, satisfying banking regulators in India and data localization mandates. State-owned banks and defense credit unions in specific jurisdictions mandate this architecture despite higher total cost of ownership.
- Hybrid:Split configurations process sensitive PII on local servers while pushing analytics workloads to public cloud. Appeals to regional banks navigating India's RBI data localization rules alongside cost pressures.
- Mobile:Native iOS and Android applications enable field agents to negotiate settlements and capture payment authorizations during door-to-door collections. Expanding most quickly in South Asian microfinance where smartphone penetration outpaces desktop infrastructure.
Cloud-Based leads on scale; Mobile leads on momentum.
End User:
Buyer sophistication and captive IT capacity fragment procurement patterns across recovery value chain participants.
- Financial Institutions:Banks, credit unions, and captive finance companies deploy first-party collection modules integrated to core banking systems. Tier-one issuers in the US and Western Europe drive demand for machine learning scoring engines that rank accounts by recovery probability.
- Collection Agencies:Third-party servicers managing charged-off debt require omnichannel campaign orchestration across email, voice, SMS, and digital portals. These buyers prioritize per-seat pricing flexibility and rapid agent onboarding workflows.
- Businesses:Non-financial enterprises with trade credit exposure—healthcare providers, utilities, telecom operators—adopt lightweight recovery tools through ERP marketplaces. Manufacturing suppliers in Germany leverage these systems for accounts receivable automation.
- Government:Tax authorities and municipal utilities impose rigid procurement protocols and sovereign data requirements. Installations concentrate at state-level agencies in India and federal entities with legacy mainframe dependencies.
Financial Institutions anchor revenue concentration; Collection Agencies show steepest expansion trajectory.
Deployment:
Tenancy model and cloud ownership structure determine isolation guarantees and operational control boundaries.
- Single Tenant:Dedicated infrastructure instances prevent noisy-neighbor performance degradation and satisfy stringent audit requirements. Preferred by US federal credit unions and German Landesbanken with regulatory mandates for physical data segregation.
- Multi-Tenant:Shared resource pools amortize infrastructure costs across client bases, enabling subscription pricing accessible to independent collection agencies. Dominates mid-market penetration in cloud-first adoption curves.
- Private Cloud:Managed deployments within client-controlled data centers or dedicated hosted environments balance elasticity with compliance. Expanding among Indian non-bank financial companies navigating RBI operational guidelines.
- Public Cloud:AWS, Microsoft Azure, and Google Cloud-hosted instances offer geographic redundancy and rapid scaling. Concentration risk emerges as regional outages disrupt recovery operations across multiple agency clients simultaneously.
Multi-Tenant leads on scale; Private Cloud leads on momentum.
Feature:
Functional modules differentiate vendor offerings based on automation depth and regulatory coverage.
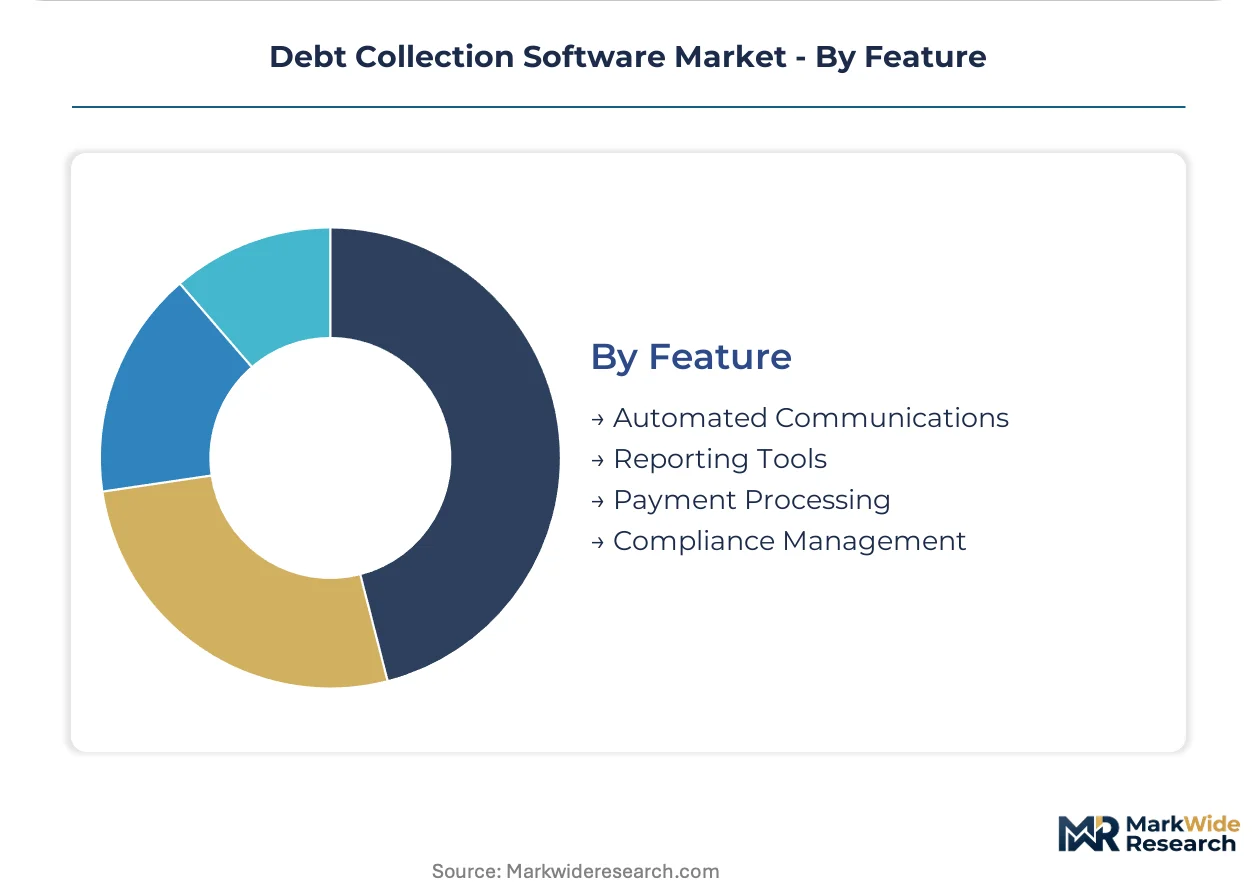
- Automated Communications:Omnichannel orchestration engines schedule contact timing across email, voice, SMS, and chatbot interfaces while enforcing jurisdiction-specific frequency caps. Self-service repayment portals within this module reduce call center dependency for US and UK issuers.
- Reporting Tools:Dashboard and analytics layers visualize portfolio performance, agent productivity, and compliance posture. Standard procurement requirement for agency managers seeking operational transparency.
- Payment Processing:Embedded settlement engines negotiate payment plans, process card and ACH transactions, and generate reconciliation files. Critical for fintech lenders in India requiring instant payment confirmation.
- Compliance Management:Audit trails, consent tracking, and regulatory reporting automation command premium pricing. Escalating FDCPA enforcement and EU AI Act requirements elevate this module to deal-breaker status in procurement evaluations.
Automated Communications leads on scale; Compliance Management leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys cloud-native recovery platforms at scale while Germany enforces stricter data sovereignty protocols under GDPR and the EU AI Act. India's digital lending surge creates divergent compliance architectures across these three major markets.
United States
First-party issuers and third-party agencies drive demand for FDCPA-compliant automation with embedded audit trails. The Consumer Financial Protection Bureau intensifies enforcement of contact-frequency caps and consent documentation requirements. Dallas and Phoenix host expanding operations centers where collection agencies deploy machine learning scoring engines for account prioritization.
Germany
Landesbanken and regional credit cooperatives prioritize on-premise and private cloud deployments to satisfy data localization mandates. The EU AI Act classifies automated settlement decisioning as high-risk, requiring human-in-the-loop protocols. Frankfurt's financial technology cluster sees vendors restructuring product roadmaps to bifurcate EU-compliant rule-based systems from full-automation stacks deployed elsewhere.
India
Non-bank financial companies issuing micro-loans require workflow automation aligned with RBI fair practices codes and structured grievance escalation paths. Mumbai and Bengaluru concentrate vendor development centers serving the domestic digital lending expansion. Hyderabad-based fintechs increasingly demand API-first collection modules integrated at transaction origination points.
United Kingdom
Buy-now-pay-later providers and challenger banks seek lightweight recovery tools with self-service repayment portals to reduce call center dependency. The Financial Conduct Authority's consumer duty rules mandate transparent communication timing and affordability assessments. London's fintech corridor drives fastest adoption of conversational AI for payment negotiation and dispute intake.
Japan
Regional banks with legacy core systems pursue hybrid deployment models to balance modernization pressures against mainframe integration complexity. METI guidelines on AI governance influence procurement evaluations for automated decisioning tools. Tokyo's financial district concentrates vendor professional services teams specializing in middleware development for legacy system connectivity.
Debt Collection Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Credit bureaus and core banking technology providers leverage data infrastructure and payment processing integration to anchor recovery solutions. Three strategic archetypes dominate: data-anchored platforms, embedded finance modules, and compliance-specialized workflows. Consolidation through strategic partnerships and geographic expansion into high-growth Asian markets represent the dominant competitive moves reshaping vendor positioning.
Within the data-anchored tier, Experian and TransUnion exemplify players leveraging credit intelligence infrastructure to differentiate recovery platform offerings. FIS occupies a position bridging core banking technology with embedded collection capabilities. These three entities represent how incumbent data and payment infrastructure providers are restructuring competitive dynamics against standalone software specialists.
| Leading Market Players |
|---|
| Experian |
| FIS |
| CGI |
| TransUnion |
| FICO |
| Temenos |
| Nucleus Software Exports Ltd. |
| Pegasystems |
| Chetu |
| Others |
Cost & Logistics Intelligence
EU AI Act human-in-the-loop mandates gate qualified supply for European deployments while compressing premium-tier pricing access for vendors lacking compliant automation architectures. FDCPA audit trail requirements in the US and RBI fair practices codes in India similarly stratify vendor tiers by regulatory certification depth.
Pricing Analysis
Capacity additions in India are reshaping price floors for API-first collection modules serving digital lenders. The dominant pricing structure is subscription-based SaaS with tiered seat licensing, though outcome-based models tying fees to recovery percentages are gaining traction among fintech issuers. Price differentiation rests on compliance certification depth and machine learning scoring accuracy. Pricing pressure stems from in-house development at large banks with captive IT teams. Mid-sized collection agencies show highest price sensitivity; tier-one financial institutions prioritize compliance coverage over cost.
Supply Chain Analysis
Dual-sourcing requirements from financial institutions mandate multi-supplier qualification across cloud infrastructure and professional services layers. Supply concentrates in the United States, Germany, and India for core platform development, with cloud hosting anchored in AWS, Microsoft Azure, and Google Cloud data centers. Raw material dependencies span machine learning compute capacity, regulatory compliance frameworks, and API integration middleware. Single-source vulnerability runs through hyperscaler concentration for multi-tenant deployments. Distribution runs through direct enterprise sales teams and banking technology channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Issuer procurement committees now mandate FDCPA audit trails and EU AI Act human oversight protocols as baseline requirements, shifting demand toward premium-tier compliance-automation bundles.
For Market Incumbents: Deepen vertical integration into machine learning scoring engines to defend against in-house bank development teams building proprietary recovery modules. Acquire specialist compliance workflow vendors in Germany and India to anchor regional certification moats. Prioritize outcome-based pricing pilots with thin-margin fintech lenders to lock in long-term platform dependency.
For New Entrants and Emerging Players: API-first distribution partnerships with buy-now-pay-later providers and embedded finance platforms offer the most penetrable entry vector. Target India's non-bank financial companies with lightweight, RBI-compliant workflow automation priced below incumbent seat-based models. Lead with conversational AI modules for payment negotiation to differentiate from legacy call-center-dependent systems.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized compliance-specialized vendors with EU AI Act-ready human-in-the-loop architectures and established RBI relationships. Long-term viability hinges on regulatory certification breadth across multiple jurisdictions. Watch for CFPB enforcement escalation intensity as the inflection signal for replacement demand cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Expansion | EU AI Act human-in-the-loop protocols open premium pricing tiers for certified vendors. |
| Outcome-Based Pricing Pilots | Fintech lender partnerships align vendor incentives with issuer recovery performance. |
| API-First Platform Integration | Embedded finance convergence demands lightweight collection modules at transaction origination. |
| Geographic Development Center Expansion | Mumbai and Bengaluru talent pools anchor India digital lending automation demand. |
| Conversational AI Module Launch | Natural language processing engines reduce contact center headcount for tier-two agencies. |
Research Approach
Direct dialogue with collection agency operations directors, bank CTOs, compliance officers at non-bank financial companies, and fintech product managers grounded qualitative findings. Secondary validation drew from CFPB enforcement bulletins, RBI circulars on fair practices, EU AI Act implementation guidance, SEC filings of publicly traded credit bureaus, and cloud hyperscaler partner program disclosures. Bottom-up sizing of deployment volumes triangulated against top-down spending estimates from financial institution technology budgets.
Segmented outputs across cloud-based, on-premises, hybrid, and mobile deployment architectures modeled penetration curves over the projection horizon. Organization size tiers, vertical specialization, and regional regulatory cluster density shaped the analytical framework. CAGRs derived from logistic adoption curves fitted to historical compliance mandate response patterns and machine learning scoring engine deployment trajectories. Forecast inputs included FDCPA enforcement intensity indices and digital lending origination growth rates.
The model assumes a particular technology adoption path; alternative pathways for conversational AI substituting human agent workflows would alter the outlook. Forecasts reflect assumptions around regulatory enforcement continuity and cloud infrastructure availability. Deviation in CFPB audit protocol intensity or EU AI Act implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
App Development Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Commissioning Software Market
Software & Services
Global Storm Tracking Apps Market
Software & Services
Nonconformance Management Software Market
Software & Services
Clustering Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Global Printing Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Embedded Hypervisor Market