
 App Building Software Market | 2026-2036
App Building Software Market Size, Share, and Industry Trends Forecast 2026-2036
App Building Software Market Insights
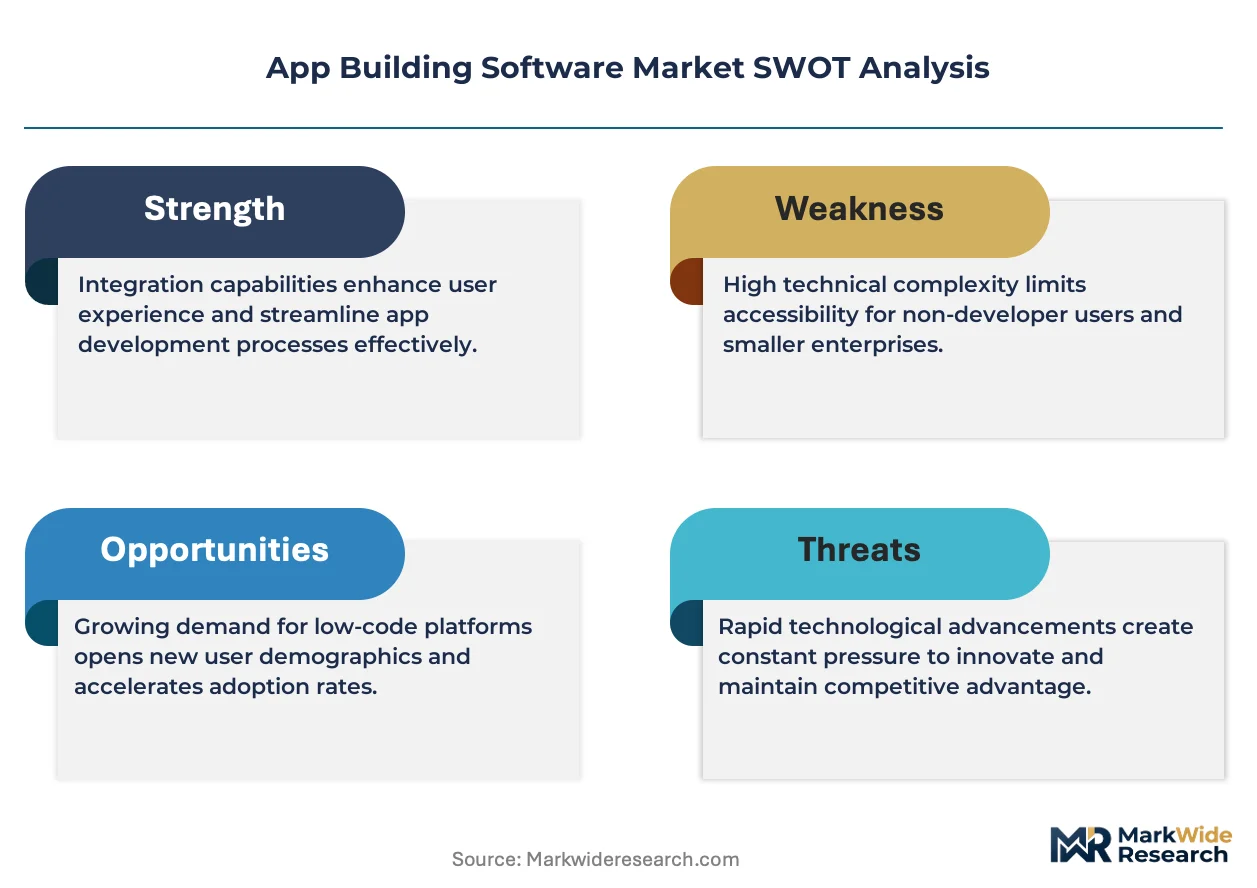
Platform bundling is consolidating buyer choice around suites that merge visual development, database layers, and automation into single subscriptions. OutSystems leverages enterprise-grade security certifications to anchor high-value contracts in regulated industries. Zapier competes through deep integration density across SaaS ecosystems, while Softr specializes in rapid front-end deployment atop existing data sources.
App building software comprises visual development environments, pre-built component libraries, and runtime engines that generate executable applications through declarative interfaces rather than hand-coded syntax. These systems typically support drag-and-drop workflow composition, API connectivity, and cross-platform compilation to reduce time-to-deployment from months to days. Cloud deployment dominates structural investment as organizations prioritize elastic scaling and zero-maintenance infrastructure over on-premise control. Low-code and no-code solutions capture the fastest expansion within the solution dimension, though traditional development retains margin concentration in complex custom engagements. Mobile-based and cross-platform technologies lead technology adoption as workforce mobility and customer-facing digitization converge.
FDA scrutiny of software-as-medical-device applications shapes validation requirements for healthcare deployments, while GDPR and the EU AI Act impose algorithmic transparency and data residency obligations on European implementations. HIPAA compliance remains non-negotiable for US healthcare use cases, constraining vendor architectures and buyer shortlists. Stakeholders must weigh sovereignty requirements against integration breadth when selecting platforms for multi-jurisdictional rollouts.
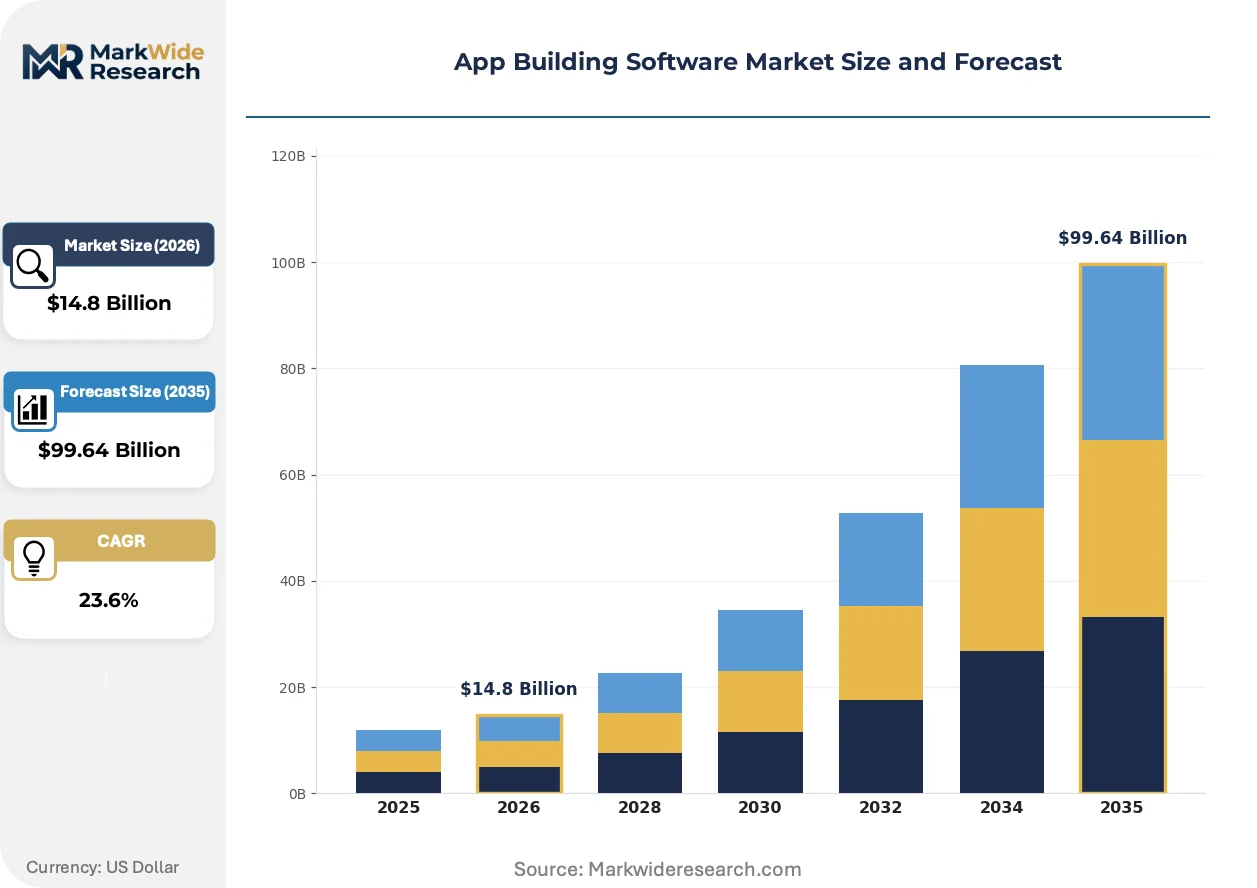
Market Dynamics
Platform bundling is consolidating buyer choice around suites that merge visual development, database layers, and automation into single subscriptions, compressing procurement cycles and displacing point solutions.
Growth Catalysts
- EU AI Act:Algorithmic transparency mandates in Europe are pushing buyers toward auditable low-code environments with built-in governance tooling.
- Healthcare digitization:HIPAA-compliant no-code platforms enable patient-facing portals without dedicated engineering teams, accelerating deployment timelines.
- Developer scarcity:Enterprise IT backlogs in the United States are forcing procurement of citizen-development tools to clear project queues.
Market Restraints
- Runtime dependency:Vendor-controlled execution environments create lock-in risks and limit data sovereignty for regulated deployments.
- Complexity ceiling:Declarative interfaces hit functional limits when applications require custom algorithmic logic or deep system integration.
- GDPR friction:Cross-border data residency requirements constrain cloud-native platform architectures and inflate compliance overhead.
Strategic Opportunities
- India:PLI scheme incentives for software exports and BIS certification pathways create favorable conditions for platform localization.
- Edge-to-cloud convergence:Integration of containerized runtime engines with 5G MEC infrastructure opens industrial IoT application development.
- Vertical specialization:Purpose-built templates for FDA software-as-medical-device validation capture high-margin healthcare contracts.
Industry Challenges
- Legacy integration:Mainframe and on-premise ERP connectivity requires specialized middleware expertise scarce in low-code talent pools.
- Security certification lag:FedRAMP and ISO 27001 timelines stretch 12-18 months, delaying public sector and enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | App Building Software Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $99.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premise, Hybrid, Multi-Tenant End User: Startups, Enterprises, Freelancers, Developers Solution: Low-Code, No-Code, Traditional Development, Prototyping Technology: Web-Based, Mobile-Based, Desktop-Based, Cross-Platform |
| Companies Covered | Bubble, OutSystems, Airtable, Zapier, Softr, Microsoft Power Apps, Retool, Appery.io, Adalo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
App Building Software Market Trends and Innovations
Generative AI is embedding into visual development environments, transforming how applications are composed and maintained across enterprise and mid-market segments.
AI-assisted code generation is integrating natural language prompts into drag-and-drop interfaces, allowing non-technical users to describe workflows that platforms translate into executable logic. Healthcare providers and financial services firms are piloting these capabilities to accelerate patient portal and compliance reporting builds. This compression of the specification-to-deployment pipeline is integrating business analysts directly into application delivery, bypassing traditional handoffs to engineering teams.
The EU AI Act's risk-based classification system is mandating documentation and human oversight for high-stakes automated decision-making. Platform vendors must now embed explainability features and audit trails into their runtime engines. Healthcare and public sector deployments across Germany, France, and the Netherlands are prioritizing vendors with pre-built compliance modules over generalist alternatives.
Subscription unbundling is fragmenting how buyers procure application capabilities, with enterprises separating database, automation, and front-end layers across best-of-breed vendors. Mid-market buyers in the United States are increasingly assembling multi-vendor stacks through API marketplaces rather than accepting monolithic suites. This pattern is most visible in retail and logistics verticals where specialized workflow engines outperform generic platform offerings.
App Building Software Market Segmentation
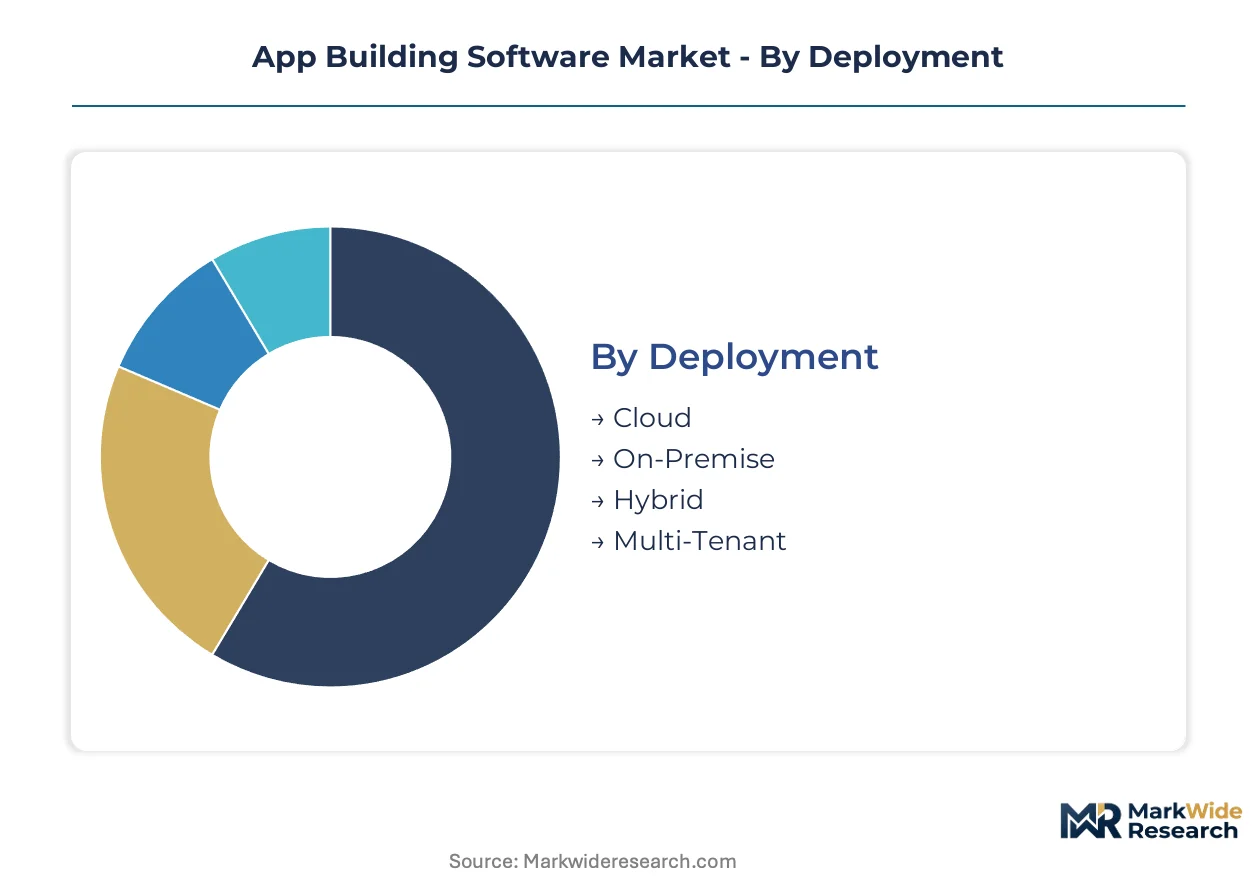
Deployment architecture determines vendor lock-in risk and compliance posture for regulated buyers. End-user segmentation reveals diverging procurement patterns between centralized IT procurement and shadow IT adoption. Solution type and technology platform choices directly constrain functional ceilings and integration depth.
Deployment:
Cloud infrastructure concentrates supply among hyperscale providers, compressing margin capture for independent platform vendors.
- Cloud:Elastic scaling through AWS, Azure, or Google Cloud infrastructure eliminates capital expenditure for compute resources. Healthcare providers in Germany and the Netherlands prioritize cloud deployments with EU data residency guarantees to satisfy GDPR requirements.
- On-Premise:Self-managed execution environments retain full data sovereignty and audit control. Financial institutions in Switzerland and defense contractors in the United States mandate on-premise runtimes to satisfy national security regulations.
- Hybrid:Split workloads across private infrastructure and public cloud based on data classification tiers.
- Multi-Tenant:Shared runtime environments minimize per-customer infrastructure overhead for SaaS platform economics.
Today's leader: Cloud. Tomorrow's challenger: Hybrid.
End User:
Procurement authority fragments across centralized IT budgets and departmental discretionary spending.
- Enterprises:Centralized procurement teams negotiate enterprise-wide platform licenses with FedRAMP or ISO 27001 prerequisites. Manufacturing conglomerates in Japan and telecommunications operators in South Korea anchor high-value contracts requiring dedicated customer success teams.
- Startups:Venture-backed companies prioritize speed-to-market over long-term architecture decisions. Fintech startups in Singapore and e-commerce ventures in the United Arab Emirates favor consumption-based pricing without upfront commitments.
- Freelancers:Independent contractors assemble client solutions across multiple platforms without standardization.
- Developers:Individual engineers evaluate platforms based on API completeness and extensibility mechanisms.
Enterprise procurement dominates current revenue. Startup adoption expands the fastest.
Solution:
Functional abstraction depth determines which user personas can participate in application delivery.
- Low-Code:Visual development environments with optional code extension points for complex logic. Insurance underwriters in France and logistics coordinators in the United States build workflow automation without engineering support while retaining escape hatches for custom algorithms.
- No-Code:Purely declarative interfaces eliminating syntax entirely. Hospital administrators in the United Kingdom and retail operations managers in Australia deploy patient portals and inventory dashboards through drag-and-drop composition.
- Traditional Development:Hand-coded implementations retaining full control over runtime behavior and optimization.
- Prototyping:Rapid validation tools for user experience testing before production commitment.
Low-code anchors current enterprise spending. No-code gains share fastest among line-of-business buyers.
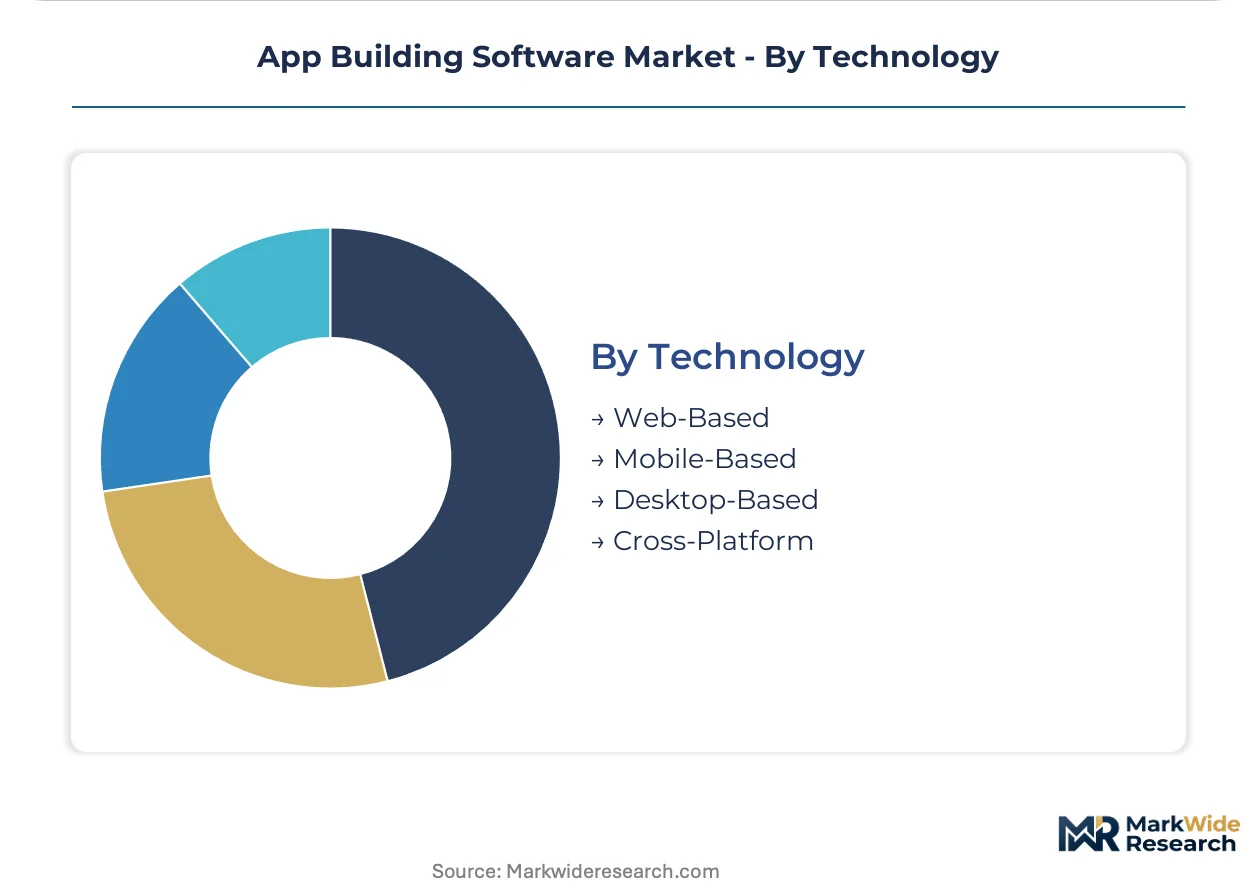
Technology:
Runtime target constrains distribution mechanics and update cadence for delivered applications.
- Cross-Platform:Single codebase compilation to iOS, Android, and web runtimes through frameworks like React Native or Flutter. Consumer brands in Brazil and quick-service restaurant chains in Mexico deploy unified customer experiences across device types without platform-specific engineering.
- Mobile-Based:Native or near-native execution optimized for smartphone sensors and offline capability. Field service technicians in Canada and agricultural inspectors in India rely on mobile-first applications with GPS and camera integration.
- Web-Based:Browser-delivered experiences eliminating app store approval friction and installation barriers.
- Desktop-Based:Local installation for compute-intensive or offline-critical workflows.
Cross-platform development commands premium pricing. Web-based delivery climbs fastest for internal tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
App building software originated in the United States during the 2010s, when cloud infrastructure maturation enabled visual development environments to displace traditional coding workflows. Early platforms scaled through venture capital concentration in Silicon Valley and Boston before expanding internationally.
United States
Enterprise IT backlogs and developer shortages drive procurement of citizen-development tools across Fortune 500 manufacturers and healthcare systems. HIPAA compliance requirements constrain vendor architectures for patient-facing portal deployments. The Boston metropolitan area anchors significant platform engineering talent pools.
Germany
Industrial automation demand from automotive and machinery producers accelerates low-code adoption for shop-floor digitization. The EU AI Act's algorithmic transparency mandates push buyers toward auditable platforms with built-in governance tooling. Munich and Stuttgart host concentrated Industry 4.0 implementation clusters.
United Kingdom
Financial services digitization and NHS administrative modernization sustain demand for rapid application deployment without dedicated engineering teams. GDPR cross-border data residency requirements influence cloud platform selection for multi-jurisdictional rollouts. London's fintech corridor represents the densest concentration of no-code procurement.
India
PLI scheme incentives for software exports and BIS certification pathways create favorable conditions for platform localization and talent arbitrage. Domestic IT services firms adopt low-code tools to compress client delivery timelines. Bengaluru and Hyderabad anchor the primary engineering and customer success operations.
Japan
Manufacturing conglomerates and telecommunications operators anchor high-value contracts requiring dedicated customer success teams and localized runtime support. METI industrial digitization directives accelerate legacy system modernization initiatives. Tokyo and Osaka metropolitan areas concentrate enterprise procurement authority.
App Building Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across security certification depth, with FedRAMP and ISO 27001 prerequisites separating enterprise-grade contracts from mid-market subscriptions. The vendor landscape organizes around three strategic archetypes: suite providers bundling database and automation layers, integration specialists maximizing SaaS connectivity density, and front-end rapid-deployment platforms. Dominant competitive moves include vertical specialization into regulated healthcare workflows and geographic expansion through localized compliance certification.
Within the suite-provider tier, Microsoft Power Apps and OutSystems occupy positions emphasizing enterprise security certifications and regulated industry penetration. Zapier exemplifies the integration-specialist archetype through its density of SaaS ecosystem connectivity. Softr represents the front-end rapid-deployment segment with its focus on visual composition atop existing data sources.
| Leading Market Players |
|---|
| Bubble |
| OutSystems |
| Airtable |
| Zapier |
| Softr |
| Microsoft Power Apps |
| Retool |
| Appery.io |
| Adalo |
| Others |
Pricing and Supply Chain Analysis
HIPAA-mandated security certifications for US healthcare deployments force platform vendors to absorb 12-18 month FedRAMP timelines before revenue recognition, compressing margins on enterprise contracts and pushing pricing differentiation toward compliance-grade tiers rather than raw feature counts.
Pricing Analysis
Consumption-based SaaS subscriptions with seat- and usage-tiered bands dominate commercial terms across the analysis window. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized enterprise suites from mid-market self-serve tiers and individual developer freemium tiers. Price differentiation rests on security certification depth and dedicated customer success staffing. Pricing pressure stems from hyperscaler bundling of Power Apps and Azure credits. Startups exhibit highest price sensitivity; regulated healthcare buyers prioritize compliance over cost.
Supply Chain Analysis
Refurbishment and runtime migration flows remain minimal given SaaS delivery models, though on-premise license holders occasionally repatriate workloads to private infrastructure. Engineering talent concentrates in the United States, India, and Germany. Cloud infrastructure draws from hyperscale providers in those markets plus Ireland and Singapore for GDPR-compliant EU residency. Single-source vulnerability sits with AWS, Azure, and Google Cloud compute dependencies. Distribution runs through direct enterprise sales teams, self-serve web onboarding, and systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-based classification system compounds demand for auditable platforms, making regulatory compliance a durable margin anchor rather than a commoditized checkbox.
For Market Incumbents: Lock in healthcare and financial services accounts through pre-built FDA software-as-medical-device validation modules and EU AI Act explainability tooling. Deepen vertical integration into specialized compliance engineering teams. Defend against hyperscaler bundling by anchoring multi-year contracts with dedicated customer success resources. For New Entrants and Emerging Players: API marketplace distribution routes offer lowest-friction customer acquisition for vertical workflow engines targeting retail and logistics buyers underserved by monolithic suites. White-space concentrates in India PLI scheme localization and 5G MEC industrial IoT edge-to-cloud convergence. Lead with consumption-based pricing and rapid time-to-value proofs. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical-specialist platforms holding pre-certified healthcare compliance modules and established hospital system relationships. Long-term viability favors vendors with durable data residency architectures spanning EU, US, and Asia-Pacific regulatory clusters. Monitor FedRAMP authorization backlog clearance as inflection signal for public sector revenue acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Specialization | FDA validation modules capture high-margin healthcare contracts from generalist competitors. |
| Geographic Expansion | India PLI scheme localization and BIS certification open software export incentives. |
| Platform Integration | 5G MEC runtime engines enable industrial IoT application development at the edge. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise sales cycles for regulated buyers. |
| Product Launch | Generative AI-assisted code generation compresses specification-to-deployment pipelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged CTOs, IT procurement officers, platform engineers, and integration specialists across enterprise, mid-market, and startup segments. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie mobile deployment data, and EU regulatory filings. Bottom-up deployment estimates triangulated against top-down IT spending benchmarks.
Segment-weighting across deployment architecture, end-user type, solution abstraction level, and technology platform shaped value projections. Cross-platform and mobile-based technologies received differentiated growth assumptions based on workforce mobility convergence. CAGRs derived from historical adoption curves, regulatory milestone timelines, and vendor revenue disclosures. Model inputs included developer shortage indices, FedRAMP authorization backlogs, and EU AI Act implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for generative AI code generation would alter the outlook if hallucination rates or security vulnerabilities stall enterprise deployment. Forecasts reflect assumptions about regulatory timeline adherence and hyperscaler bundling persistence. Practitioners should monitor EU AI Act enforcement severity and FedRAMP queue clearance rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Order Management Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Global Process Mining Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Performing Arts Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
High Education Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
Client Virtualization Software Market
Software & Services
United Kingdom HR Payroll Software Market
Software & Services
Bankruptcy Software Market