
 Global Cinema Software Market | 2026-2036
Global Cinema Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cinema Software Market Foresight
Platform licensing is rewriting margin distribution across the cinema technology stack. Vista Entertainment Solutions leverages its vertical integration across point-of-sale and loyalty modules to sustain premium positioning. GDC Technology anchors its competitive stance through hardware-software bundling in Asia-Pacific projection networks. CenterEdge Software differentiates via specialized tools for family entertainment centers and boutique cinema circuits.
Cinema software encompasses integrated digital systems managing ticketing transactions, content distribution, audience analytics, and concession operations through centralized or distributed architectures. These platforms typically process encrypted DCP (Digital Cinema Package) key delivery messages, synchronize showtime metadata with TMS (Theater Management Systems), and aggregate real-time occupancy data across multiplex portfolios. Cloud-based deployment leads solution architecture as theater chains prioritize remote accessibility and reduced on-site IT overhead, while SaaS models capture expanding margin pools through recurring revenue structures. Ticketing software retains the largest addressable base given its universal necessity, though analytics platforms represent the fastest-expanding category as exhibitors pursue dynamic pricing and audience segmentation capabilities.
FCC guidelines govern wireless transmission protocols for in-theater content delivery in the United States, while GDPR and the EU AI Act constrain customer data utilization across European exhibition networks. India's TRAI framework influences digital distribution infrastructure standards that software vendors must accommodate for theatrical release compliance. Stakeholders should monitor evolving data localization mandates and encryption certification requirements as regulatory fragmentation intensifies across key cinema markets.
Market Dynamics
Cloud-native architectures are compressing deployment cycles across theater chains, forcing legacy on-premise vendors to restructure pricing models around recurring SaaS revenue streams rather than perpetual licenses.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European exhibitors face binding requirements for customer data handling, driving replacement of legacy analytics modules with certified platforms.
- India's theater digitization wave:Regional language content distribution networks require localized TMS integration, expanding procurement of multilingual software suites.
- Edge computing architectures:Real-time occupancy sensors and dynamic pricing engines demand distributed processing nodes at multiplex sites.
Market Restraints
- Input cost volatility in semiconductor supply:TMS hardware dependencies create margin pressure when chip foundry capacity tightens.
- Regulatory friction from data localization mandates:Russia, China, and Indonesia require sovereign server placement, fragmenting vendor infrastructure strategies.
- Substitution threat from white-label platforms:Large chains develop in-house ticketing stacks, eroding third-party license volumes.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Vietnam and Philippines multiplex buildouts lack integrated loyalty-concession systems, creating greenfield deployment potential.
- Saudi Arabia's entertainment sector liberalization:Public Investment Fund theater investments mandate Western-standard software procurement.
- Convergence of AI-driven personalization with DCP key management:Predictive content scheduling engines unlock new licensing tiers for analytics vendors.
Industry Challenges
- Cybersecurity certification timelines:Common Criteria and FIPS 140-2 validation for encryption modules delays product launches by 8-14 months.
- Integration complexity with legacy POS hardware:Proprietary protocols from 2010-era concession systems resist API standardization, inflating implementation costs.
- Talent scarcity in cinema-specific DevOps:DCP key delivery message protocols and TMS synchronization require niche expertise rarely found in general software engineering pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cinema Software Market |
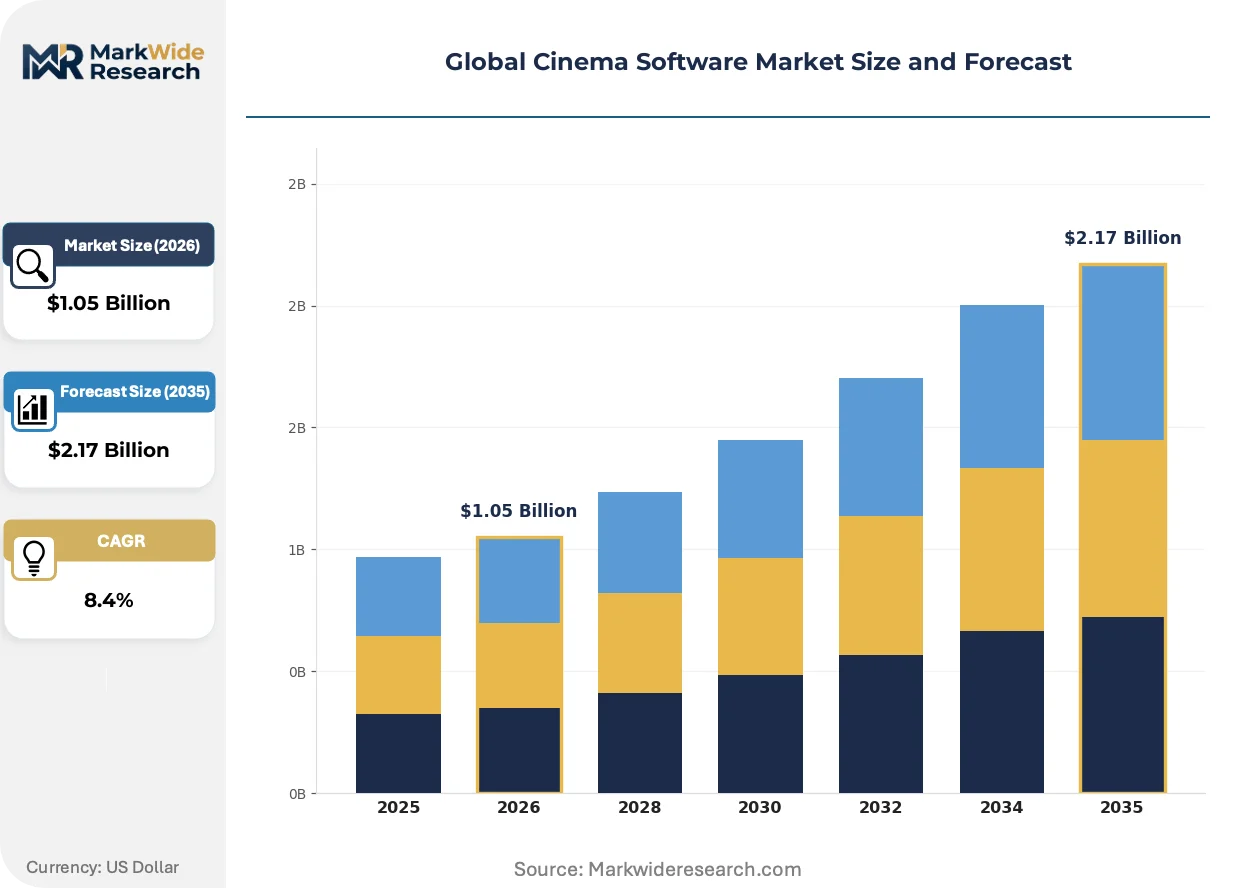
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services Solution Type: Ticketing Software, Content Management, Analytics Platforms, Advertising Management, Customer Engagement Application: Cinema Chains, Independent Theaters, Multiplexes, Drive-In Theaters, Film Festivals End User: Theater Operators, Film Distributors, Event Organizers, Marketing Agencies, Venue Managers |
| Companies Covered | Vista Entertainment Solutions, GDC Technology, CenterEdge Software, NCR Corporation, Veezi, RTS, BQT Solutions, USL Cinema, Embassy Cinema Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cinema Software Market Shifts & Advancements
Artificial intelligence inference engines are embedding directly into theater management workflows, compressing the latency between audience behavior detection and pricing algorithm execution.
Dynamic pricing algorithms are migrating from batch-processed overnight updates to real-time seat-level adjustments based on demand elasticity models. Mid-size circuits in Brazil and Mexico pilot these systems during blockbuster release windows. The shift is compressing revenue leakage from unsold inventory while demanding upgraded cloud bandwidth at individual sites.
India's TRAI framework is mandating interoperable digital distribution standards for theatrical content, forcing software vendors to decouple proprietary TMS architectures from specific projector hardware. This regulatory pressure is fragmenting previously bundled offerings and opening API ecosystems for third-party analytics plugins. Domestic exhibitors gain negotiating leverage against locked-in vendor relationships.
Subscription-based procurement models displace perpetual license purchases among North American and European circuits, unbundling implementation services from core platform fees. Buyers now treat cinema software as operational expenditure rather than capital investment, compressing vendor cash conversion cycles. This pattern is most pronounced among private equity-backed theater portfolios optimizing EBITDA metrics.
Global Cinema Software Market Segmentation
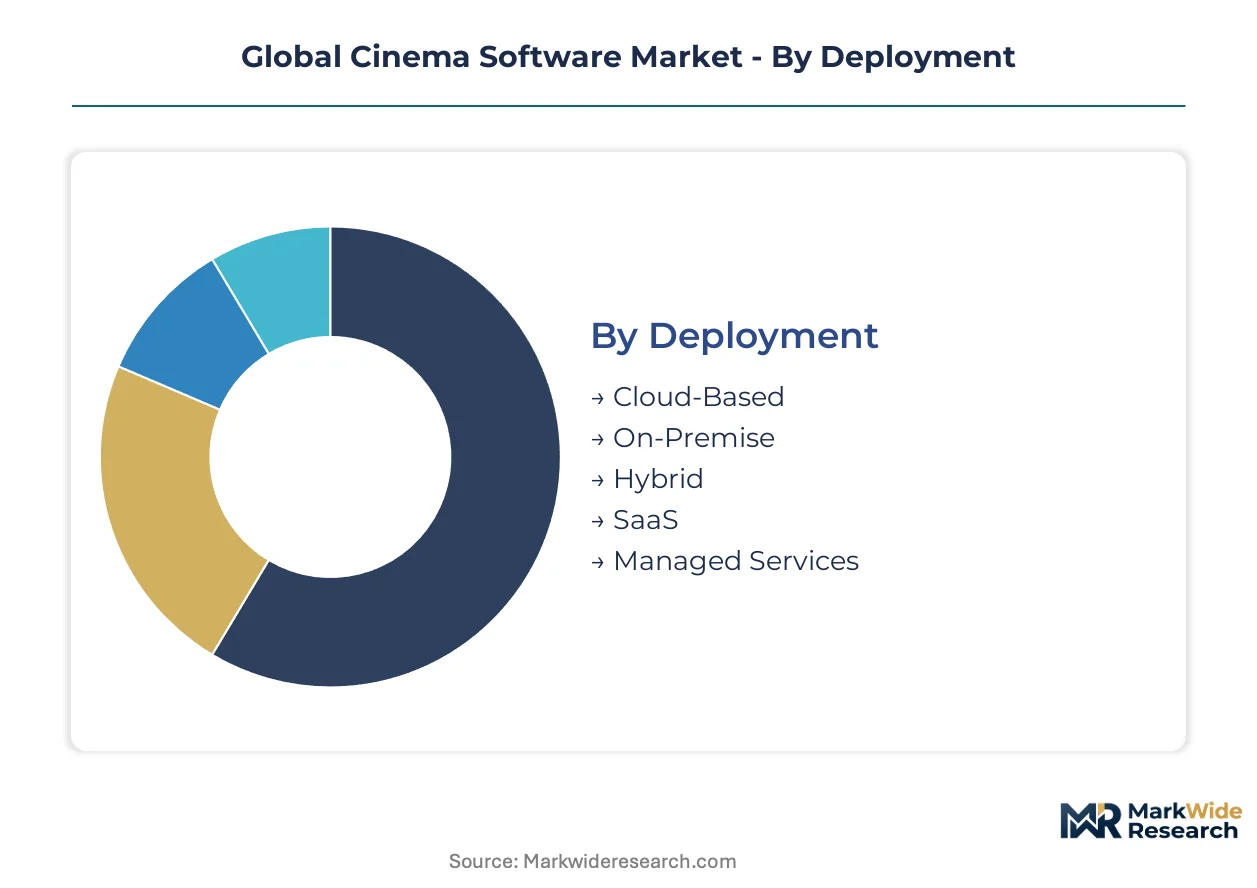
Cinema software procurement patterns diverge sharply across deployment architectures and operational scales. Theater chains prioritize integration depth while independent exhibitors minimize upfront capital exposure. Understanding these segment boundaries clarifies vendor positioning and margin capture opportunities across the technology stack.
Deployment:
Cost tier structures the deployment landscape, separating capital-intensive ownership from operational expenditure models.
- Cloud-Based:Remote server architectures eliminate on-site hardware maintenance and enable real-time synchronization across multiplex portfolios. Demand concentrates among Southeast Asian chains building greenfield circuits where IT infrastructure investment is deferred. GDPR and EU AI Act compliance requirements accelerate replacement of legacy systems in Germany and France.
- SaaS:Subscription licensing converts perpetual software purchases into recurring revenue relationships with predictable cash flow profiles. North American private equity-backed theater portfolios favor this structure for EBITDA optimization. API extensibility allows third-party analytics modules to integrate without core platform replacement.
- On-Premise:Local server installations persist in markets with unreliable connectivity or strict data sovereignty requirements.
- Hybrid:Mixed architectures balance sensitive data local processing with cloud-based analytics aggregation.
- Managed Services:Outsourced operational responsibility appeals to smaller circuits lacking specialized DevOps capacity.
Cloud-Based holds installed capacity. SaaS is rotating up the share rankings.
Solution Type:
Application functionality determines where software vendors capture margin across the exhibition workflow.
- Ticketing Software:Transaction processing engines handle seat selection, payment authorization, and DCP key delivery message generation. Universal necessity across all theater types sustains the largest addressable base. India's theater digitization wave drives localized multilingual interface procurement.
- Analytics Platforms:Audience behavior inference engines enable dynamic pricing and concession bundling optimization. Brazilian and Mexican mid-size circuits pilot real-time demand elasticity models during blockbuster windows. Predictive content scheduling unlocks premium licensing tiers.
- Content Management:TMS synchronization and DCP distribution coordination ensure projection reliability.
- Advertising Management:Pre-show inventory optimization and third-party network integration maximize ancillary revenue.
- Customer Engagement:Loyalty program orchestration and personalized communication workflows reduce churn.
Ticketing Software dominates transaction volume. Analytics Platforms are climbing the fastest.
Application:
Customer type scale dictates integration complexity and procurement negotiation leverage.
- Multiplexes:Large-format circuits require centralized portfolio management across dozens of screens with real-time occupancy aggregation. Saudi Arabia's Public Investment Fund theater investments mandate Western-standard software procurement with full feature depth. Edge computing nodes at individual sites support dynamic pricing algorithm execution.
- Cinema Chains:Regional networks balance standardization benefits against local market adaptation requirements.
- Independent Theaters:Single-screen or small-circuit operators prioritize cost minimization over advanced functionality.
- Drive-In Theaters:Seasonal operations and unique audio distribution needs shape specialized software requirements.
- Film Festivals:Temporary venue configurations demand rapid deployment and strike capabilities.
Multiplexes anchor enterprise licensing value. Cinema Chains are expanding procurement fastest.
End User:
Supply concentration varies across stakeholder types with divergent technical requirements and budget authority.
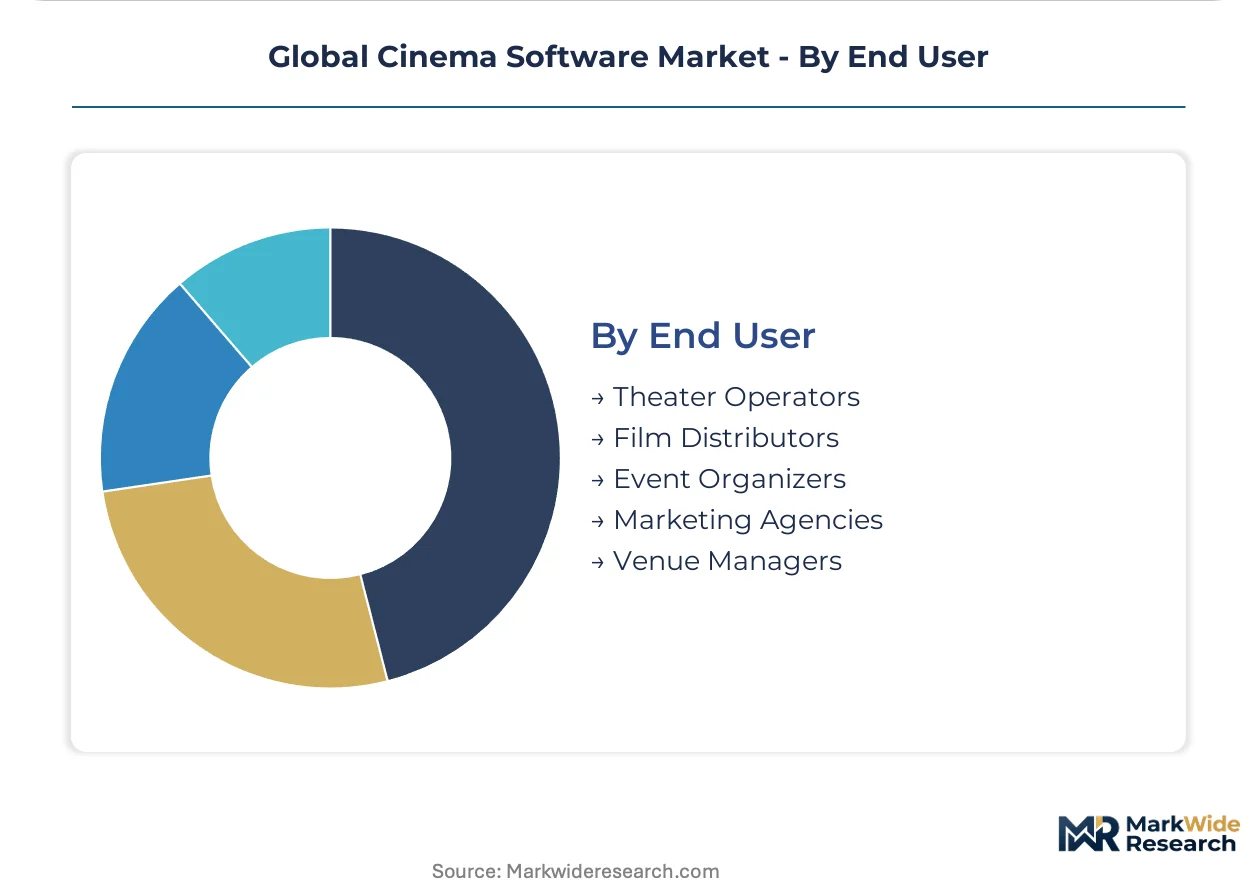
- Theater Operators:Exhibition companies own core platform procurement decisions and integration responsibility. FCC guidelines in the United States govern their wireless transmission protocols for in-theater content delivery. Cybersecurity certification timelines for Common Criteria and FIPS 140-2 validation delay product launches.
- Film Distributors:Content owners influence TMS compatibility requirements and KDM security standards.
- Event Organizers:Temporary programming needs drive short-term licensing and rapid configuration demands.
- Marketing Agencies:Third-party promotional partners require audience data access and campaign measurement tools.
- Venue Managers:Facility-focused operators prioritize scheduling efficiency and staff coordination features.
Theater Operators control primary procurement spend. Film Distributors are gaining influence over technical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States exhibitors deploy cinema software primarily for dynamic pricing and loyalty optimization, while Indian operators prioritize multilingual TMS integration for regional content distribution. This consumption-mix differential shapes vendor feature roadmaps and localization investments across geographies.
United States
FCC guidelines govern wireless transmission protocols for in-theater content delivery, mandating specific spectrum allocations for encrypted DCP distribution. Theater circuits in Los Angeles and New York Metro pilot real-time seat-level pricing algorithms during blockbuster release windows. Cybersecurity certification timelines for Common Criteria and FIPS 140-2 validation delay product launches by 8-14 months.
India
TRAI mandates interoperable digital distribution standards that force software vendors to decouple proprietary TMS architectures from specific projector hardware. Maharashtra and Karnataka multiplex buildouts drive procurement of cloud-based ticketing platforms with localized language interfaces. Domestic exhibitors gain negotiating leverage against locked-in vendor relationships as API ecosystems open for third-party analytics plugins.
Germany
GDPR and the EU AI Act impose binding requirements for customer data handling, compelling replacement of legacy analytics modules with certified platforms. Berlin and Munich theater chains accelerate adoption of SaaS deployment models to ensure compliance with evolving data governance frameworks. Edge computing nodes at individual sites support real-time occupancy processing while maintaining sovereign data controls.
Saudi Arabia
Public Investment Fund theater investments mandate Western-standard software procurement with full feature depth for new entertainment districts. Riyadh and Jeddah multiplex developments lack legacy infrastructure, creating greenfield deployment opportunities for integrated loyalty-concession systems. The country's entertainment sector liberalization drives demand for centralized portfolio management across dozens of screens.
Brazil
ANVISA frameworks influence digital distribution infrastructure standards that software vendors must accommodate for theatrical release compliance. São Paulo and Rio de Janeiro mid-size circuits pilot real-time demand elasticity models during blockbuster windows. Cloud bandwidth upgrades at individual sites enable dynamic pricing algorithm execution with reduced latency.
Global Cinema Software Market Competitive Landscape
Capability concentration sits with specialized vendors possessing deep TMS synchronization expertise; scale advantage sits with diversified technology conglomerates offering bundled hardware-software portfolios. The market structure reflects a tiered competitive dynamic where vertical integration across point-of-sale and loyalty modules sustains premium positioning for integrated providers, while hardware-software bundling anchors competitive stance in Asia-Pacific projection networks. Two strategic archetypes dominate: full-stack platform licensors and specialized boutique circuit specialists. M&A activity concentrates on analytics module acquisitions, while geographic expansion through localized TMS partnerships represents the second dominant competitive move.
Within the specialized software tier, Vista Entertainment Solutions exemplifies vertical integration across point-of-sale and loyalty modules, while GDC Technology occupies a position anchored through hardware-software bundling in Asia-Pacific markets. CenterEdge Software represents the boutique circuit specialist archetype, serving family entertainment centers with differentiated toolsets. These three entities collectively illustrate the competitive positioning spectrum from enterprise-scale platform licensing to niche application specialization.
| Leading Market Players |
|---|
| Vista Entertainment Solutions |
| GDC Technology |
| CenterEdge Software |
| NCR Corporation |
| Veezi |
| RTS |
| BQT Solutions |
| USL Cinema |
| Embassy Cinema Software |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber optic cable routes carrying encrypted DCP key delivery traffic between Los Angeles and Singapore anchor cost dynamics for cloud-native cinema software vendors, concentrating pricing power among SaaS providers with sovereign server placement while fragmenting margin capture for on-premise integrators facing data localization mandates.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise procurement among North American and European multiplex chains, displacing perpetual licensing structures. Price differentiation rests on GDPR certification tier and API extensibility depth, with premium tiers commanding substantial uplifts for EU AI Act-compliant analytics modules. Pricing pressure stems from white-label platform substitution as large chains develop in-house ticketing stacks. Independent theaters exhibit acute price sensitivity, while Saudi PIF-backed circuits prioritize feature completeness over cost minimization.
Supply Chain Analysis
Foxconn and Pegatron manufacturing concentration in Taiwan and mainland China controls server hardware provisioning for theater management systems, with secondary assembly nodes in Vietnam and Mexico. Semiconductor sourcing draws from South Korean memory foundries and Taiwanese logic chip fabricators. Single-source vulnerability in DCP encryption module production creates supply chain risk. Distribution runs through regional systems integrators with certified DevOps capacity for TMS synchronization and KDM protocol management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cinema software markets reward defensive moats built on switching costs, where TMS integration complexity and DCP key management certification timelines lock exhibitors into incumbent relationships.
For Market Incumbents: Build switching-cost moats through deeper TMS-loyalty module integration and accelerated FIPS 140-2 certification pipelines. Threats from white-label in-house development by AMC and Cineworld demand preemptive API ecosystem expansion. Capacity addition in Saudi Arabia and Vietnam secures greenfield anchor contracts before competitor entry. For New Entrants and Emerging Players: Boutique family entertainment centers in the US Southeast and drive-in theater digitization represent the most penetrable entry points with minimal incumbent saturation. Saudi Arabia's entertainment district buildouts lack legacy infrastructure, enabling full-stack platform deployment without migration friction. Go-to-market through certified systems integrators with existing theater operator relationships bypasses direct enterprise sales cycle complexity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analytics module specialists with predictive content scheduling capabilities over commoditized ticketing infrastructure. Long-term viability hinges on AI-driven personalization convergence with DCP security protocols. Acquisition targets should demonstrate EU AI Act certification progress and Southeast Asian TMS partnerships. Watch for inflection in theater operator RFP volumes from Vietnam and Philippines multiplex buildouts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified TMS-loyalty-concession architectures reduce implementation friction for Saudi PIF theater investments. |
| Acquisition of Specialist Firm | Predictive analytics module purchases accelerate AI-driven personalization roadmaps for dynamic pricing vendors. |
| Geographic Expansion | Localized TMS partnerships in Vietnam and Philippines capture greenfield multiplex procurement cycles. |
| Strategic Partnership | Systems integrator alliances bypass direct sales complexity for independent theater penetration. |
| Product Launch | EU AI Act-certified analytics platforms unlock replacement demand from GDPR-constrained German exhibitors. |
Research Methodology
A standing panel of theater operations directors, cinema software CTOs, TMS integration specialists, and film distribution technology leads provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC filings of publicly traded exhibition chains, TRAI regulatory circulars, and EU AI Act implementation guidance documents. Bottom-up deployment model sizing and top-down market aggregation triangulated volume estimates across the analysis window.
Scenario-bracketing framed the forecast architecture around cloud adoption velocity, regulatory compliance cost trajectories, and regional theater construction pipelines. Segmentation dimensions modeled include deployment architecture, solution type, application scale, and end-user procurement authority. CAGRs were derived from fitted growth curves anchored to historical SaaS transition patterns and projected digitization waves. Industry-specific inputs incorporated DCP key delivery message protocol evolution and edge computing node deployment timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting private equity theater portfolio valuations or semiconductor foundry capacity constraints would shift the trajectory. Forecasts reflect documented assumptions regarding GDPR enforcement intensity and TRAI interoperability mandate adherence. Quarterly review of theater construction permit filings in Saudi Arabia, Vietnam, and the Philippines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Metal Fabrication Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Business Analytics Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Production Optimization Software Market
Software & Services
Real Estate Software Market
Software & Services
Workstation Software Market
Software & Services
Session Support Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Computer Backup Software Market
Software & Services
Multiphysics Software Market
Software & Services
Chromatography Data System (CDS) Software Market
Software & Services
Global Software Resellers Market
Software & Services
Pharmacy Billing Software Market
Software & Services
Data Migration Software Services Market
Software & Services
Low Code Development Platform Market