
 HR Management Software (Personnel and Organization) Market | 2026-2036
HR Management Software (Personnel and Organization) Market Size, Share, and Industry Trends Forecast 2026-2036
HR Management Software (Personnel and Organization) Market Foresight
ISO 27001 certification is unwinding the competitive landscape, forcing smaller vendors to absorb compliance costs or exit procurement cycles. Workday leverages its native cloud architecture to anchor enterprise accounts across North America and Western Europe. SAP sustains dominance through deep ERP integration that locks in multinational manufacturing clients. Oracle competes by extending its database-layer advantages into unified workforce analytics stacks.
HR Management Software (Personnel and Organization) encompasses cloud-native and on-premise platforms that automate employee lifecycle workflows, compensation administration, and organizational design, typically integrating REST APIs with enterprise directory services and time-clock hardware. Core HR and Payroll Solutions command the largest installed base, while Talent Management segments attract disproportionate R&D investment as skills-based hiring protocols displace credential-centric screening. Cloud-Based deployment is displacing on-premise installations fastest among mid-market buyers, though Hybrid configurations retain stronghold status in regulated finance and defense sectors where data residency rules fragment cloud migration timelines.
FCC guidelines on communications privacy intersect with HIPAA workforce training mandates and SEC disclosure rules on human capital management, collectively elevating audit-trail and encryption standards across vendor roadmaps. The EU AI Act adds extraterritorial compliance burdens for any platform processing European employee data, forcing architectural redesigns of automated screening and sentiment-analysis modules. Buyers must weigh vendor concentration risk against the integration cost of best-of-breed point solutions as platform consolidation accelerates.
Market Dynamics
Cloud-native architectures are compressing deployment timelines from quarters to weeks, forcing incumbent vendors to dismantle monolithic codebases or surrender mid-market accounts to agile competitors. The EU AI Act's extraterritorial reach compounds this pressure by mandating algorithmic transparency for any platform touching European employee data.
Growth Catalysts
- GDPR Article 35:Mandatory data protection impact assessments for automated HR decisions are expanding addressable spend on audit-ready platforms across German and French enterprise accounts.
- Skills-based hiring protocols:Healthcare and logistics employers are replacing credential filters with competency assessments, requiring talent management modules that map micro-credentials to role requirements.
- Mid-market cloud migration:US healthcare systems with 500-5,000 employees are abandoning on-premise payroll systems for SaaS alternatives that integrate with existing EHR infrastructure.
Market Restraints
- ISO 27001 certification costs:Smaller vendors face six-figure annual compliance expenditures that consume 15-20% of operating budgets, triggering consolidation or exit from RFP cycles.
- Data residency fragmentation:German works councils and French labor inspectors enforce strict server-location rules that fragment cloud architectures and extend implementation timelines.
- Legacy ERP entrenchment:Manufacturing multinationals with decades-old SAP or Oracle deployments face seven-figure switching costs that freeze competitive displacement.
Strategic Opportunities
- EU AI Act compliance services:Vendors can capture recurring revenue by packaging algorithmic audit tools and documentation automation for platforms processing European workforce data.
- Healthcare interoperability:REST API bridges between HR platforms and Epic or Cerner EHR systems open greenfield accounts among US hospital networks consolidating vendor relationships.
- Hybrid deployment architectures:Defense contractors and Swiss private banks require on-premise payroll engines with cloud analytics layers, creating premium pricing tiers for segmented solutions.
Industry Challenges
- AI/ML engineering scarcity:Vendors struggle to hire data scientists capable of building explainable screening algorithms that satisfy French CNIL and German DPA audit standards.
- Multi-jurisdiction payroll complexity:Platforms must maintain real-time compliance with divergent tax codes across Belgian regional authorities, Spanish autonomous communities, and Italian provincial variations.
- Sentiment analysis module redesign:Automated mood-detection features require architectural overhaul to document decision logic for EU AI Act conformity assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HR Management Software (Personnel and Organization) Market |
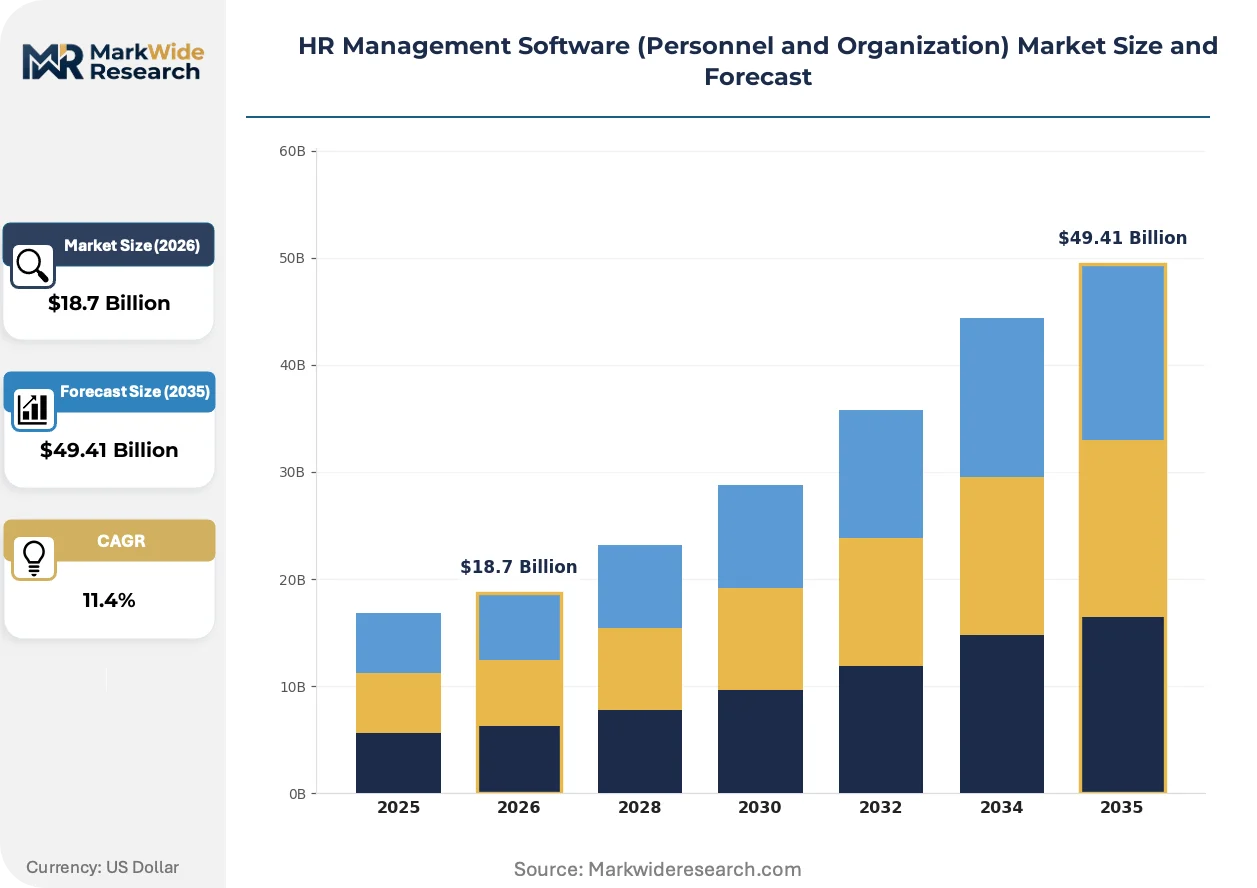
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core HR, Talent Management, Payroll Solutions, Workforce Management Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Small Enterprises, Medium Enterprises, Large Enterprises, Non-Profit Organizations Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Workday, SAP, UKG, Oracle, ADP, Paycom, Paylocity, Ceridian, BambooHR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HR Management Software (Personnel and Organization) Market Shifts & Advancements
Generative AI capabilities are embedding into workforce analytics stacks, compressing the cycle from raw HR data to executive decision support. Vendors race to deploy these tools while navigating emerging algorithmic accountability frameworks.
Embedded large language models are fragmenting traditional BI dashboards by enabling natural-language workforce queries that bypass predefined report templates. Mid-market healthcare employers in the US and Germany are piloting these interfaces for manager self-service. The technology is fragmenting incumbent vendors' analytics revenue by commoditizing structured reporting and shifting value toward conversational interfaces.
The EU AI Act's risk-classification system for employment algorithms is forcing vendors to document training data provenance and model drift metrics. Platforms processing high-risk automated screening or performance scoring must maintain technical files for market surveillance authorities. German and French enterprise buyers now require these compliance artifacts as standard procurement criteria, compressing sales cycles for prepared vendors and disqualifying laggards.
Subscription pricing for point solutions is yielding to bundled platform contracts as buyers consolidate vendor relationships to reduce integration overhead. US hospital networks and German automotive suppliers now favor unified suites over best-of-breed talent management tools. This concentration is most visible among mid-market employers with limited IT integration resources, where procurement teams prioritize single-vendor accountability over functional depth.
HR Management Software (Personnel and Organization) Market Segmentation
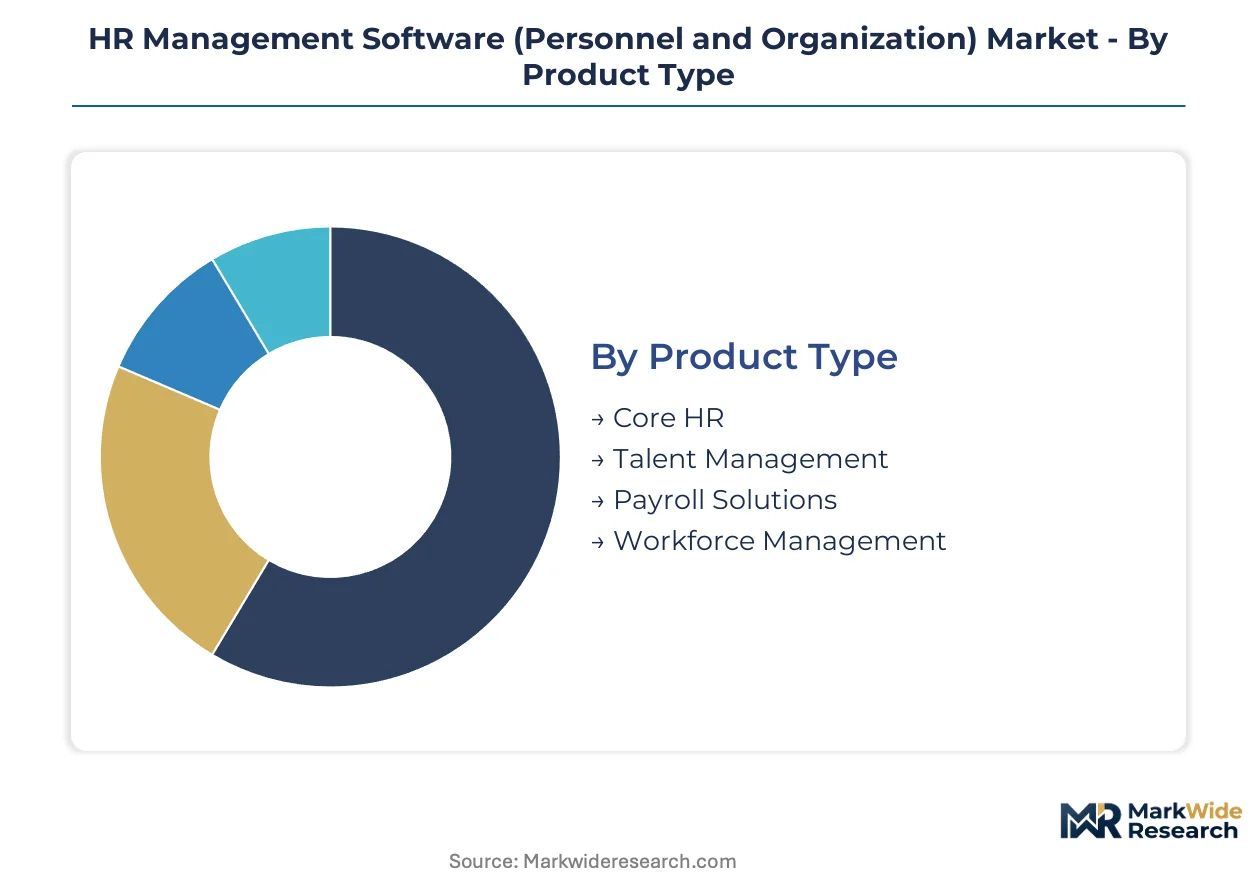
Segmentation in HR management software reveals how substitution pressures reshape procurement priorities. Cloud-native platforms displace legacy installations while skills-based hiring protocols reconfigure talent module specifications across buyer tiers.
Product Type:
Substitution pressure runs strongest against credential-centric screening tools as skills-based hiring protocols displace traditional degree filters. German automotive suppliers and US hospital networks now demand competency-mapping architectures that legacy performance modules cannot retrofit.
- Core HR:Employee lifecycle workflows, directory services, and organizational charting form the foundational layer. Manufacturing multinationals in Germany and France anchor procurement here due to works council reporting mandates and GDPR audit requirements.
- Talent Management:Micro-credential mapping, succession planning, and skills-based assessment engines attract disproportionate R&D investment. US healthcare systems with 500-5,000 employees pilot these modules to replace credential filters with competency protocols.
- Payroll Solutions:Multi-jurisdiction tax engines for Belgian regional authorities, Spanish autonomous communities, and Italian provincial variations.
- Workforce Management:Time-clock integration, shift optimization, and labor compliance dashboards for logistics and retail operations.
Core HR retains volume leadership; Talent Management holds the steepest expansion curve.
Deployment:
Cost tier stratification separates enterprise buyers willing to absorb hybrid complexity from mid-market accounts demanding pure SaaS economics. Defense contractors and Swiss private banks pay premiums for segmented architectures that cloud-native vendors struggle to replicate.
- Cloud-Based:Native multi-tenant architectures compress implementation timelines from quarters to weeks. Mid-market healthcare employers in the US and Germany accelerate migration here to integrate with Epic or Cerner EHR infrastructure.
- Hybrid:On-premise payroll engines with cloud analytics layers serve data residency requirements. French labor inspectors and German works councils enforce strict server-location rules that fragment pure cloud adoption.
- On-Premise:Monolithic legacy installations persisting in regulated finance and defense sectors.
- Mobile:Manager self-service interfaces and field workforce applications for distributed operations.
Cloud-Based deployment captures the fastest share gains; Hybrid configurations command premium pricing persistence.
End User:
Customer type determines integration complexity tolerance and compliance artifact requirements. Large enterprises demand algorithmic transparency documentation for EU AI Act conformity assessments that smaller buyers cannot evaluate.
- Large Enterprises:Multinational manufacturing clients require unified workforce analytics stacks with REST API bridges to SAP or Oracle ERP systems. German automotive suppliers and US hospital networks consolidate vendor relationships here to reduce integration overhead.
- Medium Enterprises:Organizations with 500-5,000 employees favor bundled platform contracts over best-of-breed point solutions. Limited IT integration resources drive procurement teams toward single-vendor accountability.
- Small Enterprises:Lightweight SaaS configurations with minimal customization requirements.
- Non-Profit Organizations:Grant-funded implementations prioritizing cost containment over functional depth.
Large Enterprises dominate current procurement value; Medium Enterprises are expanding most quickly.
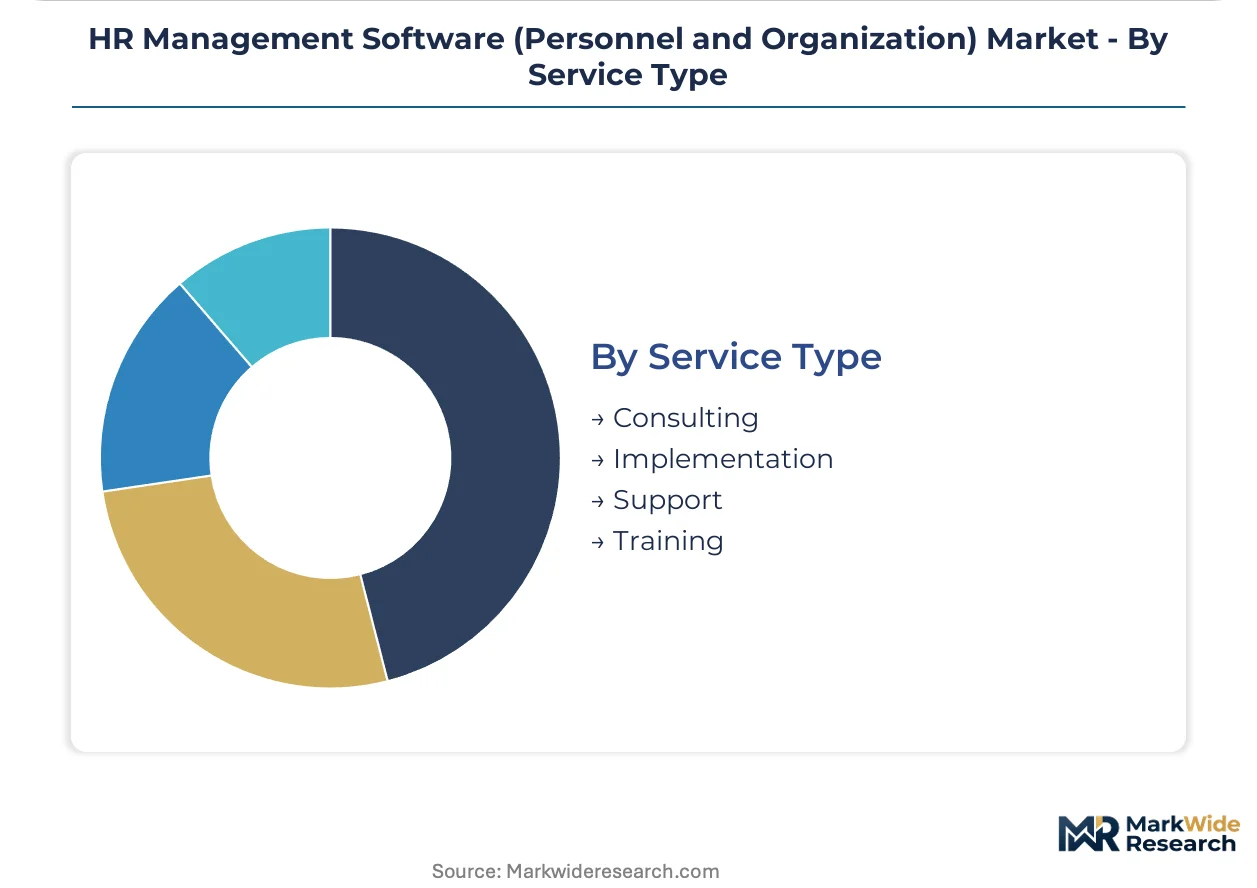
Service Type:
Margin concentration follows implementation complexity and recurring compliance burdens. EU AI Act technical file preparation and algorithmic audit documentation create sticky revenue streams distinct from commoditized support contracts.
- Implementation:System configuration, data migration, and integration with enterprise directory services and time-clock hardware. French CNIL and German DPA audit standards elevate project scope for platforms processing European workforce data.
- Consulting:Organizational design advisory and change management for HR transformation programs.
- Support:Tiered response contracts with escalation paths for payroll-critical failures.
- Training:Administrator certification and end-user adoption programs for new module rollouts.
Implementation services retain revenue leadership; Consulting holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act and GDPR Article 35 mandates are redirecting procurement budgets toward audit-ready platforms in Germany, France, and the UK. US healthcare systems accelerate cloud migration to integrate HR platforms with Epic and Cerner EHR infrastructure. Japanese manufacturers and Indian IT services exporters are adopting skills-based hiring protocols that reshape talent module specifications.
United States
Mid-market healthcare employers with 500-5,000 employees drive SaaS migration to unify payroll with existing EHR systems. HIPAA workforce training mandates intersect with SEC human capital disclosure rules, elevating encryption and audit-trail standards. Hospital networks in the Midwest and Southeast consolidate vendor relationships to reduce integration overhead.
Germany
Automotive suppliers and manufacturing multinationals anchor Core HR procurement due to works council reporting mandates. The Federal Data Protection Act and GDPR Article 35 enforcement expand addressable spend on platforms with algorithmic transparency documentation. Industrial clusters in Bavaria and Baden-Württemberg pilot skills-based assessment engines for competency-mapping architectures.
France
CNIL audit standards and strict server-location rules fragment pure cloud adoption, sustaining hybrid deployment demand. Labor inspectors enforce data residency requirements that extend implementation timelines for multinational employers. The Île-de-France region concentrates procurement activity among financial services and luxury goods headquarters requiring payroll engines with cloud analytics layers.
United Kingdom
Post-Brexit data protection frameworks maintain GDPR-equivalent standards while creating divergence in cross-border workforce data flows. Financial services firms in the City of London and Canary Wharf demand REST API bridges to legacy ERP systems. NHS trusts pilot generative AI workforce analytics while navigating emerging algorithmic accountability requirements.
Japan
Labor shortages in manufacturing and logistics accelerate adoption of automated scheduling and shift optimization modules. METI guidelines on human capital disclosure elevate workforce analytics investment among listed enterprises. The Kanto region around Tokyo concentrates demand from automotive and electronics headquarters integrating HR platforms with lean production systems.
HR Management Software (Personnel and Organization) Market Competitive Landscape
Player mix skews toward enterprise platform vendors with native cloud architectures and deep ERP integration capabilities. The vendor base concentrates around three tiers: multinational suite providers anchoring large enterprise accounts, mid-market specialists capturing healthcare and professional services verticals, and regional players serving compliance-intensive European markets. Dominant competitive moves include M&A to acquire skills-based assessment technology and strategic partnerships with EHR and directory service providers.
Within the enterprise suite tier, Workday and SAP exemplify divergent architectural philosophies—cloud-native multi-tenancy versus deep ERP integration—while Oracle occupies a position leveraging database-layer advantages into unified analytics stacks. Among mid-market specialists, UKG and Paylocity represent the SaaS-native archetype targeting healthcare employers with rapid deployment timelines. The competitive terrain rewards vendors who package EU AI Act compliance services and algorithmic audit documentation as recurring revenue streams distinct from core platform subscriptions.
| Leading Market Players |
|---|
| Workday |
| SAP |
| UKG |
| Oracle |
| ADP |
| Paycom |
| Paylocity |
| Ceridian |
| BambooHR |
| Others |
Supply & Pricing Matrix
Multi-tenant cloud infrastructure economics compress unit costs at scale, concentrating supply power among vendors operating datacenters across Germany, Ireland, and the US while establishing price floors for smaller competitors lacking comparable utilization rates. This scale dynamic feeds directly into procurement negotiations, as enterprise buyers leverage volume commitments against vendors absorbing ISO 27001 certification and EU AI Act compliance expenditures.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 27001 and GDPR Article 35 audit-ready platforms commanding premium subscriptions against uncertified alternatives. SaaS-tiered pricing dominates, stratifying across enterprise, mid-market, and small-business tiers with per-employee-per-month structures. Cost compression in the mid-market tier is intensifying because healthcare employers with 500-5,000 employees demand Epic and Cerner EHR integration without absorbing implementation premiums. Small enterprises exhibit highest price sensitivity, while defense contractors and Swiss private banks accept premium hybrid-deployment rates for data residency guarantees.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and congestion at Rotterdam and Hamburg ports elevate inbound logistics costs for time-clock hardware and on-premise server components sourced from Taiwan and China. Software supply concentrates in the US, Germany, and Ireland, with cloud infrastructure drawing from hyperscaler datacenter networks in Frankfurt, Dublin, and Virginia. Single-source vulnerability runs through REST API dependency on Microsoft Azure Active Directory and legacy SAP connector modules. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and regional value-added resellers serving French and German compliance-intensive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of data scientists capable of building explainable AI screening algorithms per French CNIL and German DPA standards constrains vendor expansion and elevates acquisition premiums for compliant engineering teams. This capability gap shapes competitive positioning across all stakeholder archetypes.
For Market Incumbents: Shield enterprise accounts by embedding algorithmic audit documentation and EU AI Act technical file preparation into standard subscription bundles, neutralizing mid-market specialists' deployment speed advantage. Deepen backward integration into skills-based assessment content libraries to reduce reliance on third-party competency-mapping providers. Prioritize certification maintenance investments that smaller vendors cannot replicate at equivalent scale. For New Entrants and Emerging Players: Differentiate on healthcare interoperability, targeting US hospital networks with 500-5,000 employees seeking rapid Epic and Cerner EHR integration without seven-figure switching costs. Penetrate German automotive supplier clusters in Bavaria and Baden-Württemberg with localized works council reporting modules that multinational suite vendors configure slowly. Pursue channel partnerships with regional systems integrators possessing existing healthcare and manufacturing relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with pre-built EU AI Act compliance architectures over those requiring fundamental platform redesigns. Long-term viability hinges on recurring revenue from algorithmic audit services rather than commoditized core HR subscriptions. Monitor French CNIL and German DPA enforcement patterns as inflection indicators for compliance-artifact demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Service Launch | Captures recurring revenue from German and French enterprise buyers mandating algorithmic transparency documentation. |
| Healthcare EHR Integration Partnership | Opens greenfield accounts among US hospital networks consolidating Epic and Cerner vendor relationships. |
| Hybrid Deployment Architecture Development | Commands premium pricing from defense contractors and Swiss private banks requiring on-premise payroll engines. |
| Skills-Based Assessment Content Acquisition | Accelerates competency-mapping capabilities for German automotive suppliers replacing credential-centric screening. |
| Regional Systems Integrator Channel Program | Extends reach into compliance-intensive European markets without direct sales infrastructure investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents to establish vendor positioning and compliance trajectory baselines. Interviews with CTOs, IT procurement officers at US healthcare systems, platform engineers, and integration specialists active in German manufacturing verticals inform deployment timeline and integration complexity assessments. Bottom-up sizing of module-level subscriptions and top-down validation against aggregate vendor disclosures ensure figure consistency across the analysis window.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster throughout the forecast period. CAGRs derive from trend extrapolation of cloud migration rates, compliance expenditure growth, and skills-based hiring protocol adoption curves. Inputs include healthcare employer EHR consolidation patterns and German works council digitization mandates.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement intensity and mid-market healthcare cloud migration continuity; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Server Virtualization Software Market
Software & Services
Creative Software Market
Software & Services
Global Email Management Software Market
Software & Services
Global Technical Illustration Software Market
Software & Services
Media Planning Software Market
Software & Services
Global Content Management Software Market
Software & Services
ITSM Market
Software & Services
Asia-Pacific IT Services Market
Software & Services
Global Business Management Software Market
Software & Services
Admission Management Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Customs Declaration Software Market
Software & Services
Legal Software Market
Software & Services
Machine Translation Software Market
Software & Services
Consignment Software Market
Software & Services
Application Virtualization Market