
 Payroll and HR Software Market | 2026-2036
Payroll and HR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Payroll and HR Software Market Analytics
Direct enterprise sales is tilting toward embedded partnerships with accounting firms and professional employer organizations. ADP leverages its captive PEO channel to sustain renewal rates above industry norms. Paycom anchors its position through in-house development of every payroll module, eliminating third-party dependencies. Workday competes at the upper boundary by extending its financials-to-HR data model into workforce planning.
Payroll and HR software encompasses cloud-native and on-premise platforms that automate wage calculation, tax withholding, benefits enrollment, and labor compliance reporting through configurable rule engines and real-time ledger integration. Its primary commercial purpose is to reduce administrative labor hours while ensuring jurisdictional accuracy across fragmented employment regulations. Cloud-based deployment leads absolute growth as mid-market buyers abandon server maintenance, though hybrid architectures retain share among organizations with sector-specific data residency requirements. By functionality, payroll processing occupies the largest revenue pool, while benefits administration represents the fastest expansion vector as employers absorb rising healthcare complexity.
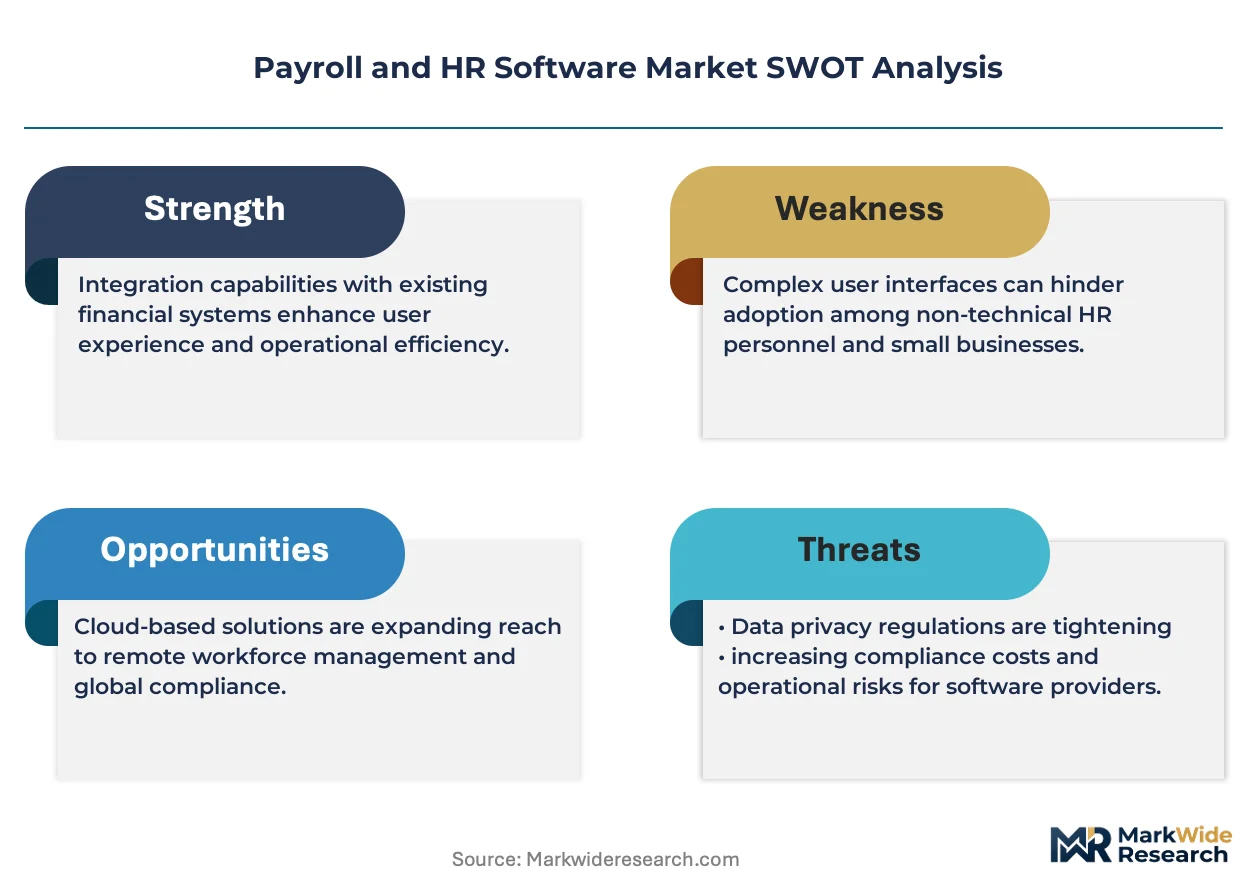
The US Internal Revenue Service, the EU GDPR enforcement network, and India's Ministry of Electronics and Information Technology each impose distinct data localization and audit-trail standards that elevate platform engineering costs. Vendors must architect multi-tenant instances with jurisdiction-specific encryption and retention rules to maintain market access. Stakeholders should monitor how emerging AI wage-auditing tools trigger new fairness and explainability mandates from labor regulators before committing to long-term platform roadmaps.
Market Dynamics
Cloud migration mandates from Germany's Federal Commissioner for Data Protection, France's CNIL, and US state-level privacy laws are forcing vendors to rebuild multi-tenant architectures with jurisdiction-specific encryption layers, elevating engineering costs and consolidating procurement toward compliant platforms.
Growth Catalysts
- GDPR and US State Privacy Laws:Data localization requirements in the European Union and California's CCPA are compelling mid-market enterprises to replace on-premise payroll servers with certified cloud instances.
- Multi-State Tax Complexity:Employers operating across Texas, New York, and Illinois face divergent withholding rules that automated rule engines resolve more efficiently than manual processing.
- API-First Integration:Real-time ledger connectivity between payroll, accounting, and benefits platforms is eliminating batch-processing delays and reconciliation errors.
Market Restraints
- Implementation Cost Concentration:Mid-market buyers in Brazil and Mexico face 18-24 month payback periods for full-suite deployments due to data migration complexity.
- Specialized Talent Scarcity:Shortages of certified Workday and SAP SuccessFactors administrators in Poland and Czech Republic delay rollout timelines.
- Legacy System Entrenchment:Manufacturing and public sector buyers in Japan maintain on-premise payroll due to METI data residency guidelines.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Localization mandates create first-mover advantage for vendors establishing Mumbai and Bangalore data centers.
- AI-Powered Wage Auditing:Machine learning fairness tools intersect with emerging explainability requirements from US Department of Labor guidance.
- Embedded Finance Integration:Earned wage access partnerships with neobanks and fintech platforms open new revenue streams beyond subscription fees.
Industry Challenges
- Cross-Border Data Architecture:Engineering teams must maintain separate encryption key hierarchies for German, French, and US tenant instances without performance degradation.
- Certification Timeline Compression:ISO 27001 and SOC 2 Type II audit cycles now overlap with product release schedules, delaying feature launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payroll and HR Software Market |
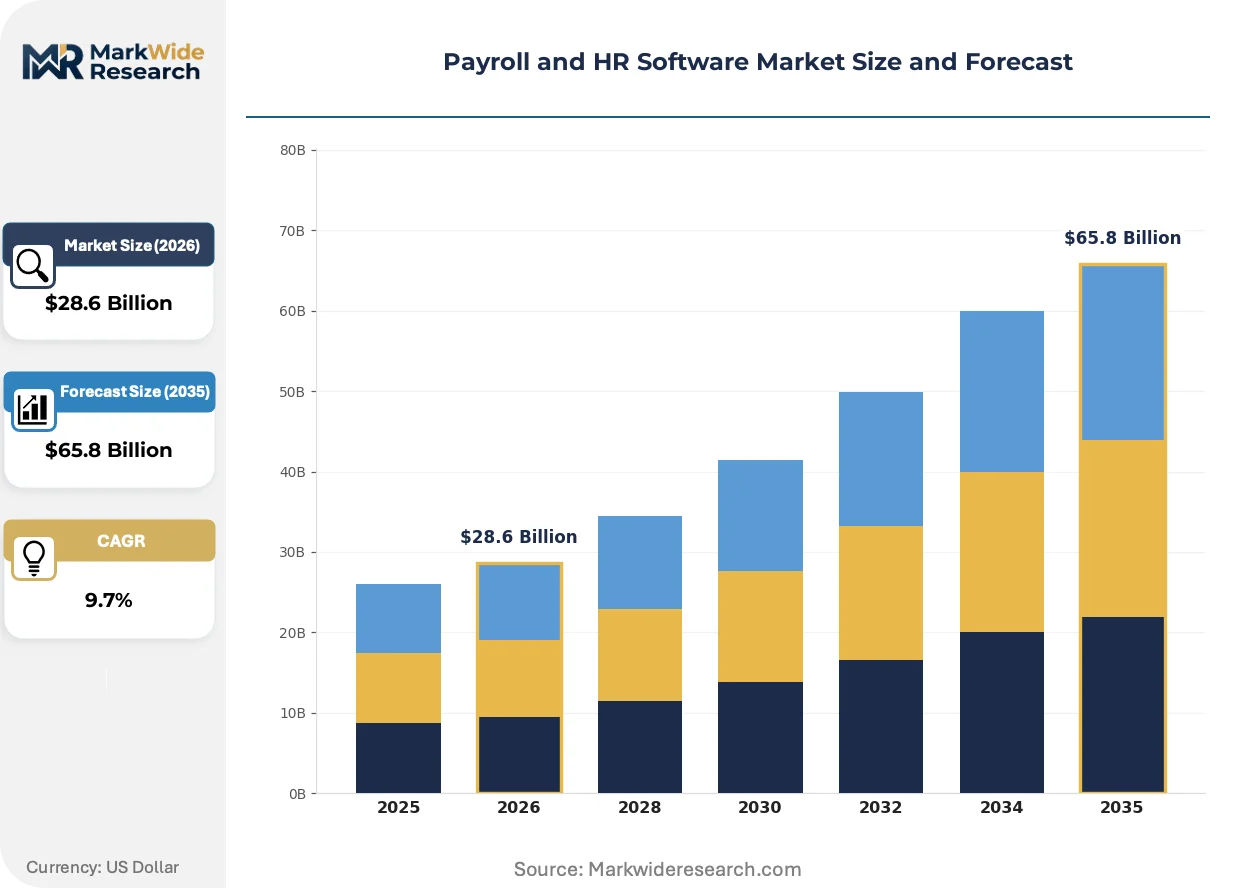
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $65.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Small Businesses, Enterprises, Freelancers, Non-Profits Functionality: Payroll Processing, Employee Tracking, Time & Attendance, Benefits Administration Pricing Model: Subscription, One-Time Fee, Pay-As-You-Go, Freemium |
| Companies Covered | ADP, Paycom, Workday, Paycor, Paylocity, UKG, Paychex, Ceridian, Sage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payroll and HR Software Market Evolving Landscape
Real-time payment rails and artificial intelligence are compressing payroll cycles from biweekly to on-demand while embedding compliance checks directly into transaction flows, eliminating post-hoc audit batches.
Machine learning algorithms trained on historical wage patterns and jurisdictional rule sets are digitizing compliance verification, replacing manual spreadsheet checks. Mid-market HR departments in retail and hospitality are adopting these tools fastest, drawn by reduced audit preparation hours. The technology is digitizing the role of payroll administrators toward exception handling and employee-facing inquiry resolution.
France's CNIL and Germany's Federal Commissioner for Data Protection have issued binding guidance requiring algorithmic transparency in automated wage calculations, effective across all EU member states. Vendors must now document decision trees and provide employee-facing explanations for tax withholding determinations. Cloud-native platforms with built-in audit trails are capturing share from legacy systems lacking explainability features.
Subscription-based pricing is yielding to transaction-scaled models where fees adjust with payroll frequency and employee count fluctuations. Professional employer organizations and accounting firm partnerships are displacing direct enterprise sales as the primary customer acquisition channel. This shift is most visible in the United States, where SMB buyers prefer bundled HR-administrative services over standalone software procurement.
Payroll and HR Software Market Segmentation
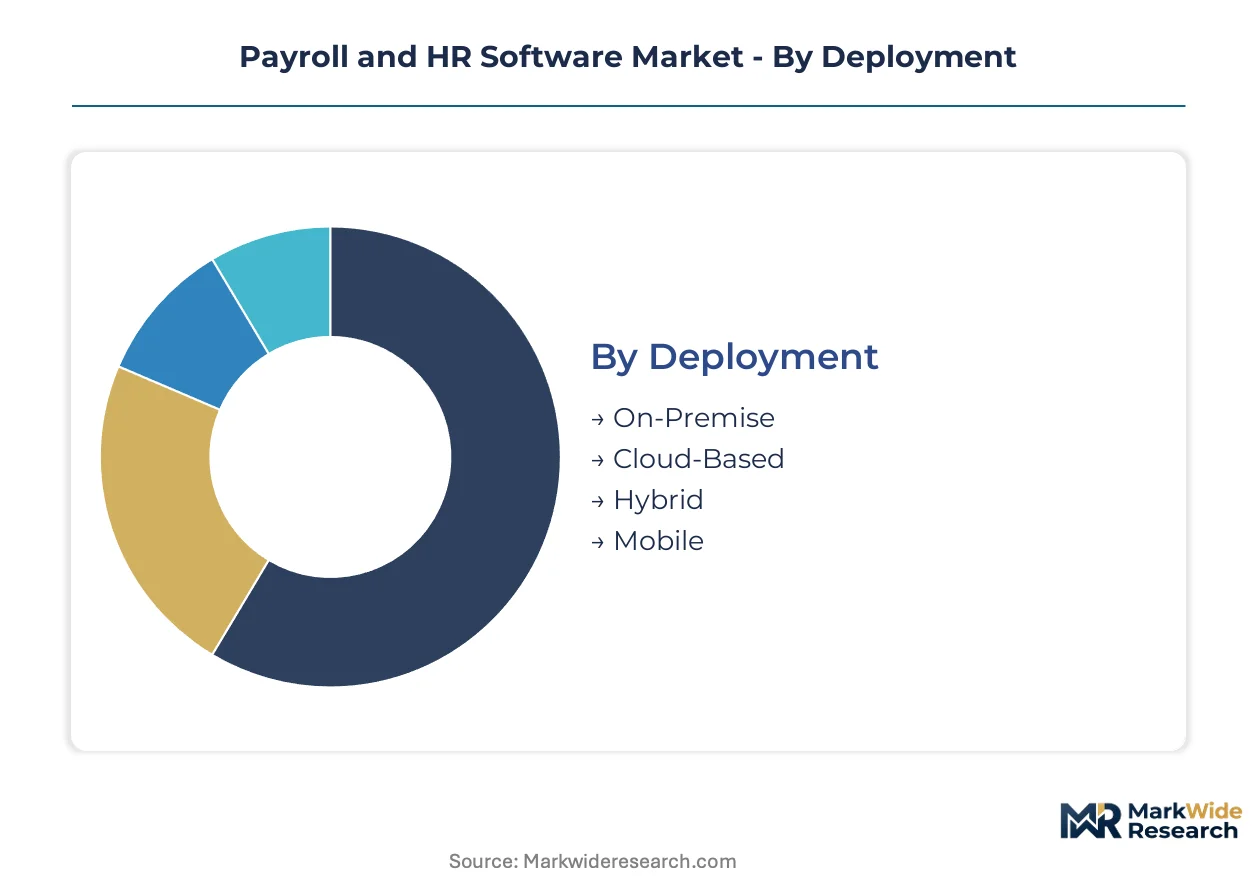
Segmentation in payroll and HR software determines vendor engineering priorities and sales motion design. Buyers select deployment modes based on data residency mandates, while pricing model preferences diverge sharply between cash-constrained SMBs and compliance-heavy enterprises.
Deployment:
After-sales service intensity varies dramatically across deployment architectures, with on-premise installations demanding sustained technical support and cloud instances shifting burden to vendor infrastructure teams.
- Cloud-Based:Multi-tenant architectures with automatic updates and jurisdiction-specific encryption layers dominate new procurement. Mid-market enterprises in Germany and France accelerate migration under CNIL and Federal Commissioner for Data Protection mandates.
- On-Premise:Single-tenant installations with localized data storage persist in manufacturing and public sector verticals. Japan's METI data residency guidelines sustain demand among organizations with sector-specific compliance requirements.
- Hybrid:Split architectures processing sensitive payroll data on-premise while routing benefits administration to cloud instances.
- Mobile:Native iOS and Android applications with biometric authentication for field workforce time capture.
By volume, Cloud-Based leads. By growth pace, Hybrid is ahead as organizations seek phased migration paths.
End User:
Cost tier segmentation separates buyers by implementation complexity and support requirements, with enterprises absorbing full-suite deployments and freelancers demanding minimal-touch onboarding.
- Enterprises:Multi-entity organizations with 1,000+ employees requiring global payroll consolidation and advanced workforce analytics. Complex multi-state tax configurations in Texas, New York, and Illinois drive platform consolidation.
- Small Businesses:Organizations with under 100 employees prioritizing out-of-box functionality over customization. Brazil and Mexico buyers face extended payback periods due to data migration complexity.
- Freelancers:Solo operators and gig workers needing simplified tax withholding and quarterly filing automation.
- Non-Profits:Mission-driven organizations with grant-funded payroll cycles and specialized compliance reporting.
By volume, Small Businesses lead. By growth pace, Enterprises is climbing the fastest as workforce planning modules expand addressable spend.
Functionality:
Application-based segmentation tracks which HR workflows vendors choose to build versus partner for, with payroll processing commanding the deepest engineering investment.
- Payroll Processing:Automated wage calculation, tax withholding, and direct deposit execution with real-time ledger integration. The largest revenue pool as employers absorb rising jurisdictional complexity.
- Benefits Administration:Healthcare enrollment, COBRA management, and retirement contribution tracking with carrier connectivity. Expanding most quickly as US employers navigate rising healthcare complexity.
- Time & Attendance:Shift scheduling, overtime calculation, and PTO accrual with biometric validation.
- Employee Tracking:Onboarding workflows, performance documentation, and separation processing with audit trails.
By volume, Payroll Processing leads. By growth pace, Benefits Administration is gaining share fastest.
Pricing Model:
Customer-type segmentation reveals divergent procurement preferences, with subscription models dominating SaaS-native buyers and transaction-scaled alternatives capturing PEO-channel demand.
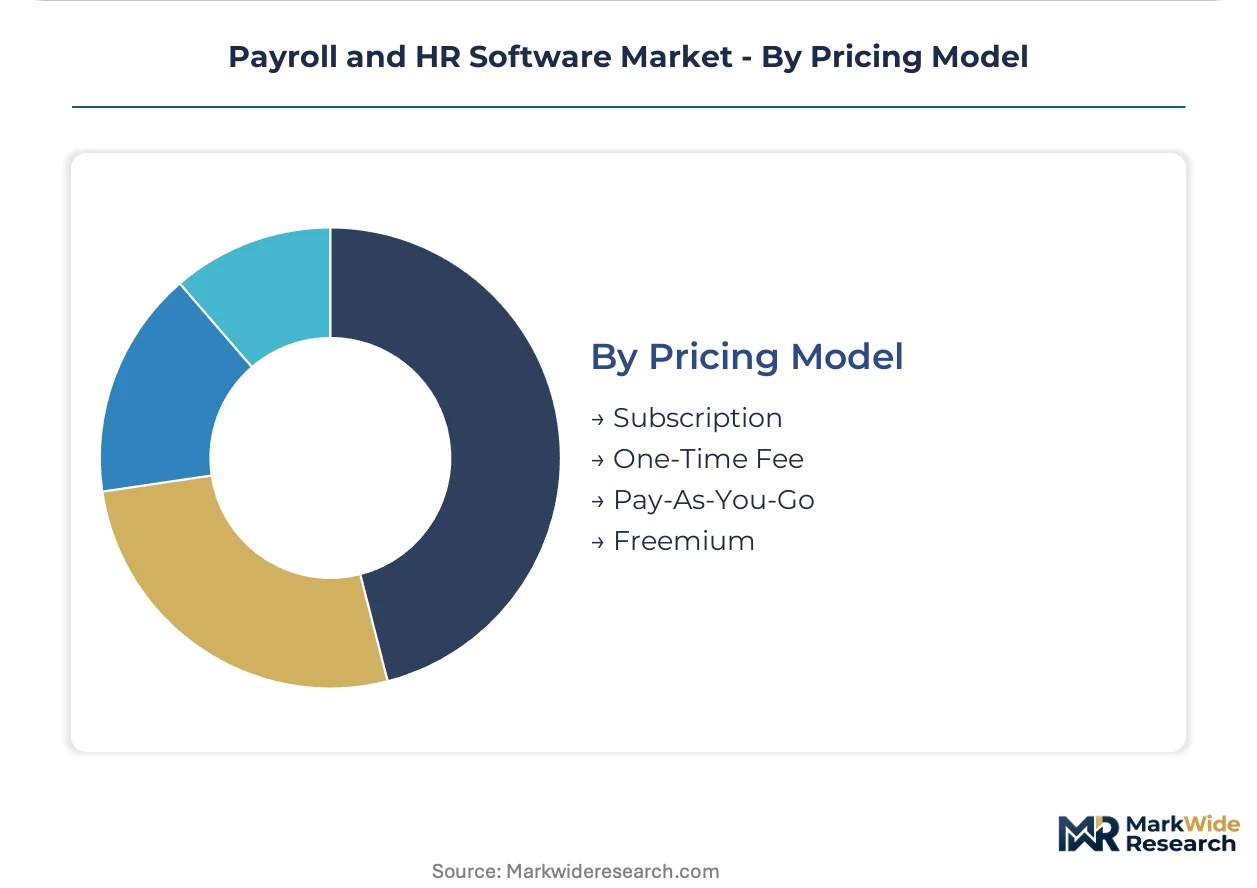
- Subscription:Fixed monthly or annual fees scaled by employee count with tiered feature access. Standard for cloud-native platforms with predictable renewal economics.
- Pay-As-You-Go:Per-transaction fees adjusting with payroll frequency and employee fluctuations. Emerging preference among professional employer organizations.
- One-Time Fee:Perpetual licenses with annual maintenance contracts retaining share in legacy on-premise accounts.
- Freemium:Zero-cost entry tiers with premium upsells for advanced reporting and multi-state compliance.
By volume, Subscription leads. By growth pace, Pay-As-You-Go shows the steepest expansion trajectory as embedded finance partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States vendors extract 40% pricing premiums over Indian competitors for equivalent feature sets, while German buyers absorb compliance surcharges that narrow this gap. Demand dispersion follows regulatory stringency rather than GDP scale.
United States
Multi-state employers in Texas, New York, and Illinois drive platform consolidation as divergent withholding rules overwhelm manual processing. State-level privacy laws in California and Virginia mandate encrypted cloud architectures that elevate vendor engineering costs. Silicon Valley and Austin clusters concentrate procurement decision-making for Fortune 500 workforce planning modules.
Germany
Mid-market manufacturers accelerate migration from on-premise servers under Federal Commissioner for Data Protection cloud mandates. Works council consultation requirements under the Betriebsverfassungsgesetz extend implementation timelines compared to Anglo-Saxon markets. Munich and Frankfurt financial centers anchor demand for integrated payroll-ERP connectivity.
France
CNIL algorithmic transparency rules force vendors to document decision trees for automated tax withholding calculations. Professional employer organizations displace direct software sales as SMBs prefer bundled HR-administrative services. Paris Île-de-France concentrates procurement for multinational headquarters with complex expatriate payroll requirements.
India
Digital Personal Data Protection Act localization mandates create first-mover advantage for vendors establishing Mumbai and Bangalore data centers. IT services exporters in Hyderabad and Pune drive demand for multi-currency payroll processing across US and European client jurisdictions. GST compliance complexity elevates platform value versus spreadsheet-based processing.
Japan
METI data residency guidelines sustain on-premise demand among manufacturing and public sector buyers resistant to cloud migration. Aging workforce demographics accelerate adoption of automated benefits administration for pension and healthcare tracking. Tokyo and Osaka clusters concentrate procurement for keiretsu-affiliated enterprises with lifetime employment legacy systems.
Payroll and HR Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream as acquisition targets or partnership fodder. The vendor base organizes around three strategic archetypes: captive PEO-channel operators, in-house module developers, and financials-to-HR extenders. Consolidation pressure intensifies as mid-market buyers abandon point solutions for unified suites. M&A activity targets API-first connectivity assets; strategic partnerships with accounting networks displace direct enterprise sales.
Within the captive-channel archetype, ADP exemplifies vertical integration through professional employer organization ownership. Paycom occupies a position as the in-house development purist, building every payroll module without third-party dependencies. Workday anchors the financials-to-HR extender tier, leveraging existing enterprise resource planning relationships into workforce planning adjacencies.
| Leading Market Players |
|---|
| ADP |
| Paycom |
| Workday |
| Paycor |
| Paylocity |
| UKG |
| Paychex |
| Ceridian |
| Sage |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure concentration in the United States and Ireland concentrates margin pools with hyperscale hosting providers, forcing payroll software vendors to absorb compute cost escalations or pass them through to mid-market subscribers. This upstream bottleneck shapes downstream pricing power and partnership economics across the vendor ecosystem.
Pricing Analysis
Configured-to-order pricing for multi-entity enterprise deployments commands substantial premiums over standard SaaS tiers for sub-100 employee accounts. The dominant structure stratifies across premium compliance-heavy, standard mid-market, and economy self-service tiers with feature-gated access. Price differentiation rests on jurisdictional complexity certification and dedicated implementation support. Pricing pressure stems from transaction-scaled models disrupting traditional subscription renewals. Small businesses exhibit highest price sensitivity, while enterprises absorbing multi-state tax complexity show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates engineering cost volatility for biometric hardware components in time-capture devices. Supply concentrates in Taiwan for semiconductor fabrication, Ireland for EU data center infrastructure, and India for software development talent. Raw material dependencies include encryption processors, cloud compute cycles, and certified compliance audit services. Single-source vulnerability persists in specialized SOC 2 attestation providers. Distribution runs through direct enterprise sales, professional employer organization partnerships, and accounting firm embedded channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified payroll tax engineers and AI fairness auditors represent critical capability gaps constraining vendor expansion timelines. Scarcity of professionals fluent in both German Works Council consultation protocols and French CNIL algorithmic documentation requirements limits first-mover capture in continental Europe.
For Market Incumbents: Build regulatory moats through preemptive ISO 27001 and SOC 2 Type II certification stacking ahead of compressed audit cycles. Deepen API-first integration capabilities to neutralize point-solution substitutes threatening platform consolidation. Acquire machine learning explainability assets before US Department of Labor guidance hardens into binding mandates. Channel control through captive PEO relationships defends renewal economics against transaction-scaled pricing entrants. For New Entrants and Emerging Players: Build out earned wage access partnerships with neobanks as the primary white-space vector. Target India's Digital Personal Data Protection Act compliance gap before established vendors complete Mumbai and Bangalore data center buildouts. Brazil and Mexico's extended implementation payback periods create services-heavy entry points for lean deployment architectures. Go-to-market through accounting firm networks displaces direct enterprise sales friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-market payroll consolidators lacking AI wage-auditing capabilities. Long-term viability across the next decade hinges on explainable compliance automation replacing manual audit preparation. Monitor US state-level privacy law proliferation as inflection indicator for cloud migration acceleration versus on-premise entrenchment. Acquisition candidates with jurisdiction-specific encryption architectures command scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Real-time ledger connectivity eliminates batch-processing delays between payroll and accounting systems. |
| Acquisition of Specialist Firm | Machine learning fairness tools address emerging explainability requirements from French CNIL and German regulators. |
| Strategic Partnership | Embedded finance alliances with neobanks unlock transaction-scaled revenue beyond subscription fees. |
| Geographic Expansion | Mumbai and Bangalore data centers capture first-mover advantage under India's Digital Personal Data Protection Act. |
| Product Launch | Hybrid deployment architectures serve Japanese manufacturing buyers under METI data residency guidelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with payroll operations directors, HR technology procurement officers, platform engineers, and professional employer organization channel managers. Secondary validation drew from SEC 10-K filings, ISO certification registries, CNIL enforcement bulletins, and IRS guidance documents. Bottom-up sizing of vendor revenue pools combined with top-down triangulation against cloud infrastructure expenditure disclosures anchored value estimates.
Calibration across the analysis window employed multi-dimensional segmentation modeling deployment architecture, organization size tier, functional module penetration, and regional regulatory cluster. CAGRs were derived from trend extrapolation of cloud migration velocity and compliance mandate implementation timelines. Forecast inputs included mid-market buyer survey data on payback period expectations and vendor engineering headcount allocations to jurisdiction-specific encryption layers.
Practitioners should monitor AI wage-auditing regulatory guidance evolution and cross-border data architecture performance benchmarks for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Outsourced Software Testing Services Market
Software & Services
Global Process Mining Software Market
Software & Services
Lifecycle Management Software Market
Software & Services
CAD Modeling Software Market
Software & Services
Animation Design Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Sales Compensation Software Market
Software & Services
North America Automotive Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Lead Mining Software Market
Software & Services
Board Portal Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Solar Rooftop Design Software Market